
 Baler Market | 2026-2036
Baler Market Size, Share, and Industry Trends Forecast 2026-2036
Baler Market Intelligence
Waste management demand for material densification is hardening as municipal recycling mandates expand across North America and Europe. Vermeer leverages its geographic dominance in the North American hay and forage belt through an extensive dealer network. John Deere anchors its position via deep integration with precision agriculture platforms that synchronize baler operation with fleet logistics. Krone specializes in high-density square baler engineering for European contractors who prioritize transport efficiency.
A baler is a mechanical compression device that binds fibrous or loose materials into dense, transportable units using platen force ranging from 100 to over 1,000 psi depending on material and intended end use. Round balers dominate the agricultural replacement cycle due to lower capital outlay and compatibility with existing tractor fleets, though margin pools concentrate in continuous balers serving industrial waste streams where throughput requirements justify premium pricing. Electric technology variants are gaining fastest in indoor recycling facilities where emissions restrictions and noise ordinances constrain internal-combustion deployment.
EPA Tier 4 Final emissions rules and the EU F-Gas Regulation constrain hydraulic system designs and refrigerant choices in climate-controlled cab variants, respectively. OSHA machine-guarding standards and ISO 4254 safety protocols dictate operator-protection geometry and emergency-stop placement, shaping product development roadmaps for manufacturers selling across multiple jurisdictions. Stakeholders must monitor how battery-electric powertrain maturation alters the total-cost-of-ownership calculus against established hydraulic architectures.
Market Dynamics
EPA Tier 4 Final emissions mandates are compressing the hydraulic powertrain design window while battery-electric architectures mature for indoor material handling applications. This regulatory-technological tension is redrawing equipment procurement criteria across agricultural and waste management verticals.
Growth Catalysts
- Midwest Dairy Consolidation:Large-scale operations in Iowa, Wisconsin, and Minnesota are replacing manual hay collection with continuous baling systems to offset climbing agricultural labor rates.
- REACH Chemical Compliance:The EU's restrictions on hydraulic fluid formulations are accelerating demand for sealed, low-maintenance baler designs that minimize fluid change intervals.
- Recycling Mandate Density:Municipal single-stream requirements in Germany, France, and Italy are forcing MRF operators to densify fiber and plastic streams prior to long-haul transport.
Market Restraints
- Steel Input Volatility:Frame and platen fabrication depends on hot-rolled coil pricing that fluctuates with energy costs and import tariff schedules.
- Hydraulic Component Concentration:Precision pump and valve supply clusters in Baden-Württemberg create vulnerability for North American assemblers during transatlantic shipping disruptions.
- Battery Energy Density Ceiling:Current lithium-ion pack configurations limit electric baler duty cycles to sub-four-hour continuous operation before recharge.
Strategic Opportunities
- India Agricultural Mechanization:The country's PLI scheme for farm machinery offers cost offsets for foreign OEMs establishing local assembly for straw and stover baling.
- Biomass Power Feedstock:Cofiring mandates at coal plants in Denmark and the Netherlands are creating spot demand for high-density straw bales with calibrated moisture content.
- Telematics-Enabled Rental:Hourly-use billing platforms are penetrating the European contractor segment where seasonal demand spikes strain ownership economics.
Industry Challenges
- Mechatronics Skill Scarcity:Servicing electrohydraulic control systems requires technicians cross-trained in CAN bus diagnostics and mechanical compression mechanics.
- ISO 4254 Certification Timelines:Third-party validation of revised operator-protection geometry extends product launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baler Market |
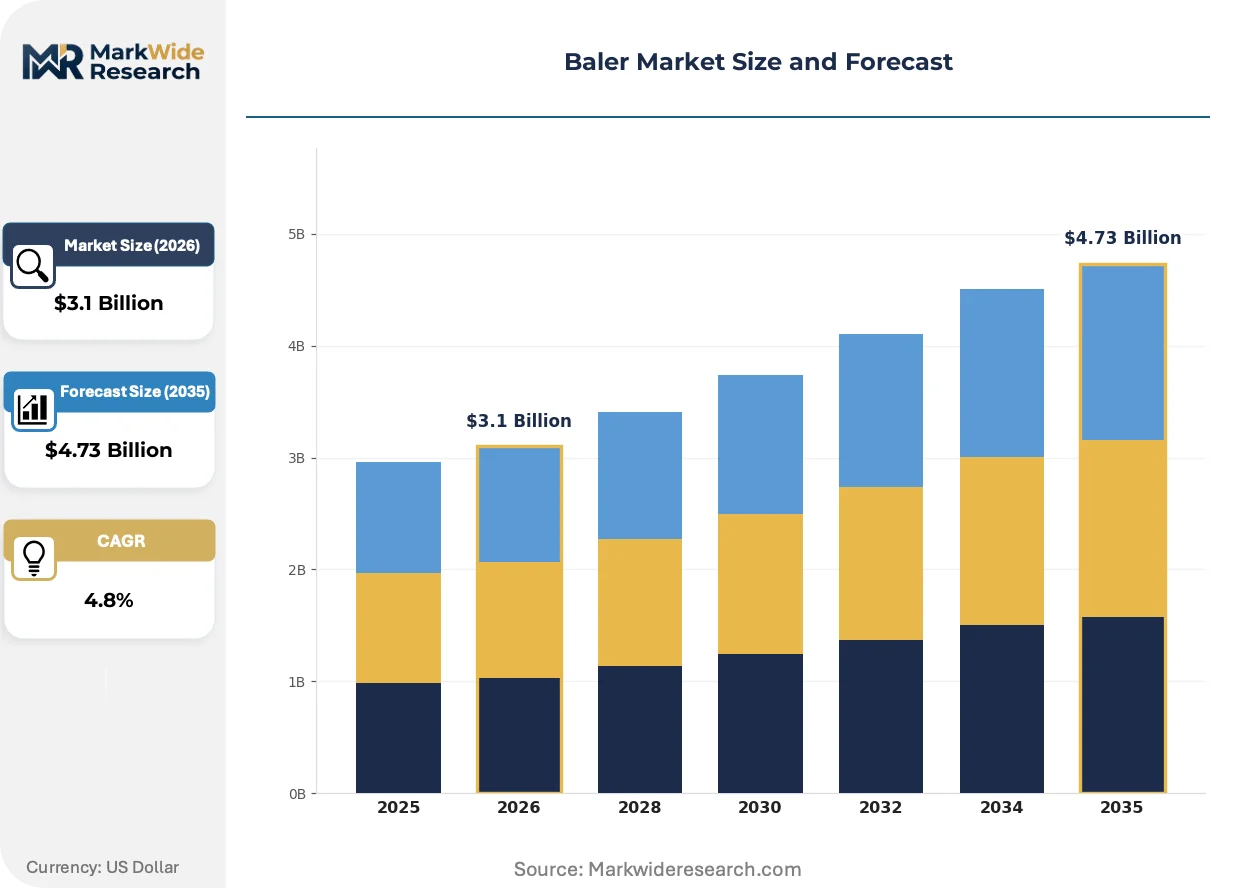
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.73 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Balers, Square Balers, Continuous Balers, Specialty Balers End User: Agriculture, Waste Management, Recycling, Bioenergy Technology: Hydraulic, Electric, Gas-Powered, Pneumatic Application: Crop Handling, Waste Processing, Material Compression, Livestock Feed |
| Companies Covered | Vermeer, KUHN Group, John Deere, Fendt, AGCO Corporation, CNH Industrial, Krone, American Baler Co., CLAAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baler Market Strategic Shifts & Innovations
Sensor fusion and electrification are converging to redefine baler architecture, shifting competitive advantage from mechanical durability to data-driven throughput optimization and emissions compliance.
Variable chamber density control is integrating load-cell feedback with hydraulic platen modulation to maintain consistent bale weight across moisture-content variation. Dairy cooperatives in the Netherlands and Denmark are piloting these systems to reduce transport cost per ton of dry matter. The technology is integrating real-time agronomic data streams that synchronize baler output with fleet logistics platforms.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in climate-controlled cab variants, forcing redesign of thermal management systems for operator comfort. This constraint is compressing the supplier base for compliant HVAC modules. Continuous square baler configurations serving European contractors face the steepest redesign burden due to extended seasonal operating hours.
Contractor purchasing committees are consolidating equipment decisions across multi-site operations, displacing decentralized dealer relationships with direct OEM fleet negotiations. Large hay and forage operations in Nebraska and Kansas are centralizing procurement through cooperative buying groups. This concentration is visible most acutely in the US Corn Belt where dairy and beef integrators operate across county and state boundaries.
Baler Market Segmentation
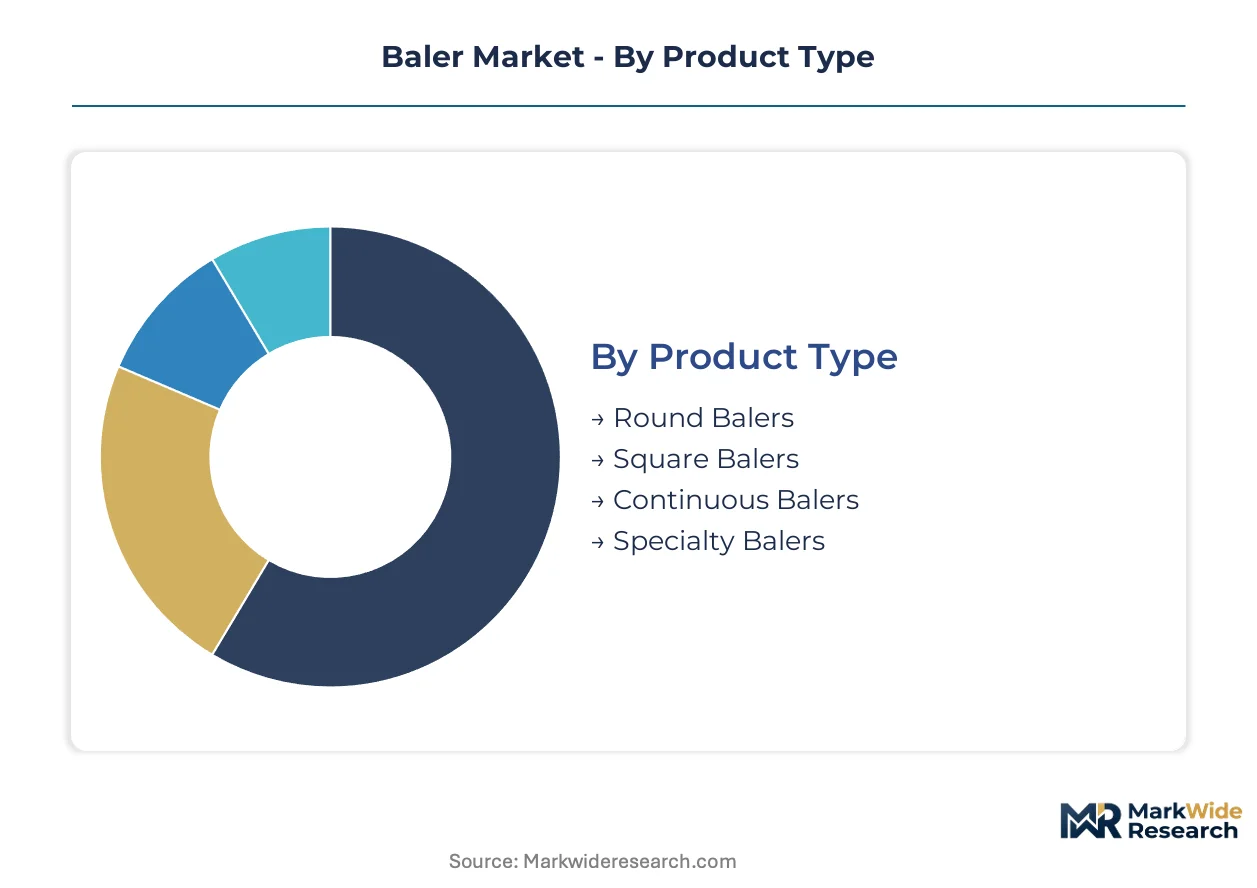
Baler procurement patterns diverge sharply across end-use contexts, with agricultural buyers prioritizing tractor compatibility and waste operators demanding throughput density. Understanding these segment boundaries clarifies why technology roadmaps and pricing architectures vary so dramatically between adjacent verticals.
Product Type:
Capital outlay thresholds and fleet integration requirements separate buyers most distinctly in this dimension.
- Round Balers:These machines form cylindrical bales using rotating belts or chains that wrap crop material into dense rolls. Demand concentrates among Midwest United States dairy and beef operations where existing tractor fleets and lower acquisition costs drive replacement cycles. Labor cost inflation in Iowa, Wisconsin, and Minnesota accelerates mechanization adoption.
- Square Balers:Platen-driven compression produces rectangular bales optimized for stacking density and transport efficiency. European contractors in Germany and Denmark prioritize these systems where long-haul logistics to biomass cofiring plants dominate economics. The EU F-Gas Regulation adds compliance complexity to cab-equipped variants running extended seasonal hours.
- Continuous Balers:Industrial waste streams with high throughput requirements justify premium pricing for non-stop operation.
- Specialty Balers:Niche configurations serve silage, hemp, or cotton applications with material-specific binding systems.
Volume sits with Round Balers; growth tilts toward Continuous Balers.
End User:
Regulatory exposure and operational scale define purchasing committee composition across these verticals.
- Agriculture:Hay and forage producers dominate installed base with seasonal utilization patterns. Corn Belt state consolidation into large-scale dairy and beef integrators shifts procurement toward cooperative buying groups spanning county boundaries. EPA Tier 4 Final emissions rules constrain hydraulic powertrain options for new acquisitions.
- Waste Management:Municipal single-stream mandates in Germany, France, and Italy force MRF operators to densify fiber and plastic prior to transport. REACH chemical compliance accelerates demand for sealed, low-maintenance designs minimizing fluid change intervals.
- Recycling:Indoor facilities face emissions restrictions and noise ordinances favoring electric technology variants.
- Bioenergy:Cofiring mandates at coal plants in Denmark and the Netherlands create calibrated moisture-content specifications for straw bales.
Revenue concentrates in Agriculture; expansion accelerates most quickly in Waste Management.
Technology:
Powertrain selection hinges on duty cycle location and emissions jurisdiction.
- Hydraulic:Dominant architecture for outdoor agricultural deployment with proven durability in variable field conditions. Supply concentration for precision pumps and valves in Baden-Württemberg creates vulnerability for North American assemblers during shipping disruptions.
- Electric:Gaining fastest in indoor recycling facilities where battery-electric powertrains circumvent emissions and noise constraints. Current lithium-ion configurations limit continuous operation to sub-four-hour cycles before recharge.
- Gas-Powered:Serves remote operations lacking electrical infrastructure or requiring rapid refueling.
- Pneumatic:Niche applications in explosive atmospheres or cleanroom material handling.
Installed base favors Hydraulic; development investment tilts toward Electric.
Application:
Material characteristics and downstream logistics shape compression force and binding specifications.
- Crop Handling:Variable chamber density control integrates load-cell feedback with hydraulic platen modulation to maintain consistent bale weight across moisture variation. Dutch and Danish dairy cooperatives pilot these systems to reduce transport cost per ton of dry matter.
- Waste Processing:Municipal recycling mandates across North America and Europe harden demand for material densification ahead of long-haul transport. OSHA machine-guarding standards and ISO 4254 safety protocols dictate operator-protection geometry.
- Material Compression:Industrial fiber and plastic streams require platen force exceeding 1,000 psi for transportable unit density.
- Livestock Feed:Silage and haylage applications prioritize anaerobic seal integrity over dry matter density metrics.
Deployment volume centers on Crop Handling; specification complexity rises fastest in Waste Processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kutch Special Economic Zone in Gujarat anchors machinery assembly incentives for agricultural equipment serving South Asian export markets.
United States
Consolidated dairy operations across Iowa, Wisconsin, and Minnesota drive replacement demand for high-throughput hay collection systems. EPA Tier 4 Final emissions mandates constrain hydraulic powertrain architectures for new equipment acquisitions. Lincoln, Nebraska hosts dense clusters of dealer networks and aftermarket service infrastructure serving the Corn Belt integration trend.
Germany
Biomass cofiring mandates at coal plants in Lower Saxony and Brandenburg create calibrated specifications for straw bale moisture content. REACH chemical compliance restricts hydraulic fluid formulations, accelerating demand for sealed, low-maintenance designs. Baden-Württemberg concentrates precision pump and valve manufacturing, creating supply vulnerability during transatlantic shipping disruptions.
India
PLI scheme incentives for farm machinery attract foreign OEMs establishing local assembly for straw and stover baling operations. Central Electricity Authority regulations promote agricultural residue collection for biomass power generation. Punjab and Haryana field mechanization programs displace manual residue burning with compressed bale collection systems.
Denmark
Dairy cooperatives pilot variable chamber density control systems to reduce transport cost per ton of dry matter. EU F-Gas Regulation phases down hydrofluorocarbon refrigerants in climate-controlled cab variants. Jutland Peninsula contractor operations consolidate procurement through cooperative buying groups spanning regional boundaries.
Netherlands
Cofiring mandates at coal plants create spot demand for high-density straw bales with calibrated moisture specifications. ECHA chemical restrictions shape hydraulic system maintenance protocols for extended seasonal operating hours. Gelderland and Overijssel host concentrated biomass logistics infrastructure connecting arable farming to power generation facilities.
Baler Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with agricultural verticals favoring integrated OEMs while waste processing tolerates modular assembly. The vendor base organizes into three tiers: full-line agricultural equipment conglomerates, regional hay and forage specialists, and industrial waste densification fabricators. Strategic moves concentrate on telematics integration and electrification roadmaps rather than capacity expansion.
Within the full-line agricultural tier, John Deere, CNH Industrial, and AGCO Corporation occupy positions defined by precision agriculture platform integration and fleet logistics synchronization. These manufacturers anchor the replacement cycle dynamics in North American and European hay and forage markets through dealer network density and cooperative procurement relationships.
| Leading Market Players |
|---|
| Vermeer |
| KUHN Group |
| John Deere |
| Fendt |
| AGCO Corporation |
| CNH Industrial |
| Krone |
| American Baler Co. |
| CLAAS |
| Others |
Cost & Logistics Intelligence
Electrohydraulic technician shortages in Baden-Württemberg widen the pricing spread between premium OEM-supported service contracts and economy-tier third-party maintenance, compressing mid-market positioning as labor cost differentials exceed component cost variation across tiers.
Pricing Analysis
Lead-time premiums command substantial markups in the baler market, with spot inventory from dealer networks pricing at standard tiers while factory-direct orders with extended delivery windows trade at economy levels. Pricing stratifies across premium, standard, and economy tiers based on precision agriculture integration depth and EPA Tier 4 Final certification status. Cost compression in the economy tier is intensifying because steel input volatility and hydraulic component concentration erode assembler margins. Agricultural cooperatives in the Corn Belt exhibit highest price sensitivity, while European biomass contractors prioritize transport efficiency over acquisition cost.
Supply Chain Analysis
Reverse-logistics flows for remanufactured platen assemblies and refurbished hydraulic pumps are gaining traction as sustainability mandates and REACH compliance extend equipment lifecycles. Manufacturing concentration centers on Germany, the United States, and India, with precision pump and valve fabrication drawing from Baden-Württemberg clusters. Steel coil, lithium-ion cells, and specialized binding twine constitute critical input dependencies. Single-source vulnerability in transatlantic hydraulic component shipping creates disruption exposure. Distribution runs through captive dealer networks for agricultural verticals and direct OEM contracting for waste management integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baler market sits in a technology-transition phase as battery-electric powertrains displace hydraulic architectures in indoor recycling applications, reshaping competitive advantage toward mechatronics integration and emissions compliance.
For Market Incumbents: To counter battery-electric new entrants in indoor material handling, John Deere and CNH Industrial should deepen precision agriculture platform integration to lock in fleet synchronization contracts across Corn Belt cooperatives. Vermeer must anchor dealer network density in Iowa and Wisconsin against telematics-enabled rental platforms eroding ownership economics. Certification investment in EU F-Gas Regulation compliance for climate-controlled cab variants preserves European contractor access. For New Entrants and Emerging Players: Telematics platform providers offer the most penetrable channel partner type for new entrants seeking to bypass entrenched dealer relationships. White-space targets include hourly-use billing platforms for European contractors and electric baler systems for German MRF operators facing emissions restrictions. A direct-to-integrator sales model targeting Nebraska and Kansas cooperative buying groups circumvents legacy distribution chokepoints. For Investors and Strategic Acquirers: Re-rating potential sits with electric powertrain specialists given EPA Tier 4 Final enforcement tightening and indoor facility electrification mandates. Long-term viability favors manufacturers with backward integration into battery pack assembly and sealed hydraulic system design. The inflection signal to monitor is lithium-ion energy density breakthroughs enabling four-plus-hour continuous duty cycles, which would collapse the total-cost-of-ownership advantage of established hydraulic architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Powertrain Development | Battery-electric architectures circumvent EPA Tier 4 Final constraints in indoor recycling facilities. |
| Telematics Platform Integration | Hourly-use billing systems penetrate European contractor segments with seasonal demand spikes. |
| Precision Agriculture Synchronization | Fleet logistics integration locks in Corn Belt cooperative procurement decisions across state boundaries. |
| REACH-Compliant Sealed Hydraulics | Low-maintenance designs minimize fluid change intervals under EU chemical restrictions. |
| Biomass Cofiring Certification | Calibrated moisture-content specifications access Danish and Dutch power plant feedstock contracts. |
Research Approach
Trade association filings, customs and import-export records, and equipment registration databases formed the secondary backbone, supplemented by primary interviews with agricultural equipment procurement managers, MRF operations directors, hydraulic systems engineers, and aftermarket service heads. Bottom-up and top-down triangulation validated volume estimates across product type, end user, technology, and application segments. The analysis combined field-level stakeholder conversations with secondary validation from EPA enforcement disclosures and EU regulatory filings.
Bottom-up modeling anchored volume projections to installed base replacement cycles and mechanization penetration rates, while top-down cross-checks referenced agricultural labor cost inflation and municipal recycling mandate expansion across the analysis window. Segmentation dimensions included product configuration, powertrain architecture, end-use vertical, and regional regulatory cluster. CAGRs were derived from trend extrapolation of replacement demand, technology substitution rates, and compliance-driven equipment refresh cycles. Industry-specific inputs encompassed steel price volatility indices and lithium-ion cell cost curves.
Caveats apply where battery energy density breakthroughs, transatlantic shipping disruptions, or sudden EPA enforcement shifts could materially shift the outlook. Forecasts reflect assumptions about electrification adoption pacing and cooperative procurement consolidation trajectories. Practitioners should monitor lithium-ion duty cycle extensions and REACH chemical restriction amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
LAMEA Water Pump Market
Construction Equipment
Cementing Accessories Market
Construction Equipment
Wood Chipper Machines Market
Construction Equipment
Mobile Asphalt Plant Market
Construction Equipment
Smart Crane Market
Construction Equipment
Friction Stir Welding Market
Construction Equipment
CNC Router Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
Boom Lifts Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
India Crane Market
Construction Equipment
Crane Aftermarket Market
Construction Equipment
Rotary Hammers Market
Construction Equipment
Global Airport Snow Removal Vehicles and Equipment Market
Construction Equipment
Middle-East and Africa Anchors and Grouts Market