
 Hand Push Trencher Market | 2026-2036
Hand Push Trencher Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Push Trencher Market Insights
EPA Tier 4 emissions standards for small off-road engines is expanding the engineering burden on gas-powered trencher lines while opening margin pools for electric alternatives. Vermeer Corporation leverages its horizontal directional drilling heritage to anchor channel relationships with utility contractors seeking compact trenching solutions. Ditch Witch sustains brand recognition through specialized dealer networks that control aftermarket parts availability. Little Beaver competes on portability, occupying the lightweight rental market where maneuverability determines purchase decisions.
A hand push trencher is a walk-behind excavation machine typically weighing under 300 pounds, equipped with a chain or blade cutting mechanism driven by small internal combustion, electric, or hydraulic power units, designed to cut narrow trenches 2 to 12 inches deep for laying cable, pipe, or irrigation lines in confined residential and light commercial sites. Gas-powered trenchers retain the largest installed base among landscaping firms, though battery-operated units are gaining fastest where noise ordinances and indoor utility work restrict engine-driven equipment. Utility installation applications command premium pricing due to specification requirements for depth consistency and soil displacement control that exceed lawn and garden standards.
OSHA excavation safety standards and the EPA's evolving small engine emissions framework shape product design cycles, forcing manufacturers to certify guard systems and catalytic converter configurations before market entry. The Federal Communications Commission's broadband infrastructure programs indirectly stimulate demand by funding fiber optic burial projects suited to compact trencher deployment. Stakeholders must weigh electrification roadmaps against the persistent torque requirements of rocky or clay-heavy soils that currently favor hydraulic and gas-powered architectures.
Market Dynamics
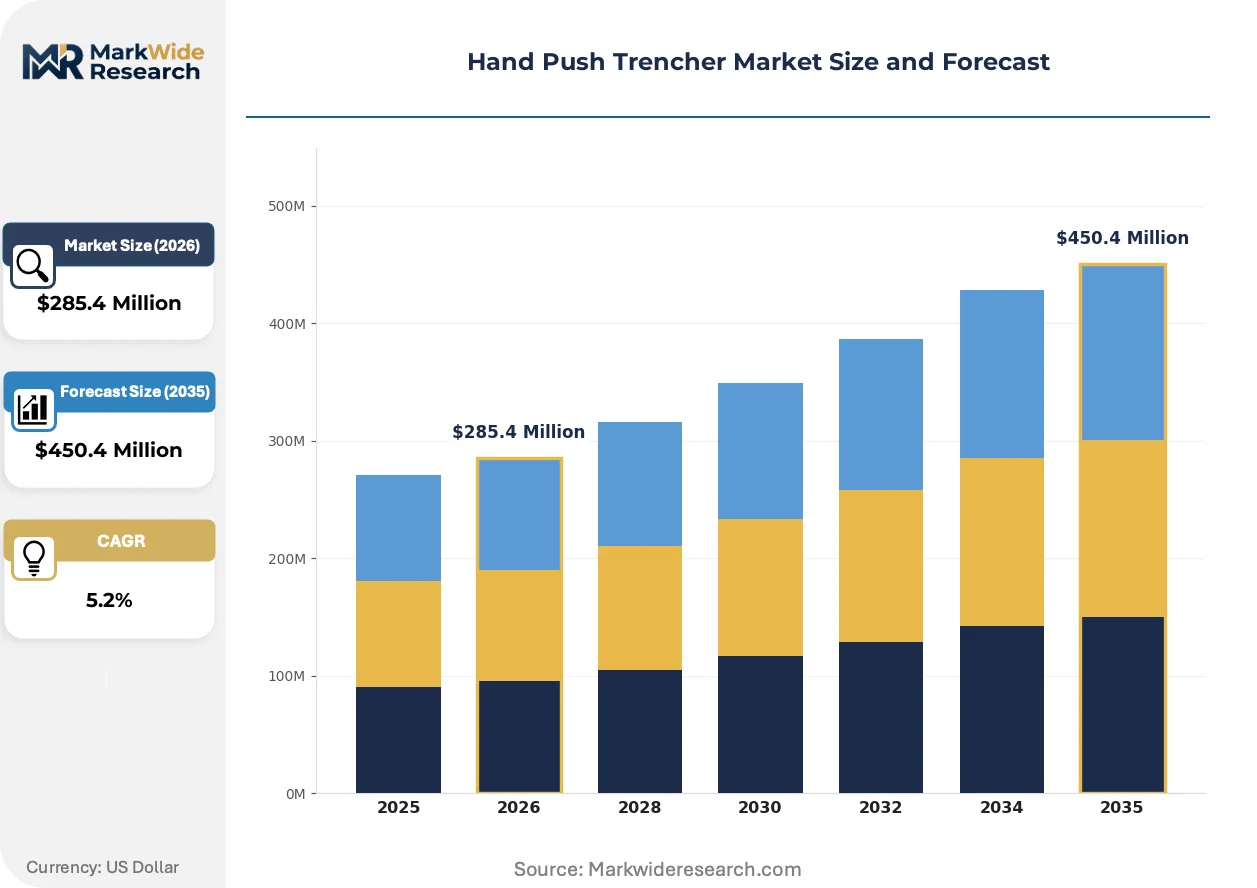
EPA Tier 4 emissions standards for small off-road engines are compressing the engineering runway for gas-powered trencher architectures while simultaneously opening margin pools for battery-electric alternatives. Manufacturers must now certify catalytic converter configurations and guard systems before market entry, fundamentally restructuring product development cycles.
Growth Catalysts
- Broadband infrastructure programs:The Federal Communications Commission's fiber optic burial funding creates specification-grade demand for compact trenchers capable of depth-consistent utility installation.
- Sun Belt housing development:Active residential construction across Texas, Florida, and Arizona concentrates equipment procurement among landscaping firms expanding fleet capacity.
- Battery chemistry advances:Lithium-ion energy density improvements enable electric drive systems to meet torque requirements previously reserved for hydraulic architectures.
Market Restraints
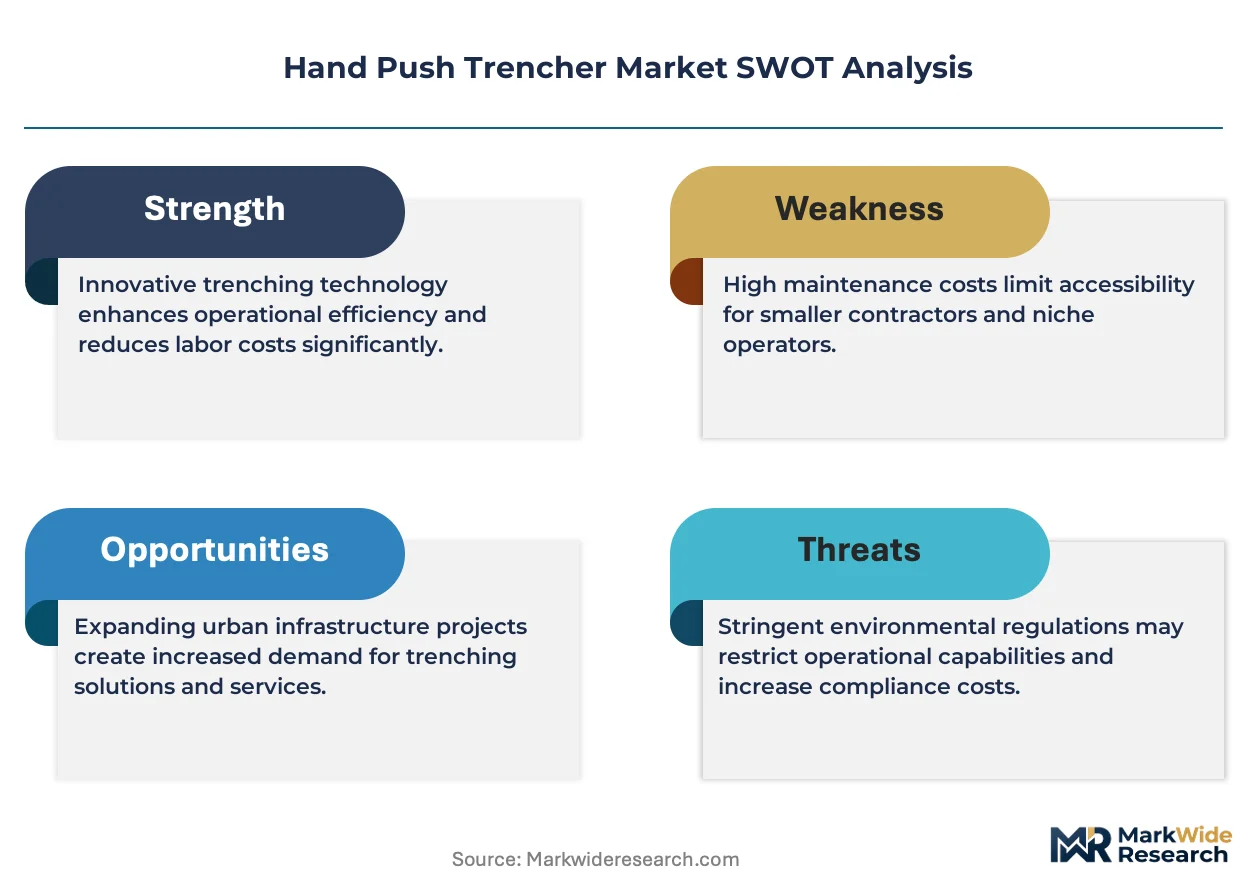
- Small engine emissions compliance:EPA certification timelines extend product development cycles by 8-14 months, freezing capital in pre-market inventory.
- Steel and aluminum input volatility:Chassis and chain component costs fluctuate with commodity indexes, compressing margin predictability for mid-tier manufacturers.
- Rocky soil performance limitations:Battery-operated units struggle with clay-heavy and aggregate-dense substrates where gas-powered torque remains superior.
Strategic Opportunities
- Indoor utility contractor segment:Noise-ordinance-restricted environments in dense urban cores favor zero-emission equipment procurement.
- Irrigation infrastructure upgrade cycles:Municipal water efficiency mandates across drought-prone states create recurring replacement demand.
- Rental channel specialization:Equipment rental firms seek lightweight, maneuverable units for residential DIY markets where purchase economics fail.
Industry Challenges
- Electrification skill gaps:Field service technicians trained on small internal combustion engines lack diagnostic capability for battery management systems and electric drivetrains.
- Dual certification burden:Manufacturers must simultaneously maintain OSHA guard system compliance and EPA emissions documentation, stretching quality assurance resources across divergent technical domains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Push Trencher Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $450.4 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Trencher, Gas-Powered Trencher, Pneumatic Trencher, Hydraulic Trencher Application: Lawn & Garden, Utility Installation, Landscaping, Road Construction, Irrigation Setup End User: Construction Contractors, Landscaping Firms, Municipal Maintenance, Agriculture Operators Power Rating: Below 5 HP, 5-10 HP, Above 10 HP, Battery Operated |
| Companies Covered | Vermeer Corporation, Ditch Witch, Little Beaver, Barreto Manufacturing, EZ-Trench, The Toro Company, Caterpillar, Guntert & Zimmerman, Cleveland Trencher Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Push Trencher Market Trends and Innovations
Electrification is consolidating technical architectures across the hand push trencher category, compressing the historical divergence between gas, hydraulic, and electric drive systems into a narrower band of battery-dominant designs. This convergence is reshaping supplier relationships and aftermarket service models.
Brushless DC motor technology is consolidating position as the default electric drive architecture for sub-300-pound trencher platforms. Landscaping firms operating in noise-restricted municipalities are adopting these units for residential irrigation and fiber drops. The technology is consolidating aftermarket parts demand toward standardized motor controllers and battery pack formats, eroding the proprietary component ecosystems that historically protected dealer margins.
OSHA excavation safety standards are tightening guard system requirements for walk-behind trenching equipment. Manufacturers must now integrate redundant kill switches and blade housing interlocks before commercial release. Utility contractors bidding on municipal fiber projects face specification audits that disqualify non-compliant equipment, accelerating replacement cycles among established fleet operators.
Rental yards are unbundling maintenance from equipment access, shifting toward usage-based service contracts that internalize repair risk. This procurement pattern disrupts the traditional dealer channel where parts markup subsidized sales support. Sun Belt equipment rental chains are piloting this model most aggressively, pressuring manufacturers to design for field-serviceability rather than dealer-dependent repair networks.
Hand Push Trencher Market Segmentation
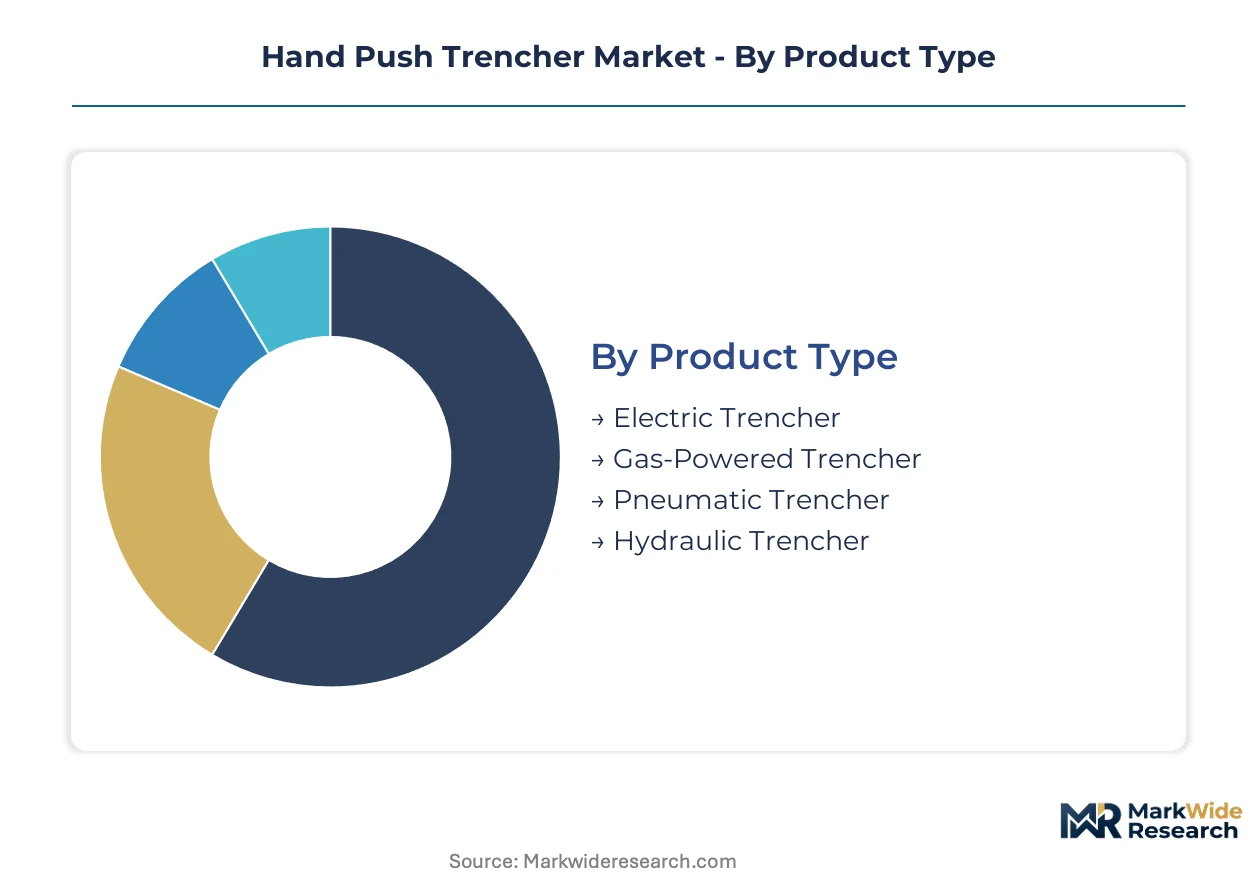
Segmentation in the hand push trencher market reveals how power source architecture, application intensity, and procurement authority reshape equipment specifications. Manufacturers configure motor systems, blade geometries, and chassis durability around distinct operational envelopes rather than pursuing universal designs.
Product Type:
Supply concentration tilts toward electric drive architectures as EPA certification burdens compress gas-powered production timelines and battery chemistry advances close torque gaps.
- Electric Trencher:Brushless DC motor platforms with lithium-ion battery packs deliver zero-emission operation for noise-restricted municipalities and indoor utility corridors. Landscaping firms in California and New York metro areas are standardizing fleets around these units to preempt local air quality ordinances.
- Gas-Powered Trencher:Small internal combustion engines with catalytic converter configurations retain dominance in rocky soil conditions where torque density requirements exceed current battery performance. Texas and Arizona contractors specify these units for aggregate-dense substrates in residential foundation work.
- Pneumatic Trencher:Compressed air drive systems serve confined industrial environments with explosion-risk protocols. Refinery maintenance contractors in the Gulf Coast region deploy these for pipeline corridor work.
- Hydraulic Trencher:Fluid power architectures deliver maximum blade force for clay-heavy soils and frost-line excavation. Municipal water departments in the Upper Midwest specify these for main-line burial below seasonal frost depths.
Gas-powered trenchers absorb the bulk of installed capacity; electric trenchers are expanding most quickly.
Application:
Cost tier differentiation separates specification-grade utility work from price-sensitive residential maintenance, with certification requirements and depth precision driving margin stratification.
- Utility Installation:Fiber optic burial and electrical conduit placement demand depth consistency within two-inch tolerances and soil displacement control that exceeds consumer-grade standards. FCC broadband infrastructure funding concentrates procurement among contractors bidding municipal projects.
- Irrigation Setup:Residential sprinkler system installation requires shallow trenching—typically four to six inches—with maneuverability prioritization over raw power. Sun Belt landscaping firms cycle equipment rapidly on these jobs during spring installation seasons.
- Lawn & Garden:Consumer and light commercial edge trenching for drainage and decorative borders represents the entry price tier. Rental yards stock lightweight units for weekend DIY projects.
- Landscaping:Multi-service firms require versatile platforms handling both softscape trenching and hardscape preparation. Fleet standardization around mid-power electric units is accelerating in noise-restricted jurisdictions.
- Road Construction:Compact trenchers supplement larger excavation equipment for shoulder drainage and conduit placement in restricted-access zones. State DOT maintenance contracts specify guard system compliance beyond standard consumer requirements.
Utility installation commands premium pricing; irrigation setup represents the highest volume deployment.
End User:
Customer type determines procurement channel—direct manufacturer relationships, specialized dealer networks, or rental yards—with distinct service expectations and parts availability requirements.
- Construction Contractors:General and specialty contractors prioritize equipment durability and OSHA guard system compliance for mixed-site deployment. These buyers negotiate fleet pricing and extended service agreements.
- Landscaping Firms:Seasonal demand patterns and crew turnover drive preference for standardized, field-serviceable platforms with minimal diagnostic complexity. Sun Belt multi-location operators are consolidating vendor relationships.
- Municipal Maintenance:Public procurement protocols mandate competitive bidding, emissions compliance documentation, and multi-year parts availability guarantees. Water departments and parks districts represent recurring replacement demand.
- Agriculture Operators:Farm-scale drainage and irrigation line installation requires cost-minimized equipment with tolerance for irregular maintenance intervals. Dealer proximity and same-day parts access determine purchase decisions.
Landscaping firms represent the largest addressable base; municipal maintenance offers the most predictable replacement cycles.
Power Rating:
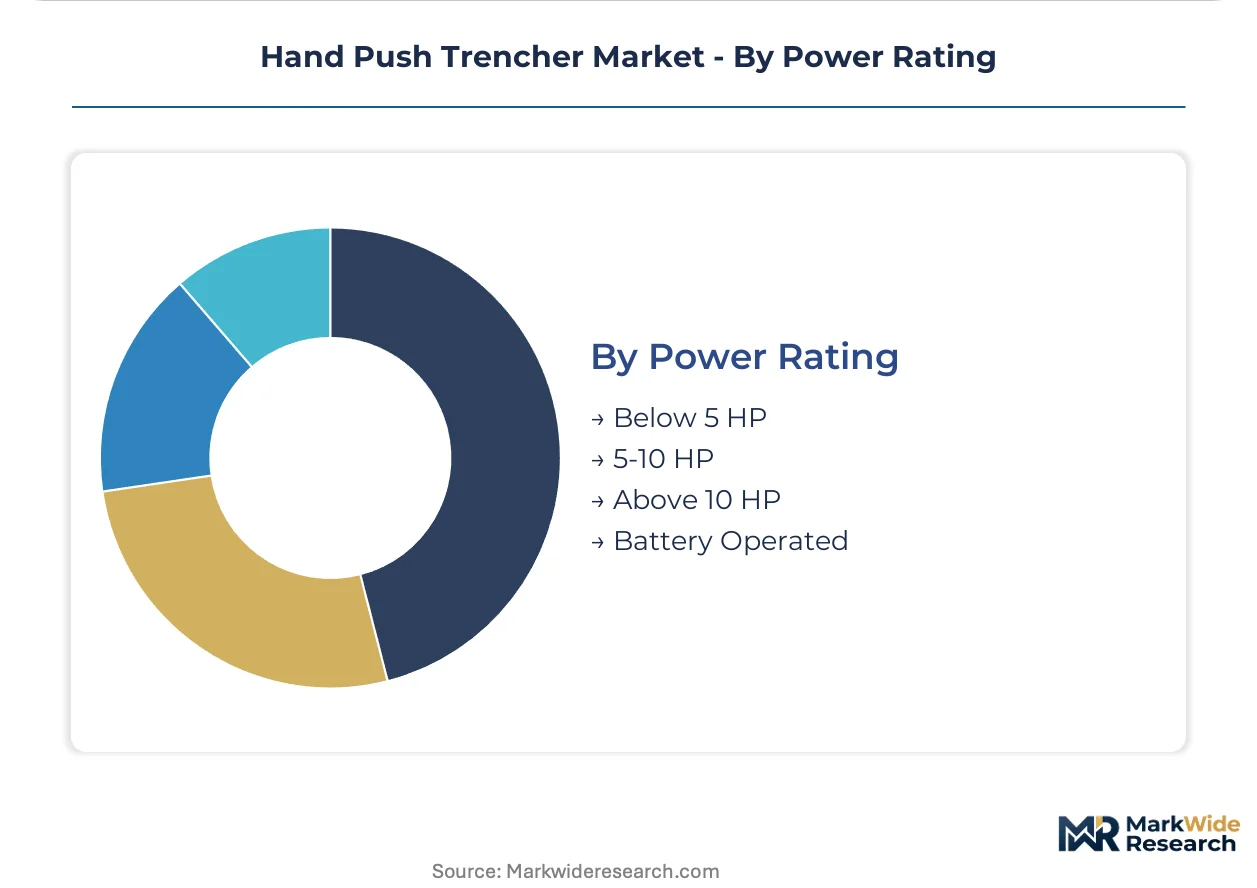
Volume distribution clusters in the 5-10 HP equivalent range where electric and gas architectures compete most directly, with battery-operated units disrupting historical segment boundaries.
- Below 5 HP:Lightweight platforms under 150 pounds serve rental markets and residential DIY applications. Maneuverability and transportability outweigh cutting speed in purchase criteria.
- 5-10 HP:Mid-range power density addresses the broadest application spectrum from lawn and garden through light utility work. Landscaping firm fleet standardization concentrates in this bracket.
- Above 10 HP:Heavy-duty hydraulic and large-displacement gas units tackle rocky soils, frost-line depths, and continuous commercial operation. Municipal and utility contractor specifications dominate demand.
- Battery Operated:Energy storage systems spanning 2-15 kWh now bracket traditional horsepower classifications, with voltage and amp-hour ratings displacing mechanical power metrics in procurement language. Indoor utility contractors and noise-restricted municipalities are driving fastest adoption.
5-10 HP configurations retain the largest installed base; battery operated systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones across Sun Belt metropolitan areas concentrate equipment procurement through accelerated depreciation incentives for landscaping and utility contractors expanding fleet capacity.
United States
Texas and Florida housing development drives trencher demand among landscaping firms upgrading irrigation installation capacity. EPA Tier 4 emissions standards compress gas-powered product development timelines while opening procurement pathways for battery-operated alternatives. Dallas-Fort Worth contractors concentrate fleet standardization efforts around mid-power electric units to meet municipal noise ordinances.
Germany
Municipal broadband burial projects under the Gigabit Infrastructure Act generate specification-grade demand for depth-consistent trenching equipment. REACH compliance requirements shape material selection for chassis and chain components across domestic manufacturers. Bavarian equipment fabricators supply compact trenchers to Central European utility contractors prioritizing OSHA-equivalent guard system certification.
China
Rural irrigation infrastructure upgrades under the Ministry of Water Resources modernization program expand addressable equipment demand. GB standards for small off-road machinery establish certification baselines for domestic and export-bound production. Shandong Peninsula manufacturing clusters supply cost-optimized trencher platforms to Southeast Asian agricultural markets.
Australia
Drought-response water efficiency mandates across New South Wales and Victoria drive recurring replacement demand for residential and municipal irrigation systems. WorkSafe Australia excavation safety protocols tighten guard system requirements for walk-behind trenching equipment entering commercial service. Sydney equipment rental chains pilot usage-based service contracts that internalize repair risk for landscaping contractor customers.
Canada
Federal broadband connectivity funding through the Universal Broadband Fund stimulates fiber optic burial projects suited to compact trencher deployment. Environment and Climate Change Canada small engine emissions regulations accelerate manufacturer investment in battery-electric product lines. Ontario landscaping firms standardize fleets around electric drive systems to comply with Toronto municipal noise restrictions.
Hand Push Trencher Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: horizontal directional drilling heritage companies leveraging utility channel relationships, specialized trenching equipment manufacturers controlling aftermarket parts ecosystems, and diversified outdoor power equipment portfolios serving multi-product procurement contracts. Dominant competitive moves include electrification roadmap investments to capture EPA-driven margin pools and dealer network consolidation to secure rental channel access.
Among heritage utility equipment specialists, Vermeer Corporation and Ditch Witch occupy positions anchored by horizontal directional drilling expertise that translates into compact trenching specification credibility. Little Beaver exemplifies the portability-focused archetype targeting lightweight rental market segments where maneuverability determines procurement decisions. The Toro Company sits within the diversified outdoor power equipment tier, leveraging multi-product portfolio breadth to capture landscaping firm procurement consolidation.
| Leading Market Players |
|---|
| Vermeer Corporation |
| Ditch Witch |
| Little Beaver |
| Barreto Manufacturing |
| EZ-Trench |
| The Toro Company |
| Caterpillar |
| Guntert & Zimmerman |
| Cleveland Trencher Company |
| Others |
Pricing and Supply Chain Analysis
Backward integration into battery pack assembly anchors both supply security and pricing power for electric trencher manufacturers navigating EPA certification timelines. This captive production of lithium-ion energy systems insulates margin pools from commodity volatility while compressing lead-time premiums that gas-powered competitors must absorb for catalytic converter sourcing.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as landscaping firms face compressed spring installation seasons. Three-tier pricing structure across specification-grade utility units, mid-range landscaping platforms, and economy rental-tier equipment reflects certification burden stratification. Cost compression in the rental tier intensifies because steel and aluminum input volatility erodes mid-manufacturer margins. Municipal maintenance departments exhibit lowest price sensitivity due to multi-year funding cycles, while residential DIY renters demonstrate highest elasticity to per-day rate fluctuations.
Supply Chain Analysis
Workforce availability constraints in Shandong Peninsula manufacturing clusters and Upper Midwest hydraulic component hubs tether production capacity to regional labor migration patterns. Chassis fabrication draws from Chinese steel rolling mills, brushless DC motors source from South Korean electronics suppliers, and lithium cells feed from Japanese chemical conglomerates. Single-source vulnerability concentrates in specialized hydraulic pump architectures for frost-line excavation equipment. Distribution runs through specialized dealer networks controlling aftermarket parts availability rather than direct manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 emissions standards for small off-road engines construct a cost-of-compliance moat that rewards pre-certified incumbents while filtering undercapitalized entrants from specification-grade procurement channels.
For Market Incumbents: Anchor dealer network consolidation in Sun Belt metropolitan corridors where landscaping firm fleet standardization concentrates procurement authority. Invest in battery management system diagnostic training infrastructure to offset electrification skill gaps among field service technicians. Defend against rental channel disintermediation by designing modular field-serviceable architectures that reduce dealer-dependent repair reliance.
For New Entrants and Emerging Players: FCC broadband infrastructure funding in the United States opens a window for specification-grade utility contractors seeking OSHA-compliant compact trenching equipment. Target indoor utility corridors in noise-restricted municipalities where zero-emission procurement mandates outpace incumbent electrification roadmaps. Pursue usage-based service contract pilots with equipment rental chains piloting internalized repair risk models.
For Investors and Strategic Acquirers: Exit pathways concentrate in diversified outdoor power equipment conglomerates seeking compact trenching capability to complete landscaping portfolio breadth. Long-term viability favors manufacturers with demonstrated EPA certification velocity and captive battery supply arrangements. Watch for inflection signals in municipal fiber procurement volumes where depth-consistency specifications accelerate replacement cycles among established fleet operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Roadmap Investment | Captures EPA-driven margin pools as gas-powered architectures face certification compression. |
| Dealer Network Consolidation | Secures rental channel access and controls aftermarket parts availability in Sun Belt corridors. |
| Battery Supply Agreement | Locks in lithium-ion cell access before energy storage demand broadens across outdoor power equipment. |
| OSHA Guard System Certification | Qualifies equipment for municipal fiber projects with specification audits disqualifying non-compliant units. |
| Field-Serviceability Redesign | Aligns product architecture with rental channel shift toward usage-based contracts internalizing repair risk. |
Research Methodology
Document review covered SEC filings from diversified outdoor power equipment manufacturers, EPA certification databases for small off-road engines, and FCC broadband infrastructure funding disclosures, complemented by interviews with landscaping firm fleet managers, utility contractor procurement leads, equipment rental chain operations directors, and trencher manufacturer product development executives. Secondary validation drew from OSHA excavation safety standard documentation, steel and aluminum commodity price indexes, and municipal procurement contract archives. Bottom-up equipment shipment estimates triangulated against top-down construction and landscaping industry expenditure models.
Unit volume and value projections across the analysis window applied segmented growth rates to power source categories, application intensity tiers, and regional housing development patterns. The modeling framework incorporated lithium-ion energy density improvement curves, EPA certification timeline distributions, and Sun Belt metropolitan construction permit trajectories as industry-specific forecast inputs. CAGRs derived from logistic adoption curves for electric drive systems intersecting with replacement demand cycles in gas-powered installed bases.
Caveats apply where EPA regulatory enforcement intensity, lithium supply contract renegotiations, or Sun Belt housing market corrections could materially shift the outlook. Forecasts reflect documented assumptions regarding battery chemistry advancement rates and municipal broadband funding continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Wheel Aligner Equipment Market
Construction Equipment
Crossover Ladder Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Gear Shaping Machine Market
Construction Equipment
Industrial Grout Pumps Market
Construction Equipment
Earthmover Market
Construction Equipment
Bulldozer Market
Construction Equipment
Global Floor Grinding Machine Market
Construction Equipment
Europe Welding Equipment Market
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
Drone-Based Solutions in Construction Market
Construction Equipment
Line Boring Machine Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Autonomous Cranes Market
Construction Equipment
Vibratory Rammer Market