
 Plastic Sifter Caps Market | 2026-2036
Plastic Sifter Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Sifter Caps Market Analytics
Market Context with Strategic Players
The plastic sifter caps market is pivoting around a widening gap between premium cosmetic-grade closures and commodity food-service lids. Berlin Packaging leverages its North American distribution network to dominate mid-tier pharmaceutical contracts. Berry Global Group anchors high-volume polypropylene production for household and food industry clients. Silgan Plastics differentiates through injection-molding precision for flip-top cosmetic applications.
Technical Definition and Structural Segments
Plastic sifter caps are thermoplastic dispensing closures incorporating perforated membranes or mesh screens, typically molded in polyethylene or polypropylene with 20-400 micron aperture tolerances, designed to control granular or powdered product flow in consumer packaging. Flip-top and screw-top variants occupy the mature volume core, while push-down formats command margin premiums in pharmaceutical child-resistant segments. Polypropylene leads material type selection due to moisture resistance and compatibility with hot-fill processes, though PET grades are gaining traction in transparent cosmetic packaging where visual product display drives shelf appeal.
Regulatory Frame and Forward-Looking Close
The US FDA maintains strict extractables and leachables standards for pharmaceutical sifter caps, while the EU REACH framework restricts certain plasticizers in cosmetics-contact materials, forcing converters to validate alternative polymer formulations. Germany's national packaging regulator enforces extended producer responsibility quotas that reshape material recovery economics for multi-component closures. Stakeholders must monitor evolving mechanical recycling infrastructure capacity, as post-consumer feedstock availability will determine which material type investments retain long-term viability.
Market Dynamics
The EU's Single-Use Plastics Directive is forcing converters to redesign multi-component closures for mechanical recyclability, compressing margins while opening premium positioning for validated circular grades.
Growth Catalysts
- REACH plasticizer restrictions:ECHA's tightening limits on phthalates in cosmetics-contact materials pull demand toward compliant polypropylene formulations certified for mineral makeup packaging.
- Hot-fill process compatibility:Polypropylene's thermal stability enables sifter cap integration with aseptic powder filling lines, accelerating adoption in pharmaceutical contract manufacturing.
- Hamburg-Düsseldorf corridor concentration:German personal care contract manufacturers cluster along this logistics axis, concentrating demand for child-resistant flip-top variants with 20-50 micron mesh precision.
Market Restraints
- Post-consumer PP feedstock scarcity:Mechanical recycling infrastructure for food-grade polypropylene remains underdeveloped in Southern Europe, constraining supply of validated circular resins.
- Multi-component disassembly economics:Sifter caps combine incompatible materials (membrane, ring, base) that complicate automated sorting, raising extended producer responsibility fees under Germany's packaging regulator.
- Glass jar substitution in premium cosmetics:Luxury mineral makeup brands are reverting to aluminum shaker tops for perceived sustainability, displacing plastic sifter caps in the highest-margin segment.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO's tightening child-resistant packaging mandates for pediatric powders create first-mover advantage for converters with USP <661> validated designs.
- Digital printing convergence:Direct-to-object inkjet on PP substrates enables lot-level traceability without label adhesives, opening serialization contracts for clinical trial materials.
- Extended producer responsibility credits:Germany's packaging regulator awards bonus quotas for mono-material designs, incentivizing membrane-to-base integration in screw-top formats.
Industry Challenges
- Extractables validation timelines:USP <661> and <1661> testing for pharmaceutical sifter caps requires 12-18 month qualification cycles, freezing design iterations mid-development.
- Mesh welding precision:Ultrasonic membrane attachment to polypropylene rings demands micron-level calibration that outstrips technician training pipelines in emerging manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Sifter Caps Market |
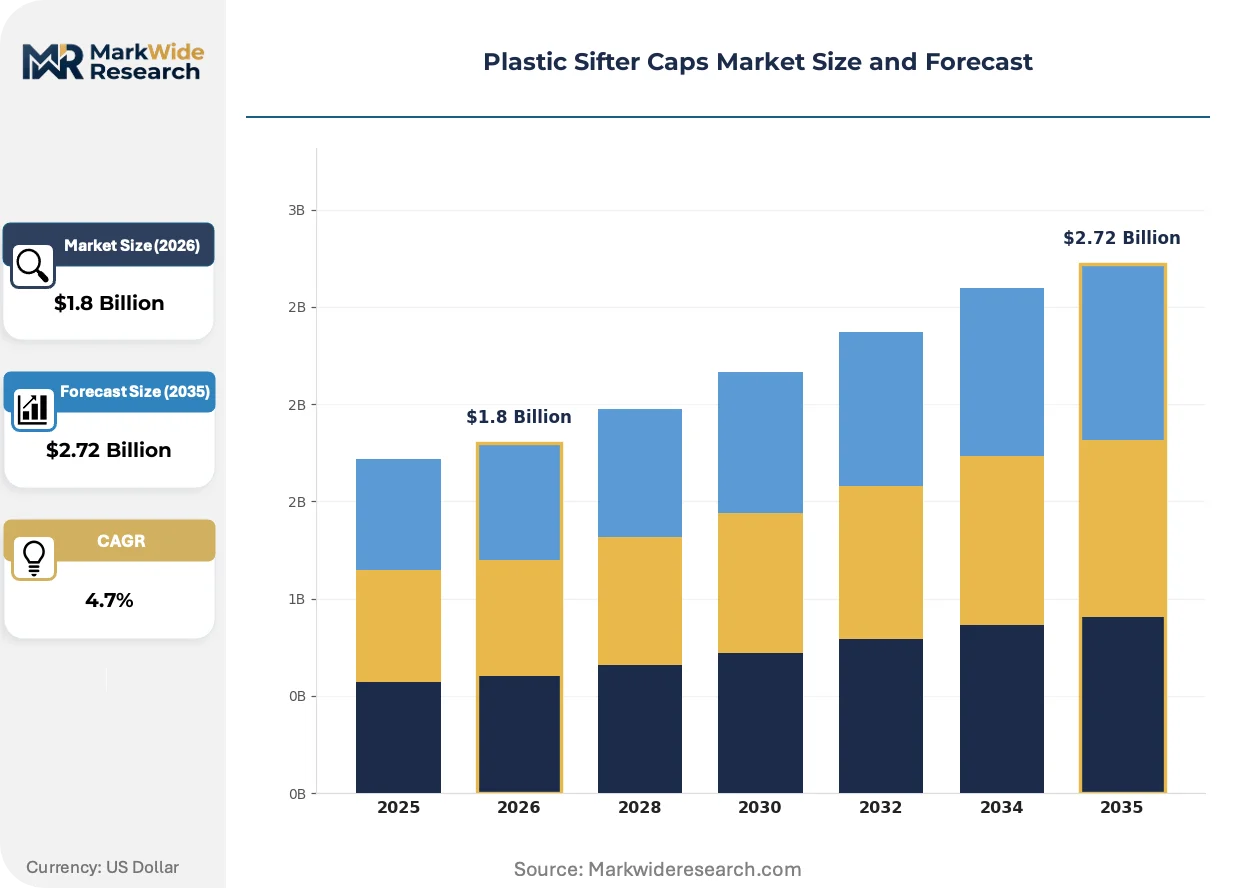
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Top, Shaker, Screw Top, Push Down Material Type: Polyethylene, Polypropylene, PVC, PET End User: Cosmetics, Food Industry, Pharmaceuticals, Household Size: Small, Medium, Large, Extra Large |
| Companies Covered | Berlin Packaging, Aaron Packaging, SKS Bottle & Packaging, Silgan Plastics, The Cary Company, Noblesmit Enterprise, Burch Bottle & Packaging, Shree Balaji Closures, Berry Global Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Sifter Caps Market Evolving Landscape
Material substitution and regulatory compliance are compressing design cycles while opening differentiation through validated circularity claims and precision manufacturing capabilities.
Post-industrial recycled polypropylene is absorbing volume share in cosmetic-grade sifter caps as brands seek immediate scope 3 reductions without awaiting food-grade mechanical recycling scale-up. Premium mineral makeup houses in Germany and France are specifying 30-50% PIR content with full batch traceability. This material shift is absorbing price premiums previously captured by virgin medical-grade resins, compressing tier differentiation.
REACH Annex XVII restrictions on microplastic-releasing products are forcing reformulation of abrasive-containing sifter-dispensed scrubs, with ECHA's 2023 opinion triggering downstream redesign of aperture geometries to control particle size distribution. Cosmetics contract manufacturers are responding with laser-perforated membranes replacing woven mesh in exfoliant packaging. Southern European converters face the steepest compliance costs due to limited in-house laser micromachining capacity.
Direct procurement from converters is displacing distributor intermediaries among mid-size pharmaceutical packagers seeking faster custom sampling and shorter MOQ flexibility. This channel compression is most visible in the US Northeast corridor, where compounders with in-house toolrooms are capturing relationships previously held by national packaging distributors. Buyers are unbundling design services from volume contracts, paying premium piece rates for rapid prototyping while driving hard on scaled production pricing.
Plastic Sifter Caps Market Segmentation
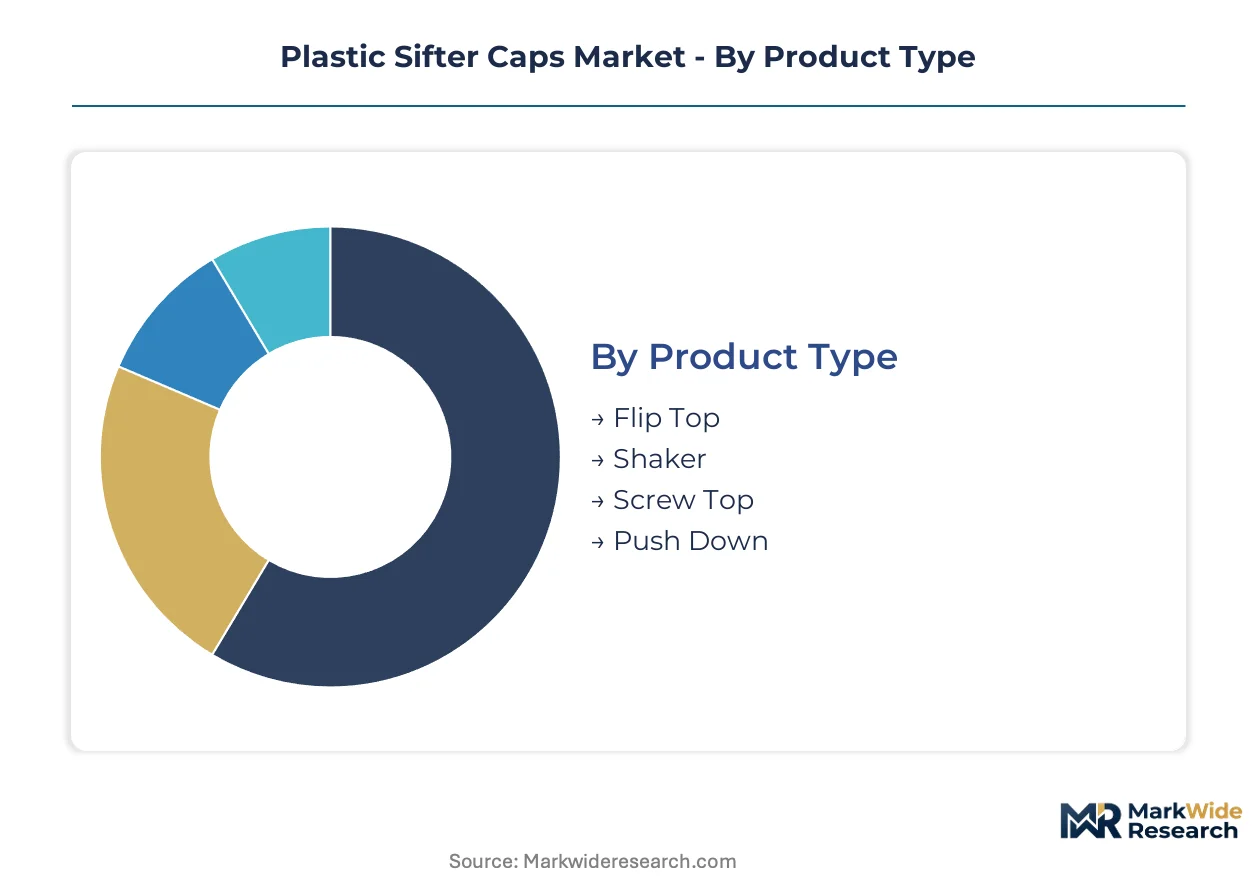
Sifter cap procurement patterns diverge sharply across end-use applications, with pharmaceutical buyers prioritizing child-resistant certification while cosmetics houses emphasize visual shelf presence. Material selection and aperture precision requirements create distinct technical specifications that reshape converter capability investments.
Product Type:
Flip-top and screw-top variants dominate commodity volume, yet push-down formats command substantial margin premiums in regulated segments.
- Flip Top:Hinged polypropylene lids with integrated mesh membranes enable single-hand dispensing for loose powder cosmetics. German mineral makeup brands along the Hamburg-Düsseldorf corridor specify 20-50 micron laser-welded apertures for controlled flow.
- Shaker:Dual-opening designs with coarse and fine mesh options serve bulk spice and seasoning applications. Food industry buyers in Italy and Spain prioritize hot-fill compatibility and moisture barrier performance.
- Screw Top:Threaded closures with removable sifter inserts dominate pharmaceutical powder packaging. USP extractables testing requirements extend qualification timelines for converters serving FDA-regulated contract manufacturers.
- Push Down:Child-resistant mechanisms with simultaneous press-and-turn activation satisfy pharmaceutical safety mandates. CDSCO tightening of pediatric packaging rules in India accelerates demand for validated USP designs.
Flip-top leads volumes today; push-down is gaining share fastest.
Material Type:
Moisture resistance and thermal stability separate premium grades from commodity substitutes in converter pricing structures.
- Polyethylene:LDPE and HDPE grades offer cost efficiency for dry food applications with moderate barrier requirements. Southern European converters favor PE for price-sensitive spice packaging where optical clarity is secondary.
- Polypropylene:Superior moisture resistance and hot-fill process compatibility anchor pharmaceutical and cosmetic specifications. REACH plasticizer restrictions pull cosmetics-contact applications toward certified PP formulations.
- PVC:Declining adoption in food-contact applications due to ECHA scrutiny of plasticizer migration. Limited to industrial non-consumable powder dispensing where cost minimization overrides regulatory exposure.
- PET:Transparent grades enable visual product display for premium mineral makeup. French and German luxury cosmetics houses specify PET for shelf differentiation despite higher resin costs.
Polypropylene dominates current procurement; PET is expanding most quickly in transparent cosmetic segments.
End User:
Regulatory stringency and batch traceability requirements fragment buyer priorities across application verticals.
- Cosmetics:Loose powder and mineral makeup packaging drives demand for precise aperture control and premium surface finishes. ECHA microplastic restrictions are forcing redesign of exfoliant-dispensing geometries.
- Food Industry:Spice, seasoning, and baking powder applications prioritize cost efficiency and moisture protection. Hot-fill aseptic processing compatibility separates qualified converters from commodity suppliers.
- Pharmaceuticals:Pediatric and geriatric powder formulations require child-resistant and senior-friendly opening mechanisms. USP extractables validation creates 12-18 month qualification barriers for new converter entry.
- Household:Cleaning powder and abrasive dispensing applications tolerate wider aperture tolerances. Price pressure from private-label retail contracts compresses margins for standard-grade producers.
Cosmetics and pharmaceuticals together anchor premium tier demand; food industry procurement scales highest in unit volumes.
Size:
Container volume and dispensing precision requirements determine diameter and mesh specifications in converter tooling investments.
- Small:20-30mm diameters serve travel-size cosmetics and single-dose pharmaceutical sachets. Precision laser micromachining requirements concentrate production with German and French converters.
- Medium:35-45mm formats dominate standard loose powder and spice applications. Balanced tooling amortization and volume scalability attract mid-tier contract manufacturers.
- Large:50-60mm closures accommodate bulk household and professional cleaning powders. Lower aperture precision tolerances permit wider supplier qualification.
- Extra Large:65mm+ diameters serve industrial and institutional dispensing with reinforced structural ribs. Limited customization demand reduces converter competition intensity.
Medium sizes command the broadest addressable demand; small formats show the steepest expansion trajectory in travel-size cosmetic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tooling engineers and polymer chemists cluster around Hamburg and Düsseldorf in Germany, anchoring European precision manufacturing for cosmetic-grade sifter caps. This workforce concentration shapes procurement patterns across pharmaceutical and personal care verticals.
Germany
Mineral makeup contract manufacturers along the Hamburg-Düsseldorf corridor drive demand for 20-50 micron laser-welded flip-top variants. The national packaging regulator enforces extended producer responsibility quotas that reshape material recovery economics for multi-component closures. Bavarian converters are investing in mono-material screw-top designs to capture bonus quotas under these rules.
United States
FDA-regulated pharmaceutical powder packagers in the Northeast corridor prioritize USP extractables validation for child-resistant push-down formats. The FDA maintains strict extractables and leachables standards that freeze design iterations mid-development. Mid-size compounders with in-house toolrooms in New Jersey and Pennsylvania are displacing national packaging distributors through direct procurement relationships.
India
CDSCO tightening of child-resistant packaging mandates for pediatric powders accelerates demand for validated USP designs in Mumbai and Ahmedabad pharmaceutical clusters. The Central Drugs Standard Control Organization is tightening enforcement of pediatric safety rules. Contract manufacturers in Maharashtra and Gujarat are qualifying new converter relationships to meet these requirements.
France
Luxury mineral makeup houses in Paris and Lyon specify PET transparent grades for shelf differentiation despite higher resin costs. ECHA REACH restrictions on plasticizers in cosmetics-contact materials force validation of alternative polymer formulations. Converters in the Île-de-France region are absorbing compliance costs through laser micromachining investments for exfoliant-dispensing geometries.
Italy
Spice and seasoning packagers in Emilia-Romagna prioritize hot-fill compatible polypropylene for cost-sensitive applications with moderate barrier requirements. Limited mechanical recycling infrastructure for food-grade polypropylene in Southern Europe constrains supply of validated circular resins. Bologna-based converters are sourcing post-industrial recycled content to meet immediate scope 3 reduction targets.
Plastic Sifter Caps Market Competitive Landscape
Capital-heavy producers with captive injection-molding assets compete with asset-light designers outsourcing precision membrane welding to specialized contract manufacturers. The vendor base organizes around three tiers: multinational packaging conglomerates with integrated polymer compounding, mid-cap regional specialists with toolroom capabilities, and niche precision converters serving pharmaceutical validation requirements. Two dominant competitive moves are reshaping positioning: direct-to-brand procurement channel compression eliminating distributor intermediaries, and backward integration into post-industrial recycled resin sourcing to secure circular feedstock claims.
Among North American packaging conglomerates, Berlin Packaging and Berry Global Group exemplify scale-driven archetypes with integrated distribution networks spanning pharmaceutical and household verticals. Silgan Plastics occupies a position within the precision-molding specialist tier, differentiated through injection-molding capabilities for flip-top cosmetic applications. Indian specialists including Shree Balaji Closures represent the emerging-market validation-focused archetype, capitalizing on CDSCO regulatory tightening to capture first-mover advantage in pediatric powder packaging.
| Leading Market Players |
|---|
| Berlin Packaging |
| Aaron Packaging |
| SKS Bottle & Packaging |
| Silgan Plastics |
| The Cary Company |
| Noblesmit Enterprise |
| Burch Bottle & Packaging |
| Shree Balaji Closures |
| Berry Global Group |
| Others |
Value Network & Pricing Analysis
CDSCO tightening of child-resistant packaging mandates in India pulls pharmaceutical buyers toward validated USP designs, forcing converters to absorb extended qualification timelines and compress margins on standard-grade offerings. This specification-driven procurement shift concentrates pricing power with compounders holding in-house toolroom capabilities.
Pricing Analysis
The bundled-vs-unbundled service split separates design prototyping from volume production contracts. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and aperture precision, with USP-validated push-down formats commanding substantial premiums over commodity flip-tops. Price differentiation hinges on laser micromachining capability and batch traceability systems. Cost compression in the standard tier intensifies as post-industrial recycled polypropylene absorbs volume share. Food industry buyers in Southern Europe exhibit highest price sensitivity, while German mineral makeup houses prioritize precision over unit cost.
Supply Chain Analysis
Reverse-logistics flows for multi-component sifter caps remain underdeveloped, with membrane-to-base disassembly economics constraining mechanical recycling yields. Manufacturing concentrates in Germany, the United States, and India, with Hamburg-Düsseldorf and Mumbai-Ahmedabad corridors anchoring precision tooling clusters. Raw material sourcing draws from virgin polypropylene resin suppliers, laser micromachining equipment vendors, and post-industrial recycled feedstock aggregators. Single-source vulnerability sits with specialized ultrasonic welding equipment providers. Distribution runs through direct procurement relationships displacing national packaging distributors, particularly among mid-size pharmaceutical contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic sifter caps market functions as a stable compounder, with regulatory mandates for child-resistant and recyclable packaging driving steady specification upgrades across pharmaceutical and cosmetic verticals.
For Market Incumbents: Lock in converter relationships with German personal care contract manufacturers along the Hamburg-Düsseldorf corridor through dedicated capacity allocations for 20-50 micron laser-welded flip-tops. Deepen backward integration into post-industrial recycled polypropylene sourcing to secure circular feedstock claims ahead of EPR quota tightening. Certify mono-material screw-top designs to capture bonus quotas under Germany's packaging regulator. For New Entrants and Emerging Players: The price-point gap between USP-validated pharmaceutical grades and unvalidated cosmetic standards creates entry space for mid-tier converters with rapid prototyping capabilities. Target Indian pharmaceutical packaging clusters in Maharashtra and Gujarat where CDSCO enforcement gaps persist. Pursue direct-to-brand procurement channel compression with US Northeast corridor compounders seeking shorter MOQ flexibility. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-molding specialists holding captive laser micromachining capabilities and validated USP extractables testing infrastructure. Long-term viability favors asset-light designers with outsourced membrane welding relationships that can scale without heavy injection-molding capex. Watch for inflection in food-grade mechanical recycling infrastructure capacity across Southern Europe as the signal determining circular resin supply economics.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Design Integration | Germany's packaging regulator awards bonus EPR quotas for membrane-to-base unified screw-top formats. |
| Laser Micromachining Capacity Expansion | ECHA microplastic restrictions force exfoliant aperture redesign toward laser-perforated membranes. |
| Post-Industrial Recycled Resin Sourcing | Cosmetic brands specify 30-50% PIR content with full batch traceability for immediate scope 3 reductions. |
| Direct Procurement Channel Development | Mid-size pharmaceutical packagers unbundle design services from volume contracts for faster custom sampling. |
| USP Extractables Validation Investment | FDA-regulated contract manufacturers freeze design iterations mid-development without qualified converter relationships. |
Research Methodology
Multiple input streams — converter production data, brand procurement specifications, and regulatory filing databases — were reconciled through bottom-up and top-down triangulation. Primary interviews with injection-molding plant managers, cosmetic packaging procurement leads, pharmaceutical contract manufacturing executives, and laser micromachining equipment specialists informed capability and capacity assessments. Secondary validation drew from FDA extractables guidance documents, ECHA REACH restriction updates, German packaging regulator EPR quota filings, and customs trade data for polypropylene resin flows.
Data-stream reconciliation anchored volume and value projections across the modeling period. Segmentation dimensions included product type, material grade, end-use vertical, aperture precision tier, and regional regulatory cluster. CAGRs were derived from trend extrapolation of specification upgrade cycles and substitution elasticity between virgin and recycled resin grades. Forecast inputs incorporated EPR quota phase-in schedules and CDSCO enforcement intensity timelines for pediatric packaging mandates.
Caveats apply where mechanical recycling infrastructure build-out delays or ECHA plasticizer restriction scope expansions could materially shift the outlook. Forecasts reflect assumptions around converter qualification timeline stability and brand sustainability commitment durability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
Overcaps Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
Tear-Tab Lids Market
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
Global Aluminum Caps and Closures Market
Caps and Closures
Twist Caps Market
Caps and Closures
Italy Plastic Caps and Closures Market
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
Crown Closures Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
Asia Pacific Metal Caps and Closures Market
Caps and Closures
Molded Fiber End Caps Market
Caps and Closures
North America Metal Caps and Closures Market
Caps and Closures
Spain Plastic Cap and Closure Market