
 Flapper Caps Market | 2026-2036
Flapper Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Flapper Caps Market Analytics
Aftermarket restoration and period-authentic refurbishment is rewriting where profit pools accumulate in heritage headwear. Goorin Bros. leverages its century-old archive patterns to sustain premium positioning in reproduction flapper styles. Christys' London anchors British manufacturing heritage through in-house blocking and hand-finishing capabilities. Eugenia Kim differentiates via contemporary reinterpretations that occupy the bridge between costume authenticity and ready-to-wear accessibility.
Flapper caps denote close-fitting, brimless head coverings constructed from felt, straw, or fabric over a rigid or semi-rigid form, typically featuring art deco embellishments, cloche silhouettes, or jeweled appliqué. These pieces serve both theatrical costuming and contemporary fashion markets where historical accuracy or vintage aesthetic drives purchasing decisions. Decorative Caps command the strongest margin pools due to labor-intensive hand-embroidery and beadwork, while Custom Caps represent the fastest-growing segment as bespoke millinery experiences gain traction among luxury consumers. Standard Caps remain the volume backbone for theatrical rental houses and film production wardrobe departments.
FDA textile contact standards and California Proposition 65 chemical disclosure rules shape material sourcing for domestic producers, while OEKO-TEX and REACH certifications govern European import eligibility. The EU Green Deal's textile sustainability requirements are forcing reformulation of synthetic embellishments and dye processes across the supply base. Stakeholders must monitor how evolving extended producer responsibility frameworks for fashion goods alter cost structures for small-batch artisan producers versus scaled manufacturers.
Market Dynamics
Extended producer responsibility frameworks for fashion goods are compressing margins for small-batch artisan milliners while advantaging scaled manufacturers with compliance infrastructure. This structural force is redistributing competitive position across the heritage headwear value chain.
Growth Catalysts
- EU Green Deal textile sustainability mandates:These requirements are accelerating reformulation of synthetic embellishments and dye processes, creating certification premiums for compliant suppliers.
- Theatrical costume department procurement expansion:Film and stage wardrobe departments are increasing volume commitments for period-authentic reproductions to satisfy streaming content production schedules.
- Artisan millinery cluster concentration:United Kingdom, Italy, and France are deepening specialized supplier networks that reduce lead times for bespoke decorative headwear.
Market Restraints
- Felt and straw input cost volatility:Climate-impacted wool and raffia harvests are squeezing material budgets for traditional construction methods.
- REACH compliance friction:European chemical disclosure rules are blocking non-certified imports and lengthening supplier qualification timelines.
- Machine-embroidered substitute threat:Automated beadwork from Asian manufacturing hubs is undercutting hand-finished premium positioning.
Strategic Opportunities
- Bespoke millinery experience channel innovation:Luxury consumers are paying experience premiums for in-person fitting and customization appointments.
- ASTM textile standard evolution:United States regulatory alignment with performance testing is opening certified product pathways for domestic producers.
- Vintage fashion retail underpenetration:Secondary market platforms are creating new inventory velocity for authenticated period pieces.
Industry Challenges
- Hand-blocking skill scarcity:Master milliners with traditional wooden block expertise are aging out of the workforce faster than apprenticeship programs replace them.
- OEKO-TEX certification timeline compression:Multi-stage testing protocols are delaying product launches for seasonal collections.
- California Proposition 65 disclosure complexity:Chemical labeling requirements are forcing reformulation of vintage-accurate dye recipes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flapper Caps Market |
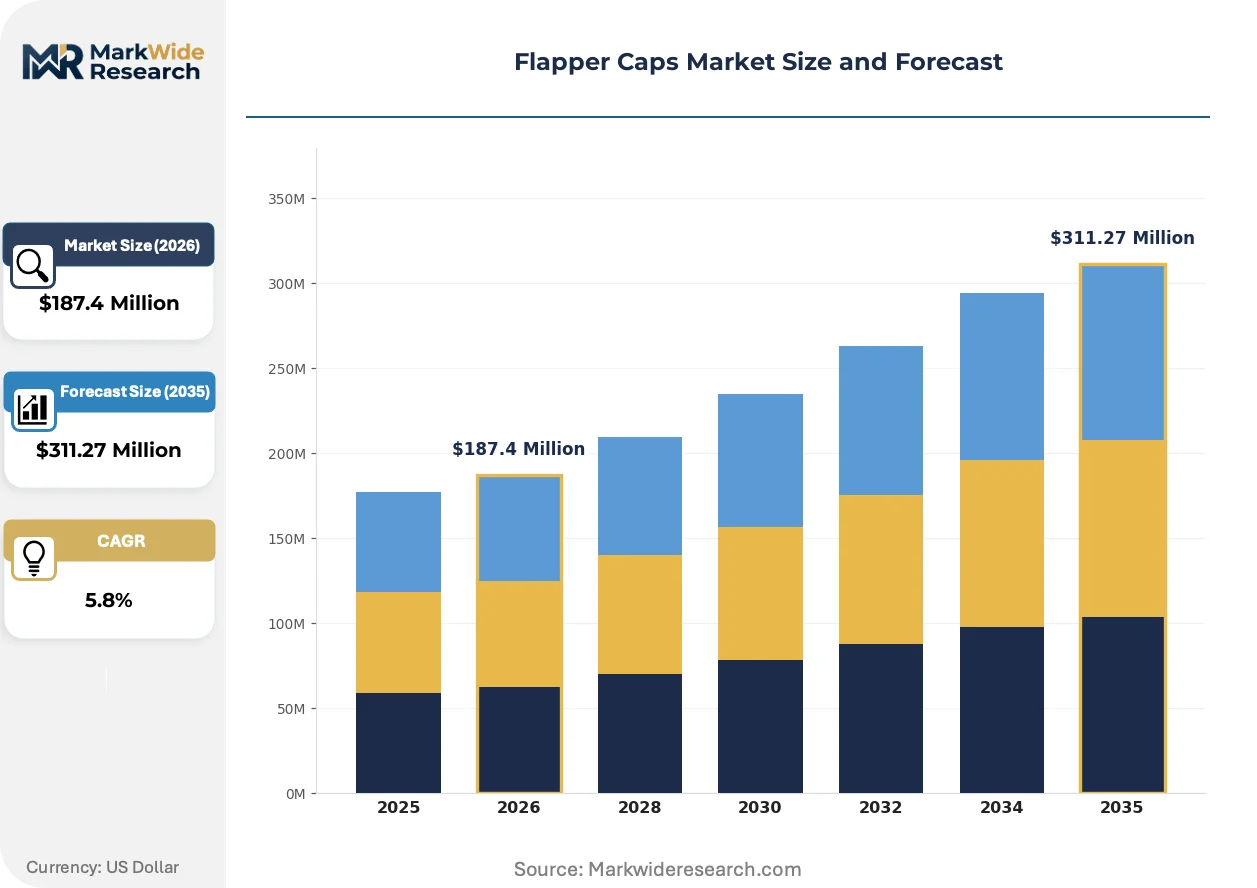
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Caps, Decorative Caps, Functional Caps, Custom Caps Size: Small, Medium, Large, Extra Large Material: Cotton, Polyester, Nylon, Blended Fabrics Usage: Fashion Wear, Sports Wear, Work Wear, Promotional Use |
| Companies Covered | Goorin Bros., Louise Green Millinery Co., Eugenia Kim, Kokin, Helen Kaminski, Betmar New York, Christys’ London, Arturo Rios, Weatherchem Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flapper Caps Market Evolving Landscape
Digital pattern archives and sustainable material science are converging to transform how heritage silhouettes are reproduced and sold. These forces are compressing design-to-retail cycles while elevating transparency expectations.
3D-printed hat blocks derived from museum collection scans are rendering obsolete hand-carved wooden forms in reproduction workshops. Costume departments at major streaming productions are adopting these tools for rapid iteration. The technology is compressing sample lead times from weeks to days while preserving archival accuracy.
REACH Annex XVII restrictions on nickel release in metal components are forcing substitution of vintage-accurate findings with hypoallergenic alternatives. Millinery suppliers in France and Italy are reformulating jeweled appliqué assemblies to maintain European market access. Decorative Caps segments are absorbing the highest compliance costs due to embellishment density.
Rental and resale platforms are capturing growing share of theatrical and consumer demand previously served by outright purchase. Wardrobe departments are unbundling ownership from access, prioritizing authenticated provenance over new production. United Kingdom vintage fashion retailers are building the deepest consignment networks for verified period headwear.
Flapper Caps Market Segmentation
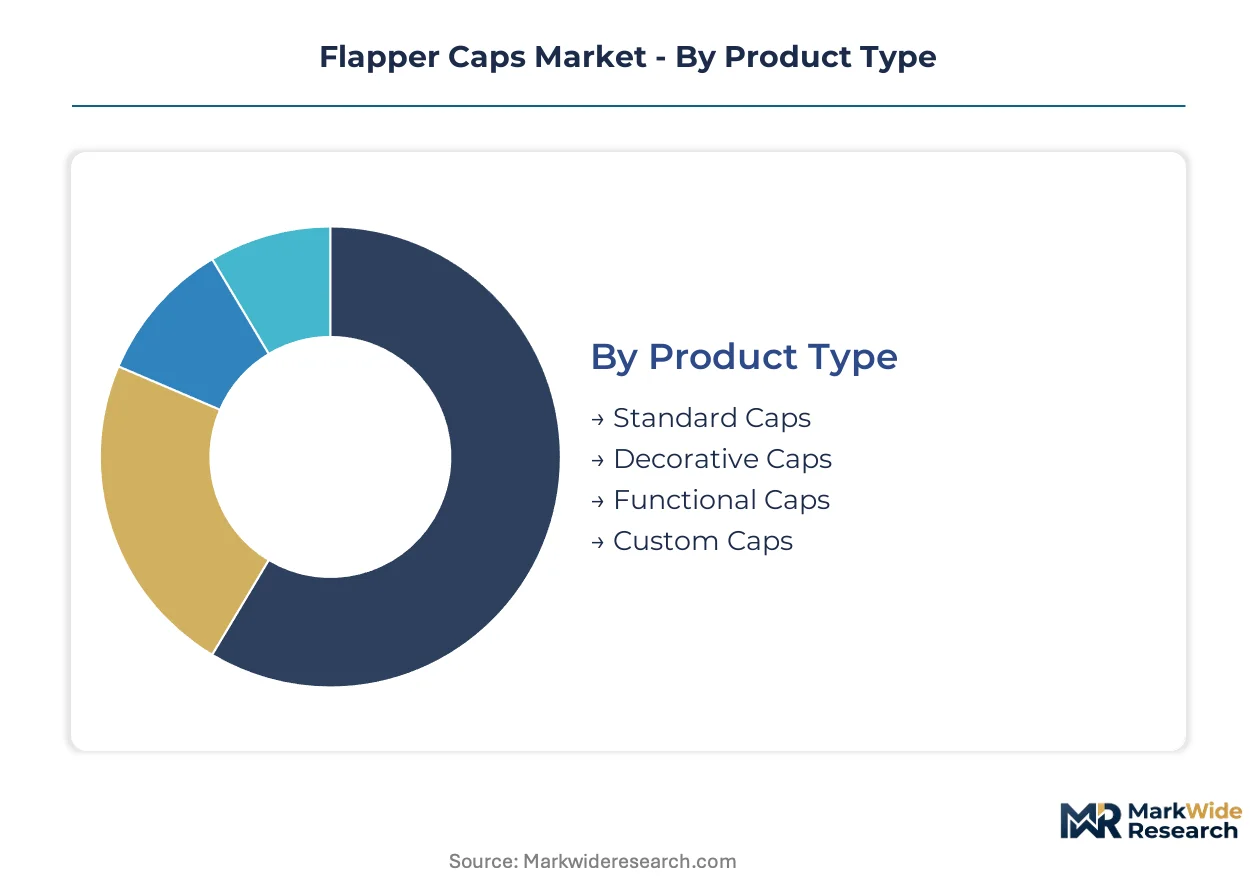
Segmentation in flapper caps reveals how artisan construction methods, theatrical procurement patterns, and regulatory compliance requirements fragment demand across distinct product tiers. Each dimension exposes different margin structures and supply chain vulnerabilities.
Product Type:
Mature reproduction formats coexist with emerging experiential formats across this spectrum.
- Standard Caps:These pieces utilize machine-pressed felt or straw over standardized wooden blocks with minimal embellishment. Theatrical rental houses in London and New York concentrate procurement here, prioritizing durability and rapid turnaround over archival precision.
- Decorative Caps:Hand-embroidery, beadwork, and jeweled appliqué elevate these pieces. Italian millinery clusters in Florence and Milan absorb the highest concentration of demand, driven by streaming production budgets for period-authentic costuming.
- Functional Caps:Weather-resistant treatments and reinforced construction serve outdoor reenactment markets. These prioritize utility over aesthetic accuracy.
- Custom Caps:Bespoke fitting appointments and client-specific archival research define this emerging tier. Luxury consumers in Paris and Los Angeles are driving expansion through experience-based purchasing.
Standard Caps handles the majority of throughput; Custom Caps is the fastest mover on share.
Size:
Volume concentrates in mid-range dimensions while specialty sizing commands premium positioning.
- Medium:This dimension aligns with standardized theatrical rental inventories and mass-market vintage reproduction lines. Costume departments at major streaming productions specify Medium as their baseline procurement target to maximize interchangeability across talent pools.
- Small:Historical accuracy for period pieces often requires smaller dimensions than contemporary headwear. Specialized milliners in the United Kingdom maintain dedicated Small-size blocking equipment for archival reproduction contracts.
- Large:Contemporary sizing adjustments accommodate modern head proportions in costume applications. These specifications are expanding fastest among North American theatrical suppliers.
- Extra Large:Custom blocking and pattern adaptation are required. This segment serves niche theatrical casting and bespoke private commissions.
Medium carries the volume base; Large is climbing the fastest as modern sizing standards permeate period costuming.
Material:
Natural fiber traditions face displacement from compliance-driven synthetic alternatives.
- Cotton:Breathable woven or felted cotton serves warm-weather theatrical productions and casual vintage fashion. REACH-compliant dye processes are compressing supplier margins for European market access.
- Polyester:Synthetic felt and structured fabrics offer dimensional stability and lower cost. Asian manufacturing hubs dominate supply, though EU Green Deal sustainability mandates are forcing reformulation of virgin polyester content.
- Nylon:Lightweight, quick-drying properties suit functional and sports-oriented applications. This material is gaining share in outdoor reenactment markets.
- Blended Fabrics:Cotton-polyester and wool-synthetic combinations balance hand-feel with performance. Italian textile mills are developing proprietary blends to satisfy both archival aesthetic and OEKO-TEX certification requirements.
Polyester underpins volume manufacturing; Blended Fabrics is expanding most quickly as compliance complexity rises.
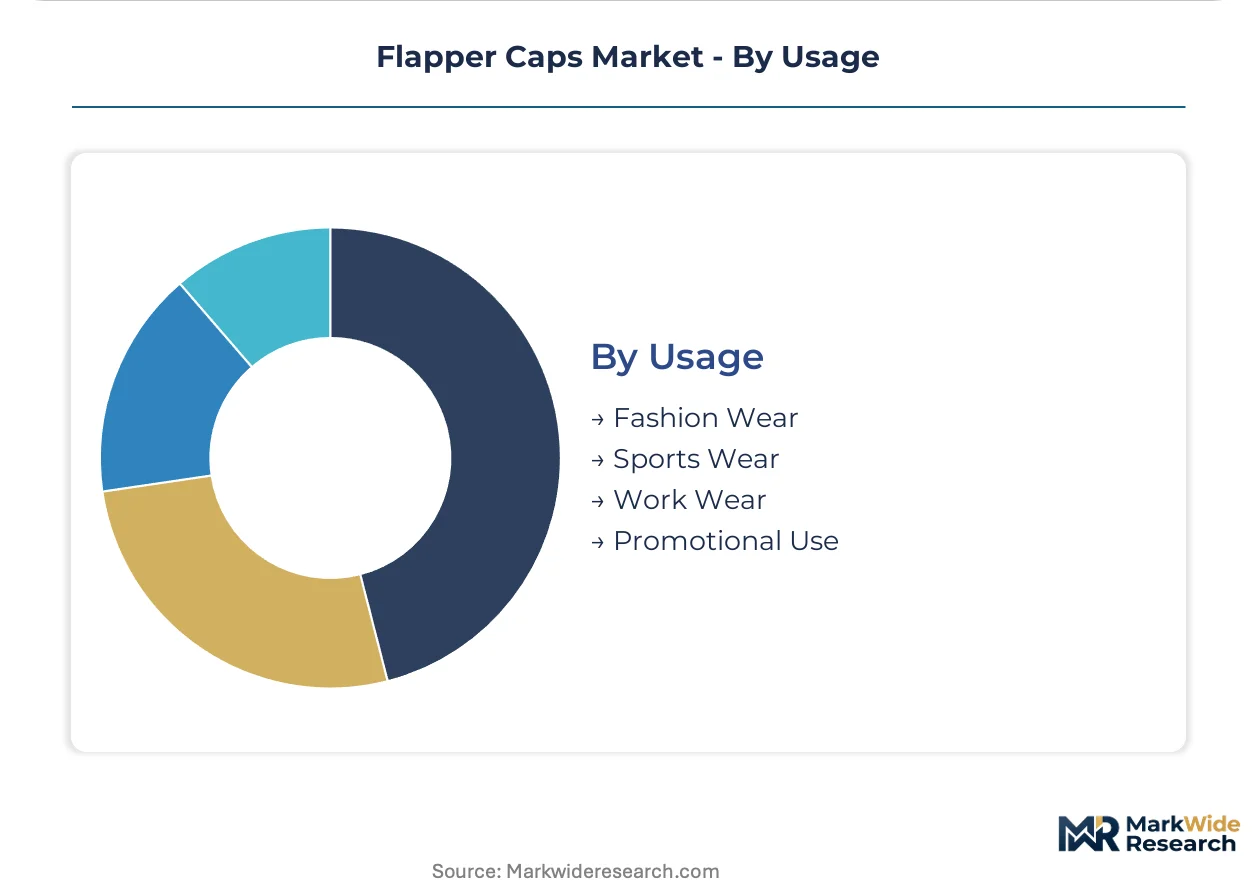
Usage:
Application context determines construction standards, pricing tolerance, and regulatory exposure.
- Fashion Wear:Ready-to-wear and vintage-inspired styling drives this mature segment. United Kingdom and French retailers are deepening consignment networks for authenticated period pieces alongside reproduction lines.
- Promotional Use:Branded flapper-style headwear for themed events and marketing campaigns represents an emerging volume channel. Short production runs and simplified construction prioritize cost efficiency over archival accuracy.
- Sports Wear:Performance-oriented adaptations with moisture-wicking linings and secure fastenings serve niche athletic costuming markets.
- Work Wear:Protective modifications for historical reenactment professions and themed hospitality roles apply reinforced construction standards.
Fashion Wear absorbs the dominant revenue share; Promotional Use is gaining share fastest as experiential marketing budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. United States theatrical buyers absorb premium pricing for archival accuracy, while Asian manufacturing hubs compete on machine-embroidered substitutes. European heritage markets occupy the middle ground, trading cost tolerance for regulatory compliance.
United States
Streaming production budgets and experiential marketing campaigns drive procurement volume. California Proposition 65 chemical disclosure rules force reformulation of vintage-accurate dye recipes. New York and Los Angeles host the deepest costume rental networks, with wardrobe departments prioritizing rapid turnaround over ownership.
United Kingdom
Artisan millinery clusters concentrate demand for hand-finished decorative headwear. REACH compliance timelines extend supplier qualification periods for European market access. London anchors British manufacturing heritage through in-house blocking capabilities, while Edinburgh and Manchester deepen specialized consignment networks for authenticated period pieces.
Italy
Florence and Milan absorb the highest concentration of streaming production budgets for period-authentic costuming. EU Green Deal textile sustainability mandates accelerate reformulation of synthetic embellishments. Venetian textile mills develop proprietary blended fabrics to satisfy both archival aesthetic and OEKO-TEX certification requirements.
France
Luxury consumers in Paris drive expansion of bespoke millinery experiences with premium pricing tolerance. ECHA enforcement of nickel release restrictions in metal components forces substitution of vintage-accurate findings. Lyon and Marseille host emerging rental platforms capturing theatrical demand previously served by outright purchase.
Germany
Theatrical costume houses prioritize durability and interchangeability for touring productions. Extended producer responsibility frameworks for fashion goods compress margins for small-batch artisan suppliers. Berlin and Munich anchor the deepest networks for authenticated vintage consignment alongside reproduction manufacturing.
Flapper Caps Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Heritage milliners with hand-blocking expertise command premium positioning in decorative and custom segments, while standardized theatrical rental suppliers compete on volume throughput and rapid turnaround. The market structures around three archetypes: archive-driven reproduction specialists, contemporary bridge designers, and theatrical rental consolidators. Competitive moves center on digital pattern archive development and sustainable material certification acquisition.
Within the heritage reproduction tier, Goorin Bros. and Christys' London occupy positions anchored by century-old manufacturing traditions. Eugenia Kim exemplifies the contemporary bridge archetype, sitting between costume authenticity and ready-to-wear accessibility. These three companies represent the span of competitive positioning from archival precision to fashion-forward reinterpretation.
| Leading Market Players |
|---|
| Goorin Bros. |
| Louise Green Millinery Co. |
| Eugenia Kim |
| Kokin |
| Helen Kaminski |
| Betmar New York |
| Christys' London |
| Arturo Rios |
| Weatherchem Corporation |
| Others |
Value Network & Pricing Analysis
Florence and Milan millinery clusters concentrate hand-finishing capacity for decorative caps, translating artisan scarcity into premium pricing power for bespoke orders. REACH compliance costs and felt input volatility compress margins at the standard tier while amplifying spreads for certified decorative pieces.
Pricing Analysis
Long-term offtake contracts dominate theatrical rental procurement, locking volume commitments from London and New York costume houses at fixed rates for seasonal production cycles. Three-tier pricing structure across premium, standard, and economy levels separates archival-accurate custom caps from machine-pressed theatrical inventory and promotional event pieces. Pricing pressure stems from automated beadwork substitutes out of Asian manufacturing hubs undercutting hand-embroidery premiums. Theatrical rental houses exhibit highest price sensitivity due to budget constraints across touring productions, while streaming production wardrobes absorb premium positioning for period authenticity.
Supply Chain Analysis
Tariff exposure between Italy and non-EU raw wool suppliers dominates supply chain risk planning for felt-dependent milliners. Production concentrates in Italy, the United Kingdom, and France, drawing from Australian merino wool, Madagascar raffia, and Czech glass bead inputs. Single-source vulnerability sits with aged master milliners whose hand-blocking expertise outpaces apprenticeship pipeline replenishment. Distribution runs through theatrical rental consolidators, authenticated vintage consignment platforms, and direct bespoke appointment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flapper caps function as a service-attach opportunity where restoration, authentication, and bespoke fitting experiences expand faster than physical unit sales. Rental and resale platform economics reward provenance verification and archival research capabilities over pure manufacturing scale.
For Market Incumbents: Pre-empt machine-embroidered substitute erosion by securing exclusive digital pattern archives from museum partnerships and accelerating OEKO-TEX certification coverage across Italian supplier networks. Backward integration into proprietary wool-scouring operations in Australia hedges felt input volatility threatening standard tier margins. For New Entrants and Emerging Players: Build out experiential fitting studios in Los Angeles and Paris where luxury consumers pay premiums for in-person archival research and blocking appointments. Promotional use segments offer lowest competitive density for automated production capabilities targeting marketing campaign volume. For Investors and Strategic Acquirers: Long-term, this sits as a heritage IP consolidation play because archive authenticity and hand-blocking skill scarcity compound defensive moats for reproduction specialists. Watch theatrical rental platform consolidation velocity as the inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Pattern Archive Development | Museum partnership licensing secures exclusive reproduction rights for streaming production authenticity demands. |
| Certification Investment Program | REACH and OEKO-TEX acquisition unlocks European theatrical procurement and reduces supplier qualification friction. |
| Experiential Studio Expansion | Bespoke fitting appointments in Paris and Los Angeles capture luxury consumer willingness to pay service premiums. |
| Authenticated Consignment Platform | Vintage verification capabilities address rental market shift from ownership to access across United Kingdom networks. |
| Apprenticeship Pipeline Development | Hand-blocking skill transfer programs counter master milliner aging-out risk threatening decorative tier supply. |
Research Methodology
Operator-level perspectives from theatrical costume directors, millinery workshop owners, vintage fashion retailers, and streaming production wardrobe supervisors anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against customs records, theatrical production databases, and heritage textile certification registries. Bottom-up demand modeling across theatrical, fashion, and promotional use segments triangulated against top-down market sizing from millinery cluster output estimates.
Scenario-bracketing framed projections across conservative, baseline, and accelerated adoption paths for bespoke experience channels. Segmentation dimensions modeled include product type, material composition, usage context, and regional regulatory cluster. CAGRs derived from weighted average growth across theatrical procurement expansion, vintage fashion retail velocity, and experiential service attach rates. Felt and straw input cost trajectories, REACH compliance timeline compression, and hand-blocking labor availability shaped industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by automated manufacturing entrants or rapid streaming production budget contraction would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Plastic Caps and Closure Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Cuvette Caps Market
Caps and Closures
PVC-Free Cap Liners Market
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Italy Plastic Caps and Closures Market
Caps and Closures
Tube Closures Market
Caps and Closures
Case Closures and Sealers Market
Caps and Closures
Buttress Closures Market
Caps and Closures
Shrink Bands Market
Caps and Closures
Latin America Metal Caps and Closures Market
Caps and Closures
Plunger Stopper Market
Caps and Closures
PCR Closures Market
Caps and Closures
Sport Caps and Closures Market
Caps and Closures
Twist Caps Market
Caps and Closures
United Kingdom Plastic Caps and Closures Market