
 Pressure Sensitive Wads Market | 2026-2036
Pressure Sensitive Wads Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Sensitive Wads Market Analytics
Pharmaceutical packaging is recalibrating demand composition as tamper-evident and contamination-resistant sealing becomes non-negotiable for sterile drug delivery. Henkel AG & Co. KGaA leverages its adhesive chemistry portfolio to dominate high-barrier pharmaceutical wad formulations. H.B. Fuller Company anchors North American supply through specialized hot-melt coating systems for induction-sealable wads. 3M Company differentiates via microreplication technology that controls release force precision across variable substrate surfaces.
Pressure sensitive wads are laminated disc structures combining a facing layer, functional adhesive coating, and release liner, manufactured through slot-die or reverse gravure coating processes to achieve uniform 25–75 micrometer adhesive deposition for hermetic sealing upon moderate finger pressure. Foam wads lead volume in beverage and cosmetic applications where compressibility compensates for container lip irregularities, while paper wads command premium positioning in pharmaceutical segments demanding fiber-based sustainability credentials and compatible sterilization pathways. Plastic wads, particularly polyethylene constructions, represent the fastest-growing material trajectory as mono-material recyclability targets reshape converter specifications across European and North American packaging mandates.
FDA 21 CFR Part 211, EMA GMP Annex 1, and BIS IS 15495 collectively govern wad migration limits, sterility assurance, and food-contact compliance, creating segmented certification burdens that filter regional supplier participation. ISO 15378 pharmaceutical packaging standards and EU MDR traceability requirements further elevate documentation and batch-release obligations for healthcare-facing wad producers. Stakeholders must monitor evolving extended producer responsibility frameworks and adhesive substance restrictions under REACH and state-level chemical disclosure laws to preempt reformulation cycles and secure market access continuity.
Market Dynamics
Pharmaceutical serialization mandates and mono-material recyclability targets are compressing formulation cycles while fragmenting supplier qualification pathways across FDA, EMA, and BIS jurisdictions.
Growth Catalysts
- Tamper-evident mandates:FDA 21 CFR Part 211 and EMA GMP Annex 1 sterility requirements are expanding induction-sealable wad deployment in parenteral drug packaging.
- India:Domestic pharmaceutical production scaling under PLI scheme incentives is localizing wad supply chains and accelerating BIS IS 15495 certification adoption.
- Polyethylene mono-material constructions:Converter specifications across European packaging mandates are displacing multi-layer laminates with recyclable single-substrate alternatives.
Market Restraints
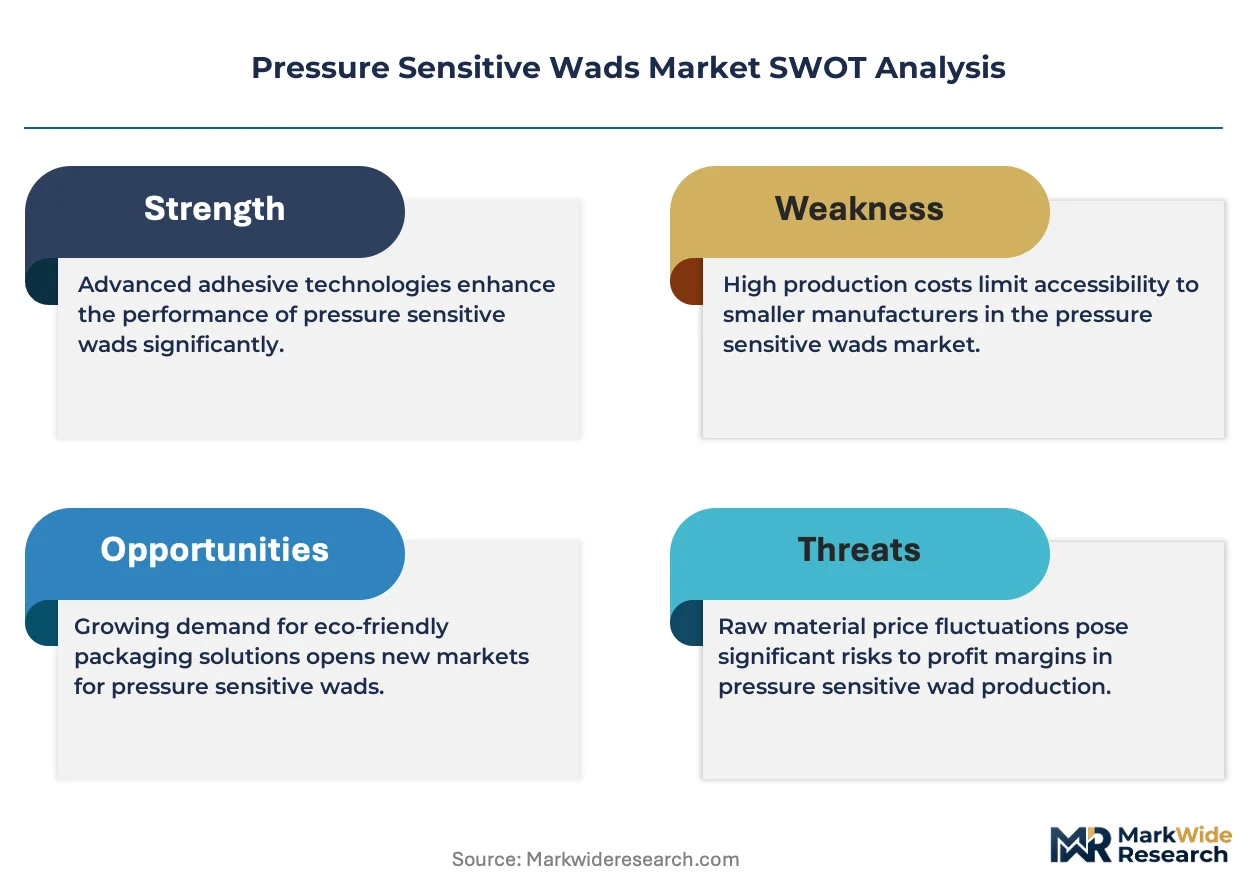
- Adhesive raw material volatility:Acrylic and rubber-based adhesive feedstocks face petrochemical price swings that compress converter margins.
- Specialized coating equipment concentration:Slot-die and reverse gravure coating systems for 25–75 micrometer precision deposition concentrate among limited European and Japanese machinery suppliers.
- REACH substance restrictions:ECHA scrutiny of siloxanes and residual monomers in pressure-sensitive adhesives is forcing preemptive reformulation cycles ahead of compliance deadlines.
Strategic Opportunities
- Brazil:ANVISA pharmaceutical packaging localization requirements create white space for induction-sealable wad producers serving sterile generic drug exports.
- Digital watermarking integration:Convergence of microreplication release-force control with serialized traceability layers enables unit-level authentication for high-value biologics.
- EU Green Deal packaging waste targets:Extended producer responsibility frameworks are mandating fiber-to-fiber and plastic-to-plastic recyclability that rewards mono-material wad designs.
Industry Challenges
- ISO 15378 auditor scarcity:Pharmaceutical packaging certification backlog delays batch-release documentation for healthcare-facing wad producers entering regulated supply chains.
- Legacy sterilization compatibility:Gamma and ethylene oxide sterilization pathways for fiber-based wads require adhesive chemistry revalidation that extends qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Sensitive Wads Market |
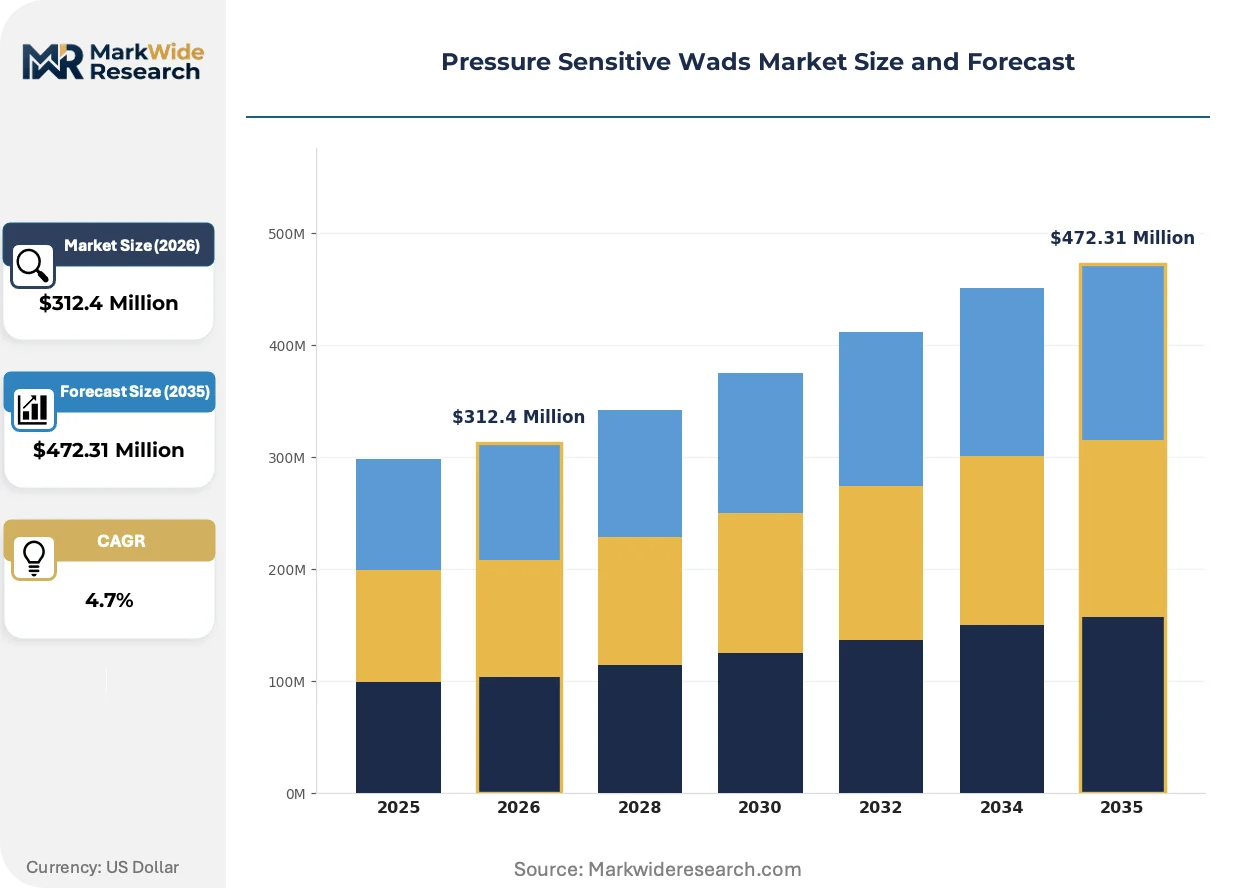
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Wads, Paper Wads, Plastic Wads, Metal Wads Application: Food Packaging, Pharmaceutical Packaging, Beverage Packaging, Cosmetic Packaging End User: Food Industry, Healthcare, Cosmetics, Beverages Material: Polyethylene, Polypropylene, PVC, Paper |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, 3M Company, Tesa SE, Arkema Group, Avery Dennison Corporation, Nitto Denko Corporation, Lohmann GmbH & Co. KG, Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Sensitive Wads Market Evolving Landscape
Adhesive microreplication and digital printing convergence are redefining functional performance boundaries while regulatory substance scrutiny accelerates material substitution cycles.
Microreplication technology is electrifying release-force precision across variable substrate surfaces. Pharmaceutical contract packagers are adopting these controlled-peel systems for biologics with narrow sealing windows. The technology is compressing defect rates in high-speed capping lines while enabling thinner adhesive deposits that reduce material intensity.
REACH adhesive substance restrictions are tightening migration limit enforcement for siloxanes and residual monomers in food-contact and pharmaceutical applications. ECHA evaluation processes are forcing converters to maintain parallel formulation portfolios for EU versus non-EU supply. Healthcare-facing wad producers are responding with accelerated substance hazard assessments and supply chain chemical disclosure systems.
Buyer concentration among top-tier pharmaceutical contract manufacturers is compressing supplier qualification cycles and unbundling technical service from material supply. Direct converter-to-packager relationships are displacing traditional distribution layers for sterile drug packaging specifications. This pattern is most visible in Germany and Switzerland where CDMO consolidation has reduced qualified supplier lists to single-digit counts per therapeutic category.
Pressure Sensitive Wads Market Segmentation
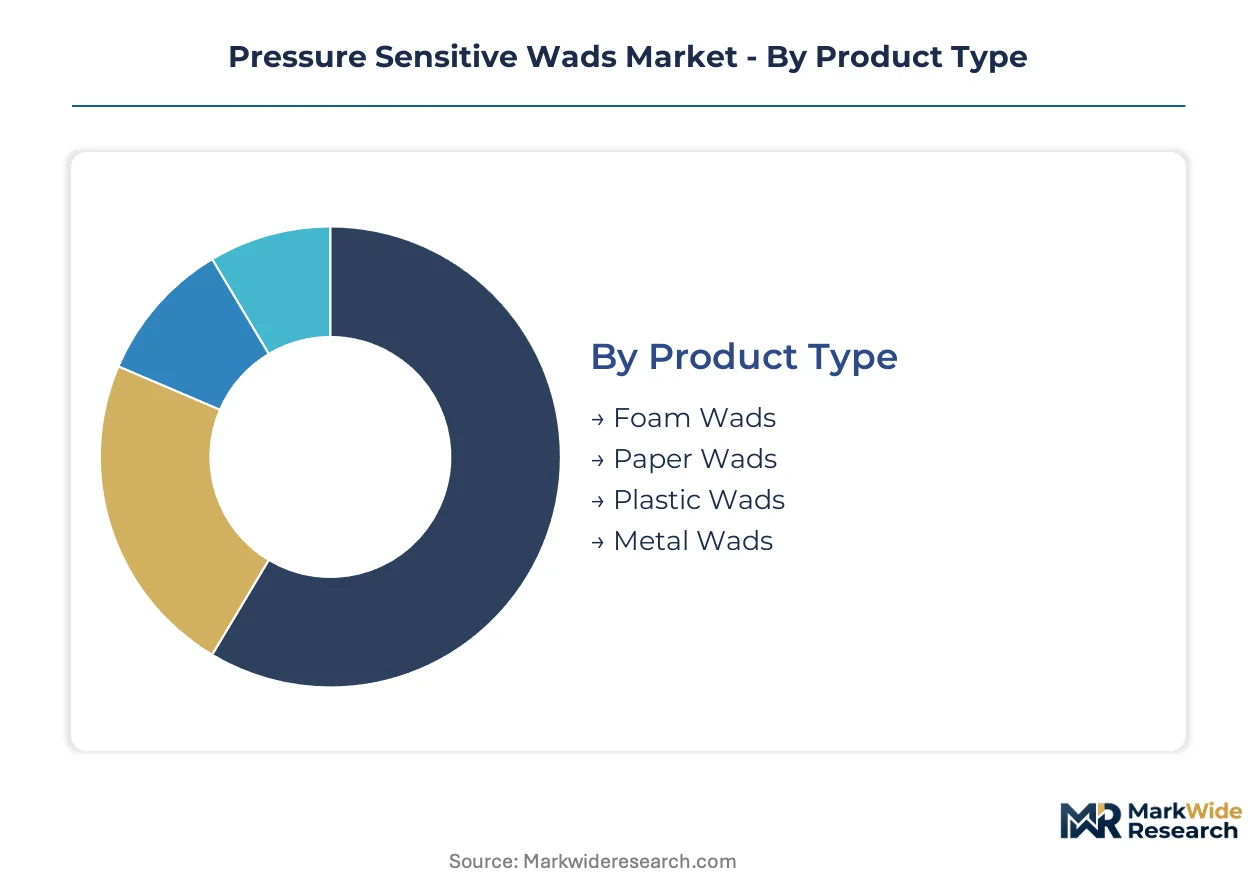
Pressure sensitive wads serve heterogeneous sealing requirements across pharmaceutical sterility mandates, beverage compressibility needs, and cosmetic sustainability preferences. Segmentation reveals how material chemistry and application specifications fragment supplier capabilities and margin structures.
Product Type:
Foam wads dominate volume through compressibility advantages, while paper wads command premium positioning through sterilization compatibility and fiber-based sustainability credentials.
- Foam Wads:Laminated cellular structures combining polyethylene or polyurethane cores with pressure-sensitive adhesive coatings. Beverage and cosmetic applications in India concentrate demand where container lip irregularities require compensatory sealing. BIS IS 15495 certification pressures are localizing supply chains for domestic pharmaceutical producers.
- Paper Wads:Fiber-based constructions with functional coatings enabling gamma and ethylene oxide sterilization pathways. Pharmaceutical packaging in Germany and Switzerland drives specification intensity as CDMO consolidation reduces qualified supplier lists per therapeutic category. FDA 21 CFR Part 211 migration limits elevate documentation burdens.
- Plastic Wads:Mono-material polyethylene constructions displacing multi-layer laminates under EU Green Deal packaging waste targets. Converter specifications across European mandates reward recyclability credentials.
- Metal Wads:Aluminum-faced laminates for high-barrier pharmaceutical applications requiring oxygen and moisture ingress protection. Specialized induction-sealing compatibility limits supplier participation.
Mature deployment sits with foam wads. Newer deployment is concentrated in plastic wads as mono-material recyclability targets reshape converter procurement.
Application:
Pharmaceutical specifications concentrate margin and certification complexity, while beverage applications drive volume scale through standardized compressibility requirements.
- Pharmaceutical Packaging:Induction-sealable wads for parenteral drug delivery under EMA GMP Annex 1 sterility requirements. Serialization mandates and traceability layers under EU MDR elevate batch-release documentation. Henkel AG and H.B. Fuller anchor supply through specialized adhesive formulations.
- Beverage Packaging:High-speed capping line compatibility with foam-based compressibility for carbonated and still drinks. Standardized specifications enable volume manufacturing with thinner adhesive deposits reducing material intensity.
- Food Packaging:Migration limit compliance under FDA and EFSA frameworks for direct-contact applications. Extended producer responsibility frameworks are mandating fiber-to-fiber and plastic-to-plastic recyclability.
- Cosmetic Packaging:Premium positioning through aesthetic facing layers and controlled release-force precision. Microreplication technology from 3M differentiates performance across variable substrate surfaces.
Pharmaceutical packaging captures the steepest expansion trajectory as tamper-evident mandates tighten under FDA and EMA jurisdictions. Beverage packaging maintains volume leadership through compressibility-driven specifications.
End User:
Healthcare procurement concentrates technical service unbundling and direct converter relationships, while food industry buyers prioritize cost efficiency at scale.
- Healthcare:Sterile drug manufacturers and contract packagers demanding ISO 15378 certification and auditor-scarce qualification pathways. Direct relationships displace distribution layers as CDMO consolidation accelerates.
- Food Industry:Volume-scale procurement with standardized migration limit compliance. REACH substance restrictions on siloxanes and residual monomers force parallel formulation portfolios.
- Cosmetics:Premium brand positioning through aesthetic and functional differentiation. Digital watermarking integration enables unit-level authentication for high-value product lines.
- Beverages:High-throughput capping operations requiring defect-rate compression and release-force consistency across variable production speeds.
Healthcare procurement is reshaping supplier engagement models. Beverage procurement maintains traditional distribution structures.
Material:
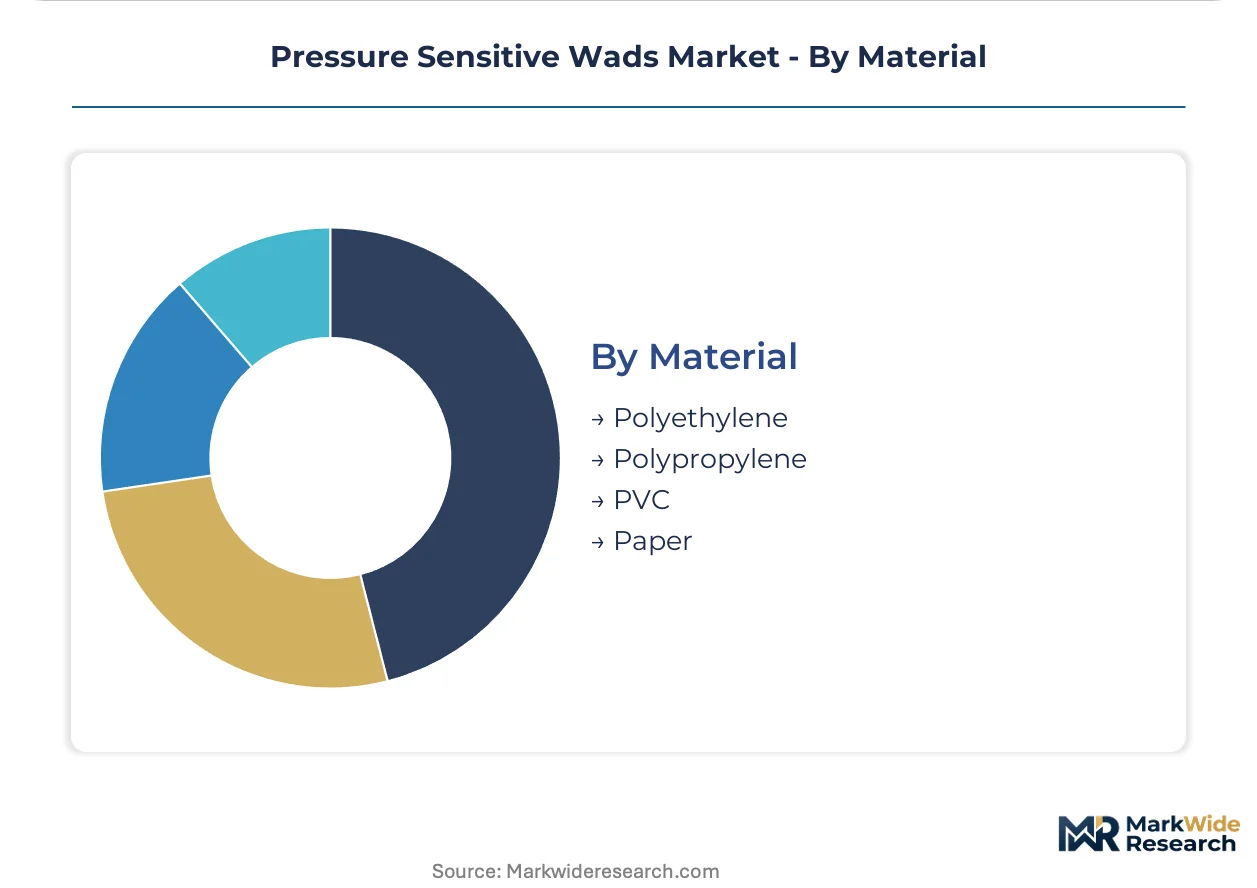
Polyethylene climbs fastest on mono-material recyclability mandates, while paper retains pharmaceutical preference through sterilization pathway compatibility.
- Polyethylene:Mono-material constructions satisfying EU Green Deal extended producer responsibility targets. Converter specifications across European and North American mandates displace multi-layer alternatives.
- Paper:Fiber-based sustainability credentials with gamma and ethylene oxide sterilization compatibility. Adhesive chemistry revalidation extends qualification timelines for healthcare-facing producers.
- Polypropylene:Chemical resistance and thermal stability for aggressive fill products. Specialized coating equipment concentration among limited European and Japanese machinery suppliers constrains capacity expansion.
- PVC:Declining deployment under REACH substance restrictions and state-level chemical disclosure laws. Preemptive reformulation cycles ahead of compliance deadlines accelerate material substitution.
PVC maintains legacy installed base. Polyethylene captures new specification momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Gujarat and Maharashtra concentrate Indian pharmaceutical packaging capacity under Production Linked Incentive scheme benefits. Tax-advantaged manufacturing enclaves in Hyderabad and Visakhapatnam anchor wad converter expansion for domestic sterile drug supply.
United States
Contract development and manufacturing organization consolidation in New Jersey and Massachusetts drives induction-sealable wad qualification intensity. FDA 21 CFR Part 211 sterility requirements compress supplier approval timelines for parenteral drug packaging. Boston-Cambridge biotech corridor demands microreplication-enabled release-force precision for high-value biologics.
Germany
CDMO concentration in Baden-Württemberg and Bavaria reduces qualified wad supplier lists to single-digit counts per therapeutic category. EMA GMP Annex 1 migration limits elevate batch-release documentation burdens for healthcare-facing producers. Frankfurt-Rhine-Main logistics hub channels wad supply into centralized European pharmaceutical distribution.
India
Domestic pharmaceutical production scaling under PLI scheme incentives localizes wad supply chains away from import dependency. BIS IS 15495 certification pressures accelerate converter qualification for sterile generic drug exports. Ahmedabad-Vadodara industrial corridor hosts expanding foam and paper wad manufacturing for beverage and pharmaceutical segments.
Switzerland
Swissmedic pharmaceutical packaging standards enforce stringent traceability layers for high-barrier wad applications. Basel-Lucerne-Zurich pharmaceutical cluster demands ISO 15378-certified suppliers with direct converter-to-packager relationships. Precision coating equipment from limited Japanese and European machinery suppliers concentrates qualification pathways.
Brazil
ANVISA pharmaceutical packaging localization requirements create white space for induction-sealable wad producers serving sterile generic drug exports. São Paulo state chemical industry base supplies acrylic and rubber-based adhesive feedstocks for domestic converter operations. Campinas pharmaceutical manufacturing hub drives demand for tamper-evident sealing compliance.
Pressure Sensitive Wads Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with adhesive chemistry leaders commanding pharmaceutical margins and regional fabricators capturing beverage volume. Market structure tilts toward consolidated supply at the premium tier where certification burdens filter participation, while standard-grade applications sustain fragmented regional competition. Three archetypes dominate: multinational adhesive formulators with pharmaceutical certification depth, regional converters with localized BIS and ANVISA compliance capabilities, and specialized coating equipment integrators serving precision deposition requirements. Competitive dynamics center on M&A-driven CDMO vertical integration and capacity expansion in Indian SEZs.
Among multinational adhesive formulators, Henkel AG & Co. KGaA and H.B. Fuller Company exemplify the certification-intensive tier serving sterile drug packaging specifications. These Germany-based and US-based entities occupy positions where EMA and FDA compliance documentation creates defensive moats. 3M Company represents the technology-differentiated archetype through microreplication-enabled release-force control. Together these three anchors illustrate how pharmaceutical-facing supply concentrates around adhesive chemistry portfolios and precision coating capabilities rather than geographic coverage alone.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| 3M Company |
| Tesa SE |
| Arkema Group |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| Lohmann GmbH & Co. KG |
| Dow Chemical Company |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap converters in Gujarat and Maharashtra anchor Indian supply for foam and paper wad production, translating localized BIS certification depth into pricing discipline that resists commoditization pressure from multinational adhesive formulators.
Pricing Analysis
Premium positioning attaches to short lead-time pharmaceutical specifications under FDA 21 CFR Part 211 and EMA GMP Annex 1 compliance windows, while spot inventory of standard-grade beverage wads trades at compressed margins. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15378-certified pharmaceutical grades from BIS IS 15495 domestic tiers and uncertified commodity foam constructions. Pricing pressure stems from acrylic and rubber-based adhesive feedstock volatility that squeezes converter margins without full pass-through elasticity. Healthcare procurement exhibits lowest price sensitivity due to sterility assurance requirements, while beverage bottlers drive hardest volume-negotiation leverage.
Supply Chain Analysis
Direct-to-CDMO channels handle sterile pharmaceutical demand in Germany, Switzerland, and the United States, bypassing traditional distribution layers as buyer consolidation accelerates. Manufacturing concentrates in India for foam and paper wad exports, Germany for precision-coated pharmaceutical grades, and Japan for specialized slot-die coating equipment. Raw material dependencies rest on petrochemical-derived acrylic adhesives, specialty release liners from European suppliers, and precision coating machinery from limited Japanese and European machinery builders. Single-source vulnerability concentrates in specialized coating equipment for 25–75 micrometer adhesive deposition precision. Distribution runs through regional converter networks for beverage and cosmetic segments, with direct technical service relationships dominating healthcare procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EMA GMP Annex 1 sterility requirements erect barrier-to-entry moats that reward certified incumbents and filter speculative entrants from sterile drug packaging supply chains.
For Market Incumbents: Lock in auditor-scarce ISO 15378 certification pathways through captive training investments and backward integration into precision coating equipment maintenance capabilities. Defend margin position by accelerating microreplication technology deployment for biologics with narrow sealing windows, neutralizing substitute pressure from induction-sealing alternative technologies. Prioritize capacity expansion in Indian Special Economic Zones under PLI scheme incentives to capture domestic pharmaceutical production localization. For New Entrants and Emerging Players: ANVISA pharmaceutical packaging localization requirements in Brazil open a window for induction-sealable wad producers serving sterile generic drug exports to Latin American markets. Target polyethylene mono-material constructions for European converter specifications under EU Green Deal extended producer responsibility frameworks, exploiting incumbents' legacy multi-layer laminate stranded assets. Pursue direct technical service relationships with mid-tier pharmaceutical contract packagers as the most penetrable buyer segment, unbundling material supply from application engineering support. For Investors and Strategic Acquirers: Distressed-cycle entries favor Indian converters with BIS IS 15495 certification depth and established relationships with domestic pharmaceutical producers scaling under PLI scheme incentives. Long-term viability centers on adhesive chemistry portfolios capable of preemptive reformulation ahead of REACH substance restrictions on siloxanes and residual monomers. Monitor ECHA evaluation timelines for pressure-sensitive adhesive substance restrictions as the critical inflection signal for forced consolidation among non-compliant regional fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Chemistry | Henkel AG and H.B. Fuller anchor pharmaceutical margins through captive formulation control. |
| Capacity Expansion in Indian SEZs | PLI scheme incentives localize supply chains for sterile generic drug exports under BIS certification. |
| Microreplication Technology Deployment | 3M Company differentiates release-force precision for biologics with narrow sealing windows. |
| Mono-Material Recyclability Transition | Polyethylene constructions satisfy EU Green Deal extended producer responsibility mandates. |
| Direct Converter-to-Packager Relationships | CDMO consolidation in Germany and Switzerland displaces traditional distribution layers. |
Research Methodology
Independent corroboration across regulatory filing databases, customs trade records, and pharmaceutical packaging certification registries underwrites the qualitative findings in this analysis. Primary interviews with adhesive formulation chemists, pharmaceutical packaging engineers, CDMO procurement directors, and precision coating equipment specialists combined with secondary validation from FDA 21 CFR guidance documents, EMA GMP Annex 1 revisions, BIS IS 15495 standards, and ISO 15378 pharmaceutical packaging specifications. Bottom-up triangulation across converter capacity assessments and top-down demand modeling from pharmaceutical production statistics anchored the market sizing framework.
Comparable-period anchoring tied the projection horizon to historical pharmaceutical packaging expenditure patterns and induction-sealing equipment deployment cycles across the analysis window. Segmentation modeling incorporated product type, application, end user, and material chemistry dimensions alongside regional regulatory cluster differentiation. CAGRs derived from trend extrapolation of pharmaceutical serialization mandate adoption curves and mono-material recyclability specification velocity. Forecast inputs included PLI scheme incentive disbursement trajectories and ECHA substance restriction evaluation timelines.
The model assumes a particular technology adoption path for microreplication-enabled release-force control; alternative pathways for digital watermarking integration with serialized traceability layers would alter the outlook for high-value biologics authentication. Forecasts reflect assumptions regarding REACH adhesive substance restriction enforcement intensity and Indian domestic pharmaceutical production scaling under PLI scheme continuation. Practitioners should monitor ECHA evaluation timelines, BIS certification backlog resolution rates, and CDMO vertical integration announcements for early signals of supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Aerosol Valves Market
Caps and Closures
Magnetic Closure Box Market
Caps and Closures
North America Metal Caps and Closures Market
Caps and Closures
Drop Sealers Market
Caps and Closures
Smooth Hinge Caps and Closure Market
Caps and Closures
Caps and Closures Market
Caps and Closures
Latin America Metal Caps and Closures Market
Caps and Closures
Dispensing Caps Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Non-Aerosol Overcaps Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
France Plastic Caps and Closures Market
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
Humidity Indicator Plugs Market
Caps and Closures
Twist-Off Metal Caps Market
Caps and Closures
Screw Caps and Closure Market