
 Gamma Seal Lids Market | 2026-2036
Gamma Seal Lids Market Size, Share, and Industry Trends Forecast 2026-2036
Gamma Seal Lids Market Analytics
Food storage is broadening as the dominant application vertical for gamma seal lids, displacing slower-growing industrial chemical segments. Gamma2 leverages its brand recognition and proprietary threading designs to sustain premium positioning across homesteading and preparedness channels. Pleasant Hill Grain anchors the specialty retail segment with curated distribution focused on grain preservation and long-term food security customers.
Gamma seal lids are threaded, gasketed closures engineered from high-density polyethylene or polypropylene, featuring a two-piece rotating ring design that creates an airtight seal on standard pails for dry goods, chemicals, and bulk materials. Heavy-duty gamma lids command margin pools in commercial settings where repeated opening cycles demand reinforced rib structures and UV-stabilized resins. Child-resistant gamma lids represent the fastest-growing product type as pharmaceutical and cannabis-adjacent storage regulations tighten across multiple state jurisdictions.
FDA food contact notifications govern polymer selection for food-grade gamma seal lids, while EPA chemical containment standards shape industrial-use specifications for chemical storage applications. The Consumer Product Safety Commission oversees child-resistant closure testing protocols that manufacturers must satisfy before commercial distribution. Stakeholders should monitor evolving state-level cannabis packaging mandates and biodegradable plastic performance standards to anticipate material substitution timelines and certification requirements.
Market Dynamics
Food-grade polymer certification requirements and state-level cannabis packaging mandates are restructuring material sourcing priorities and child-resistant closure R&D budgets across gamma seal lid manufacturers.
Growth Catalysts
- FDA food contact notifications:BPA-free polypropylene formulations gain preference among food manufacturers seeking compliant bulk ingredient storage. Material suppliers accelerate resin certification timelines to capture replacement demand.
- Homesteading supply channel expansion:Long-term food security preparedness drives repeat purchase cycles for airtight pail closures. Specialty retailers curate multi-lid bundles for grain preservation customers.
- UV-stabilized HDPE formulations:Commercial food processors adopt heavy-duty rotating ring designs for outdoor storage applications. UV resistance extends replacement intervals in high-exposure environments.
Market Restraints
- Petrochemical feedstock volatility:High-density polyethylene and polypropylene resin prices fluctuate with crude oil derivatives. Margin compression pressures mid-tier manufacturers without long-term supply contracts.
- Injection molding equipment concentration:Precision thread-forming machinery suppliers cluster in Germany and Japan. New market entrants face 18-24 month equipment lead times.
- Child-resistant testing protocols:Consumer Product Safety Commission certification requirements extend product development cycles. Specialized torque testing adds $15,000-$40,000 per SKU validation.
Strategic Opportunities
- Biodegradable polymer performance standards:PLA and PHA blends meeting ASTM D6400 compostability criteria open municipal procurement channels. Early movers secure pilot contracts with waste management districts.
- Pharmaceutical compliance storage:USP <661> plastic packaging standards create adjacent demand for gamma lids in compounding pharmacies. Child-resistant designs satisfy DEA controlled substance storage requirements.
- Direct-to-prepper e-commerce:Subscription box models bypass traditional homesteading retail markups. Bundled pail-and-lid kits command premium pricing through preparedness influencers.
Industry Challenges
- Multi-jurisdiction labeling compliance:California Prop 65 warnings, Oregon cannabis packaging rules, and FDA nutrition facts panels require SKU proliferation. Inventory complexity strains ERP systems.
- Gasket compound formulation expertise:Thermoplastic elastomer selection for chemical resistance versus food contact approval demands specialized polymer chemistry talent. Smaller manufacturers outsource compound development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gamma Seal Lids Market |
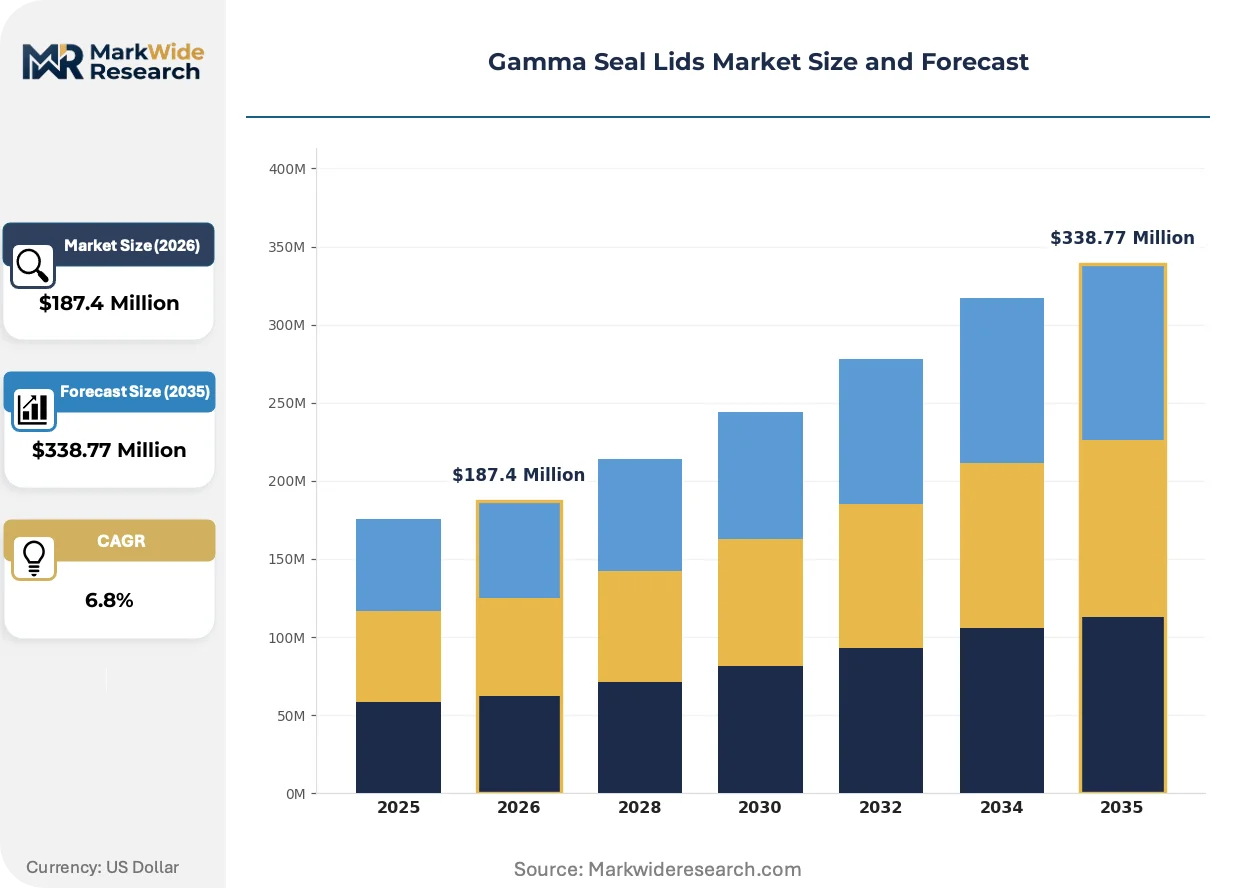
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Gamma Lids, Heavy-Duty Gamma Lids, Child-Resistant Gamma Lids, Custom Gamma Lids Material: Polyethylene, Polypropylene, PVC, Biodegradable Plastics Application: Food Storage, Chemical Storage, Industrial Use, Home Use End User: Household Consumers, Food Manufacturers, Chemical Producers, Retailers |
| Companies Covered | Gamma2, Pleasant Hill Grain, Lee Valley Tools, Menards, Walmart, ePackage Supply, Innopack, United Poly, Leaktite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gamma Seal Lids Market Evolving Landscape
Threaded closure engineering is converging with smart packaging sensors and sustainable material science, creating performance tiers that separate premium commercial-grade products from commodity homesteading supplies.
Embedded NFC-enabled tamper-evident rings are electrifying supply chain authentication for high-value chemical and pharmaceutical bulk storage. Logistics providers in the United States deploy smartphone-readable seals to verify chain-of-custody without secondary documentation. This technology compresses insurance premiums for hazardous material shippers while enabling real-time inventory tracking.
REACH SVHC candidate list expansions are forcing European manufacturers to reformulate color masterbatches and UV stabilizers. ECHA notifications for titanium dioxide and certain phthalate plasticizers trigger material substitution programs across food-contact gamma lid production. German chemical distributors now demand full material disclosure documentation before stocking imported closures.
Homesteading buyers increasingly specify complete pail-and-lid systems rather than component purchases. Preparedness retailers respond with pre-assembled, vacuum-sealed grain kits that eliminate separate lid procurement decisions. This bundling pattern concentrates volume with integrated suppliers capable of blow-molding pails and injection-molding gamma lids under one roof.
Gamma Seal Lids Market Segmentation
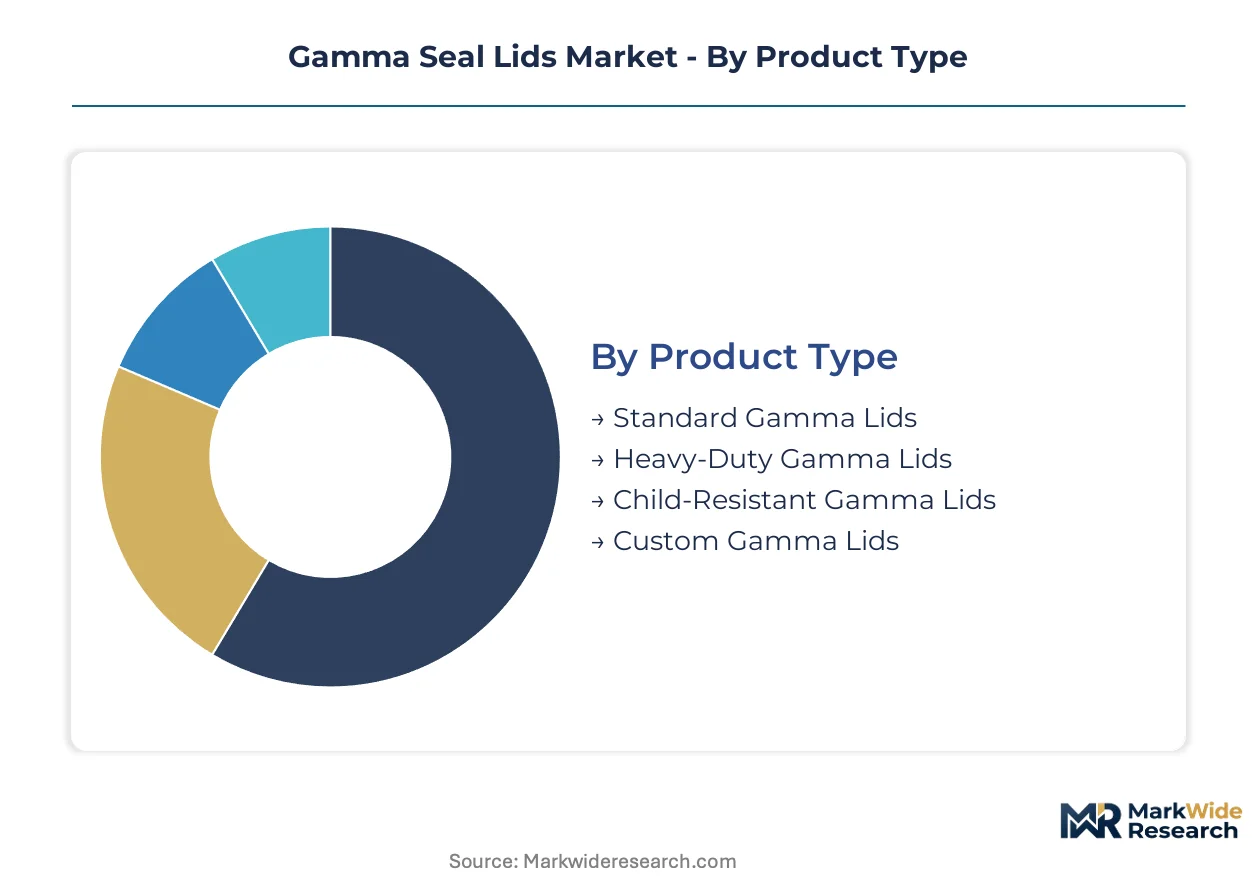
Gamma seal lid manufacturers configure production lines around four intersecting dimensions that determine resin selection, thread geometry, and certification requirements. Product managers balance standardization economies against the premium capture available from specialized formulations and regulatory-compliant designs.
Product Type:
Customization intensity varies sharply across this category, with commodity-standard designs anchoring volume while engineered variants command specialized margins.
- Heavy-Duty Gamma Lids:Reinforced rib structures and UV-stabilized HDPE formulations withstand repeated opening cycles in outdoor commercial environments. Food processors in the United States specify these for bulk ingredient pails exposed to loading dock conditions, where extended service intervals offset higher unit costs.
- Child-Resistant Gamma Lids:Specialized torque mechanisms and push-and-turn designs satisfy Consumer Product Safety Commission protocols for pharmaceutical and cannabis-adjacent storage. State-level packaging mandates in multiple jurisdictions are accelerating SKU development cycles for this configuration.
- Standard Gamma Lids:Baseline two-piece rotating ring designs in food-grade polypropylene serve homesteading and general dry goods storage applications.
- Custom Gamma Lids:Proprietary thread patterns and color-matched formulations for branded pail systems occupy niche specification channels.
Leading the category by volume: Standard Gamma Lids. Growing fastest: Child-Resistant Gamma Lids.
Material:
Cost tiering tracks resin certification complexity, with commodity thermoplastics separating from engineered grades demanding food contact notification documentation.
- Polyethylene:High-density formulations dominate heavy-duty applications where impact resistance and moisture barrier properties prove critical. HDPE's established recycling infrastructure supports circular economy procurement requirements from institutional buyers.
- Polypropylene:BPA-free homopolymer and copolymer grades have displaced legacy polycarbonate in food-contact gamma lids following FDA notification pathways. Material suppliers accelerate resin certification timelines to capture replacement demand from reformulating manufacturers.
- PVC:Limited to industrial chemical containment where specific solvent resistance requirements override sustainability concerns.
- Biodegradable Plastics:PLA and PHA blends meeting ASTM D6400 criteria open municipal procurement channels for composting program integration.
Polyethylene retains the largest installed base. Biodegradable Plastics are climbing the fastest as waste management districts pilot sustainable packaging mandates.
Application:
Application segmentation reflects divergent performance specifications, with food-grade certification separating premium commercial supply from general-purpose storage.
- Food Storage:FDA food contact material regulations govern polymer selection and migration testing for bulk ingredient handling. Airtight sealing performance preserves grain quality across extended distribution chains from agricultural processors to preparedness retailers.
- Chemical Storage:EPA containment standards and UN certification requirements shape industrial specifications for hazardous material handling. Gasket compound selection prioritizes chemical resistance over food contact approval.
- Industrial Use:General manufacturing and construction material handling applications where thread durability exceeds sealing precision requirements.
- Home Use:Homesteading and household organization applications driving repeat purchase cycles through specialty retail channels.
Food Storage generates the highest absolute volume. Chemical Storage is expanding most quickly on pharmaceutical and cannabis regulatory tailwinds.
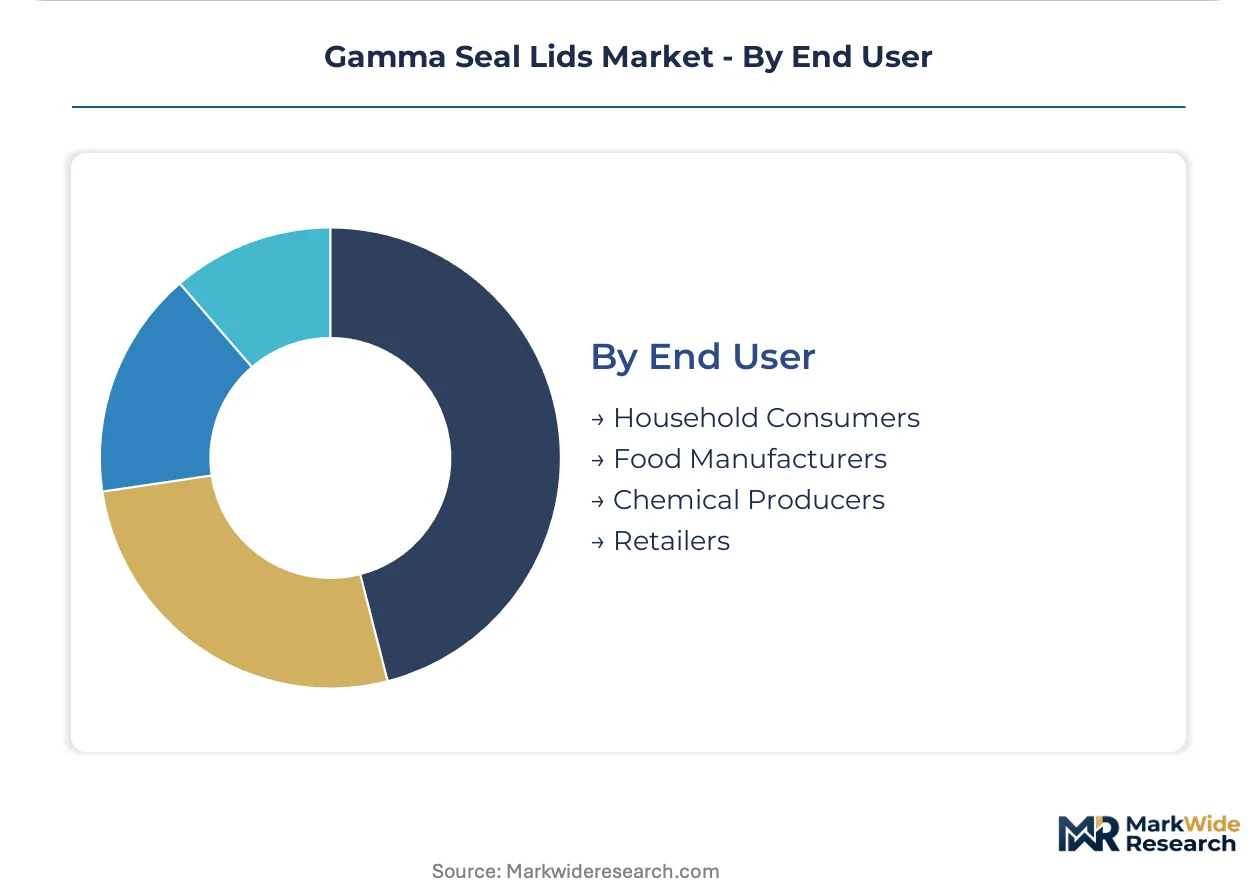
End User:
Customer type segmentation reveals procurement pattern divergence, with institutional buyers emphasizing certification documentation against consumer preference for bundled convenience.
- Food Manufacturers:Large-format processors specify heavy-duty gamma lids for bulk ingredient pails with documented lot traceability. Long-term supply contracts and resin certification requirements favor established suppliers with validated quality systems.
- Household Consumers:Homesteading supply channels and preparedness retailers curate multi-lid bundles for grain preservation customers. Subscription box models bypass traditional retail markups through direct-to-prepper e-commerce.
- Chemical Producers:Industrial compounders and specialty chemical manufacturers specify UN-rated closures for hazardous material containment.
- Retailers:Specialty grain suppliers and preparedness retailers increasingly specify complete pail-and-lid systems rather than component purchases.
Food Manufacturers represent the dominant procurement volume. Household Consumers are gaining share fastest through homesteading channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in injection molding clusters across Germany, Japan, and the United States, while consumption spreads through homesteading retail channels and commercial food processing networks in North America and Western Europe.
United States
Homesteading supply retailers and bulk food distributors drive replacement cycles for airtight pail closures. FDA food contact notifications govern polymer selection for food-grade applications. Midwest injection molding clusters around Chicago and Detroit supply heavy-duty gamma lids to commercial food processors.
Germany
REACH SVHC candidate list expansions force reformulation of color masterbatches and UV stabilizers in gamma lid production. ECHA notifications for titanium dioxide trigger material substitution programs across food-contact closures. Chemical distributors in the Rhine-Ruhr region now require full material disclosure documentation before stocking imported products.
China
Domestic demand from e-commerce preparedness retailers accelerates production of standard gamma lid configurations. GB standards for food contact plastics shape resin certification requirements for export-oriented manufacturers. Yangtze River Delta molding operations supply cost-competitive closures to North American private label distributors.
Japan
Precise thread-forming machinery from Nagoya and Osaka underpins high-tolerance gamma lid manufacturing for pharmaceutical applications. METI guidelines on plastic recycling influence material selection for domestic market products. Kanto region compounders develop specialized thermoplastic elastomer formulations for chemical-resistant gaskets.
Canada
Health Canada food contact material regulations align with FDA standards while adding domestic notification requirements for novel polymer formulations. Prairie grain handling operations specify heavy-duty gamma lids for extended outdoor storage. Ontario-based distributors serve cross-border homesteading demand through integrated North American supply chains.
Gamma Seal Lids Market Competitive Landscape
Top-tier vendors anchor premium positioning through proprietary threading designs and validated quality systems, while mid-tier fabricators compete on resin certification speed and private label flexibility. The vendor base stratifies across three archetypes: integrated pail-and-lid manufacturers, specialized closure engineers, and private label distributors sourcing from Asian molding networks. Dominant competitive moves include backward integration into blow-molded pail production and geographic expansion through preparedness retail channel partnerships.
Within the specialty retail tier, Pleasant Hill Grain exemplifies curated distribution focused on grain preservation and long-term food security customers. Gamma2 occupies a position as a recognized brand in homesteading and preparedness channels. Lee Valley Tools represents the woodworking and home organization retail segment that cross-sells gamma lids to household storage buyers.
| Leading Market Players |
|---|
| Gamma2 |
| Pleasant Hill Grain |
| Lee Valley Tools |
| Menards |
| Walmart |
| ePackage Supply |
| Innopack |
| United Poly |
| Leaktite |
| Others |
Value Network & Pricing Analysis
Commercial food processors and large-format manufacturers concentrate procurement volume for heavy-duty gamma lids, anchoring contract-based pricing with resin escalation clauses that transfer petrochemical volatility risk upstream.
Pricing Analysis
Margin tightening in mid-tier standard lids reflects HDPE and polypropylene resin cost volatility without long-term supply contract protection. Three-tier pricing structure across premium heavy-duty, standard food-grade, and economy private-label levels tracks certification burden and UV stabilization content. Cost compression accelerates as Asian molding networks compete on private label flexibility. Household consumers through homesteading channels show highest price sensitivity, while pharmaceutical and cannabis storage buyers absorb child-resistant certification premiums.
Supply Chain Analysis
Ocean freight rates and domestic trucking costs from Yangtze River Delta ports to North American distribution centers shape landed cost competitiveness for imported closures. Manufacturing concentrates in China, Germany, and Japan, with precision thread-forming machinery clustered around Nagoya and Osaka. Raw material sourcing draws from Saudi Arabian and U.S. Gulf Coast petrochemical feedstocks for HDPE, and South Korean polypropylene resin suppliers. Single-source vulnerability in German and Japanese injection molding equipment creates 18-24 month capacity expansion bottlenecks. Distribution runs through integrated pail-and-lid manufacturers, specialty preparedness retailers, and private label distributors serving big-box channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around resin certification speed and integrated pail-lid production capability, with FDA notification requirements and child-resistant testing protocols forcing sub-scale fabricators toward exit or acquisition.
For Market Incumbents: Deploy proprietary threading design patents to lock in commercial food processor contracts against Asian private label encroachment. Accelerate backward integration into blow-molded pail production to capture bundling margin pools from preparedness retailers consolidating vendor bases. Expand UV-stabilized HDPE capacity in Midwest injection molding clusters to defend heavy-duty segment share against resin-certified European imports. For New Entrants and Emerging Players: Municipal waste management districts piloting compostable packaging mandates represent an underserved buyer archetype with limited incumbent focus. PLA and PHA blend gamma lids meeting ASTM D6400 criteria open procurement channels without competing on food-grade polypropylene certification speed. Direct-to-prepper e-commerce subscription models bypass traditional retail markups while building brand recognition before scaling into commercial segments. For Investors and Strategic Acquirers: The window for entry favors integrated pail-and-lid manufacturers with validated FDA food contact notification pathways and existing Midwest production footprints. Mid-tier fabricators with resin certification expertise but lacking pail integration represent prime consolidation targets as bundling patterns concentrate volume. Watch state-level cannabis packaging mandate expansion as the inflection signal for child-resistant lid capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pail Manufacturing | Captures bundling economics as preparedness retailers consolidate vendor relationships. |
| Child-Resistant Certification Investment | Unlocks pharmaceutical and state-regulated cannabis storage procurement channels. |
| Biodegradable Polymer R&D Partnership | Secures pilot contracts with municipal waste districts advancing composting mandates. |
| Direct-to-Consumer E-Commerce Launch | Bypasses traditional homesteading retail markups through subscription grain preservation kits. |
| Midwest Capacity Expansion | Reduces freight exposure to commercial food processors in Chicago and Detroit clusters. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant managers at injection molding operations, procurement leads at commercial food processors, regulatory affairs directors at resin suppliers, and category buyers at specialty preparedness retailers. FDA food contact notifications, EPA chemical containment standards, and state cannabis packaging regulations provided compliance framework validation. Bottom-up volume builds from pail-and-lid shipment data triangulated against top-down polymer consumption estimates from HDPE and polypropylene resin trade flows.
Reconciling production capacity surveys, import-export customs records, and end-user procurement patterns generated volume and value estimates across the projection horizon. Segmentation modeling captured product type, material grade, application vertical, and end-user procurement pattern dimensions. CAGRs derived from regression analysis against petrochemical feedstock price indices, homesteading supply channel expansion rates, and regulatory mandate adoption curves. Child-resistant closure certification timelines and biodegradable plastic performance standard evolution served as industry-specific forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH SVHC list expansions, state cannabis packaging mandate fragmentation, and biodegradable polymer cost-competitiveness breakthroughs. Forecasts reflect documented assumptions about resin certification pathway durations and equipment lead time stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Resealable Closures and Spouts Packaging Market
Caps and Closures
Thailand Plastic Caps and Closures Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
France Plastic Caps and Closures Market
Caps and Closures
Disc Top Caps Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
Europe Plastic Caps and Closures Market
Caps and Closures
Steel Ring Pull Caps Market
Caps and Closures
Foamed End Caps Market
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Drop Sealers Market
Caps and Closures
Foam Cap Liners Market