
 T-Top Closures Market | 2026-2036
T-Top Closures Market Size, Share, and Industry Trends Forecast 2026-2036
T-Top Closures Market Analytics
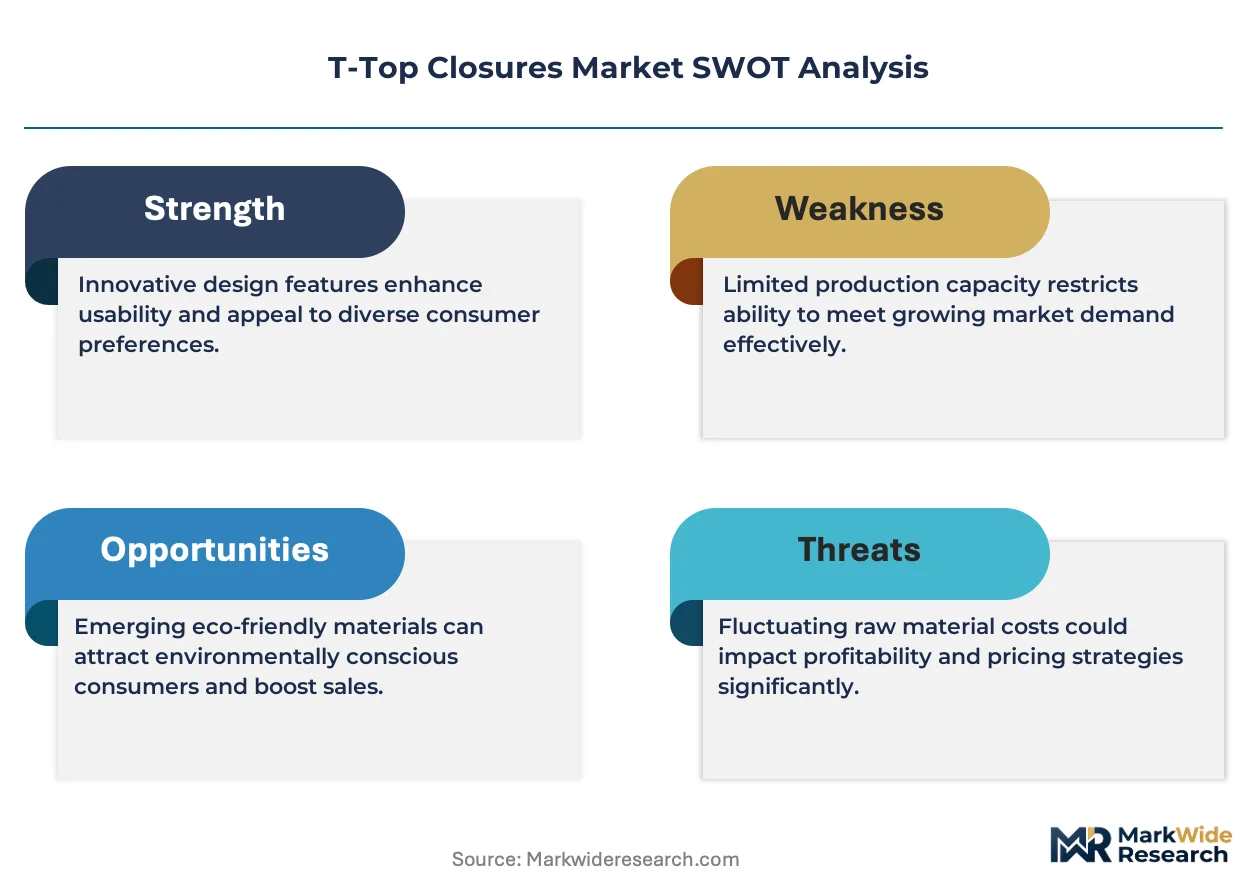
The EU Green Deal is restructuring procurement criteria across European marine OEMs, compelling suppliers to demonstrate recyclability and reduced carbon footprints in every component tier. Jelinek Cork Group leverages its Portuguese raw material sourcing to sustain premium positioning in cork-composite closure lines. Widgetco competes aggressively on price through high-volume plastic injection molding capacity in Southeast Asia. Advance Cork International anchors its reputation on certified sustainable harvesting protocols that satisfy ESG audit requirements from major boat builders.
T-top closures are rigid overhead canopy structures mounted on center-console boats and select recreational vehicles, typically fabricated from polycarbonate, acrylic, or aluminum extrusions with marine-grade hardware to provide weather protection while preserving open-air maneuverability. Composite material segments command margin premiums due to weight reduction and corrosion resistance in saltwater environments, while aluminum variants dominate aftermarket replacement cycles because of repair accessibility and lower installed cost. Plastic applications represent the fastest-growing category as rotational molding advances reduce unit costs for entry-level boat OEMs.
The EPA enforces marine emissions thresholds that indirectly shape hull and superstructure design, including T-top aerodynamics and weight profiles, while the EU's REACH framework restricts certain plasticizers and coatings used in closure manufacturing. The US Coast Guard maintains structural integrity standards for overhead installations on passenger-carrying vessels. Stakeholders must monitor evolving material compliance obligations across multiple jurisdictions before committing to long-term supply contracts or capital expansion plans.
Market Dynamics
Marine OEM procurement consolidation around Florida's boat-building corridor is compressing supplier margins while elevating technical performance requirements for T-top closure assemblies.
Growth Catalysts
- EPA marine emissions standards:Pressure toward lighter, more aerodynamic closure designs is stimulating composite material innovation and hardware miniaturization across center-console boat platforms.
- Rotational molding advances:Entry-level boat OEMs are adopting plastic T-top configurations as unit production costs decline and surface finish quality matches traditional materials.
- Florida manufacturing cluster concentration:Proximity between Fort Lauderdale and Tampa Bay fabricators enables just-in-time delivery models that reduce inventory carrying costs for marine assemblers.
Market Restraints
- Aluminum price volatility:Raw material swings in the London Metal Exchange aluminum contract compress margin predictability for extrusion-dependent closure fabricators serving aftermarket replacement cycles.
- REACH plasticizer restrictions:The EU's framework limits certain coatings and additives used in marine-grade hardware, forcing reformulation investments for suppliers maintaining European market access.
- Acrylic UV degradation:Technical limitations in polycarbonate alternative materials constrain product lifecycle guarantees in high-sunlight operating environments, particularly for charter fleet operators.
Strategic Opportunities
- EU Green Deal procurement criteria:European marine OEMs now require demonstrable recyclability and carbon footprint documentation, creating premium positioning for cork-composite closure suppliers with certified sustainable harvesting protocols.
- Modular quick-attach hardware systems:Technology convergence between marine fastening engineering and automotive clip-system design is enabling owner-installable T-top retrofits that bypass traditional dealer channels.
- Texas Gulf Coast boat-building expansion:Underpenetrated production capacity around Corpus Christi and Houston offers geographic diversification for suppliers seeking to reduce Florida cluster dependency.
Industry Challenges
- Marine-grade welding certification:Shortage of aluminum TIG specialists certified to US Coast Guard structural integrity standards lengthens production lead times for custom closure fabricators.
- Multi-jurisdiction compliance mapping:Suppliers must simultaneously satisfy EPA emissions-related design pressures, REACH substance restrictions, and Coast Guard overhead installation standards before contract execution.
- Legacy inventory system integration:Small-batch closure manufacturers face friction connecting ERP platforms with major boat builder procurement portals that mandate EDI transaction protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | T-Top Closures Market |
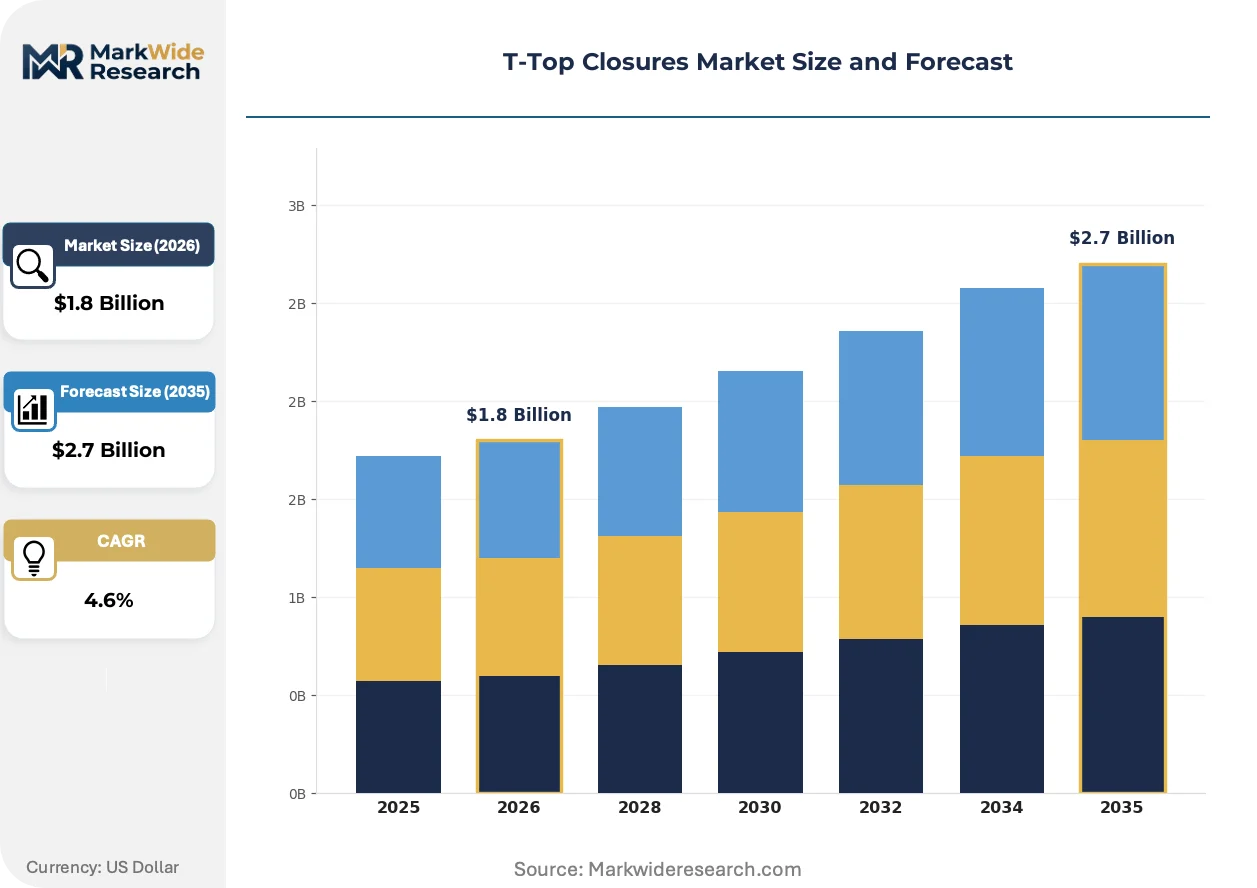
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite, Metal, Plastic, Glass End User: OEMs, Aftermarket Providers, Distributors, Retailers Material: Polycarbonate, Acrylic, Aluminum, Fiberglass Application: Recreational Vehicles, Boats, Industrial, Automotive |
| Companies Covered | MJS Packaging, Advance Cork International, Stanimirov Cork Industry, CorkLink, CP Lab Safety, Barnacork, Jelinek Cork Group, Bangor Cork, Widgetco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
T-Top Closures Market Evolving Landscape
Material science breakthroughs and regulatory compliance automation are restructuring how T-top closures are specified, fabricated, and certified across marine OEM supply chains.
Multi-axis CNC routing of carbon-fiber-reinforced polymer sheets is integrating complex curvature geometries previously requiring hand-laid fiberglass construction. Premium center-console builders in Florida and the Carolinas are specifying these components for tournament fishing vessels where weight reduction directly impacts fuel efficiency and top-speed performance. The technology is integrating design-to-manufacture workflows that compress prototype-to-production cycles from months to weeks.
The EU's Corporate Sustainability Reporting Directive is mandating supply-chain emissions disclosure from marine component suppliers serving European-flagged vessels. This framework compels T-top closure manufacturers to document embodied carbon in aluminum extrusions, composite resins, and marine hardware coatings. Suppliers with Portuguese cork-composite sourcing or certified recycled aluminum content are capturing preferred vendor status with EU-based boat builders.
Boat builders are consolidating vendor panels and shifting toward specification-grade procurement contracts that bundle T-top closures with integrated electronics mounting, lighting, and canvas enclosure systems. This pattern displaces component-by-component purchasing that previously allowed mix-and-match supplier selection. The concentration is most visible among mid-size center-console OEMs in the 24-to-36-foot segment operating along the US Atlantic seaboard.
T-Top Closures Market Segmentation
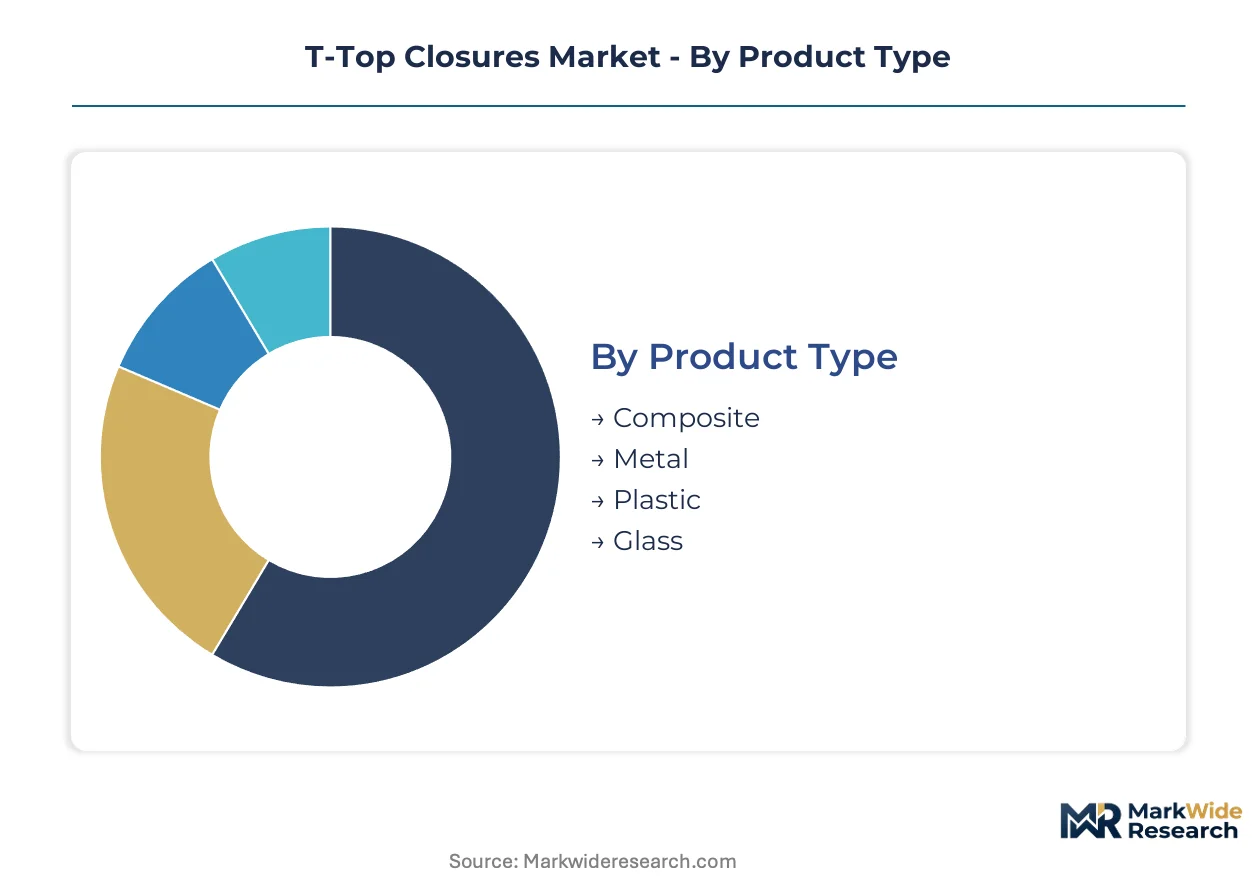
Segmentation in the T-top closures market reflects divergent buyer priorities across marine OEM procurement cycles, aftermarket replacement patterns, and material compliance requirements. Understanding these divisions enables suppliers to align production capacity with distinct margin structures and technical specifications.
Product Type:
Buyers differentiate primarily by weight tolerance, corrosion exposure, and installed cost thresholds across center-console boat platforms.
- Composite:Carbon-fiber-reinforced polymer and fiberglass blends deliver weight reduction and saltwater corrosion resistance for tournament fishing vessels. Florida OEMs specify these for premium center-console builds where EPA emissions pressures reward lighter superstructures.
- Metal:Aluminum extrusions dominate aftermarket replacement cycles due to repair accessibility and lower installed cost at dealer service centers. Price volatility in London Metal Exchange contracts compresses margin predictability for fabricators serving this segment.
- Plastic:Rotational-molded configurations serve entry-level boat OEMs as unit production costs decline and surface finish quality improves.
- Glass:Tempered and laminated variants provide optical clarity for luxury yacht applications where aesthetic integration commands premium positioning.
Composite leads volumes today; plastic is gaining share fastest.
End User:
Procurement authority concentrates differently across direct manufacturer relationships versus channel intermediaries.
- OEMs:Marine boat builders in Florida's Fort Lauderdale-Tampa Bay corridor consolidate vendor panels around specification-grade contracts bundling T-top closures with integrated electronics and canvas systems.
- Aftermarket Providers:Independent marine service centers source aluminum variants for collision repair and retrofit upgrades, prioritizing inventory turnover over technical customization.
- Distributors:Regional warehousing operations buffer small-batch closure manufacturers against major boat builder EDI transaction mandates.
- Retailers:Specialty marine chandlers serve owner-installable retrofit demand through modular quick-attach hardware systems.
OEMs anchor revenue concentration; aftermarket providers expand most quickly.
Material:
Specification decisions trace regulatory compliance obligations and operating environment exposure.
- Polycarbonate:Impact-resistant thermoplastic sheets withstand center-console hardtop impacts while maintaining optical clarity for integrated lighting systems.
- Acrylic:UV-stabilized variants serve budget-conscious charter fleet operators despite technical limitations in lifecycle guarantees under high-sunlight exposure.
- Aluminum:Marine-grade extrusions satisfy US Coast Guard structural integrity standards for overhead installations on passenger-carrying vessels.
- Fiberglass:Hand-laid and spray-up constructions persist in custom fabrication shops where CNC routing capacity remains limited.
Aluminum dominates replacement demand; polycarbonate climbs the fastest.
Application:
End-use environments dictate hardware corrosion specifications and aerodynamic loading requirements.
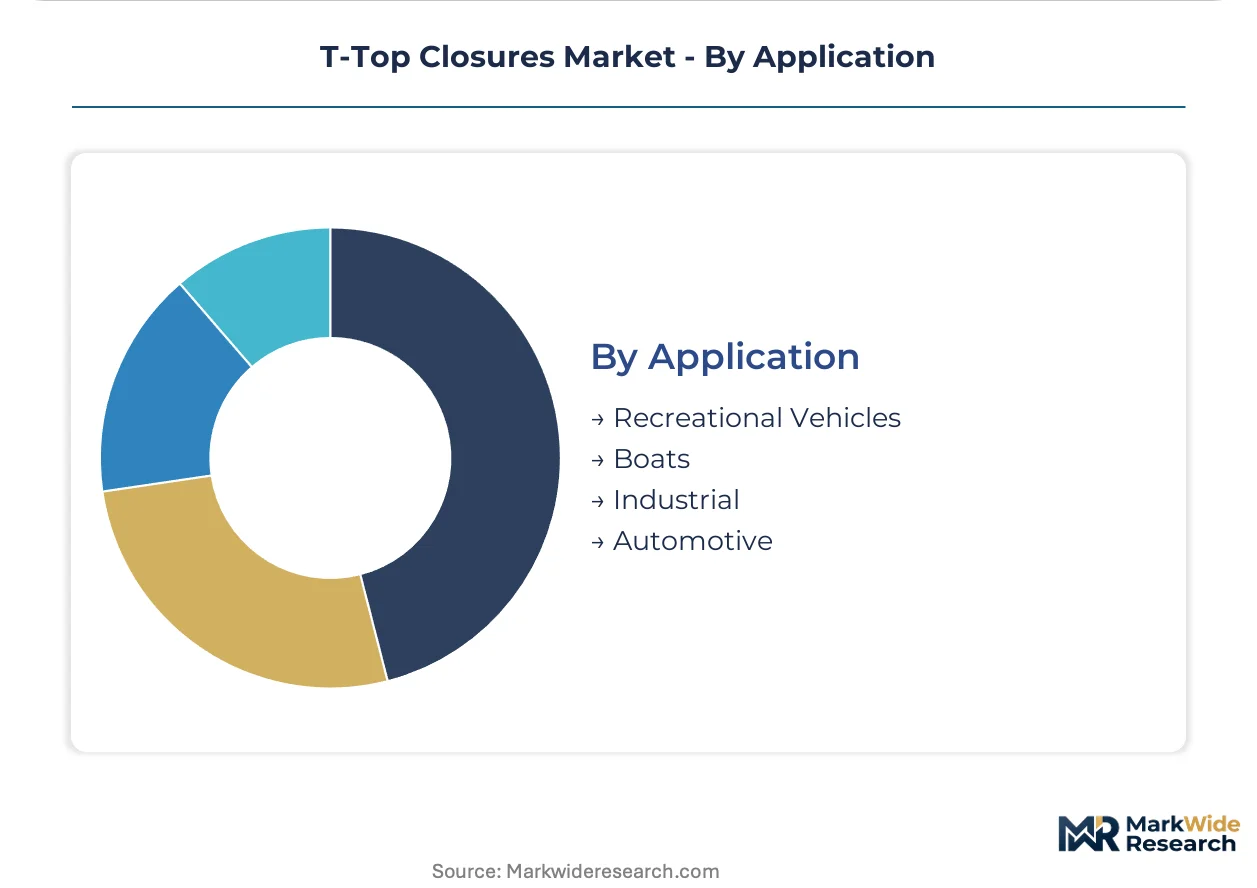
- Recreational Vehicles:Overland expedition vehicles adopt T-top configurations for rooftop tent mounting and solar panel integration, sourcing lighter composite variants.
- Boats:Center-console fishing vessels represent the core demand center, with EPA emissions standards indirectly shaping hull and superstructure design including T-top aerodynamics.
- Industrial:Offshore platform crew transfer vessels specify heavy-duty aluminum extrusions for structural overhead protection in salt-spray environments.
- Automotive:Utility vehicle aftermarket conversions represent a nascent category as modular quick-attach hardware migrates from marine to terrestrial applications.
Boats anchor absolute volumes; recreational vehicles show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified aluminum TIG welders and composite laminators concentrate in coastal manufacturing zones where boat-building heritage anchors technical workforce development.
United States
Florida's Fort Lauderdale-Tampa Bay corridor hosts the densest cluster of center-console OEM procurement activity. EPA marine emissions standards pressure hull and superstructure designers toward lighter T-top configurations. The state's vocational training programs at Manatee Technical College feed specialized welding talent directly into regional fabricators.
Portugal
Sustainable cork harvesting expertise supports premium composite closure supply chains serving EU-flagged vessel builders. The EU Green Deal procurement criteria mandate documented carbon footprint reductions across component tiers. The Alentejo and Algarve regions maintain certified harvesting cooperatives that satisfy ESG audit requirements from major European boat builders.
Germany
Precision aluminum extrusion and marine-grade hardware engineering serve industrial crew-transfer vessel specifications. ECHA REACH restrictions on plasticizers and coatings force reformulation investments for suppliers maintaining European market access. The Hamburg-Bremen port complex anchors fabrication capacity for offshore platform support vessels requiring heavy-duty overhead protection.
China
Rotational molding capacity expansion reduces unit production costs for entry-level boat OEMs sourcing plastic T-top configurations. The country's national environmental regulator enforces dual carbon goals that indirectly shape manufacturing energy intensity disclosures. The Pearl River Delta manufacturing belt integrates surface finish quality improvements that match traditional material aesthetics.
Australia
UV-stabilized polycarbonate demand climbs among charter fleet operators in high-sunlight operating environments. The country's national standards body maintains structural integrity protocols for passenger-carrying vessel overhead installations. The Gold Coast marine precinct concentrates custom fabrication shops serving tournament fishing vessel specifications.
T-Top Closures Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across material technology tiers, with extrusion-dependent fabricators facing margin compression from London Metal Exchange volatility while composite specialists capture premium positioning through certified sustainable sourcing. The vendor base stratifies into three archetypes: cork-composite sustainability leaders, high-volume plastic injection molders, and aluminum extrusion aftermarket suppliers. Competitive moves concentrate on geographic diversification away from Florida cluster dependency and modular quick-attach hardware system development.
Among cork-specialist fabricators, Jelinek Cork Group and Advance Cork International exemplify the sustainability-certified tier, with Portuguese raw material sourcing anchoring EU Green Deal compliance positioning. Widgetco occupies the scale-driven injection molding segment, with Southeast Asian production capacity enabling aggressive price competition for entry-level OEM procurement. These three anchors illustrate how material specialization and geographic sourcing strategy determine competitive positioning across regulatory jurisdictions.
| Leading Market Players |
|---|
| MJS Packaging |
| Advance Cork International |
| Stanimirov Cork Industry |
| CorkLink |
| CP Lab Safety |
| Barnacork |
| Jelinek Cork Group |
| Bangor Cork |
| Widgetco |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between EU Green Deal-compliant cork-composite suppliers and commodity aluminum extruders manifests in both margin structures and procurement geography, with premium tiers commanding vendor consolidation while price-competitive segments fragment across Southeast Asian molding capacity.
Pricing Analysis
Bundled specification-grade contracts dominate OEM procurement in Florida's Fort Lauderdale-Tampa Bay corridor, unbundled aluminum replacement parts flow through aftermarket service centers. Three-tier pricing structure across premium cork-composite, standard aluminum extrusion, and economy rotational-molded plastic reflects certification burden and raw material volatility. Cost compression in aluminum replacement cycles intensifies because London Metal Exchange contract swings erode fabricator margins. Entry-level boat OEMs exhibit highest price sensitivity; tournament fishing vessel builders demonstrate lowest.
Supply Chain Analysis
Reverse-logistics flows for collision-damaged T-top closures remain underdeveloped, limiting refurbishment revenue capture for aluminum extrusion fabricators. Manufacturing gravity centers on Florida, Portugal, and China's Pearl River Delta, with raw material dependencies spanning Portuguese cork harvests, London Metal Exchange aluminum contracts, and polycarbonate resin feedstocks. Single-source vulnerability concentrates in certified aluminum TIG welding talent pools feeding Florida fabricators. Distribution runs through marine OEM vendor panels, aftermarket dealer networks, and regional distributor warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by marine OEM procurement consolidation around specification-grade bundles integrating electronics mounting and canvas enclosure systems.
For Market Incumbents: Extend certified sustainable harvesting protocols into adjacent composite applications beyond T-top closures, securing preferred vendor status as EU Corporate Sustainability Reporting Directive disclosure requirements tighten. Defend margin position by acquiring modular quick-attach hardware technology from automotive clip-system designers before new entrants replicate owner-installable retrofit channels. For New Entrants and Emerging Players: Enter via Texas Gulf Coast boat-building expansion around Corpus Christi and Houston, where geographic diversification demand runs ahead of established supplier presence. Target recreational vehicle overland expedition segment for T-top configurations serving rooftop tent mounting, sourcing lighter composite variants absent entrenched marine incumbents. Pursue direct-to-consumer modular retrofit positioning bypassing traditional dealer channels. For Investors and Strategic Acquirers: Consolidation pressure builds where small-batch closure manufacturers face friction connecting ERP platforms with major boat builder EDI transaction mandates. Long-term viability favors asset-light designers with carbon-fiber-reinforced polymer CNC routing capability over extrusion-dependent fabricators tethered to commodity aluminum volatility. Monitor EPA marine emissions standard amendments as inflection indicator for composite material specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cork Harvesting | Portuguese certified cooperatives satisfy EU Green Deal procurement audit requirements. |
| Modular Quick-Attach Hardware Development | Automotive clip-system convergence enables owner-installable retrofit channel bypass. |
| Texas Gulf Coast Manufacturing Footprint | Corpus Christi and Houston capacity reduces Florida cluster dependency risk. |
| Carbon-Fiber CNC Routing Investment | Multi-axis curvature integration compresses prototype-to-production cycles for tournament vessels. |
| REACH Compliance Reformulation | ECHA plasticizer restrictions force coating chemistry investments maintaining European market access. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with marine OEM procurement directors, aluminum extrusion plant managers, cork-composite technical R&D directors, and aftermarket dealer service heads with secondary validation against US Coast Guard structural integrity filings, EPA marine emissions documentation, EU REACH substance restriction updates, and customs trade data. Bottom-up T-top closure shipment aggregation triangulated against top-down boat production database analysis.
Comparable-period anchoring linked projection horizons to historical reference cycles spanning regulatory implementation lags and material substitution patterns. Segmentation dimensions modeled included product type tier, end-user procurement authority, material compliance grade, and application environment exposure. CAGRs derived from shipment volume trajectories adjusted for aluminum price volatility corridors and rotational molding cost decline curves.
Inputs from marine OEM procurement portals and certified harvesting cooperatives were available through the study window; gaps in small-batch manufacturer ERP integration status introduce uncertainty bands around vendor consolidation timing. Forecasts reflect assumptions regarding EPA emissions standard enforcement intensity and EU Green Deal procurement criteria adoption velocity. Practitioners should monitor London Metal Exchange aluminum contract movements and Florida welding certification program throughput for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Peelable Lid Stock Market
Caps and Closures
Mexico Plastic Caps and Closures Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Reverse Cap Bottles Market
Caps and Closures
Europe Plastic Caps and Closures Market
Caps and Closures
Twist-Off Metal Caps Market
Caps and Closures
Tube Closures Market
Caps and Closures
Molded Fiber End Caps Market
Caps and Closures
Metal Closures Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Dispensing Caps Market
Caps and Closures
Australia and New Zealand Plastic Caps and Closures Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Aerosol Valves Market
Caps and Closures
Hinged Dispensing Caps Market