
 Germany Plastic Caps and Closures Market | 2026-2036
Germany Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Plastic Caps and Closures Market Insights
CE marking under the EU Packaging and Packaging Waste Regulation is unwinding the competitive landscape for imported closure systems. Bericap GmbH & Co. KG leverages its captive injection-molding footprint across Rhineland-Palatinate to dominate bulk beverage contracts. Pöppelmann GmbH & Co. KG anchors its position through deep specialization in automotive-adjacent fluid management caps. Silgan Holdings Inc. competes via European co-manufacturing partnerships that sustain continental delivery reliability without German production assets.
Plastic caps and closures are injection- or compression-molded polymeric sealing devices, typically specified to torque-release thresholds between 0.6 and 1.8 Nm, that secure container integrity across liquid and semi-solid supply chains. Their primary commercial purpose is to combine hermetic preservation with controlled consumer access while supporting automated capping lines running at 600+ units per minute. Screw caps retain the largest volume share within product type segmentation, though child-resistant caps command premium positioning in pharmaceutical contracts. HDPE and PP together capture the bulk of material demand, yet rPP formulations are gaining structural traction as brand owners face EPR fee restructuring.
Germany's Federal Environment Agency enforces the national Packaging Act implementation, while the EU Green Deal's packaging recyclability targets and REACH substance restrictions jointly constrain material formulation freedom. KBA and ECHA compliance documentation now gates market access for non-EU suppliers seeking German distribution. Stakeholders must monitor how the EU's pending mandatory recycled content quotas for plastic packaging reconfigure sourcing economics and qualification timelines for closure converters.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are forcing German converters to requalify entire product portfolios around mono-polymer recyclability, collapsing legacy multi-layer designs and rewiring supplier qualification timelines.
Growth Catalysts
- Pharmaceutical serialization mandates:Tighter EU Falsified Medicines Directive enforcement is expanding demand for tamper-evident and child-resistant closure systems across prescription packaging lines.
- Bavaria chemical corridor concentration:Dense clustering of agrochemical and specialty chemical formulators sustains high-volume contracts for chemical-resistant HDPE closures with fluoropolymer liners.
- rPP formulation advances:Mechanical recycling technology improvements are enabling food-grade post-consumer polypropylene integration into beverage closure specifications.
Market Restraints
- Feedstock cost volatility:Propylene and ethylene price swings tied to naphtha-cracking economics compress margin predictability for PP and HDPE closure molders.
- Import certification friction:Non-EU suppliers face KBA and ECHA documentation gates that extend German market entry timelines by 8-14 months.
- Aluminum substitution in premium beverages:Crown cork and screw-cap aluminum formats are capturing share in craft beer and mineral water segments.
Strategic Opportunities
- North Rhine-Westphalia logistics hub proximity:Closure converters co-located near Duisburg container terminals can compress lead times for Benelux re-export markets.
- EU Green Deal recycled content quotas:Pending mandatory thresholds for post-consumer plastic in packaging create first-mover advantages for rPP-qualified suppliers.
- Smart closure integration:NFC-enabled authentication caps combining polymer molding with electronics assembly open pharmaceutical anti-counterfeiting contracts.
Industry Challenges
- REACH substance restriction compliance:ECHA candidate list expansions force continuous reformulation of UV stabilizers and colorants in closure masterbatches.
- Tooling amortization pressure:Mono-polymer redesigns require new injection mold investments with 4-6 year payback horizons amid uncertain quota implementation dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Plastic Caps and Closures Market |
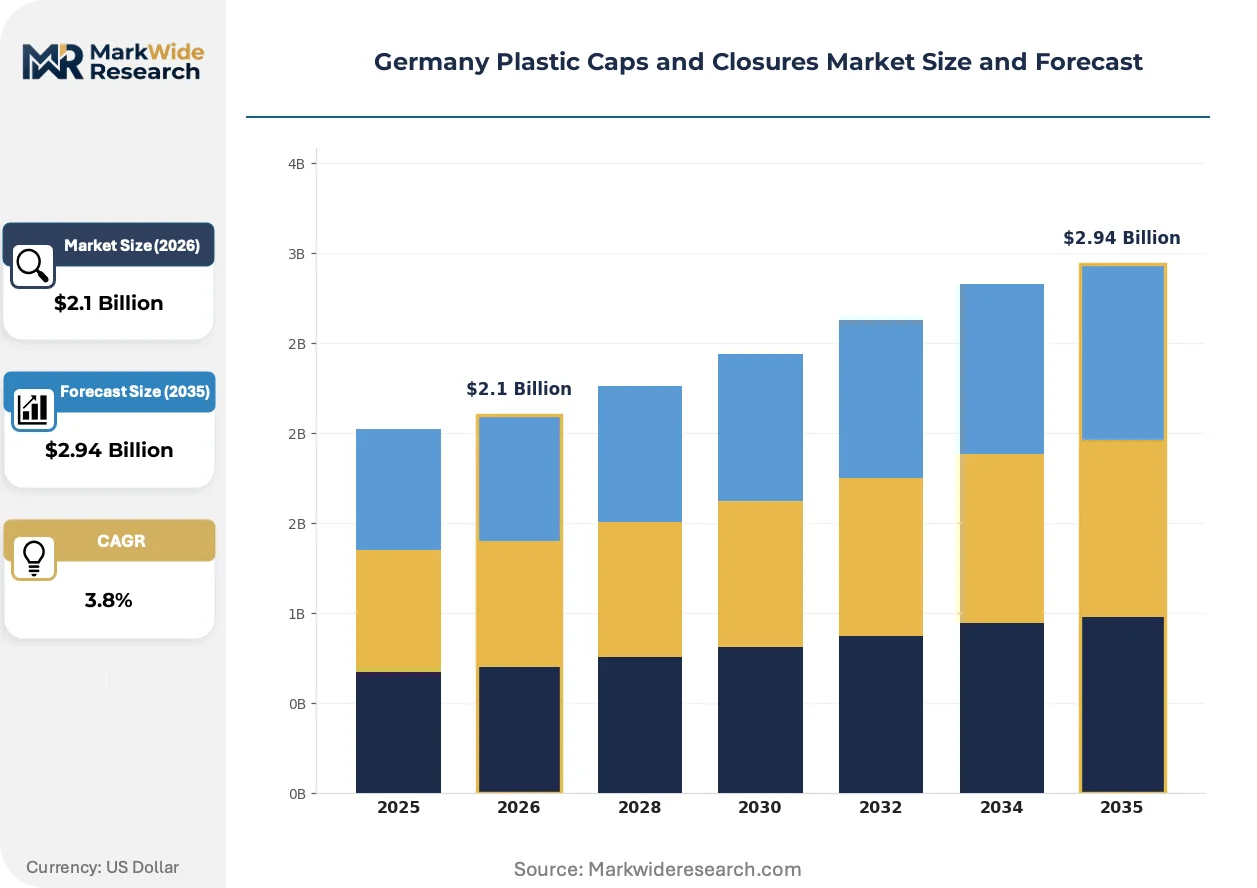
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap-On Caps, Dispensing Caps, Child-Resistant Caps Material: HDPE, PP, LDPE, PET End User: Beverage Industry, Food Industry, Pharmaceutical Industry, Cosmetic Industry Closure Design: Flip Top, Sports Cap, Twisting Cap, Tamper-Proof Cap |
| Companies Covered | Bericap GmbH & Co. KG, Pöppelmann GmbH & Co. KG, Silgan Holdings Inc., Berry Global, Inc., Caplugs, Inc., United Caps, AptarGroup, Inc., Amcor plc, ALPLA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Plastic Caps and Closures Market Trends and Innovations
Digital watermarking and blockchain traceability are converging with material science advances to reconfigure how German closure converters prove compliance and capture premium positioning.
Mono-material polypropylene closures with integrated tamper-evident bands are decomposing legacy multi-component designs across beverage and dairy segments. Aldi Nord and Rewe Group are accelerating adoption in private-label water and juice lines. This compression is eliminating separate liner insertion steps and reducing capping line jam rates.
EU Green Deal packaging recyclability targets are mandating design-for-recycling protocols that disqualify complex multi-polymer assemblies. German Federal Environment Agency enforcement is tightening documentation requirements for EPR fee calculations. Pharmaceutical and food contact segments are responding with accelerated mono-PP qualification programs.
Brand owners are consolidating supplier panels around vertically integrated molders capable of in-house rPP compounding and closed-loop collection. Direct contracting between Nestlé Deutschland and closure converters is displacing traditional distributor intermediaries in bottled water procurement. Bavaria and Baden-Württemberg bottling clusters exhibit the most advanced panel consolidation.
Germany Plastic Caps and Closures Market Segmentation
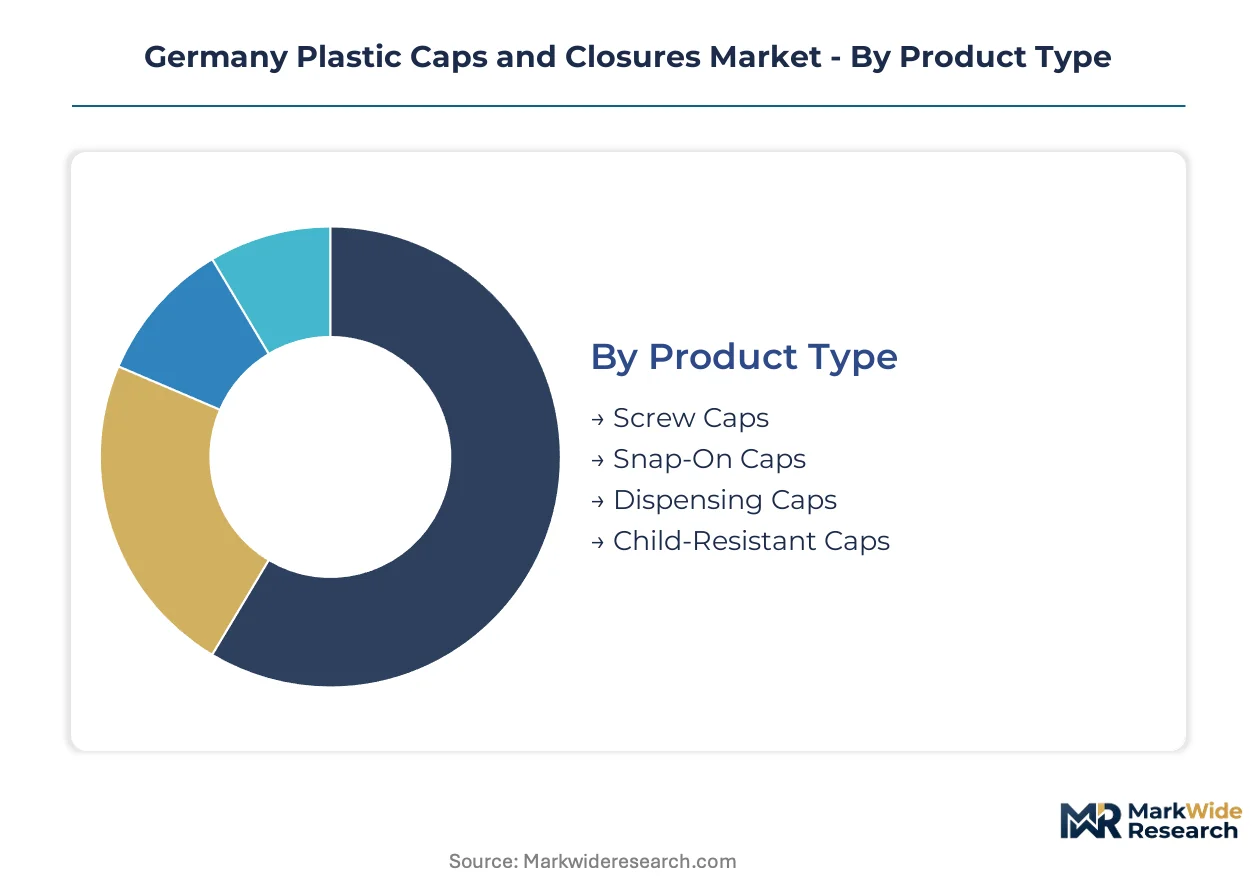
Plastic caps and closures in Germany fragment across four structural dimensions that determine qualification pathways and margin architecture. Product type and material choices lock in recyclability compliance under EU Packaging and Packaging Waste Regulation mandates. End-user concentration in Bavaria's chemical corridor and North Rhine-Westphalia's logistics hubs reshapes regional demand patterns.
Product Type:
Channel mix varies sharply: screw caps and snap-on caps dominate high-volume beverage bottling lines, while child-resistant and dispensing caps flow through pharmaceutical and cosmetic contract packers with longer qualification cycles.
- Screw Caps:Threaded polypropylene or HDPE designs specified to 0.6-1.8 Nm torque-release thresholds secure carbonated beverage and edible oil containers. Bavaria's bottling clusters consume the bulk of volume as Aldi Nord and Rewe Group consolidate private-label procurement around mono-PP specifications.
- Child-Resistant Caps:Dual-action mechanisms combining push-and-turn torque with senior-friendly ergonomics protect prescription pharmaceuticals. North Rhine-Westphalia's pharmaceutical packaging lines drive demand as EU Falsified Medicines Directive enforcement tightens serialization requirements.
- Snap-On Caps:Compression-fit designs eliminate threading for dairy and ready-to-drink applications.
- Dispensing Caps:Integrated valve or orifice controls serve agrochemical and household chemical containers.
By volume, screw caps lead. By growth pace, child-resistant caps are climbing the fastest.
Material:
Cost tiers separate commodity resins from recycled-content grades facing EPR fee restructuring.
- PP:Homopolymer and random copolymer grades dominate beverage closure specifications for their fatigue resistance and organoleptic neutrality. Mechanical recycling advances now enable food-grade rPP integration, with converters in Baden-Württemberg piloting closed-loop collection systems.
- HDPE:High-density formulations with fluoropolymer liners resist chemical permeation in agrochemical packaging. The Bavaria chemical corridor sustains premium pricing for fluorosilicone-lined HDPE caps serving specialty chemical formulators.
- LDPE:Lower-density grades flex for squeeze tubes and flexible pouch fitments.
- PET:Crystalline clarity suits cosmetic dispensing applications where aesthetic differentiation commands margin.
By installed capacity, PP leads. By regulatory momentum, rPP-qualified HDPE blends are expanding most quickly.
End User:
Application requirements dictate performance tiering from commodity beverage to validated pharmaceutical grades.
- Beverage Industry:Carbonated soft drink and mineral water bottlers specify mono-PP screw caps at 600+ units per minute line speeds. KBA compliance documentation gates supplier qualification for non-EU resin sources.
- Pharmaceutical Industry:Tamper-evident and child-resistant systems integrate with serialization infrastructure under EMA guidance. ECHA REACH restrictions on UV stabilizers force continuous masterbatch reformulation.
- Food Industry:Dairy and condiment packers prioritize hermetic seal integrity for refrigerated supply chains.
- Cosmetic Industry:Premium dispensing and twisting designs emphasize aesthetic differentiation over functional complexity.
By contract value, pharmaceutical leads. By volume scale, beverage maintains the steepest expansion trajectory.
Closure Design:
Maturity gradients separate established flip-top beverage formats from emerging smart closure electronics integration.
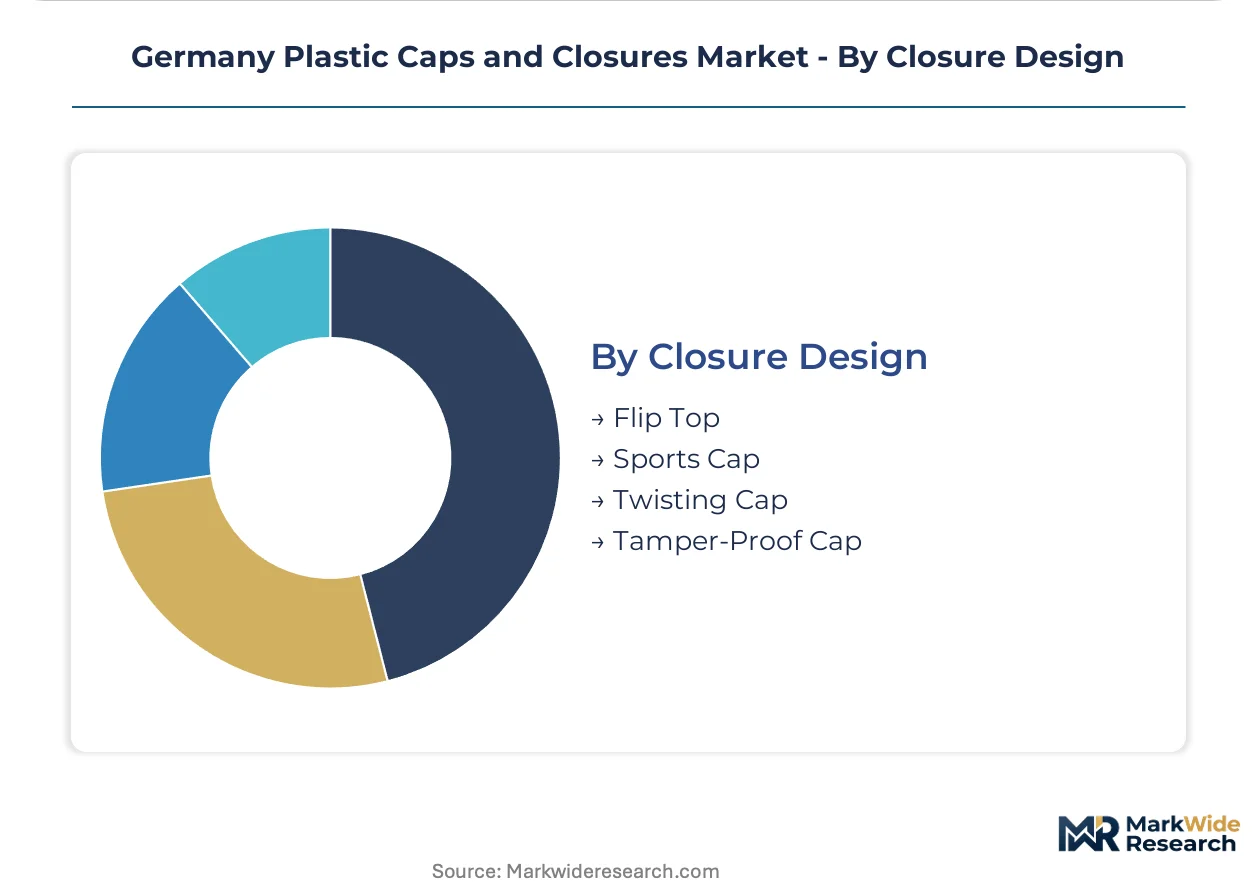
- Flip Top:Hinged polypropylene lids integrate tethered retention for on-the-go beverage consumption. Sports nutrition and functional drink brands in North Rhine-Westphalia drive specification updates.
- Tamper-Proof Cap:Break-band or shrink-sleeve evidence systems secure pharmaceutical and food contact applications. EU Green Deal recyclability targets now mandate mono-material band designs eliminating multi-component assemblies.
- Sports Cap:Pull-spout mechanisms target athletic and children's beverage segments.
- Twisting Cap:Continuous thread variants serve condiment and sauce dispensing.
By line integration speed, flip top leads. By compliance urgency, tamper-proof formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German beverage and pharmaceutical packers concentrate procurement authority in Bavaria and North Rhine-Westphalia, driving closure demand patterns that favor regional supplier proximity over pan-European sourcing.
Bavaria
Carbonated beverage bottlers and agrochemical formulators anchor closure consumption in southern Germany. The Federal Environment Agency enforces Packaging Act compliance documentation that gates supplier qualification. Munich and Nuremberg chemical processing corridors sustain high-volume contracts for fluorosilicone-lined HDPE caps serving specialty chemical applications.
North Rhine-Westphalia
Pharmaceutical serialization mandates under the EU Falsified Medicines Directive expand demand for tamper-evident and child-resistant systems. ECHA REACH restrictions on UV stabilizers force continuous masterbatch reformulation for local converters. Düsseldorf and Cologne logistics hubs compress lead times for Benelux re-export markets through direct rail and barge connections.
Baden-Württemberg
Automotive-adjacent fluid management applications and dairy packaging lines diversify closure specifications in southwestern Germany. KBA compliance documentation requirements extend market entry timelines for non-EU resin suppliers. Stuttgart industrial belt converters pilot closed-loop rPP collection systems for food-grade beverage closure integration.
Lower Saxony
Dairy and condiment packers prioritize hermetic seal integrity for refrigerated supply chains in northern Germany. EU Green Deal packaging recyclability targets mandate design-for-recycling protocols that disqualify multi-polymer assemblies. Hanover and Brunswick food processing clusters accelerate mono-PP qualification programs for private-label procurement.
Hesse
Cosmetic and household chemical dispensing applications emphasize aesthetic differentiation in central Germany. EPR fee restructuring under national Packaging Act implementation redirects material choices toward recyclable mono-polymer designs. Frankfurt Rhine-Main logistics infrastructure supports just-in-time delivery contracts for premium cosmetic brands.
Germany Plastic Caps and Closures Market Competitive Landscape
Player mix skews toward vertically integrated molders with captive injection-molding footprints and regional co-manufacturing partnerships. Market structure consolidates around three strategic archetypes: Rhineland-Palatinate-based bulk beverage specialists, Baden-Württemberg automotive-adjacent fluid management experts, and European co-manufacturing networks sustaining continental delivery reliability. Dominant competitive moves include mono-polymer portfolio requalification and rPP compounding capability expansion.
Among Germany-based fabricators, Bericap GmbH & Co. KG and Pöppelmann GmbH & Co. KG exemplify distinct archetype positioning. Bericap anchors the bulk beverage contract tier through Rhineland-Palatinate manufacturing concentration. Pöppelmann occupies a specialist position in automotive-adjacent fluid management applications. Silgan Holdings Inc. represents the European co-manufacturing partnership model, sustaining market presence without German production assets.
| Leading Market Players |
|---|
| Bericap GmbH & Co. KG |
| Pöppelmann GmbH & Co. KG |
| Silgan Holdings Inc. |
| Berry Global, Inc. |
| Caplugs, Inc. |
| United Caps |
| AptarGroup, Inc. |
| Amcor plc |
| ALPLA |
| Others |
Pricing and Supply Chain Analysis
CE marking and KBA certification gates simultaneously constrain supplier qualification timelines and stratify price tiers across the German closure market. Brand owners now pay premiums for converters holding validated EPR documentation while non-compliant imports face extended entry delays that compress their pricing power.
Pricing Analysis
Cost-plus contracts with naphtha-indexed resin clauses dominate procurement agreements between Bavarian bottlers and Rhineland-Palatinate molders. Three-tier pricing structure across pharmaceutical-grade, food-contact standard, and industrial economy levels reflects certification burden differentials. Pricing pressure stems from propylene volatility feeding through to PP closure margins. Beverage bottlers exhibit highest price sensitivity due to volume scale and commoditized specifications, while pharmaceutical packers accept premiums for child-resistant validation.
Supply Chain Analysis
Inventory buffers at Duisburg container terminals compress lead times for Benelux re-export markets by 10-14 days versus southern German alternatives. Supply concentrates in Germany, Italy, and Poland for injection-molded closures, with resin feedstock drawing from Belgian and Dutch petrochemical complexes. Single-source vulnerability runs through fluorosilicone liner suppliers serving Bavaria's agrochemical corridor. Distribution feeds from converter direct contracts into Aldi Nord and Rewe Group procurement hubs, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's pending recycled content quotas constitute a technological-regulatory inflection that will restructure competitive economics across the forecast window. Stakeholders must position before mandate implementation locks in supplier hierarchies.
For Market Incumbents: Shield market position through captive rPP compounding investments in Baden-Württemberg and Rhineland-Palatinate before quota thresholds activate. Accelerate mono-polymer mold requalification programs to collapse competitor qualification timelines. Backward integration into post-consumer collection partnerships with Nestlé Deutschland and regional bottling clusters secures feedstock priority.
For New Entrants and Emerging Players: Lead with smart closure electronics integration targeting pharmaceutical anti-counterfeiting contracts in North Rhine-Westphalia. White-space opportunity sits in NFC-enabled authentication caps where incumbents lack electronics assembly competency. Direct contracting with mid-tier cosmetic brands in Hesse offers lower qualification barriers than beverage volume plays.
For Investors and Strategic Acquirers: EU Green Deal recycled content quotas reshape the acquisition landscape toward rPP-qualified molders with closed-loop infrastructure. Long-term viability favors targets holding KBA documentation and EPR fee optimization capabilities. Monitor ECHA candidate list expansions for UV stabilizer reformulation costs that will stress undercapitalized converters.
| Strategic Initiative | Industry Significance |
|---|---|
| rPP Compounding Capacity Expansion | Captures first-mover advantage under EU Green Deal recycled content mandates. |
| Smart Closure Electronics Integration | Opens pharmaceutical anti-counterfeiting contracts with NFC-enabled authentication. |
| Mono-Polymer Mold Requalification | Ensures Packaging Act compliance while eliminating multi-component assembly costs. |
| Closed-Loop Collection Partnerships | Secures post-consumer feedstock priority with Nestlé Deutschland and Rewe Group. |
| Direct Brand Owner Contracting | Displaces distributor intermediaries in private-label beverage procurement. |
Research Methodology
Initial hypotheses were tested against primary input from closure converter plant managers, beverage procurement leads at Aldi Nord and Rewe Group, pharmaceutical packaging engineers, and EPR compliance officers, then refined through secondary validation. Customs data from German Federal Statistical Office, ECHA REACH registration databases, KBA certification filings, and EU Packaging and Packaging Waste Regulation impact assessments supplied quantitative anchors. Bottom-up volume triangulation across Bavaria, North Rhine-Westphalia, and Baden-Württemberg production clusters converged with top-down macroeconomic drivers.
Variance decomposition across product type, material grade, end-use industry, and regional production hub dimensions structured the analytical framework. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EU Falsified Medicines Directive serialization timelines, EPR fee restructuring schedules, and rPP mechanical recycling yield improvements.
The analysis sits within stated boundaries; outcomes outside EU regulatory implementation timelines or propylene price band assumptions would require recalibration. Forecasts reflect documented assumptions about mandate enforcement intensity and resin technology maturation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Aerosol Caps Market
Caps and Closures
End Cap Market
Caps and Closures
Buttress Closures Market
Caps and Closures
Dauber Caps Market
Caps and Closures
Ribbed Closures Market
Caps and Closures
Linerless Closures Market
Caps and Closures
Bag Closure Clips Market
Caps and Closures
Asia Pacific Metal Caps and Closures Market
Caps and Closures
Nordic Plastic Caps and Closures Market
Caps and Closures
Spray Caps Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Australia and New Zealand Plastic Caps and Closures Market
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
Humidity Indicator Plugs Market
Caps and Closures
Side Pour Caps Market
Caps and Closures
Snap-On Closures Market