
 Plastic Caps and Closure Market | 2026-2036
Plastic Caps and Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Caps and Closure Market Intelligence
A shift toward lightweighted and tethered designs is rotating the competitive landscape for plastic caps and closures. This move prioritizes material reduction and compliance with new environmental regulations. Berry Global Inc. leverages its extensive manufacturing footprint to supply high-volume beverage markets. Amcor plc differentiates with its portfolio of sustainable and recyclable closure solutions, while Closure Systems International Inc. specializes in advanced sealing technologies for carbonated drinks and aseptic packaging.
Plastic caps and closures are primarily injection or compression-molded components designed to seal containers. Materials like Polypropylene and Polyethylene are selected for their durability, chemical resistance, and sealing properties. These products serve to protect contents from contamination, maintain freshness, and enable controlled dispensing. Screw Caps continue to dominate market volume, driven by their widespread use on bottles in the food & beverage industry, whereas Dispensing Caps command higher margins in the cosmetics and household products sectors.
Regulatory frameworks significantly influence material composition and product design. In the United States, the FDA sets stringent standards for food-contact materials. The EU's Single-Use Plastics Directive mandates tethered cap designs to reduce litter, while China's GB standards govern packaging safety and quality. Navigating evolving recycled content mandates and consumer demand for convenience will dictate future material selection and investment in new molding technologies.
Market Dynamics
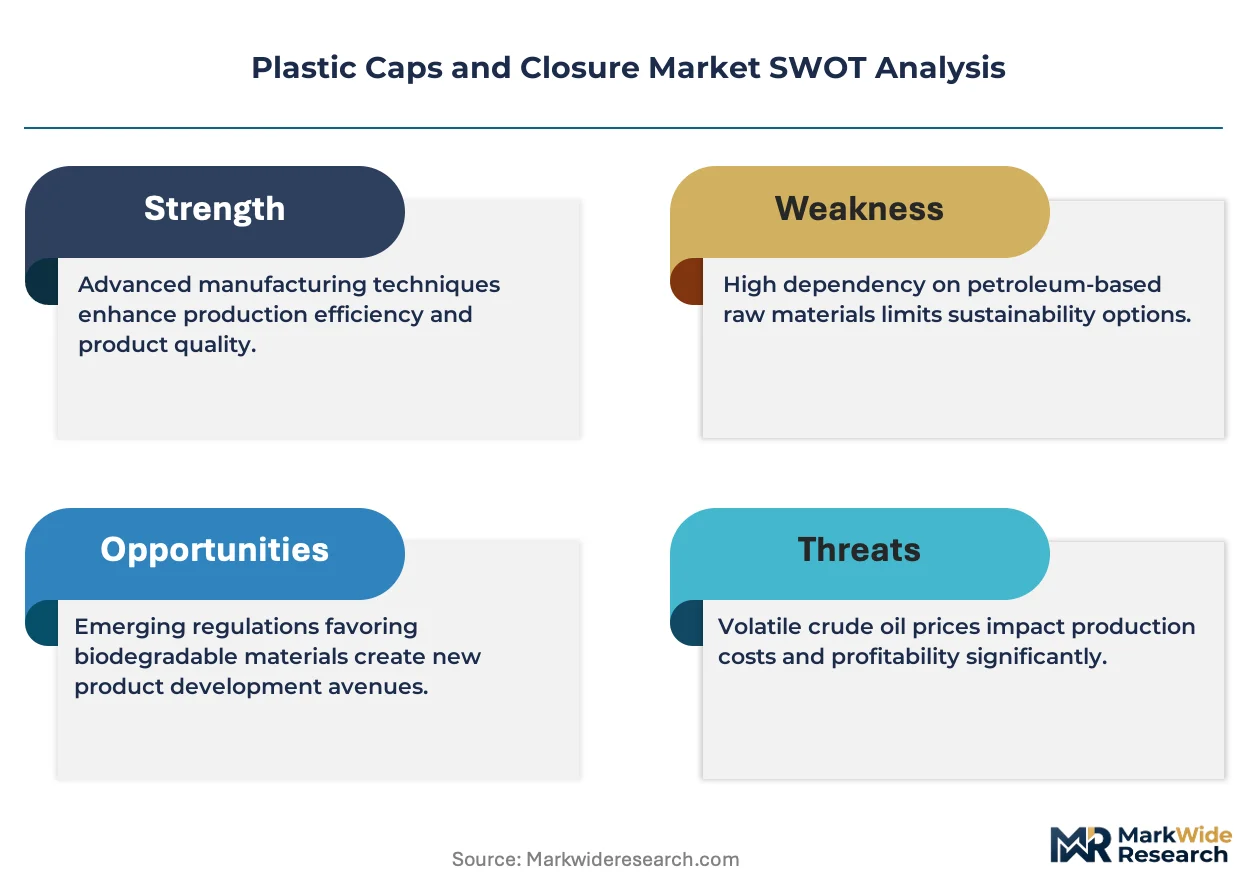
The central dynamic shaping the plastic caps and closure market is the regulatory push for circularity, exemplified by the EU's tethered cap mandate. This force compels manufacturers to balance complex design innovation and material science against persistent cost pressures from volatile polymer feedstocks.
Growth Catalysts
- Regulatory Mandates:The EU's Single-Use Plastics Directive is forcing a market-wide redesign toward tethered caps, creating a non-discretionary replacement cycle for beverage closures and stimulating investment in new molding technologies.
- Beverage Market Expansion:Significant growth in the ready-to-drink coffee, tea, and functional beverage segments, particularly in consumer markets like Indonesia and Vietnam, is driving volume demand for standard and sport closures.
- Aseptic Packaging Demand:The need for extended shelf life in dairy, juice, and alternative milk products fuels demand for advanced closures with superior sealing and barrier properties, often used with aseptic cartons.
Market Restraints
- Raw Material Volatility:Price fluctuations for key thermoplastic resins like Polypropylene and Polyethylene, which are linked to global oil and gas markets, directly impact production costs and compress manufacturer margins.
- Threat of Substitution:Increasing consumer and brand owner preference for alternative packaging materials, such as aluminum cans and glass bottles, poses a substitution risk, especially in the premium beverage and personal care sectors.
- High Retooling Costs:The significant capital investment required to upgrade or replace injection and compression molding equipment to produce lightweighted or tethered designs acts as a barrier for smaller manufacturers.
Strategic Opportunities
- Smart Closure Integration:Incorporating technologies like NFC tags or scannable QR codes into closures offers a path for brand protection, anti-counterfeiting, and direct consumer engagement, especially for pharmaceuticals and high-end spirits.
- Recycled Content Leadership:Proactively developing and scaling the use of high-quality, food-grade post-consumer resin (PCR) provides a competitive advantage as recycled content mandates expand in jurisdictions like California and the EU.
- Geographic Market Penetration:There is significant white space for sophisticated dispensing closures for cosmetics and home care products in emerging economies across South America and Africa, where demand for packaged goods is rising.
Industry Challenges
- Divergent Global Standards:Navigating disparate food-contact safety regulations, such as the FDA framework in the United States versus China's GB standards, complicates supply chain management and slows the launch of global product lines.
- Recycled Feedstock Scarcity:Securing a consistent and high-quality supply of food-grade recycled polymers remains a primary operational hurdle, limiting the ability of manufacturers to meet ambitious sustainability goals set by CPG clients.
- Tethered Design Fragmentation:The absence of a universal industry standard for tethered cap systems results in a proliferation of proprietary designs, creating potential inefficiencies and compatibility issues across the bottling industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Caps and Closure Market |
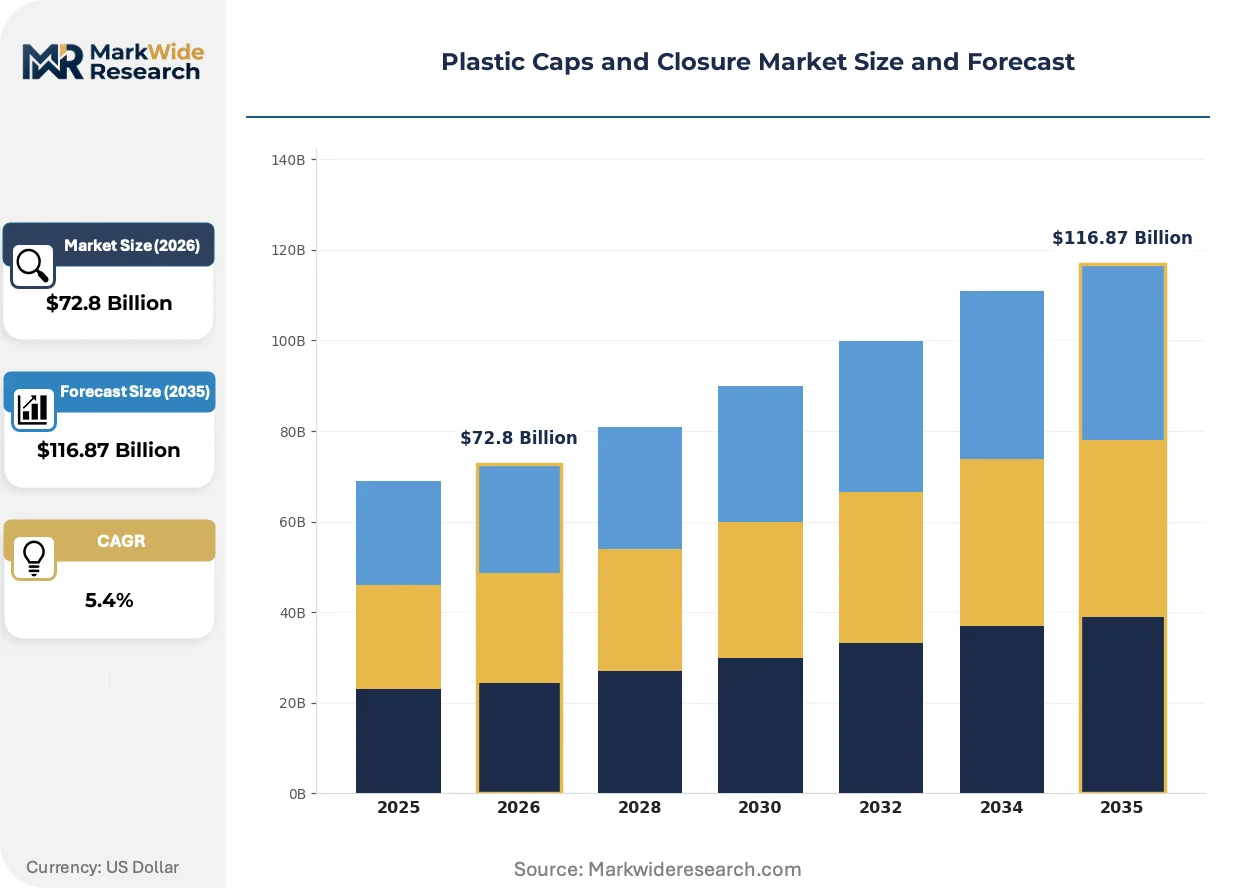
| Market Size in 2026 | $72.8 Billion |
| Market Size in 2035 | $116.87 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Screw Caps, Snap-on Caps, Dispensing Caps, Child-resistant Caps Material: Polypropylene, Polyethylene, PVC, PET End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Packaging Type: Bottles, Jars, Tubes, Cans |
| Companies Covered | Closure Systems International Inc., Crown Holdings Inc., Silgan Holdings Inc., Guala Closures S.p.A, BERICAP Holding GmbH, Amcor plc, Berry Global Inc., Sonoco Products Company, AptarGroup Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Caps and Closure Market Strategic Shifts & Innovations
Material science innovation is converging with new regulatory pressures to redefine product viability. The market is moving toward designs that either enhance recyclability through material simplification or provide advanced functionality, creating a clear performance and cost divergence in product portfolios.
Mono-material closures, typically made entirely of Polypropylene or Polyethylene, are designed to simplify sorting and improve recycling outcomes. These closures are seeing accelerated adoption by beverage and food producers in Europe aiming to meet circular economy objectives. This development is bifurcating the market between these easily recyclable, single-polymer caps and higher-margin, multi-component dispensing systems that offer convenience but present recycling challenges.
Recycled content mandates, including California's AB 793 and similar frameworks under discussion within the EU, are becoming a critical design parameter. This shift compels manufacturers to validate and secure stable supply chains for post-consumer resin (PCR) that satisfy stringent performance and safety criteria. The beverage and household chemical sectors are most impacted, driving investment in advanced purification and chemical recycling to produce food-grade recycled polymers.
A demand-side shift toward e-commerce requires closures engineered to withstand the rigors of parcel shipping and prevent leakage. This trend is disrupting packaging strategies, creating a preference for closures with induction seals or robust dispensing mechanisms over basic screw caps for liquids. This evolution is most prominent in the North American and European markets for products like household cleaners, sauces, and personal care items sold online.
Plastic Caps and Closure Market Segmentation
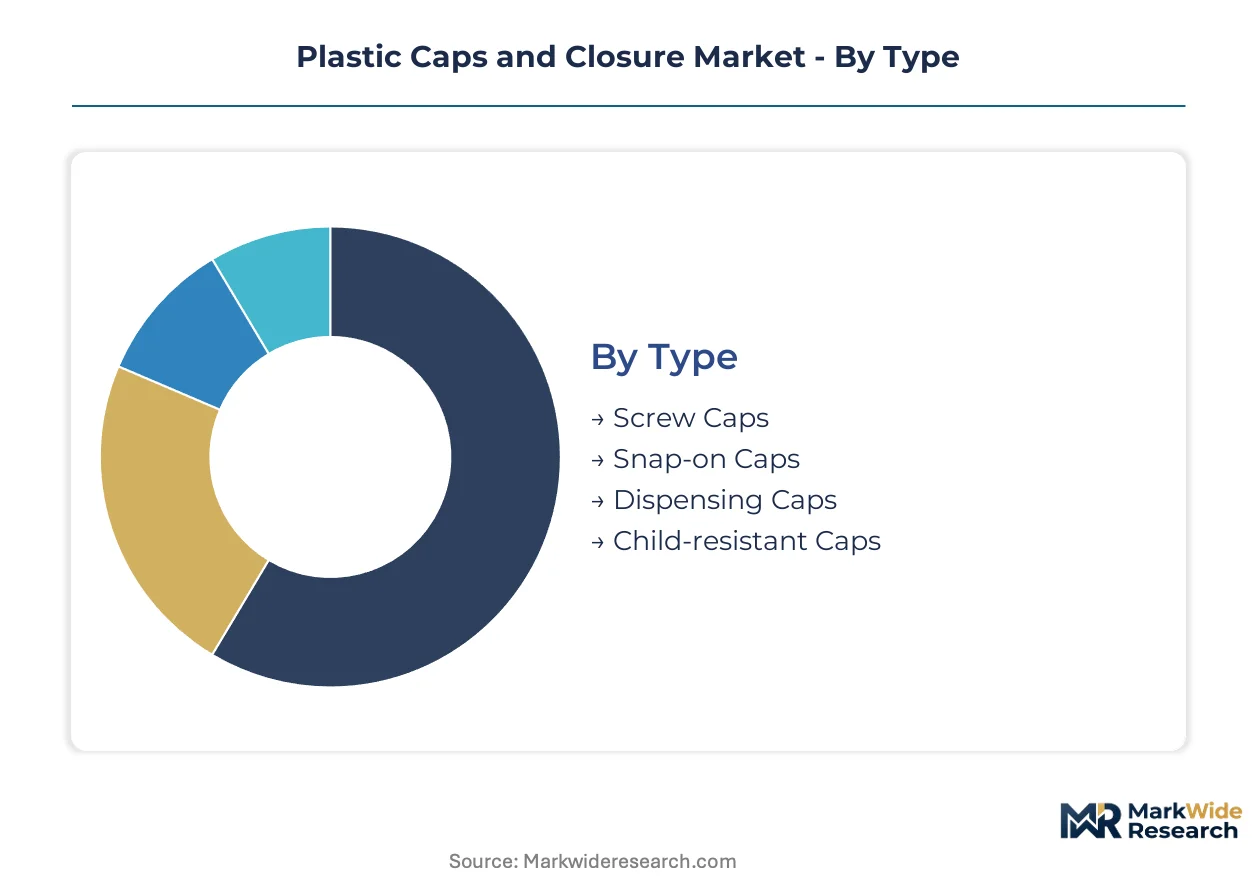
Understanding market segmentation reveals the diverse forces shaping product development and demand within the plastic caps and closure industry. This analysis highlights how material science, regulatory compliance, and end-user application drive distinct value propositions across various product categories. Strategic investments align with segments demonstrating robust growth potential and evolving consumer requirements.
Type:
Margin pools within the cap and closure types are concentrated in specialized dispensing and security features rather than basic sealing functions. Manufacturers prioritize functionality and user convenience for premium products.
- Screw Caps:These closures utilize a threaded design to create a secure, reclosable seal, commonly molded from Polypropylene or Polyethylene. Demand for screw caps remains dominant in the global food and beverage sector due to their cost-effectiveness and widespread use on bottles.
- Dispensing Caps:Designed for controlled product release, these include flip-top, push-pull, and disc-top designs, often incorporating multiple components for precise delivery. Dispensing caps command higher margins in the cosmetics and household products sectors, driven by consumer demand for convenience and product differentiation.
- Snap-on Caps:These caps secure containers through a friction fit or a mechanical snap, providing a quick and often tamper-evident seal for various packaging types.
- Child-resistant Caps:Engineered with complex opening mechanisms, these closures prevent young children from accessing hazardous contents, primarily for pharmaceuticals and household chemicals.
Screw Caps hold installed capacity. Dispensing Caps are rotating up the share rankings.
Material:
The cost tier for plastic closure materials varies significantly based on polymer properties, processing requirements, and regulatory approvals for specific applications. Material selection impacts both performance and recyclability.
- Polypropylene:A versatile thermoplastic polymer, Polypropylene offers excellent chemical resistance, heat stability, and hinge properties, making it ideal for flip-top and screw caps. Its use is prevalent across food and beverage, and personal care packaging due to its balance of cost and performance.
- Polyethylene:Available in high-density (HDPE) and low-density (LDPE) forms, Polyethylene provides flexibility, impact resistance, and good moisture barrier properties. HDPE is extensively used for milk and juice bottle caps, while LDPE is favored for squeeze bottle closures, particularly in regions like Southeast Asia.
- PVC:Polyvinyl Chloride provides strong barrier properties and clarity, historically used for some tamper-evident seals and pharmaceutical closures.
- PET:Polyethylene Terephthalate is known for its clarity and gas barrier properties, primarily used in beverage bottles but less common for the caps themselves, though it appears in some specialty closures.
Polypropylene maintains a broad installed base. Polyethylene is expanding most quickly in beverage applications.
End User:
Application volume in the end-user segments is heavily skewed towards daily consumables, where high-speed bottling lines require consistent and reliable closure performance. Specialized sectors prioritize safety and product integrity.
- Food & Beverage:This segment represents the largest volume consumer of plastic caps and closures, encompassing water, carbonated soft drinks, dairy, and food containers. Regulatory mandates like the EU's tethered cap directive are reshaping designs for beverage closures.
- Pharmaceuticals:Closures for pharmaceutical products demand stringent quality, tamper-evidence, and child-resistant features to ensure product safety and regulatory compliance. The US FDA sets strict standards for food-contact materials in this sector.
- Cosmetics:This sector utilizes a wide array of dispensing and aesthetic closures, often prioritizing design and brand differentiation for lotions, creams, and makeup.
- Household Products:Closures for household chemicals and cleaning products require robust chemical resistance and often incorporate dispensing or child-resistant features.
The Food & Beverage sector drives significant volume. Pharmaceuticals are gaining share fastest in value-added closures.
Packaging Type:
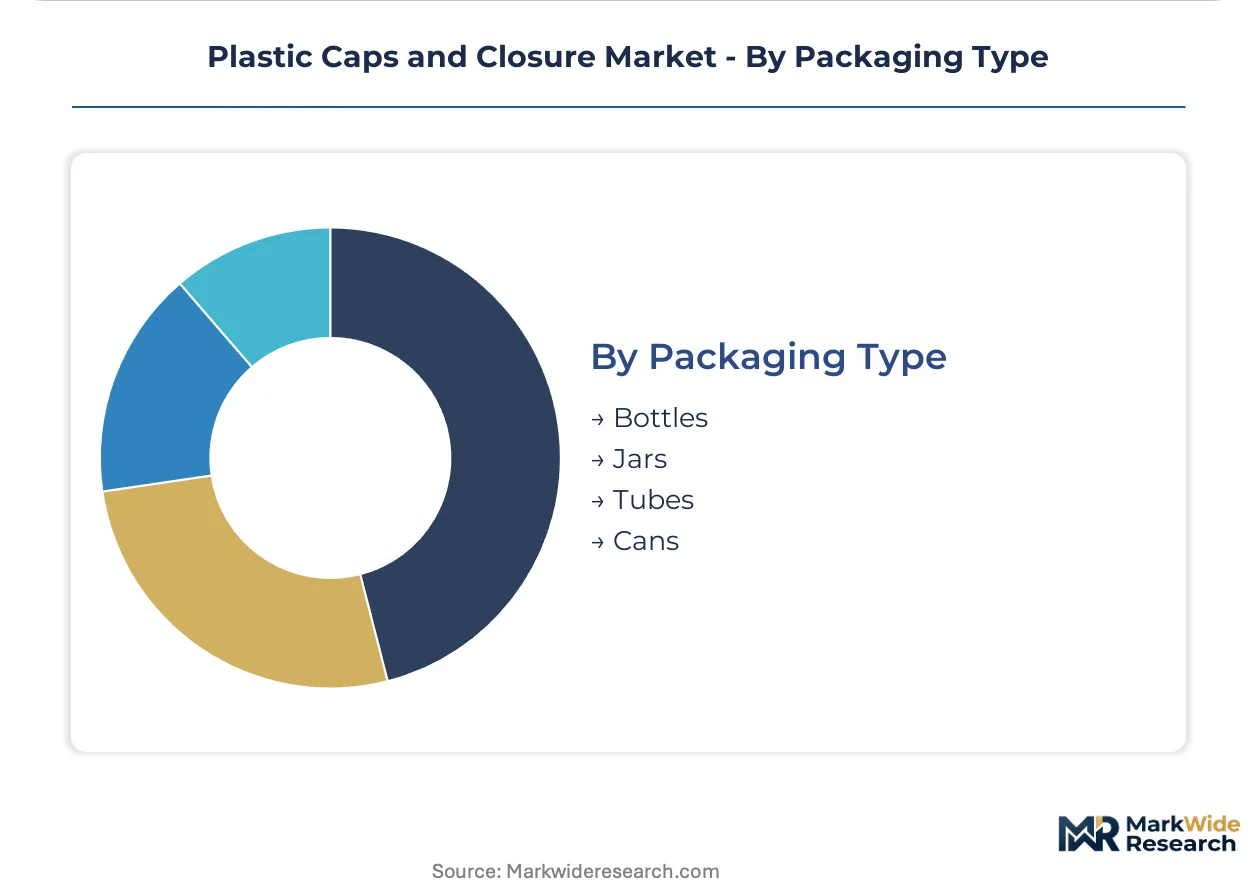
Customer type preferences for packaging formats influence closure design, with bottles dominating volume and other formats requiring specialized sealing solutions. E-commerce trends impact closure robustness.
- Bottles:The primary packaging format for liquids, bottles extensively use screw caps, sport caps, and dispensing closures across beverages, personal care, and pharmaceutical products. Demand in emerging economies like Indonesia and Vietnam significantly contributes to bottle closure volume.
- Jars:Typically used for solid or semi-solid products like food spreads and creams, jars commonly employ wide-mouth screw caps or snap-on lids. These closures prioritize ease of access and product freshness.
- Tubes:Flexible tubes for products like toothpaste, ointments, and cosmetics primarily use flip-top or screw caps designed for controlled dispensing.
- Cans:While less common for plastic caps, some specialized cans, particularly for powdered goods, may utilize plastic overcaps for reclosability or dispensing.
Bottles represent the largest installed capacity. Jars show a steepest expansion trajectory in specialty food applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The plastic caps and closure market exhibits varying demand elasticity across regions. Price sensitivity is higher for basic closures, while specialized, high-performance closures command premium pricing in pharmaceuticals. Regulatory frameworks significantly influence material choices and design innovation globally.
United States
Demand for plastic caps and closures in the United States is driven by the vast food and beverage sector and expanding e-commerce. The FDA sets stringent standards for food-contact materials. California's AB 793, mandating recycled content, influences material procurement in manufacturing hubs across the Midwest.
Germany
Germany's market is shaped by its advanced manufacturing base and beverage industry. The EU's Single-Use Plastics Directive mandates tethered caps, directly impacting product design. Major packaging producers in the Rhine-Ruhr region invest in new molding technologies to comply with these regulations.
China
China's substantial consumer goods market fuels significant volume demand for plastic caps, especially for food and household products. GB standards govern packaging safety and quality, creating a complex compliance landscape. Industrial clusters in the Yangtze River Delta focus on high-speed production for domestic consumption and export.
Indonesia
Indonesia experiences robust demand due to its expanding consumer base and growth of ready-to-drink beverages. The national food safety agency, BPOM, regulates packaging materials, ensuring product integrity. Packaging manufacturers in Jakarta and Surabaya are scaling operations to meet rising domestic consumption.
Vietnam
Vietnam's rapid economic development and urbanization contribute to rising demand for plastic caps across various sectors. The Ministry of Health's regulations on food packaging materials guide product development. Key industrial zones near Ho Chi Minh City are emerging as significant production centers for beverage and personal care closures.
Plastic Caps and Closure Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the plastic caps and closure market. The market structure exhibits a tiered consolidation, with large multinational corporations competing on scale and innovation, while smaller regional players focus on niche applications. Strategic archetypes include specialized technology providers, high-volume commodity producers, and integrated packaging solution providers. Competitive moves involve significant capacity expansion to meet beverage demand and strategic partnerships for sustainable material development.
At the scale-driven end, Berry Global Inc. exemplifies a multinational corporation leveraging an extensive manufacturing footprint for high-volume beverage markets, particularly within North America. Amcor plc, a global packaging leader, represents companies differentiating through portfolios of sustainable and recyclable closure solutions, addressing evolving environmental mandates. Closure Systems International Inc. occupies a position as a specialist in advanced sealing technologies for carbonated drinks and aseptic packaging, reflecting a focus on specific functional requirements and product integrity across diverse applications.
| Leading Market Players |
|---|
| Closure Systems International Inc. |
| Crown Holdings Inc. |
| Silgan Holdings Inc. |
| Guala Closures S.p.A |
| BERICAP Holding GmbH |
| Amcor plc |
| Berry Global Inc. |
| Sonoco Products Company |
| AptarGroup Inc. |
Cost & Logistics Intelligence
Typical lead times for custom closure molds often extend to several months, directly influencing the capital expenditure required and shaping pricing power for specialized designs. This dynamic compels manufacturers to balance long-term investment in tooling with immediate market demand for innovative solutions, particularly for regulated products.
Pricing Analysis
Specialized functionality, particularly for dispensing and child-resistant caps, commands premium pricing in the plastic caps and closure market. The dominant pricing structure is contract-based long-term offtake for high-volume commodity caps, while specialty closures utilize value-based models. Price differentiation stems from material quality grade and FDA/EU food-contact certification. Pricing softness in basic screw caps results from intense competition and raw material volatility. The food and beverage sector remains highly price-sensitive for standard closures, whereas pharmaceuticals prioritize performance over cost.
Supply Chain Analysis
Polymer resin inventory levels dictate production flexibility for plastic caps and closures, impacting manufacturers' ability to respond to demand shifts. Geographic supply concentration for plastic caps and closures centers on China, Germany, and the United States. Raw material dependencies include Polypropylene, Polyethylene, and various additives. A key structural risk is commodity price volatility for polymer feedstocks, directly linked to global oil and gas markets. Distribution runs through a mix of direct sales to large CPGs and a network of packaging distributors for smaller clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic caps and closure market represents a high-growth disruption, driven by the EU's tethered cap mandate which forces widespread redesign and investment.
For Market Incumbents: Fortify existing market share through strategic acquisitions of smaller, specialized molding firms to gain tethered cap intellectual property. Prioritize investments in advanced molding technologies for lightweighted and mono-material designs. This defends against the margin pressure from volatile polymer feedstocks and regulatory compliance costs. Expand production capacity in Southeast Asia to leverage growing beverage market demand.
For New Entrants and Emerging Players: Anchor in underserved regional markets like South America by offering advanced dispensing closures for cosmetics and household products. The most penetrable segment is specialized dispensing closures where brand differentiation is valued. A go-to-market angle involves partnering with local consumer goods brands to co-develop region-specific, convenient closure solutions. Focus on sustainable material options to meet evolving consumer preferences.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core plastic closure divisions. Long-term viability hinges on companies with strong intellectual property in tethered designs and robust recycled content supply chains. The acquisition target archetype includes mid-sized manufacturers specializing in advanced molding techniques or proprietary sealing technologies. A signal to watch is the increasing adoption rate of food-grade PCR in beverage closures.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Tethered Caps | Increases production scale to meet regulatory compliance, especially in European beverage markets. |
| PCR Supply Chain Development | Secures access to high-quality recycled polymers for meeting expanding content mandates. |
| Smart Closure Technology Integration | Adds brand protection and consumer engagement features, particularly for pharmaceuticals and spirits. |
| Mono-material Design R&D | Simplifies recycling processes and enhances product sustainability for food and beverage applications. |
| Geographic Market Penetration in APAC | Captures demand from expanding consumer bases in Indonesia and Vietnam for packaged goods. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory documents, corporate financial reports, and industry association publications. Primary interviews engaged procurement leads at CPG companies, R&D directors at closure manufacturers, packaging engineers, and sustainability officers. This approach involved extensive bottom-up and top-down triangulation to ensure data accuracy and market representativeness.
The market segmentation dimensions modeled include closure type, material, end-user application, and packaging format, alongside regional regulatory compliance. The analytical framework projects market growth across the analysis window, with CAGRs derived from historical trends and forward-looking industry forecasts. Key forecast inputs include polymer feedstock price projections and beverage consumption growth rates.
Material uncertainties — including unforeseen shifts in polymer feedstock prices or expanded regulatory scope — sit outside the modeled envelope. Forecasts reflect assumptions regarding technological adoption and consumer behavior. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Clic Loc Closure Market
Caps and Closures
Pharmaceutical Caps and Closures Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Heat Shrink Bands Market
Caps and Closures
Nordic Plastic Caps and Closures Market
Caps and Closures
Molded Fiber End Caps Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Spout Closures Market
Caps and Closures
Aerosol Caps Market
Caps and Closures
Overcaps Market
Caps and Closures
Poland Plastic Caps and Closures Market
Caps and Closures
Reverse Cap Bottles Market
Caps and Closures
Steel Ring Pull Caps Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Bag Closures Market
Caps and Closures
Aerosol Valves Market