
 Scanning and Migration Software Market | 2026-2036
Scanning and Migration Software Market Size, Share, and Industry Trends Forecast 2026-2036
Scanning and Migration Software Market Analytics
India is tilting toward cloud-native migration capacity as enterprises modernize legacy document infrastructure. Microsoft Corporation leverages its Azure stack to anchor hybrid deployment pipelines across South Asian financial institutions. IBM competes through Watson-powered OCR engines that sustain high-accuracy extraction rates for regulatory filings. Oracle Corporation dominates on-premise-to-cloud transitions among government clients with specialized data sovereignty tooling.
Scanning and migration software encompasses systems that digitize physical documents through optical capture and relocate structured or unstructured data across storage environments, typically achieving 99.5% character recognition accuracy in production deployments. Its primary commercial purpose is eliminating paper-dependent workflows while preserving audit trails and metadata integrity. Cloud migration tools lead product-type revenue as enterprises abandon tape and local server archives. SaaS deployment captures the fastest expansion within the deployment dimension, though hybrid configurations retain the deepest margin pools due to integration complexity. Healthcare end users drive disproportionate technology investment, particularly where AI-enhanced image processing reduces manual clinical record indexing.
FDA 21 CFR Part 11 shapes validation requirements for healthcare scanning systems, while the EU AI Act imposes conformity assessments on machine-learning classification engines processing sensitive records. India's BIS cloud standards and data localization directives further constrain cross-border migration architectures. Stakeholders must monitor whether emerging sovereign AI frameworks fragment interoperability standards before committing to single-vendor extraction pipelines.
Market Dynamics
Cloud migration pipelines are compressing deployment timelines as enterprises abandon tape archives, while algorithmic accountability mandates under the EU AI Act force revalidation of automated extraction workflows.
Growth Catalysts
- Federal data sovereignty mandates:Germany's industrial digitization programs accelerate enterprise migration projects requiring compliant archiving infrastructure.
- Healthcare digital archiving:Providers expand investments in AI-enhanced image processing to reduce manual clinical record indexing burdens.
- Optical character recognition advancement:Production deployments now sustain 99.5% accuracy rates, eliminating paper-dependent workflows across regulated industries.
Market Restraints
- Cross-border data localization:India's BIS cloud standards and directives constrain migration architectures requiring jurisdictional infrastructure duplication.
- Algorithmic conformity assessments:The EU AI Act imposes validation burdens on machine-learning classification engines processing sensitive records.
- Legacy system integration complexity:Hybrid configurations demand specialized tooling that extends deployment timelines and inflates professional services costs.
Strategic Opportunities
- South Asian financial modernization:Indian enterprises seek cloud-native capacity to replace legacy document infrastructure.
- SaaS deployment expansion:Subscription models capture fastest growth within deployment dimensions while reducing upfront capital barriers.
- ISO interoperability frameworks:Emerging sovereign AI standards create openings for vendors offering multi-jurisdictional extraction pipelines.
Industry Challenges
- Specialized engineering scarcity:Shortages of machine-learning engineers with document processing expertise delay product roadmaps.
- FDA 21 CFR Part 11 validation:Healthcare scanning systems require extensive documentation cycles that compress margin on fixed-price contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scanning and Migration Software Market |
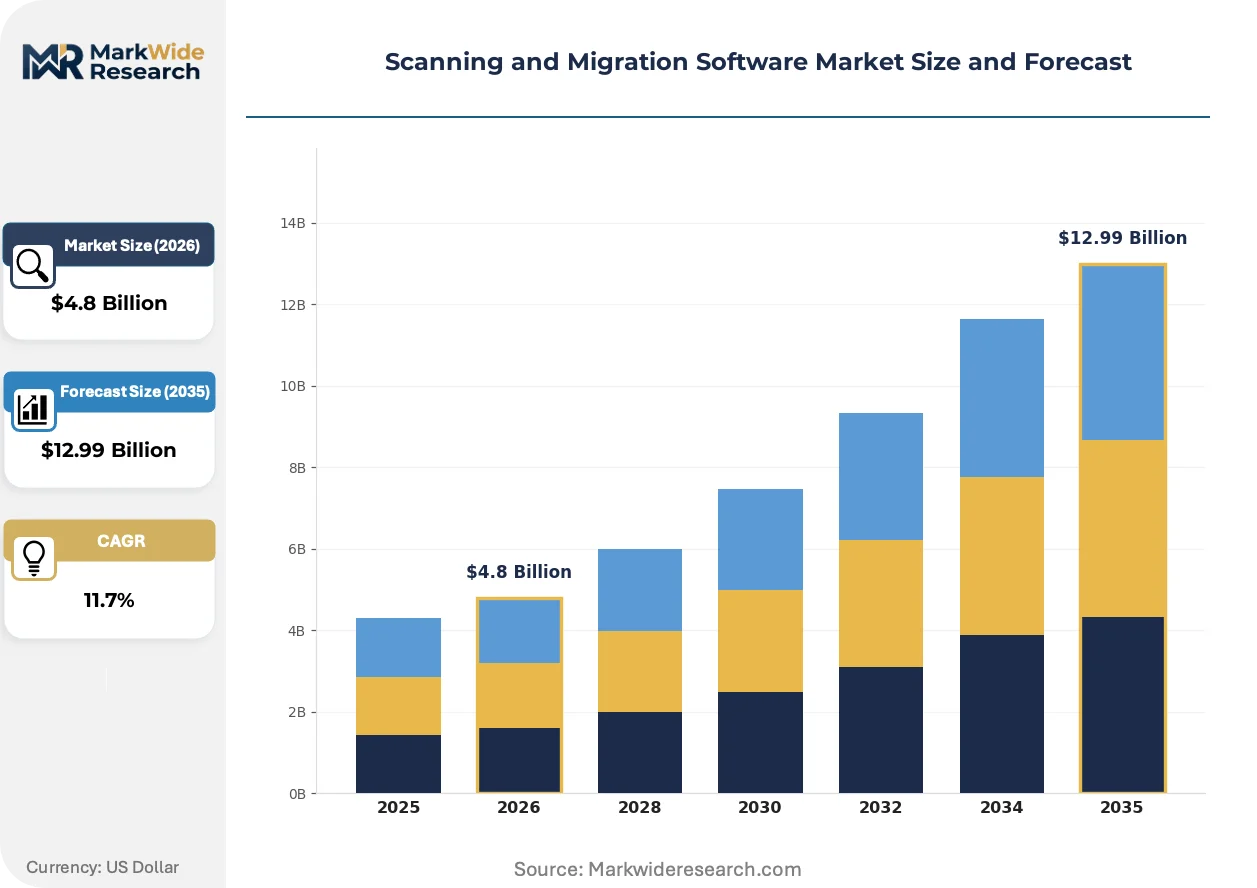
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Document Scanners, Image Capture Software, Cloud Migration Tools, Data Transfer Solutions Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Healthcare, Finance, Education, Government Technology: Optical Character Recognition, Artificial Intelligence, Machine Learning, Image Processing |
| Companies Covered | Microsoft Corporation, IBM, Amazon Web Services, Oracle Corporation, SAP SE, Informatica Corporation, SAS Institute, Attunity, Syncsort Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scanning and Migration Software Market Evolving Landscape
Automated document processing is undergoing architectural transformation as regulatory pressure and buyer sophistication reshape competitive requirements.
Intelligent document processing is migrating from rules-based extraction to transformer-based neural architectures that handle unstructured formats. Healthcare providers and financial institutions adopt these engines fastest where compliance documentation volumes strain manual capacity. This shift compresses pricing for traditional OCR licenses while expanding addressable market for contextual understanding tools.
The EU AI Act mandates conformity assessments for high-risk AI systems processing sensitive records including automated document classification. Industrial consequence includes mandatory bias testing and human oversight requirements that extend development cycles. Healthcare and legal sectors in Germany, France, and the Netherlands face earliest enforcement deadlines and are pre-emptively redesigning extraction pipelines.
Enterprise buyers now unbundle implementation services from software licensing to secure specialized systems integrators with vertical expertise. This fragments vendor control over deployment outcomes and elevates channel partner certification programs. German automotive suppliers and Indian public sector banks demonstrate this pattern most visibly, with procurement teams separating RFPs for platform selection from migration execution.
Scanning and Migration Software Market Segmentation
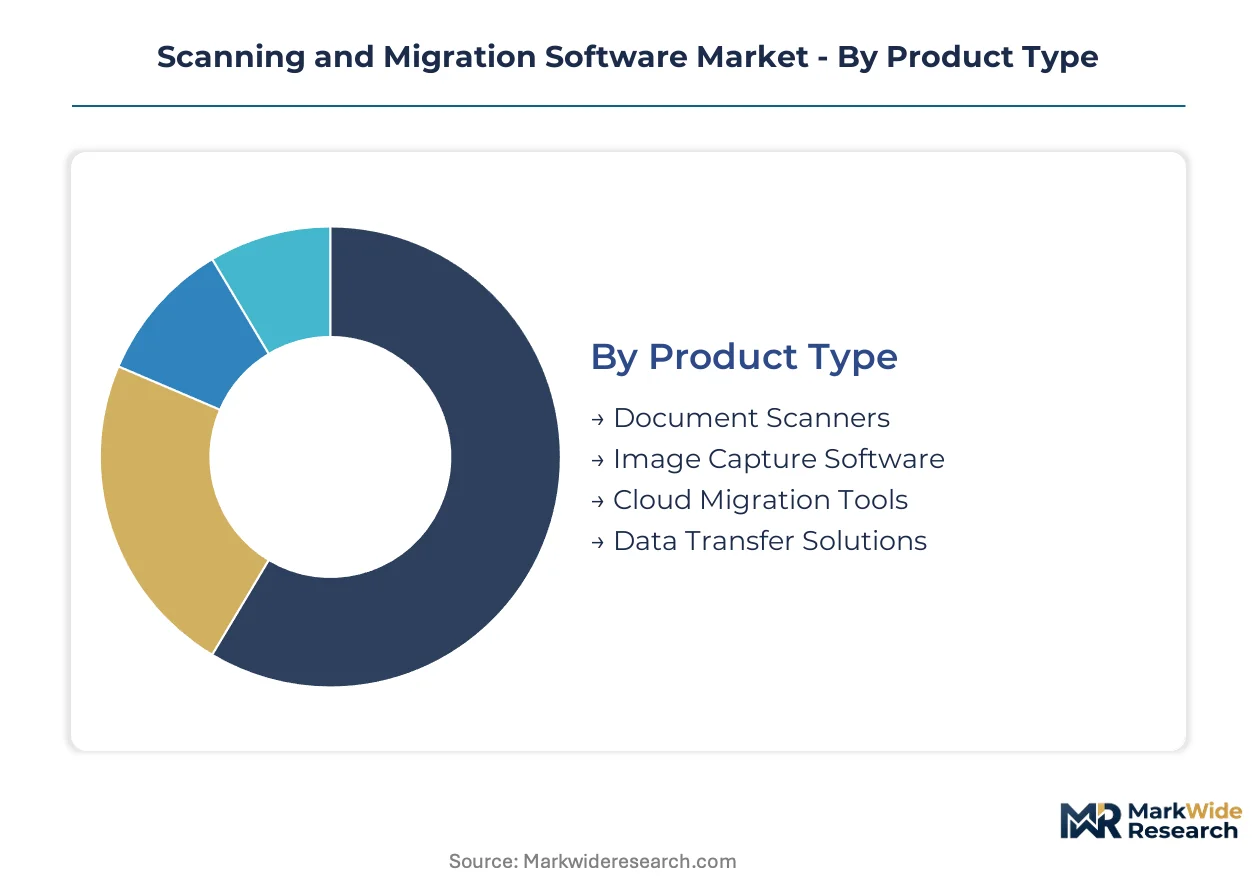
Segmentation in scanning and migration software reveals distinct service intensity profiles. Cloud migration pipelines demand continuous vendor engagement, while on-premise deployments concentrate professional services at implementation. Understanding these patterns shapes margin capture and account management resource allocation.
Product Type:
After-sales-service intensity varies sharply across product categories, with cloud migration tools requiring ongoing subscription support and scanner hardware demanding field maintenance contracts.
- Cloud Migration Tools:These platforms orchestrate data relocation across storage environments with automated integrity verification. Healthcare providers in Germany deploy these for clinical archive consolidation under federal data sovereignty mandates. The EU AI Act's conformity assessment requirements extend deployment timelines and inflate validation service attach rates.
- Document Scanners:Hardware capture devices with integrated feeding mechanisms and image enhancement processors. German automotive suppliers and Indian public sector banks maintain dense installed bases requiring preventive maintenance schedules and consumables replenishment programs.
- Image Capture Software:Applications processing scanner output through deskew, despeckle, and color correction algorithms.
- Data Transfer Solutions:Utilities enabling bulk movement across heterogeneous storage architectures with checksum validation.
By volume, Document Scanners leads. By growth pace, Cloud Migration Tools is ahead.
Deployment:
Cost tier stratification separates capital-intensive on-premise installations from operational expenditure SaaS models, with hybrid configurations commanding premium integration fees.
- SaaS:Subscription-delivered platforms with vendor-managed infrastructure and automatic feature updates. Indian financial institutions adopt these fastest as BIS cloud standards clarify compliance pathways, reducing upfront capital barriers for mid-tier banks.
- Hybrid:Architectures combining local processing nodes with cloud storage tiers, requiring specialized orchestration tooling. German government clients favor these for sensitive record retention, balancing accessibility against data localization requirements.
- Cloud-Based:Fully remote infrastructure with browser-accessible management consoles.
- On-Premise:Self-hosted software running on customer-managed servers with perpetual licensing.
SaaS captures the steepest expansion trajectory. Hybrid retains the deepest margin pools.
End User:
Application context determines extraction accuracy requirements and regulatory validation burdens, with healthcare and finance imposing the most stringent conformance standards.
- Healthcare:Clinical documentation systems requiring FDA 21 CFR Part 11 validation for electronic record integrity. German hospitals invest heavily in AI-enhanced image processing to reduce manual indexing of radiology and pathology reports.
- Finance:Regulatory filing pipelines demanding high-accuracy OCR for audit trail preservation. Indian banks modernize legacy document infrastructure under RBI data localization directives, creating concentrated demand for cloud-native migration capacity.
- Government:Public archive digitization with sovereignty and long-term preservation requirements.
- Education:Student record management and research material archiving with moderate compliance intensity.
Healthcare commands the highest technology investment per seat. Finance is expanding most quickly in absolute deployment terms.
Technology:
Technology maturity curves separate established optical recognition from emerging neural architectures, with implementation risk and performance differentiation concentrated in transition zones.
- Artificial Intelligence:Transformer-based neural engines enabling contextual understanding of unstructured document formats. Healthcare and legal sectors in Germany, France, and the Netherlands adopt these fastest as EU AI Act enforcement deadlines approach.
- Optical Character Recognition:Mature pattern-matching algorithms achieving 99.5% accuracy on structured text fields. Production deployments across regulated industries rely on these for standardized form processing with predictable validation documentation.
- Machine Learning:Classification models improving extraction accuracy through training on domain-specific document corpora.
- Image Processing:Pre-extraction enhancement routines including binarization, noise reduction, and geometric correction.
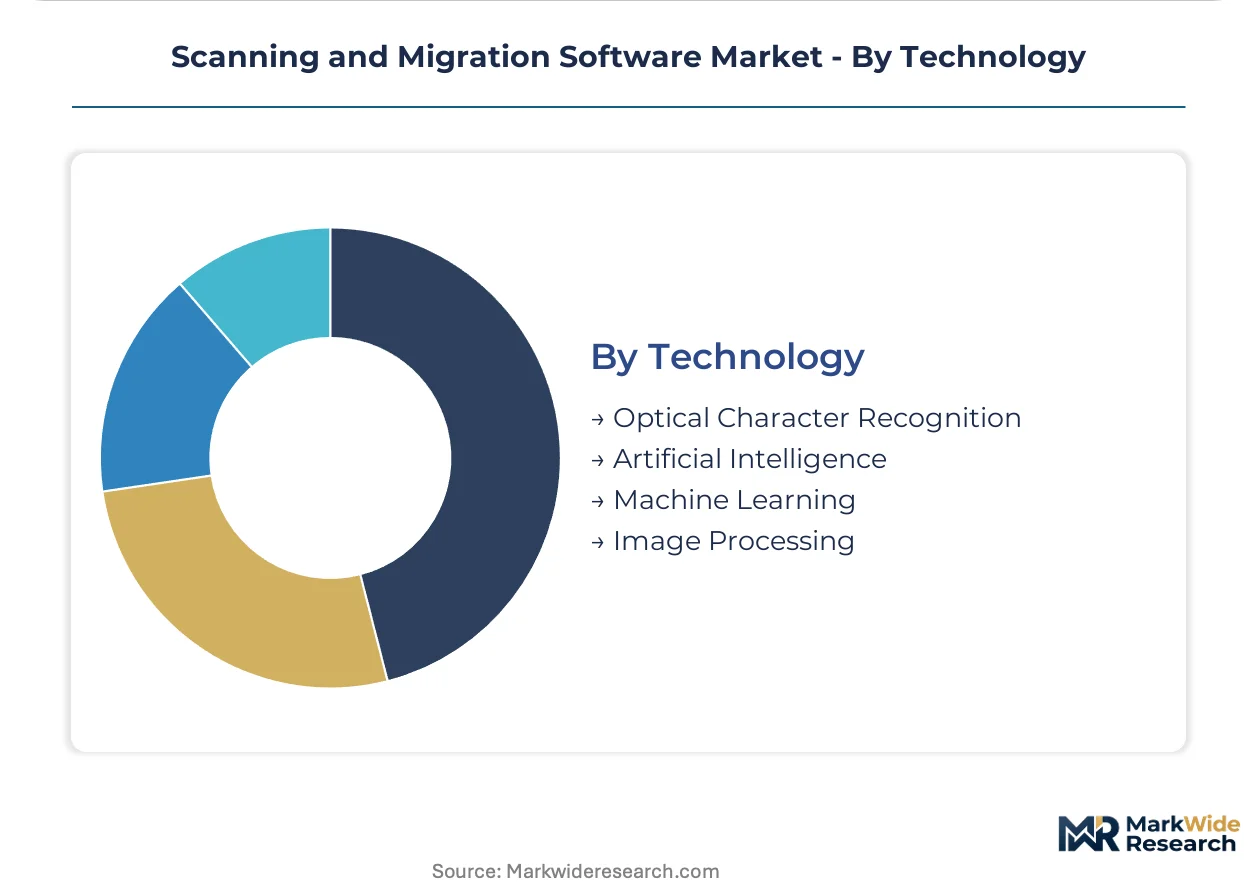
OCR dominates current installed value. AI is gaining share fastest among new procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor engineering capacity clusters in the United States, Germany, and India, with cloud infrastructure deployment tilting toward South Asian financial institutions and European sovereign data zones. Federal mandates and data localization regimes now determine procurement eligibility more than feature differentiation.
United States
Healthcare providers and defense contractors drive demand for FDA-validated scanning systems and CMMC-compliant migration pipelines. The FDA enforces 21 CFR Part 11 requirements for electronic record integrity in clinical trials and pharmaceutical manufacturing. Boston's medical research corridor and Washington DC's federal contracting ecosystem anchor concentrated deployment of high-assurance document processing infrastructure.
Germany
Industrial digitization programs and automotive supplier networks require compliant archiving under federal data sovereignty mandates. The EU AI Act imposes conformity assessments on machine-learning classification engines processing sensitive enterprise records. Bavaria's automotive engineering clusters and Baden-Württemberg's machinery manufacturers pre-emptively redesign extraction pipelines ahead of enforcement deadlines.
India
Public sector banks and insurance enterprises modernize legacy document infrastructure under RBI data localization directives. BIS cloud standards constrain cross-border migration architectures, forcing jurisdictional infrastructure duplication. Mumbai's financial district and Bengaluru's technology corridor concentrate cloud-native procurement decisions among mid-tier institutions shedding tape archives.
United Kingdom
Legal services and insurance sectors adopt transformer-based extraction engines to manage compliance documentation volumes. The Information Commissioner's Office enforces GDPR-aligned retention and deletion protocols for automated processing of personal data. London's financial and legal services cluster drives premium-tier demand for contextual understanding tools beyond traditional OCR accuracy thresholds.
Japan
Manufacturing conglomerates and government agencies pursue digitization of paper-based administrative workflows. METI promotes interoperability frameworks for legacy system integration in industrial supply chains. Tokyo's corporate headquarters and Osaka's precision manufacturing belt sustain demand for hybrid deployment models balancing accessibility against long-term preservation requirements.
Scanning and Migration Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in extraction engines and data orchestration modules. The vendor base separates into consolidated hyperscale cloud providers, specialized data management software houses, and legacy enterprise application vendors extending into migration tooling. Three archetypes dominate: infrastructure-anchored platforms, AI-enhanced extraction specialists, and database-centric migration utilities. Competitive moves concentrate on strategic partnerships with systems integrators and portfolio diversification into vertical-specific compliance modules.
Within the infrastructure-anchored tier, Microsoft Corporation and Amazon Web Services exemplify platform leverage through native cloud stack integration. IBM occupies a position among AI-enhanced extraction specialists, with Watson-branded capabilities representing the neural architecture transition in regulated document processing. Oracle Corporation anchors the database-centric archetype, extending relational infrastructure dominance into on-premise-to-cloud transition tooling for government and healthcare clients with stringent data sovereignty requirements.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM |
| Amazon Web Services |
| Oracle Corporation |
| SAP SE |
| Informatica Corporation |
| SAS Institute |
| Attunity |
| Syncsort Incorporated |
| Others |
Value Network & Pricing Analysis
Engineering talent pools in India and Germany anchor the highest-margin service tiers, concentrating value capture where AI-enhanced extraction engines require scarce machine-learning specialists with document processing expertise. Cloud infrastructure commoditization compresses SaaS pricing at the base tier while hybrid deployment complexity sustains premium professional services rates.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across European deployments, with conformity assessment costs elevating premium-tier validation services above standard cloud migration offerings. Three-tier pricing structure across enterprise, mid-market, and entry-level SaaS subscriptions separates buyers by compliance intensity and integration complexity. Pricing pressure stems from hyperscaler bundling of migration tools with base cloud contracts, eroding standalone vendor margins. Mid-tier financial institutions in India exhibit highest price sensitivity, while German government clients accept premium rates for data sovereignty guarantees.
Supply Chain Analysis
Extended payment terms from systems integrators to specialized OCR engine vendors characterize working capital dynamics in this sector. Component supply concentrates in the United States, Germany, and India, with transformer-based neural architectures drawing from NVIDIA GPU supply chains and open-source model repositories. Optical sensor hardware and high-volume scanner mechanics feed from Japanese and Taiwanese manufacturing bases. Single-source vulnerability sits with hyperscaler cloud infrastructure for SaaS delivery. Distribution runs through certified channel partners with vertical industry expertise, particularly in healthcare and automotive sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise digitization cycles are recovering from post-pandemic budget freezes, with federal data sovereignty mandates in Germany and RBI directives in India providing cyclical tailwinds for migration software procurement.
For Market Incumbents: Insulate recurring revenue streams by embedding AI-enhanced extraction engines deeply into client compliance workflows, creating switching costs against modular challengers. Pursue backward integration into specialized systems integrator networks to reclaim control over deployment outcomes fragmented by unbundled procurement patterns. Fortify certification moats around FDA 21 CFR Part 11 and EU AI Act validation documentation, as regulatory complexity accelerates buyer consolidation toward proven vendors. For New Entrants and Emerging Players: Pursue white-space opportunities in mid-tier Indian banks modernizing legacy document infrastructure under BIS cloud standards, where incumbent pricing exceeds budget constraints. Target legal services and insurance sectors in the United Kingdom adopting transformer-based extraction beyond traditional OCR accuracy thresholds. Lead with API-first architectures that unbundle from monolithic platforms, capturing developer mindshare through integration flexibility rather than feature parity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed data management software houses holding on-premise customer bases ripe for cloud transition revenue expansion. Long-term viability hinges on neural architecture differentiation as rules-based OCR commoditizes across the analysis window. Monitor EU AI Act enforcement velocity in Germany, France, and Netherlands as inflection indicator for compliance-driven consolidation appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure stack anchoring hybrid pipelines secures South Asian financial institution loyalty. |
| Acquisition of Specialist Firm | Watson-powered OCR engines sustain IBM's high-accuracy positioning for regulatory filing extraction. |
| Strategic Partnership | Oracle's government channel partnerships leverage data sovereignty tooling for on-premise-to-cloud transitions. |
| Product Launch | Transformer-based neural architectures displace rules-based extraction in German healthcare compliance documentation. |
| Geographic Expansion | SaaS deployment captures fastest expansion in Indian mid-tier banks shedding tape archives. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with enterprise IT procurement officers, platform engineers, channel integration specialists, and healthcare compliance directors; and secondary validation through SEC filings of listed software vendors, hyperscaler capex disclosures, FDA 510(k) clearance databases, and EU AI Act implementation guidance documents. Bottom-up segment sizing triangulated against top-down market envelope checks derived from cloud infrastructure spending correlations.
Forecast inputs considered deployment model transitions, vertical adoption intensity, and regulatory enforcement timelines across the projection horizon. Segmentation dimensions modeled include product type, deployment architecture, end-user industry, technology maturity, and regional data localization requirements. CAGRs derived from logistic adoption curves fitted to historical SaaS penetration patterns, with AI-enhanced processing capabilities and federal digitization program budgets as primary demand drivers.
Macroeconomic conditions sit as an overlay; deviation in enterprise IT capital expenditure cycles or cloud infrastructure investment pauses would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement schedules and technology substitution rates. Macroeconomic contraction, accelerated sovereign AI framework fragmentation, or breakthrough open-source model availability would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Calorie Metering Software Market
Software & Services
Cloud-Based Payroll Software Market
Software & Services
Digital Painting Software Market
Software & Services
Stone Analysis Software Market
Software & Services
Mobile Enterprise Application Development Platform Market
Software & Services
Performance Management Software Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
Desktop Hypervisor Market
Software & Services
Global Construction Management Software Market
Software & Services
Runtime Software Market
Software & Services
Smartphone OS Market
Software & Services
Microsoft Office 365 Integration Services Market
Software & Services
Global Ad Server Software Market
Software & Services
Lab Automation Software Market
Software & Services
Global Demand Planning Software Market
Software & Services
Metal Recycling Software Market