
 Global Ad Server Software Market | 2026-2036
Global Ad Server Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ad Server Software Market Foresight
Modular bundling of creative optimization with core ad serving is broadening buyer choice across mid-market agencies and independent publishers. Google leverages its search and video ecosystem to sustain dominance in managed hosting infrastructure. Amazon Web Services anchors its position through cloud-native deployment options that integrate with retail media networks.
Ad server software is a centralized platform that stores, delivers, and tracks digital advertisements across websites, mobile applications, and connected devices, operating through real-time decisioning engines that select creative assets based on targeting rules, frequency caps, and bid responses. Its primary commercial purpose is to ensure accurate impression counting, brand safety enforcement, and revenue attribution for publishers and advertisers. Cloud-Based deployment leads the solution type landscape because elastic scaling matches the traffic volatility of video advertising and mobile advertising use cases. Self-Serve platforms occupy the fastest-expanding margin pool as e-commerce and technology providers seek direct control over campaign workflows without intermediary fees.
The Federal Trade Commission in the United States, the European Commission through GDPR enforcement, and the Information Commissioner's Office in the United Kingdom collectively shape demand by mandating transparent data processing and consent audit trails within ad serving infrastructure. These frameworks compel vendors to embed privacy-by-design architectures that limit cross-site tracking while preserving addressability. Stakeholders must monitor how regulatory fragmentation across national data protection authorities affects interoperability standards and client retention costs.
Market Dynamics
First-party data migration is compressing third-party cookie dependencies across publisher tech stacks, forcing infrastructure rebuilds that favor cloud-native deployment models with embedded consent management layers.
Growth Catalysts
- GDPR Consent Frameworks:European enforcement mandates are accelerating vendor investment in privacy-by-design architectures that preserve addressability while limiting cross-site tracking capabilities.
- Retail Media Networks:E-commerce platforms are deploying self-serve ad serving tools to monetize first-party shopper data through direct-sold inventory without intermediary fees.
- Connected TV Infrastructure:Video advertising traffic volatility is pulling elastic scaling demand toward cloud-based deployment models that handle programmatic auction spikes.
Market Restraints
- Input Cost Concentration:Cloud compute and storage pricing volatility from hyperscaler concentration in the United States creates margin pressure for mid-market SaaS providers.
- Technical Addressability Limits:Apple's Intelligent Tracking Prevention and similar browser-level restrictions constrain frequency capping accuracy across Safari's mobile and desktop user base.
- Regulatory Fragmentation:Divergent national data protection authority interpretations of lawful basis for processing create compliance overhead across multi-jurisdictional deployments.
Strategic Opportunities
- India Digital Infrastructure:Underpenetrated publisher markets present whitespace for localized ad serving platforms that integrate with domestic payment rails and regional language creative support.
- Clean Room Convergence:Privacy-preserving data collaboration between advertisers and publishers is opening integration opportunities with identity resolution and measurement vendors.
- Green Ad Serving:EU Green Deal alignment is creating procurement preference for vendors with carbon-neutral cloud operations and impression-level emissions reporting.
Industry Challenges
- Identity Resolution Engineering:Scarcity of engineers with expertise in probabilistic matching, differential privacy, and federated learning is constraining product roadmap velocity.
- Legacy Integration Friction:Publisher migration from on-premise ad servers to cloud-native stacks requires sustained professional services investment and data pipeline reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ad Server Software Market |
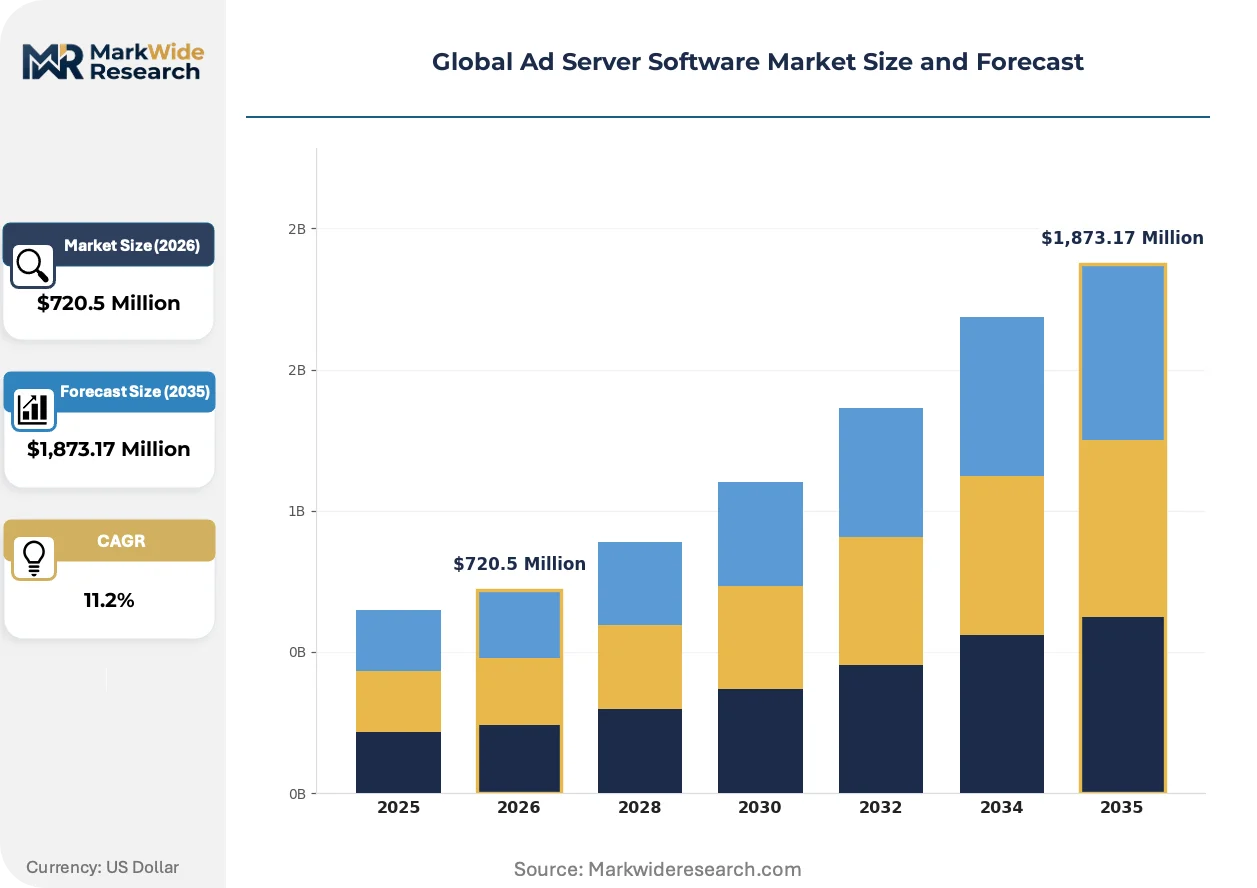
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,873.17 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Managed Hosting Solution Type: Self-Serve, Managed Service, Programmatic, Analytics, Data Management, Creative Optimization Use Case: Performance Marketing, Brand Awareness, Retargeting, Lead Generation, Video Advertising, Mobile Advertising End User Industry: Publishing, Agencies, E-Commerce, Technology Providers, Telecommunications, Education |
| Companies Covered | Google, Amazon Web Services, Microsoft, Magnite, PubMatic, OpenX, Adform, The Trade Desk, Adobe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ad Server Software Market Shifts & Advancements
Real-time decisioning architectures are undergoing fundamental reconstruction as identity signals fragment and measurement methodologies pivot toward aggregated attribution models that preserve user privacy.
Server-side ad insertion is rewriting how video inventory is monetized across connected television and mobile streaming applications. Premium publishers are adopting SSAI to bypass client-side ad blockers and improve creative quality through transcoding control. This technology is compressing the addressable gap between linear and digital video buying workflows.
GDPR enforcement actions from the European Commission and national data protection authorities are mandating granular consent audit trails within ad serving infrastructure. Vendors must now embed technical measures that demonstrate lawful basis for each impression served. Mid-market publishers in Germany and France are prioritizing vendors with pre-certified compliance documentation to accelerate procurement cycles.
Direct-sold campaign management is displacing programmatic-only workflows among independent publishers seeking margin recovery. Self-serve interfaces that bypass agency trading desks are capturing budget from mid-market advertisers with simplified creative upload and reporting tools. This pattern is most visible in the United Kingdom and Nordic markets where publisher sales teams are rebuilding around platform-enabled customer success models.
Global Ad Server Software Market Segmentation
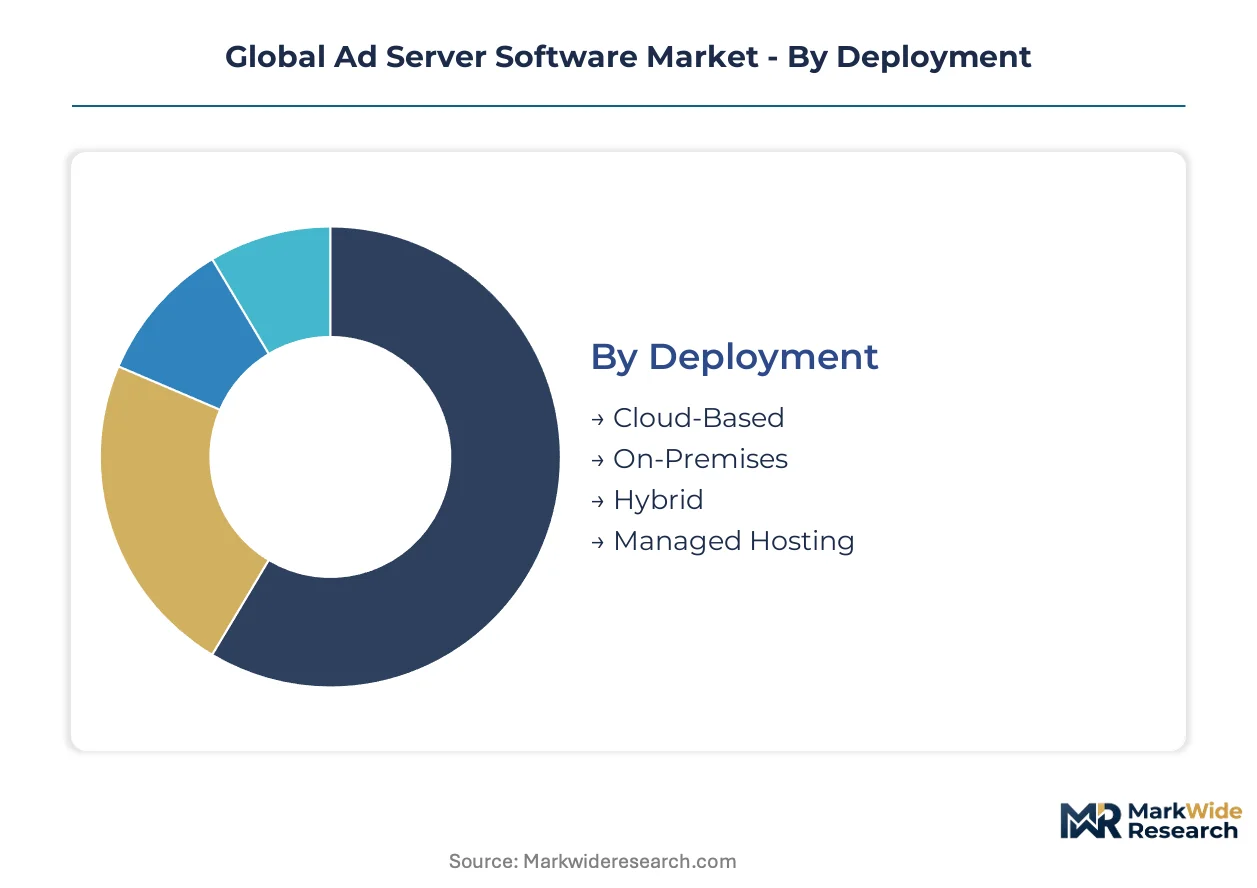
Ad server software procurement patterns diverge sharply across deployment models, solution architectures, and end-user sophistication. Buyers weight elastic scaling needs against data sovereignty requirements, while regulatory pressure reshapes which segments absorb compliance investment.
Deployment:
Cloud compute certifications from AWS, Azure, and Google Cloud Platform impose distinct audit burdens that segment buyers by risk tolerance and data residency mandates.
- Cloud-Based:Elastic infrastructure auto-scales impression volumes during programmatic auction spikes without capital expenditure. Retail media networks in the United States and Germany are consolidating here to handle first-party data traffic volatility while embedding GDPR consent management layers.
- On-Premises:Dedicated hardware installations satisfy national data localization laws in China, Russia, and Saudi Arabia where cross-border transfer restrictions apply. State-owned publishers and defense-adjacent media buyers absorb higher total cost of ownership to retain physical control over impression logs and user identifiers.
- Hybrid:Split architectures route sensitive identity data through private infrastructure while pushing creative delivery to public cloud edge nodes. Japanese broadcasters and French premium publishers deploy this model to balance latency optimization with CNIL audit readiness.
- Managed Hosting:Third-party data center operators handle infrastructure maintenance under service-level agreements that specify uptime thresholds and geographic redundancy. Mid-market agencies in the United Kingdom and Australia select this path to avoid hiring specialized DevOps engineering talent.
Cloud-Based deployment sits at the top of the volume ranking, with Hybrid climbing the fastest as sovereignty-conscious buyers seek compromise architectures.
Solution Type:
Margin structure separates segments where buyers pay for workflow autonomy versus those purchasing operational offload to vendor professional services.
- Self-Serve:Browser-based interfaces enable direct campaign setup, creative trafficking, and reporting without intermediary touchpoints. E-commerce platforms in India and Southeast Asia are expanding here to monetize retail media inventory without agency trading desk fees.
- Managed Service:Vendor teams handle trafficking, optimization, and troubleshooting under recurring fee structures. Legacy newspaper groups in Italy and Spain rely on this model where internal digital expertise remains thin.
- Programmatic:Real-time bidding integration and header bidding wrapper management form the technical core. Demand concentrates among programmatic-native publishers in the United States and United Kingdom upgrading to first-party data-enabled auction mechanics.
- Analytics:Cross-channel attribution and audience segmentation tools layer measurement onto core serving infrastructure. Brand advertisers in Germany and France prioritize vendors with pre-built GDPR-compliant reporting pipelines.
- Data Management:First-party data onboarding, identity resolution, and segment building capabilities integrate with serving decisions. Telecommunications carriers in South Korea and Brazil deploy these tools to activate subscriber data for advertising.
- Creative Optimization:Dynamic creative assembly and multivariate testing engines personalize ad experiences at impression time. Performance marketing specialists in the United States and Australia absorb premium pricing for conversion lift verification.
Programmatic solutions command the largest revenue base, though Self-Serve platforms are expanding most quickly as direct-sold inventory management displaces intermediary-dependent workflows.
Use Case:
Traffic pattern volatility and measurement methodology requirements segment buyers by technical infrastructure needs and creative format complexity.
- Performance Marketing:Conversion tracking and return-on-ad-spend optimization drive real-time bidding algorithms. Direct-to-consumer brands in the United States and United Kingdom anchor demand for attributable downstream event measurement.
- Brand Awareness:Reach and frequency management across premium publisher environments prioritizes viewability verification. Consumer packaged goods advertisers in Germany and France invest here to align digital spending with offline sales lift studies.
- Retargeting:Site visitor segmentation and sequential messaging workflows depend on persistent identity resolution. E-commerce marketplaces in India and Brazil face headwinds from browser-level tracking restrictions on Safari and Firefox.
- Lead Generation:Form completion tracking and cost-per-lead optimization suit business-to-business verticals. Technology vendors and financial services advertisers in the United States and Australia concentrate procurement here.
- Video Advertising:Server-side ad insertion and transcoding pipelines handle connected television and mobile streaming inventory. Broadcasters in Japan and South Korea are rebuilding infrastructure to monetize over-the-top viewership migration.
- Mobile Advertising:In-app SDK integration and mobile-specific creative formats address app developer monetization. Gaming publishers and utility app developers in Southeast Asia and Latin America drive SDK adoption rates.
Video Advertising leads by infrastructure investment volume, while Performance Marketing gains share fastest as attribution capabilities mature beyond last-click measurement.
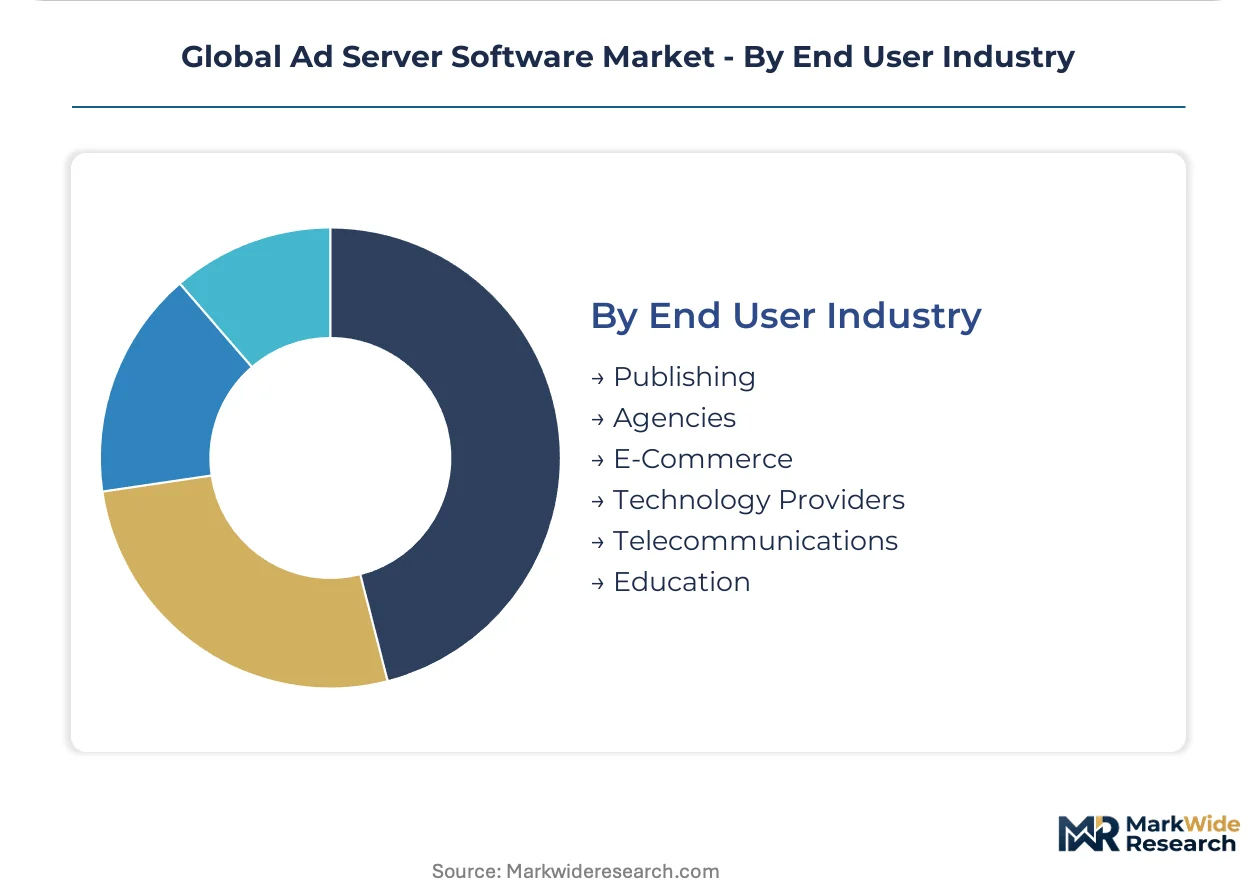
End User Industry:
Buyer sophistication and in-house technical capacity separate segments, with compliance surface area expanding fastest among data-rich verticals.
- Publishing:Multi-channel inventory monetization across web, mobile, and connected television environments. National newspaper groups in the United States, United Kingdom, and Germany are consolidating onto unified stacks to reduce vendor fragmentation.
- Agencies:Cross-client campaign management and consolidated billing workflows demand multi-tenant architectures. Holding company media agencies in France and Australia prioritize platforms with interoperable identity graphs.
- E-Commerce:Retail media network expansion and first-party shopper data activation create self-serve infrastructure demand. Marketplaces in India, Brazil, and Southeast Asia are building captive ad tech stacks to compete with Amazon and Alibaba.
- Technology Providers:Embedded advertising in software products and developer platforms requires lightweight SDK deployment. Productivity tool vendors and communication platforms in the United States and Israel integrate serving infrastructure as ancillary revenue streams.
- Telecommunications:Subscriber data monetization and network-level advertising insertion leverage carrier-scale identity graphs. Operators in South Korea, Japan, and Brazil are deploying privacy-preserving targeting using differential privacy techniques.
- Education:Learning management system integration and student privacy compliance constrain vendor selection. EdTech platforms in the United States and United Kingdom face COPPA and GDPR-K enforcement that limits data retention periods.
Publishing retains the deepest installed base, though E-Commerce is climbing fastest as retail media networks displace traditional display budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ad serving infrastructure originated in Silicon Valley during the late 1990s dot-com era, with early platforms scaling through venture capital before cloud computing transformed deployment economics worldwide.
United States
Major publishers and programmatic platforms are upgrading infrastructure to support first-party data strategies, driving consolidation around cloud-native stacks. The Federal Trade Commission enforces transparent data processing standards that shape vendor procurement decisions. New York and San Francisco anchor the densest concentration of ad tech engineering talent and venture funding flows.
Germany
Mid-market publishers prioritize vendors with pre-certified GDPR compliance documentation to accelerate procurement cycles. The Federal Cartel Office and national data protection authority interpretations create stringent audit requirements for impression-level consent tracking. Berlin and Munich host the largest clusters of privacy-by-design engineering teams serving European media buyers.
United Kingdom
Independent publishers are rebuilding sales teams around platform-enabled customer success models for direct-sold campaign management. The Information Commissioner's Office mandates granular consent audit trails within serving infrastructure. London concentrates holding company media agencies demanding multi-tenant architectures for cross-client workflow management.
Japan
Broadcasters are rebuilding infrastructure to monetize over-the-top viewership migration through server-side ad insertion pipelines. The Ministry of Internal Affairs and Communications oversees telecommunications carriers deploying privacy-preserving targeting using differential privacy techniques. Tokyo and Osaka anchor premium publisher technology investment for connected television inventory.
India
E-commerce marketplaces are building captive ad tech stacks to compete with multinational retail media networks. The Telecom Regulatory Authority of India and evolving data protection frameworks reshape how domestic platforms handle user identity and consent management. Bangalore and Mumbai concentrate engineering talent for localized platforms integrating with domestic payment rails and regional language creative support.
Global Ad Server Software Market Competitive Landscape
The competitive structure tilts toward hyperscaler dominance with specialized programmatic platforms occupying distinct functional niches. Cloud infrastructure providers leverage elastic scaling capabilities to anchor managed hosting segments, while independent software vendors compete on workflow autonomy and privacy specialization. Two strategic archetypes predominate: vertically integrated cloud ecosystems and modular best-of-breed stacks. Competitive moves concentrate on API integration partnerships and geographic data center expansion to satisfy data residency mandates.
Within the cloud-native tier, Google and Amazon Web Services represent the integrated ecosystem archetype, leveraging search, video, and retail media network adjacencies to sustain infrastructure dominance. Magnite and PubMatic exemplify the independent programmatic specialist archetype, occupying positions focused on header bidding optimization and sell-side platform interoperability. These four entities collectively illustrate the market's bifurcation between scale-driven consolidation and workflow-specific differentiation.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| Magnite |
| PubMatic |
| OpenX |
| Adform |
| The Trade Desk |
| Adobe |
| Others |
Supply & Pricing Matrix
Server-side ad insertion and cloud-native deployment architectures are compressing legacy on-premise cost structures while concentrating infrastructure procurement power among three hyperscalers. This technology transition simultaneously reduces capital expenditure barriers for mid-market publishers and tightens margin capture for independent software vendors competing against vertically integrated cloud ecosystems.
Pricing Analysis
SaaS subscription tiers anchored to impression volume bands dominate commercial structures, with premium pricing attaching to embedded consent management and real-time optimization modules. Price differentiation rests on GDPR certification depth and multi-cloud deployment flexibility rather than core serving throughput alone. Pricing pressure stems from hyperscaler concentration in the United States compressing independent vendor margins through bundled infrastructure offers. Mid-market agencies exhibit highest price sensitivity, while telecommunications carriers absorbing subscriber data monetization projects show lowest elasticity.
Supply Chain Analysis
Engineering talent scarcity in Bangalore and Berlin constrains roadmap velocity for privacy-preserving architectures and federated learning implementations. Cloud compute supply concentrates in the United States, Ireland, and Singapore, with raw material dependencies spanning semiconductor fabrication in Taiwan, memory modules from South Korea, and specialized networking hardware from Japan. Supply chain risk centers on single-source vulnerability for advanced GPU clusters essential to real-time decisioning engines. Distribution runs through direct enterprise sales teams and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
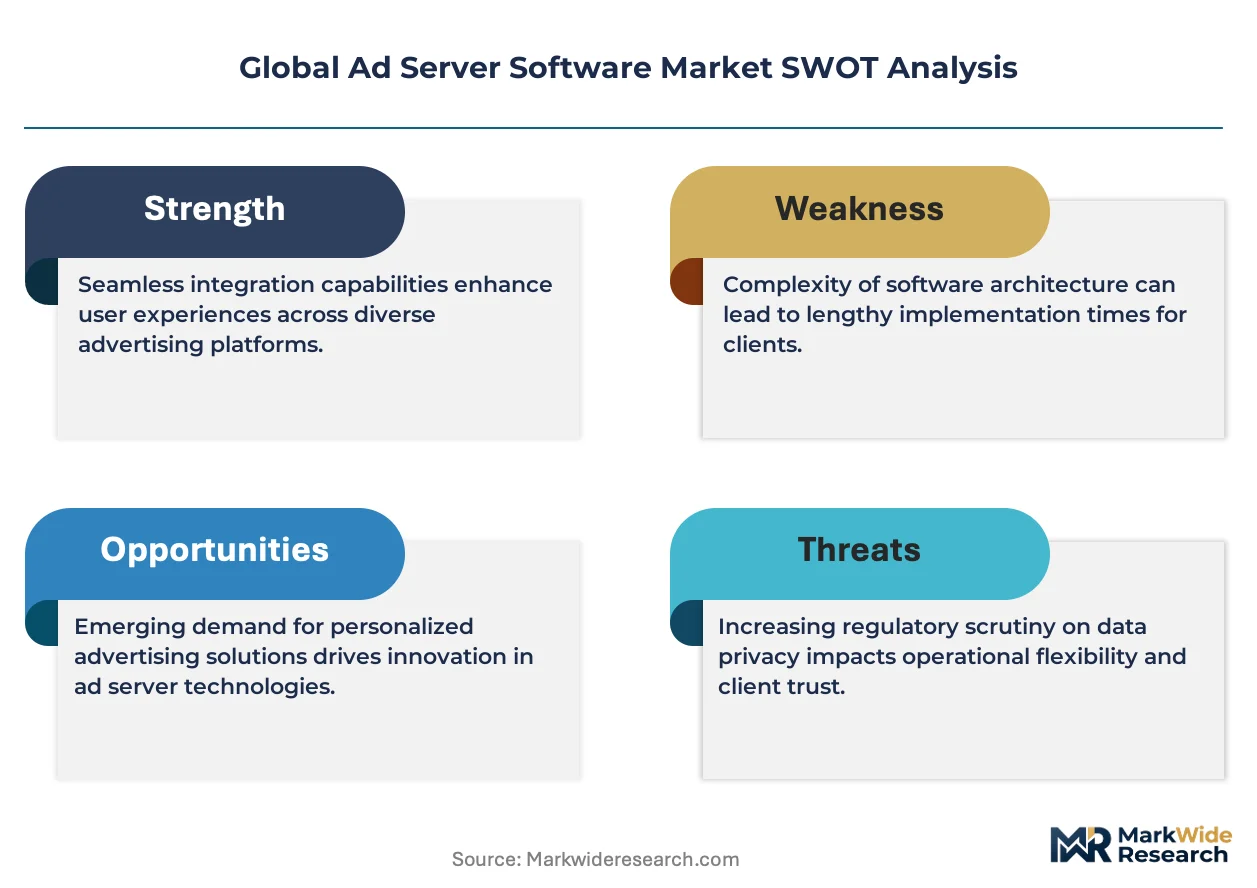
This market functions as a geographic-arbitrage play where engineering talent costs in India and regulatory compliance burdens in Germany create divergent vendor economics for equivalent technical capabilities.
For Market Incumbents: Hedge against hyperscaler bundling by deepening API integration partnerships with retail media networks and telecommunications carriers. Invest in CNIL and ICO pre-certification documentation to accelerate European procurement cycles. Prioritize backward integration into consent management layers to defend margin position against modular best-of-breed competitors.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in self-serve platforms creates entry space for localized solutions in underpenetrated Indian and Southeast Asian publisher markets. Target e-commerce marketplaces seeking direct-sold inventory control without agency trading desk intermediation. Lead with domestic payment rail integration and regional language creative support as differentiation wedge.
For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid deployment specialists with proven CNIL audit readiness and Japanese broadcaster relationships. Long-term viability favors vendors with differential privacy engineering teams and clean room integration capabilities. Watch for inflection where Apple's Intelligent Tracking Prevention expansion triggers accelerated first-party data infrastructure replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API partnerships with retail media networks reduce customer acquisition costs for independent vendors. |
| Geographic Expansion | Data center buildout in India satisfies TRAI data localization mandates for domestic e-commerce platforms. |
| Acquisition of Specialist Firm | Differential privacy engineering teams address telecommunications carrier demand for subscriber data monetization. |
| Product Launch | Server-side ad insertion modules capture connected television infrastructure budgets from Japanese broadcasters. |
| Strategic Partnership | Clean room integrations with identity resolution vendors open privacy-preserving measurement revenue streams. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ad tech CTOs, publisher revenue operations directors, agency trading desk heads, and privacy engineering leads with secondary validation against SEC filings, hyperscaler capex disclosures, and national data protection authority enforcement databases. Bottom-up impression volume modeling and top-down cloud infrastructure spend analysis were triangulated to anchor market sizing.
Segment-weighted forecasting applied deployment model, solution type, and end-user industry dimensions across the projection horizon, with CAGRs derived from elasticity-adjusted adoption curves and infrastructure replacement cycle analysis. First-party data migration velocity and browser-level tracking restriction expansion served as scenario-weighting inputs.
Caveats apply where GDPR enforcement intensity or hyperscaler pricing volatility could materially shift the outlook. Forecasts reflect assumptions about consent framework standardization and identity signal persistence. Material deviation in regulatory fragmentation patterns or cloud compute cost trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Organizational Change Management Software Market
Software & Services
Parks and Playground Inspection Software Market
Software & Services
Lease Accounting and Management Software Market
Software & Services
Global Embedded Hypervisor Software Market
Software & Services
Account-Based Advertising Software Market
Software & Services
Laser Engraving Software Market
Software & Services
Africa Financial Services Software Market
Software & Services
Web Framework Software Market
Software & Services
Fitness App Market
Software & Services
Global Recipe Apps Market
Software & Services
Global Healthcare Contract Management Software Market
Software & Services
Exploration and Production Accounting System Software Market
Software & Services
Global Investor Relationship Management Software Market
Software & Services
Global Municipal Software Market
Software & Services
Software Market
Software & Services
Royalty Management Software and Services Market