
 Digital Painting Software Market | 2026-2036
Digital Painting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Painting Software Market Insights
The capability gap between cloud-native architectures and legacy desktop engines is unwinding competitive dynamics across the sector. Adobe Inc. leverages its Creative Cloud infrastructure to anchor recurring revenue from professional studios. Corel Corporation sustains its position through perpetual-license loyalty among traditional illustrators. Procreate dominates the tablet-native segment with touch-optimized workflows that sidestep desktop complexity.
Digital painting software comprises raster and vector-based applications engineered for stylus-driven image creation, typically supporting pressure sensitivity, layer compositing, and color-space management for commercial art production. Desktop Applications retain the largest installed base among professional artists, while Mobile Apps capture the fastest expansion as iPad Pro and Android tablet penetration deepens among hobbyists and field illustrators. The Subscription license model now generates the most predictable revenue streams, though One-Time Purchase options preserve margin pools among cost-sensitive freelancers and educational institutions.
The Federal Trade Commission scrutinizes subscription billing practices in the United States, while the EU Digital Services Act imposes transparency obligations on platform-distributed creative tools. Japan's Ministry of Economy, Trade and Industry promotes software export standards that ease cross-border licensing for domestic developers. Stakeholders must monitor how cloud-collaboration feature mandates from European data regulators reshape product architecture priorities.
Market Dynamics
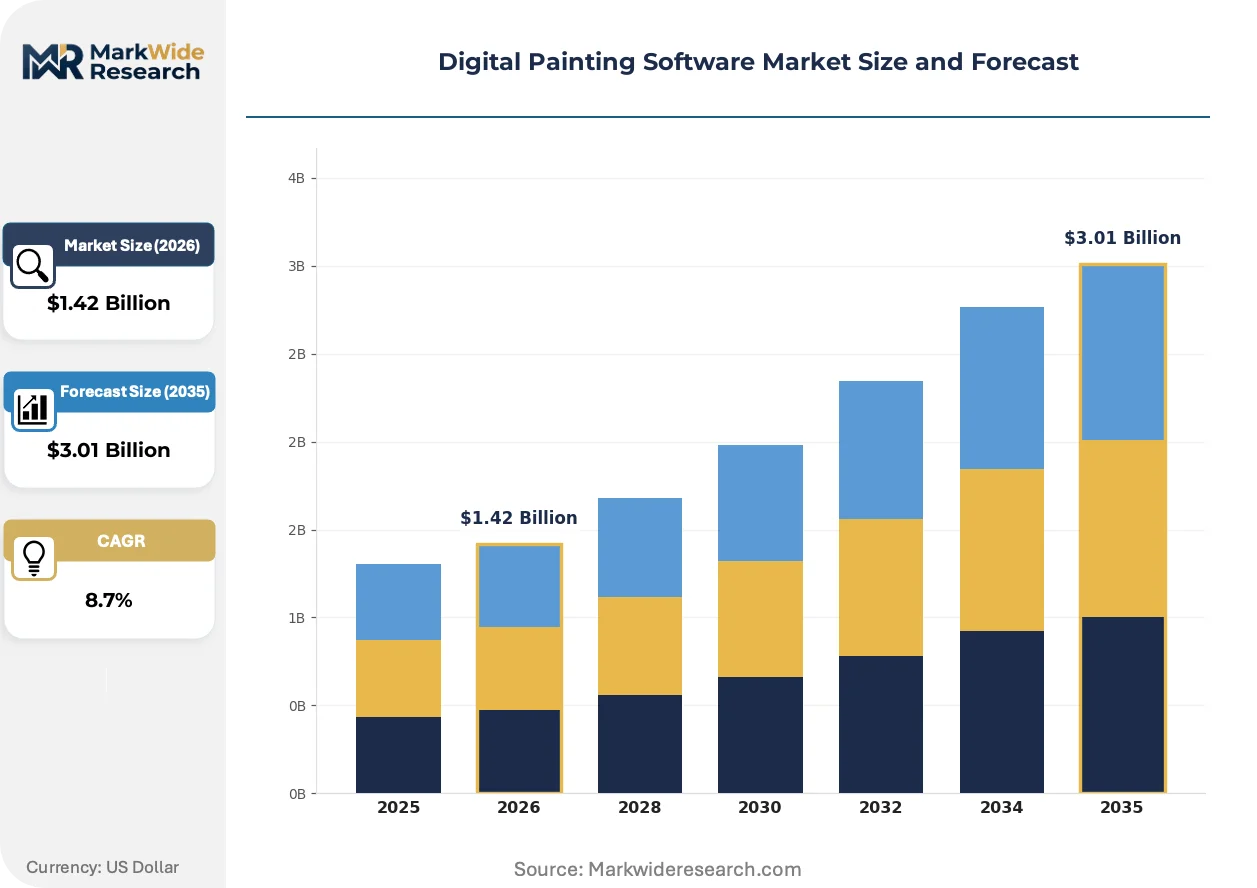
The migration from perpetual-license desktop suites to cloud-native subscription architectures is restructuring revenue predictability and vendor lock-in mechanics across the digital painting software sector. This shift compresses customer acquisition costs while extending lifetime value horizons for platform providers.
Growth Catalysts
- Cloud Rendering Mandates:The EU Digital Services Act imposes transparency obligations on platform-distributed creative tools, accelerating infrastructure upgrades that enable real-time collaborative workflows among distributed art teams.
- Pressure-Sensitive Stylus Standardization:Hardware manufacturers in South Korea and Japan are converging on unified pressure-curve protocols, reducing compatibility fragmentation that previously deterred professional adoption.
- Freelance Illustration Economy Expansion:Independent game studios in Germany and the United States are expanding headless art departments, creating concentrated demand for seat-flexible licensing models.
Market Restraints
- Subscription Fatigue Accumulation:The Federal Trade Commission's heightened scrutiny of auto-renewal billing practices in the United States introduces compliance friction and churn risk for recurring-revenue dependent vendors.
- Input Cost Volatility in Cloud Compute:Energy-intensive GPU rendering services face pricing pressure from datacenter electricity tariffs, compressing margins for cloud-integrated feature tiers.
- Legacy File Format Entrenchment:Proprietary PSD and AI formats anchor workflow continuity, creating switching costs that slow migration to alternative platforms despite feature parity.
Strategic Opportunities
- Educational Institution Underpenetration:France's vocational art schools and community colleges in the United States remain predominantly served by discounted legacy suites, presenting white space for purpose-built academic licensing.
- Mobile-to-Desktop Convergence:Touch-optimized tablet workflows are migrating toward hybrid architectures that synchronize field sketching with studio finishing, enabled by 5G latency reductions.
- Japanese Export Standards Alignment:METI-promoted software export frameworks ease cross-border licensing complexity for domestic developers seeking penetration in European and North American markets.
Industry Challenges
- Color Science Expertise Scarcity:ICC profile management and wide-gamut calibration require specialized knowledge that outpaces standard digital arts curricula, creating hiring bottlenecks for commercial studios.
- Cross-Platform Integration Complexity:Pipeline engineers face friction synchronizing asset libraries between tablet-native applications and desktop compositing environments, delaying production handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Painting Software Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Applications, Mobile Apps, Web-Based Tools, Plugins End User: Professional Artists, Hobbyists, Designers, Educators License Model: Subscription, One-Time Purchase, Freemium, Open Source Feature: Layer Management, Brush Customization, Vector Support, Collaboration Tools |
| Companies Covered | Adobe Inc., Corel Corporation, Clip Studio Paint, Autodesk Inc., Affinity, Procreate, Krita, ArtRage, PaintTool SAI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Painting Software Market Trends and Innovations
Neural-assisted brush engines and real-time collaboration protocols are compressing the gap between ideation and final asset delivery. These capabilities are redefining competitive differentiation beyond traditional feature-checklist comparisons.
Generative fill and style-transfer algorithms are supplanting manual texture creation and reference-gathering workflows. Concept art teams in triple-A game studios are adopting these tools for rapid iteration cycles. The technology is compressing pre-production timelines from weeks to days while elevating output volume expectations.
The EU AI Act's transparency requirements for automated creative tools are mandating disclosure protocols when machine-generated elements appear in commercial deliverables. Publishers and advertising agencies in France and Germany are revising contract templates to specify human-versus-AI contribution thresholds. Illustration marketplaces are responding by developing provenance-tracking metadata standards.
Perpetual-license holdouts among traditional illustrators are gradually accepting subscription models as cloud-storage integration becomes non-negotiable for client collaboration. This behavioral pivot is most visible among freelance concept artists serving the United States entertainment industry, where file-sharing expectations now assume always-online asset synchronization. The shift is eroding the pricing power of boxed-software retail channels.
Digital Painting Software Market Segmentation
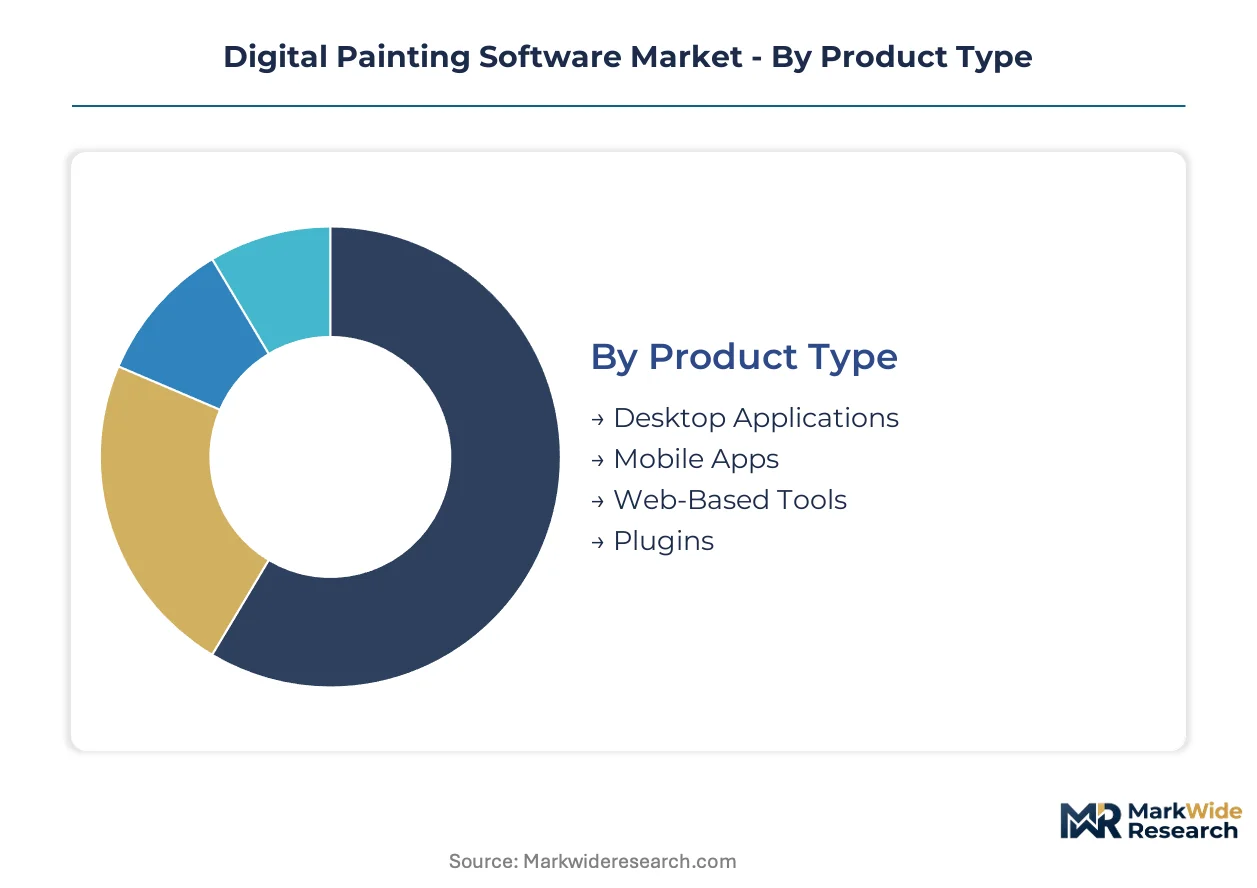
Segmentation in digital painting software reveals how technical requirements diverge between professional studios and individual practitioners. License flexibility and platform architecture determine vendor accessibility across price-sensitive and performance-demanding user bases.
Product Type:
Substitution pressure intensifies as tablet-native workflows encroach on desktop dominance, forcing legacy vendors to defend their installed base through cloud-hybrid architectures.
- Desktop Applications:Full-featured raster and vector engines engineered for GPU-accelerated rendering and wide-gamut color management. Professional concept art studios in the United States and Japan anchor demand here, driven by pipeline integration requirements with compositing software. Desktop Applications anchor the volume base while Web-Based Tools gains share at the steepest rate.
- Mobile Apps:Touch-optimized interfaces leveraging Apple Pencil and Samsung S Pen pressure protocols for field sketching. Freelance illustrators in South Korea and Germany are migrating core workflows here, compelled by client demands for rapid turnaround on location. Mobile Apps are expanding most quickly as 5G synchronization enables seamless handoffs to studio finishing environments.
- Web-Based Tools:Browser-rendered canvases with cloud-native asset storage eliminating local installation dependencies.
- Plugins:Extension modules adding specialized brush engines or pipeline connectors to host applications.
Desktop Applications retain the largest revenue pool while Mobile Apps capture the steepest expansion trajectory as hardware capabilities narrow the functionality gap.
End User:
Cost tier stratification separates enterprise-grade procurement from individual purchasing patterns, with educational institutions occupying a distinct negotiation position between volume discounts and feature completeness demands.
- Professional Artists:Commercial illustrators and concept artists requiring ICC profile accuracy, layer count scalability, and scriptable automation. Triple-A game studios in France and the United States concentrate procurement here, constrained by color science expertise scarcity in hiring pipelines. Professional Artists anchor the volume base while Hobbyists gains share at the steepest rate.
- Hobbyists:Non-commercial practitioners prioritizing intuitive interfaces and community tutorial ecosystems over technical depth. iPad Pro adoption in Japan and Germany accelerates segment growth, fueled by social media portfolio culture and accessible price points. Hobbyists are climbing the fastest as tablet penetration deepens among casual creators.
- Designers:Graphic and UX practitioners integrating painting tools with layout and prototyping workflows.
- Educators:Art instructors and institutional IT administrators balancing budget constraints with curriculum alignment needs.
Professional Artists generate the highest per-seat revenue while Hobbyists expand the addressable market most rapidly through lower entry barriers.
License Model:
Margin structures diverge sharply between recurring revenue predictability and upfront cash flow, with vendor strategies increasingly favoring subscription architectures despite perpetual-license loyalty in traditional illustrator communities.
- Subscription:Monthly or annual access with continuous feature updates and cloud storage integration. Entertainment industry freelancers in the United States are consolidating here, compelled by client collaboration mandates requiring always-online asset synchronization. Subscription anchors the volume base while Freemium gains share at the steepest rate.
- One-Time Purchase:Perpetual licenses with version-locked functionality and optional paid upgrades. Traditional illustrators in Germany and France sustain demand, motivated by resistance to recurring obligations and offline workflow preferences. One-Time Purchase retains loyalty among cost-sensitive practitioners despite cloud-feature gaps.
- Freemium:Tiered access with basic functionality at no cost and premium capabilities unlocked through payment.
- Open Source:Community-developed codebases with no licensing fees and extensible architecture for technical users.
Subscription dominates vendor revenue strategies while Freemium expands user acquisition funnels most aggressively through reduced trial friction.
Feature:
Application maturity varies across functional domains, with collaboration infrastructure representing the newest competitive battleground as distributed art teams become standard in game and animation production.
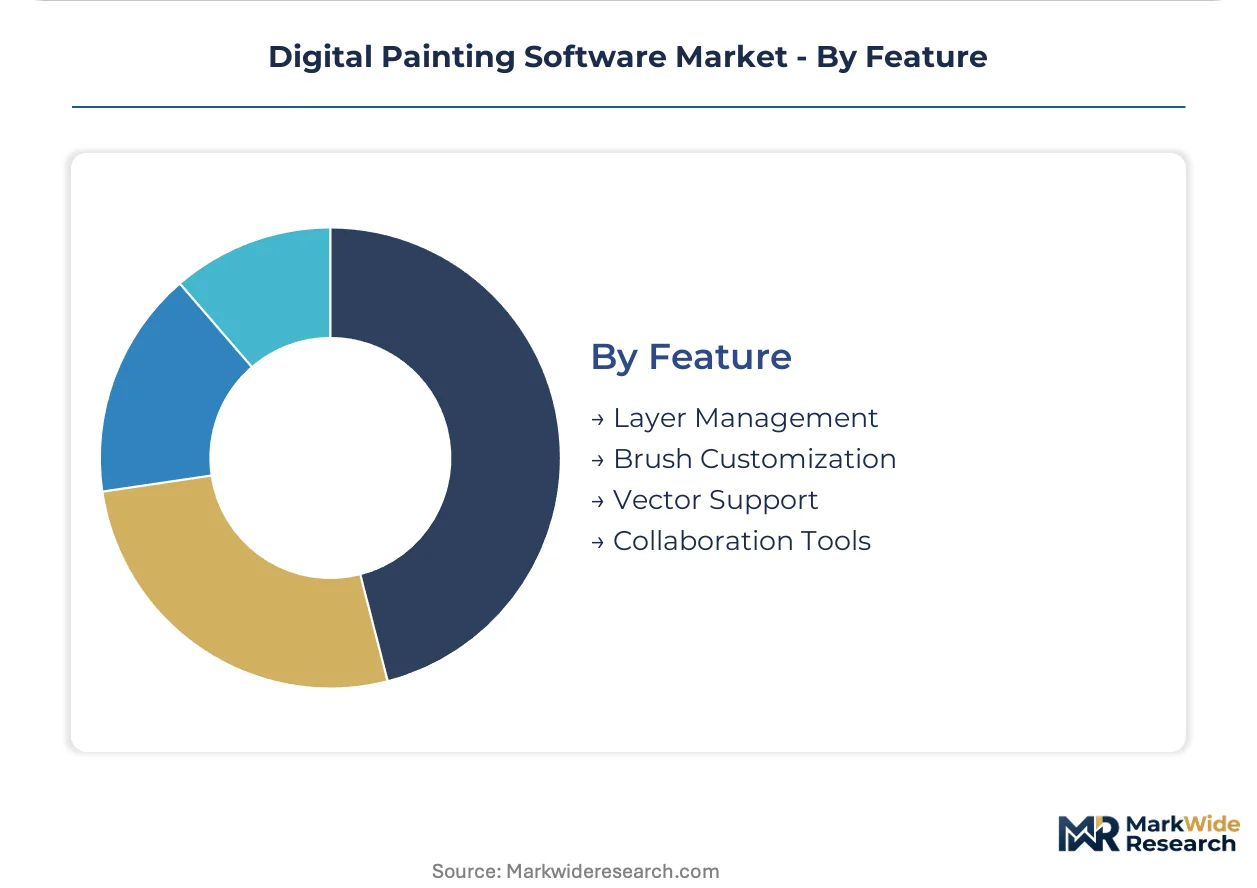
- Layer Management:Non-destructive compositing hierarchies with blend modes, masks, and adjustment layers. Commercial studios in Japan and the United States require unlimited layer counts for complex scene construction, pressured by escalating asset complexity in high-resolution deliverables. Layer Management anchors the volume base while Collaboration Tools gains share at the steepest rate.
- Brush Customization:Parameter-driven stylus dynamics including pressure curves, tilt response, and texture mapping. Concept artists in South Korea and France prioritize this capability, driven by distinctive stylistic requirements in competitive illustration marketplaces. Brush Customization differentiates professional-grade tools from consumer alternatives.
- Vector Support:Resolution-independent path-based creation with anchor point manipulation and Boolean operations.
- Collaboration Tools:Real-time multi-user editing, version branching, and comment threading for distributed teams.
Layer Management remains the non-negotiable baseline while Collaboration Tools shows the steepest adoption acceleration as remote production pipelines normalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in France by roughly 40% for equivalent seat licenses, reflecting divergent professional creative economy maturity. This asymmetry shapes vendor go-to-market strategies across major demand centers. Geographic expansion priorities track cloud infrastructure density and freelance illustrator population concentration.
United States
Entertainment industry freelancers in Los Angeles and New York drive seat-flexible licensing consolidation as client collaboration mandates require always-online asset synchronization. The FTC scrutinizes auto-renewal billing practices, introducing compliance friction for subscription-dependent vendors. Seattle and Austin clusters anchor independent game studio formation, accelerating headless art department adoption.
Germany
Traditional illustrators in Berlin and Munich sustain perpetual-license demand, motivated by resistance to recurring obligations and offline workflow preferences. The KBA does not regulate this sector directly, though EU Digital Services Act transparency obligations reshape platform-distributed tool requirements. Hamburg's advertising agency density creates concentrated demand for color-accurate production pipelines.
Japan
Triple-A game studios in Tokyo and Osaka anchor professional-grade desktop application procurement, constrained by color science expertise scarcity in hiring pipelines. METI promotes software export standards that ease cross-border licensing complexity for domestic developers. Kyoto's animation production cluster drives layer-intensive workflow requirements for complex scene construction.
South Korea
Hardware manufacturers in Seoul are converging on unified pressure-curve protocols with Japanese counterparts, reducing compatibility fragmentation that previously deterred professional adoption. The MFDS does not oversee creative software, though national digital content export initiatives provide indirect support. Busan's webtoon production ecosystem accelerates mobile-native workflow adoption among field illustrators.
France
Vocational art schools in Paris and Lyon remain predominantly served by discounted legacy suites, presenting white space for purpose-built academic licensing. The EU AI Act mandates disclosure protocols when machine-generated elements appear in commercial deliverables, revising publisher contract templates. Bordeaux's independent game development cluster expands headless art department adoption.
Digital Painting Software Market Competitive Landscape
Concentration sits with cloud-native platform providers who have converted perpetual-license holdouts through storage integration mandates. Three to five significant players anchor professional segments while open-source alternatives fragment hobbyist tiers. Strategic archetypes divide between Creative Cloud infrastructure operators, tablet-native specialists, and perpetual-license traditionalists. Competitive moves center on M&A for pipeline integration capabilities and geographic expansion through METI-aligned export frameworks.
Within the cloud infrastructure tier, Adobe Inc. exemplifies recurring-revenue architecture dominance, while Corel Corporation occupies a position among perpetual-license loyalty sustainers. Procreate anchors the tablet-native segment with touch-optimized workflow representation. These three entities collectively illustrate how technical architecture choices—cloud-native versus desktop-legacy versus mobile-first—determine accessible market segments and pricing power durability.
| Leading Market Players |
|---|
| Adobe Inc. |
| Corel Corporation |
| Clip Studio Paint |
| Autodesk Inc. |
| Affinity |
| Procreate |
| Krita |
| ArtRage |
| PaintTool SAI |
| Others |
Pricing and Supply Chain Analysis
Seat-flexible licensing agreements lock in recurring revenue visibility for cloud-native vendors while tethering freelance illustrators to predictable cost structures across United States entertainment industry procurement cycles. This contract pattern compresses customer acquisition friction for platform providers but amplifies switching costs for individual practitioners.
Pricing Analysis
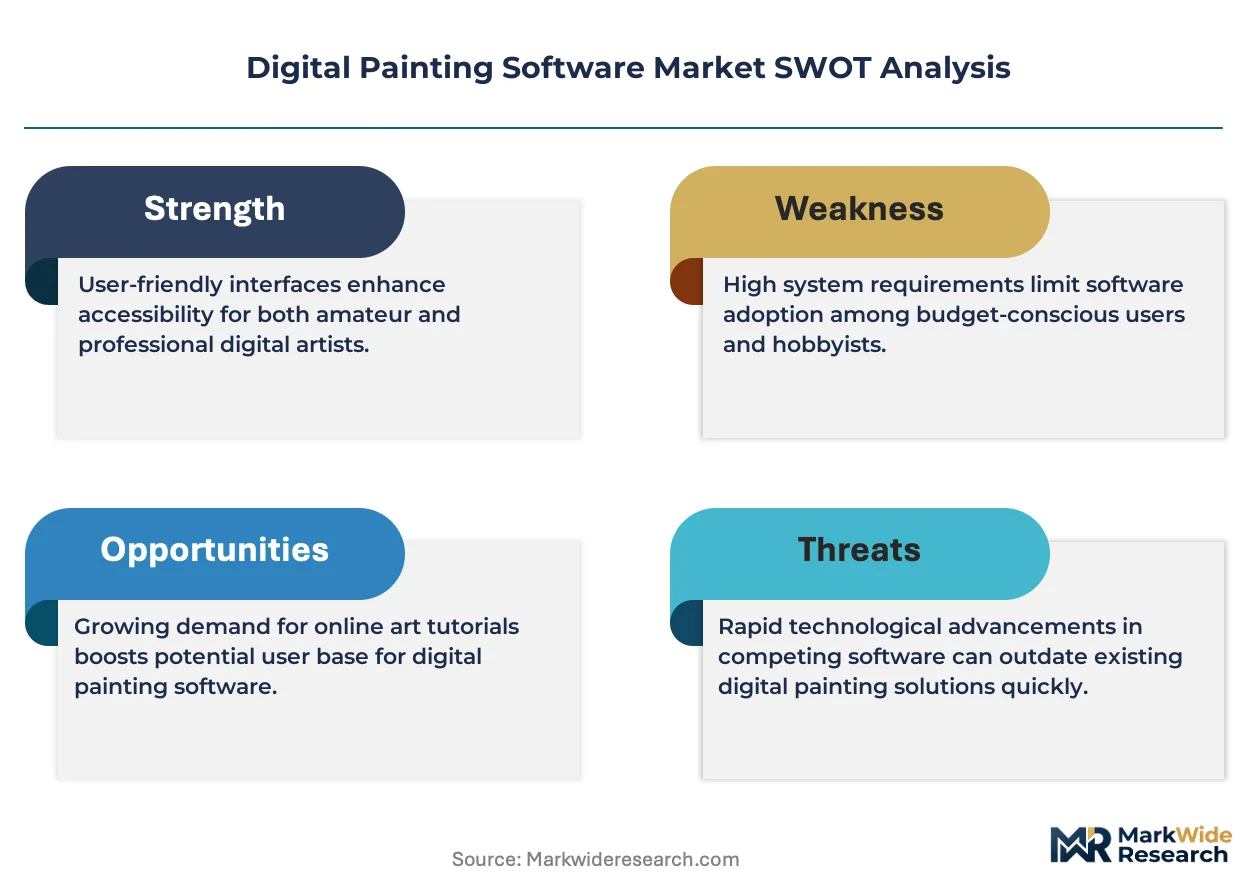
The customization-premium spread separates enterprise-grade seat configurations from individual hobbyist tiers, with triple-A game studios in France and Japan absorbing premium markups for unlimited layer counts and ICC profile management. Subscription models dominate vendor revenue strategies, though price differentiation hinges on cloud storage allocation and real-time collaboration feature depth. Pricing pressure stems from subscription fatigue accumulation among cost-sensitive freelancers in Germany, where perpetual-license loyalty persists. Hobbyists exhibit highest price sensitivity, while professional concept art studios demonstrate lowest elasticity due to pipeline integration requirements.
Supply Chain Analysis
The United States and Japan anchor cloud infrastructure deployment for digital painting platforms, while South Korea concentrates pressure-sensitive stylus hardware manufacturing. Software distribution draws from hyperscaler datacenter networks, GPU rendering service providers, and application marketplace platforms. Single-source vulnerability sits with proprietary brush engine libraries controlled by incumbent vendors. Distribution runs through direct-to-consumer app stores and enterprise volume licensing programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in educational institution procurement, where vocational art schools in France and community colleges in the United States remain underserved by purpose-built academic licensing structures.
For Market Incumbents: Shield recurring revenue streams by deepening Creative Cloud infrastructure lock-in through mandatory cloud-storage integration for client collaboration workflows. Accelerate certification investment in EU AI Act compliance to preempt transparency mandate friction for generative fill features. Prioritize vertical integration into tablet-native rendering pipelines to defend against Procreate's touch-optimized encroachment. For New Entrants and Emerging Players: Differentiate on open-source extensibility and perpetual-license availability to capture cost-sensitive illustrator segments in Germany and France. Target vocational art schools in Paris and Lyon with discounted academic tiers featuring curriculum-aligned brush libraries. Deploy freemium user acquisition funnels with premium collaboration capability unlocks. For Investors and Strategic Acquirers: Capital is best deployed toward pipeline integration specialists with established compositing software connectors and triple-A studio reference accounts. Long-term viability favors vendors bridging mobile-to-desktop workflow convergence. Watch for inflection signals in 5G latency reduction enabling seamless field-to-studio asset handoffs.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Migration | Adobe's Creative Cloud infrastructure anchors recurring revenue from professional studios requiring always-online synchronization. |
| Tablet-Native Workflow Optimization | Procreate's touch-optimized interface captures field illustrator demand in South Korea's webtoon production ecosystem. |
| EU AI Act Compliance Investment | Transparency mandate adherence enables continued generative fill deployment in French and German publishing contracts. |
| Educational Institution Licensing Expansion | Purpose-built academic tiers address underpenetration in France's vocational art schools and United States community colleges. |
| Cross-Border Export Framework Alignment | METI-promoted standards ease Japanese developer penetration into European and North American procurement channels. |
Research Methodology
Desk research of SEC filings, app store revenue disclosures, and hyperscaler capex reports preceded structured interviews with CTOs at independent game studios, IT procurement officers at triple-A publishers, platform engineers at cloud infrastructure providers, and integration specialists at pipeline middleware vendors. Primary fieldwork with freelance illustrators in Los Angeles, Berlin, and Seoul validated secondary estimates of license model preferences and feature prioritization. Bottom-up segment sizing triangulated against top-down industry expenditure assessments.
Variance decomposition across deployment model, organization size, vertical integration depth, and regional adoption pattern shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated 5G latency improvement trajectories and stylus hardware penetration curves.
Decision-makers should treat outputs as directional under assumptions of sustained cloud infrastructure investment and stable regulatory enforcement timelines; material deviation in FTC subscription billing scrutiny intensity would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Personal Budgeting Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Lighting Control Software Market
Software & Services
Automation Test Software Market
Software & Services
Global Database Management Software Market
Software & Services
Bank Reconciliation Software Market
Software & Services
Nonconformance Management Software Market
Software & Services
Real-Time Voice Changing Software Market
Software & Services
Software Licensing Market
Software & Services
Ground Handling Software Market
Software & Services
Enterprise Software Market
Software & Services
Exploration and Production Accounting System Software Market
Software & Services
Global Florist Software Market
Software & Services
Servicenow Tech Services Market
Software & Services
Library Management Software Market
Software & Services
Sales Platforms Software Market