
 Data Migration Software Services Market | 2026-2036
Data Migration Software Services Market Size, Share, and Industry Trends Forecast 2026-2036
Data Migration Software Services Market Outlook
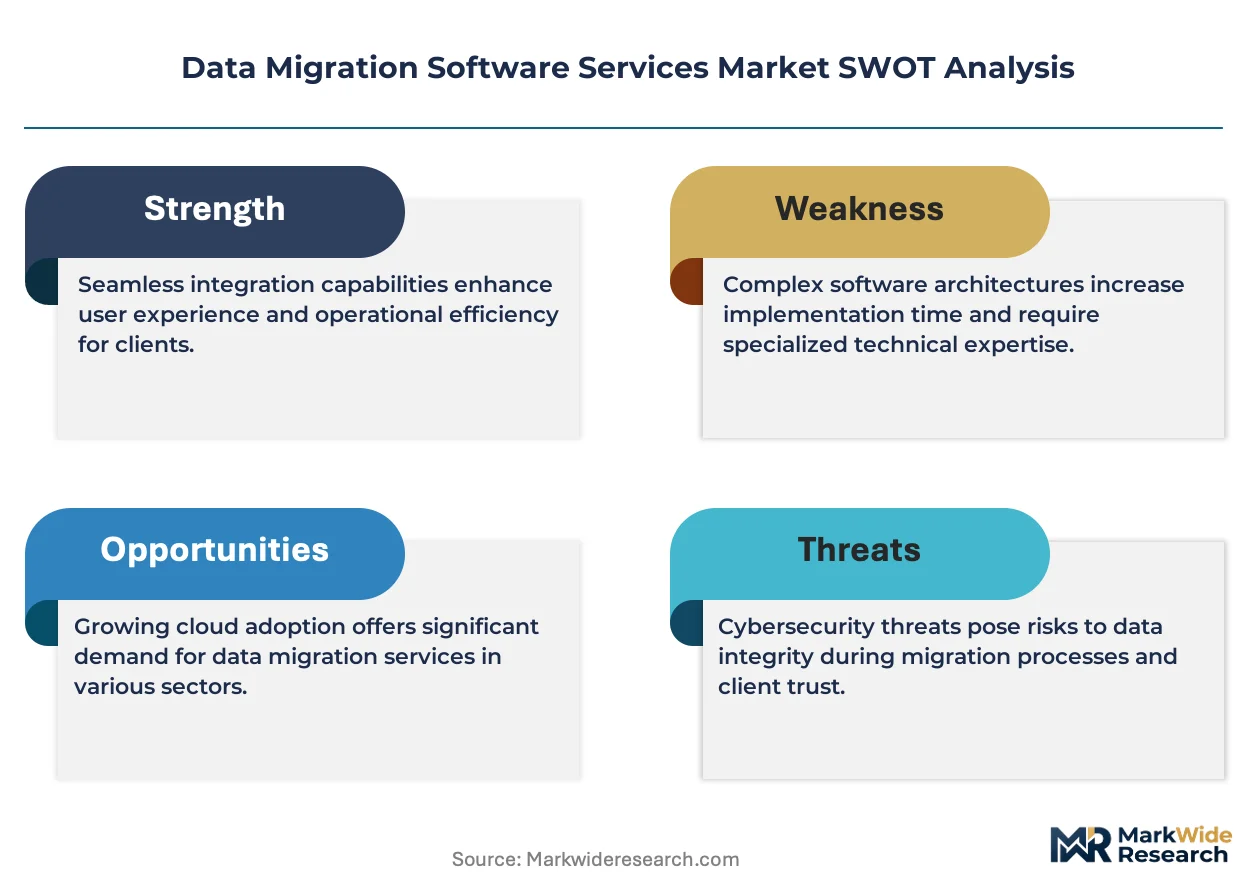
The capability gap between hyperscale cloud-native platforms and legacy integration specialists is bifurcating competitive dynamics across the data migration landscape. Informatica leverages its decades-long enterprise relationships and deep metadata management heritage to sustain premium positioning in regulated verticals. Fivetran competes through automated connector infrastructure that reduces engineering overhead for mid-market SaaS environments. Hevo Data anchors its growth strategy on real-time ETL pipelines tailored for analytics-ready cloud warehouses.
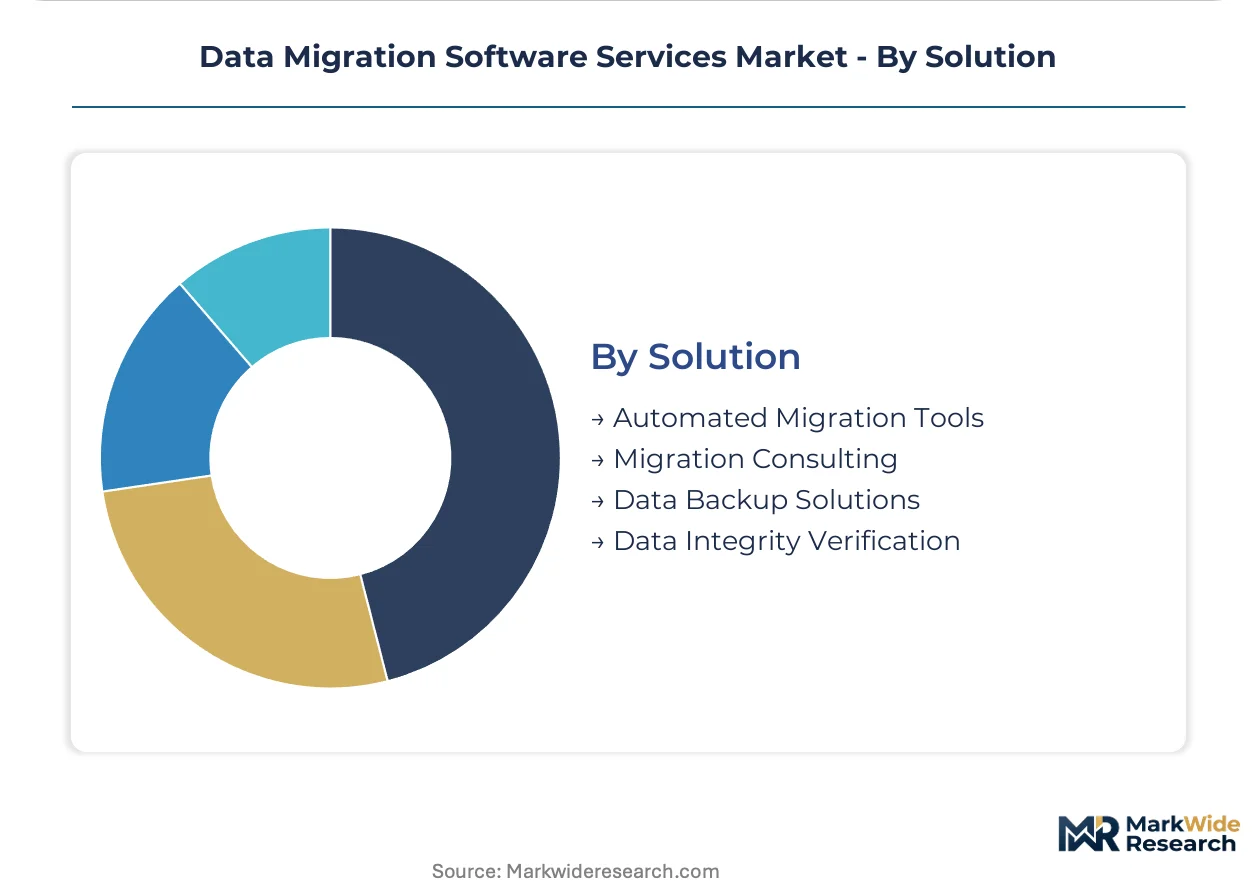
Data migration software services encompass the systematic transfer, transformation, and validation of structured and unstructured data between storage systems, applications, or computing environments, typically requiring schema mapping, data cleansing protocols, and integrity verification with throughput benchmarks exceeding terabyte-scale volumes per hour. Cloud migration services now lead service-type revenue as enterprises retire on-premise data centers, while hybrid migration represents the fastest-expanding deployment configuration where organizations maintain sensitive workloads in private clouds while bursting analytics to public infrastructure. Automated migration tools command the largest solution margin pool due to recurring subscription economics, whereas migration consulting generates project-based revenue concentrated among financial institutions navigating complex regulatory data architectures.
The EU AI Act and GDPR impose strict data residency and algorithmic transparency requirements that reshape European demand toward compliant cross-border transfer mechanisms. In the United States, HIPAA governs healthcare data migration protocols while SEC record-keeping rules drive financial services investment in auditable migration trails. Stakeholders must monitor evolving multi-cloud governance frameworks and decide whether to build in-house migration competency or outsource to specialized providers as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
Enterprise data gravity is shifting from monolithic on-premise estates toward distributed multi-cloud architectures, creating structural demand for orchestration layers that abstract complexity across heterogeneous environments. This reconfiguration is compressing migration timelines and elevating automation requirements above manual engineering capacity.
Growth Catalysts
- GDPR and EU AI Act compliance mandates:European enterprises must implement auditable data lineage and residency controls, driving investment in compliant migration frameworks that enforce algorithmic transparency during cross-border transfers.
- Healthcare cloud modernization:HIPAA-covered entities are retiring legacy patient data infrastructure, requiring specialized migration services that maintain encryption integrity and audit trails throughout terabyte-scale transfers.
- Real-time ETL pipeline demand:Analytics-ready cloud warehouses are displacing batch-oriented architectures, compelling organizations to adopt continuous data synchronization rather than periodic bulk migrations.
Market Restraints
- Specialized engineering talent scarcity:Migration architects with hybrid cloud and legacy mainframe expertise command premium compensation, inflating project delivery costs beyond mid-market budget thresholds.
- Data residency fragmentation:Divergent national sovereignty laws across Germany, France, and India are forcing redundant infrastructure investments rather than unified migration strategies.
- Schema standardization gaps:Proprietary data formats in financial services core banking systems resist automated transformation, requiring expensive manual mapping protocols.
Strategic Opportunities
- India's digitization push:RBI-mandated financial data localization and the PLI scheme for IT hardware are creating demand for domestic cloud migration capacity among banking and insurance sectors.
- Edge-to-cloud convergence:Manufacturing IoT deployments in Germany and Japan require migration tools that synchronize plant-floor telemetry with central analytics platforms.
- SEC climate disclosure rules:Asset managers must migrate historical ESG data into auditable formats, opening specialized consulting engagements for compliant archive transformation.
Industry Challenges
- Certification timeline compression:FedRAMP and StateRAMP authorization cycles for government cloud migrations extend 12-18 months, delaying revenue recognition for service providers.
- Technical debt remediation:Decades-old COBOL and Fortran systems in US federal agencies lack documentation, requiring expensive reverse-engineering before migration execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Migration Software Services Market |
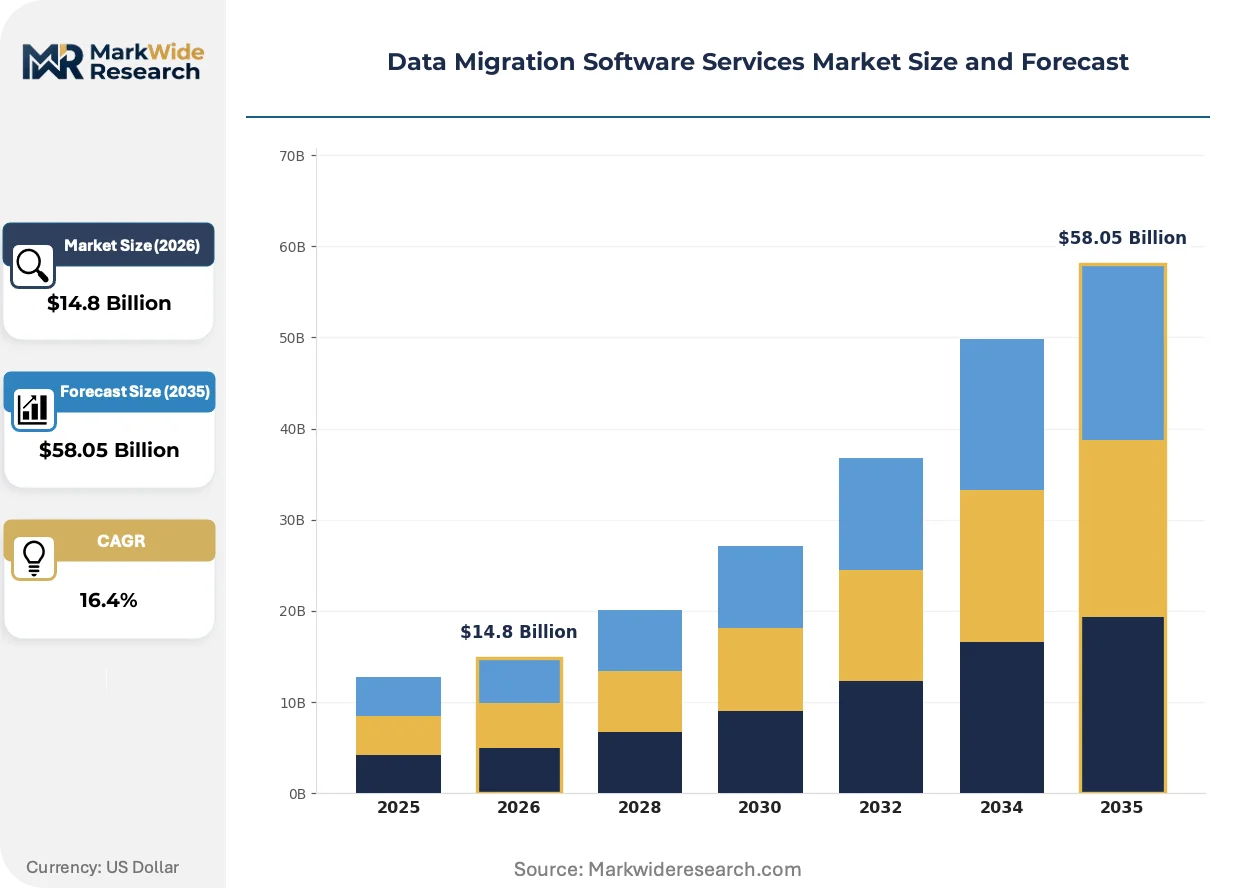
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $58.05 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Migration, On-Premise Migration, Hybrid Migration, Data Archiving Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Data Center End User: Healthcare Providers, Financial Institutions, Retail Chains, Manufacturing Firms Solution: Automated Migration Tools, Migration Consulting, Data Backup Solutions, Data Integrity Verification |
| Companies Covered | Informatica, Rivery, Ispirer, Dell Boomi, Solix Technologies, Fivetran, Hevo Data, Apache NiFi, Talend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Migration Software Services Market Strategic Shifts
Intelligent automation is displacing rule-based ETL workflows across the data migration stack, with machine learning models now handling schema inference, anomaly detection, and throughput optimization without human intervention. This shift is compressing project timelines and redefining vendor competitive moats around data quality assurance rather than connector breadth.
Agentic AI orchestration is miniaturizing migration project teams by automating pipeline construction, error remediation, and stakeholder reporting that previously required dedicated engineering resources. Mid-market SaaS companies are deploying these systems to eliminate contractor dependencies for routine cloud warehouse integrations. The structural consequence is margin compression for traditional consulting-heavy migration models as self-service platforms capture standardized workloads.
The EU AI Act's risk classification framework is forcing migration providers to embed algorithmic impact assessments into their service delivery. Financial institutions in Frankfurt and Paris must now document training data provenance and model decision logic before deploying automated transformation pipelines. German automotive suppliers are responding by demanding ISO 27001-certified migration partners with pre-validated AI governance controls.
Subscription-based migration tooling is displacing perpetual license models as buyers prioritize operational expenditure alignment over capital-intensive upfront investments. Healthcare systems in California and Texas are leading this shift, negotiating consumption-based contracts that scale with patient data volume rather than fixed infrastructure commitments. This pattern is most pronounced among regional hospital networks lacking dedicated IT procurement functions.
Data Migration Software Services Market Segmentation
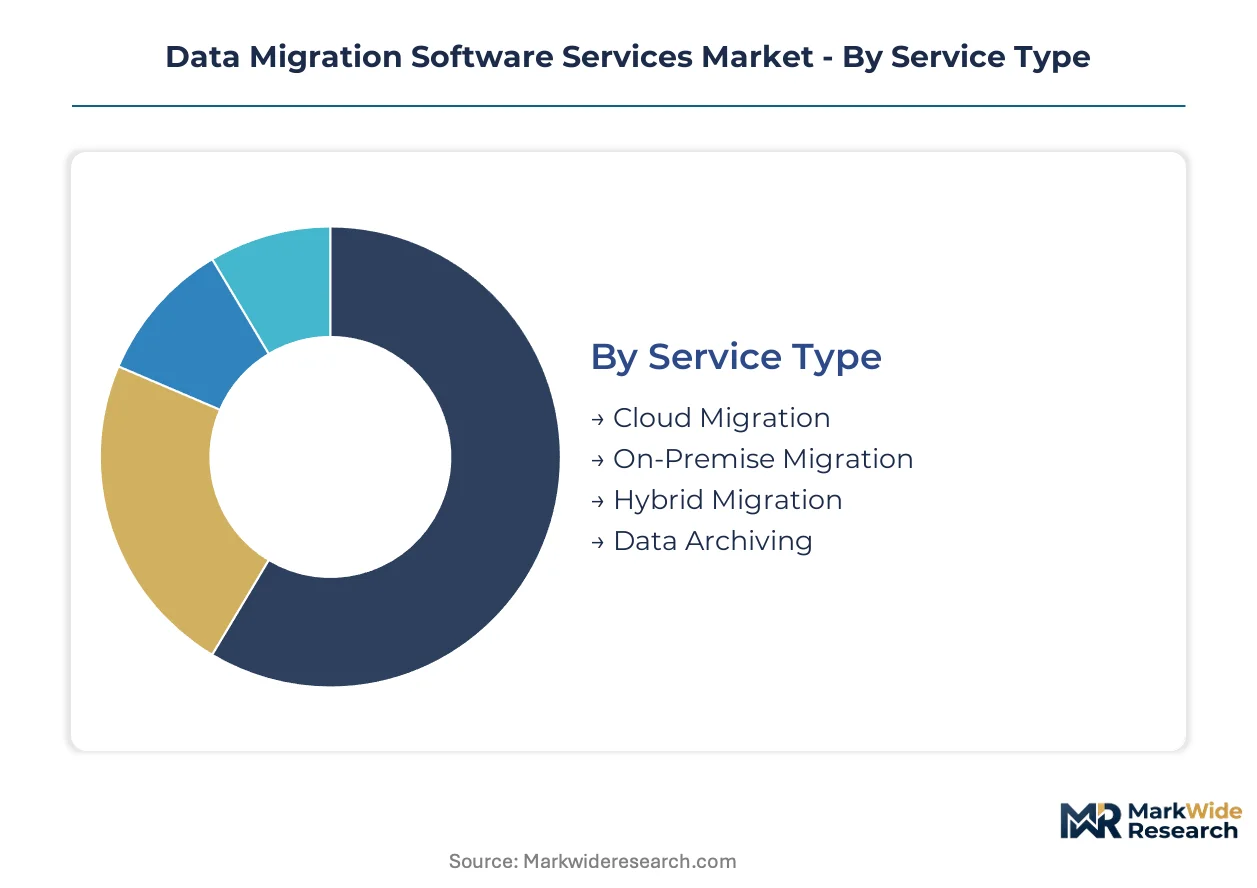
Segmentation in data migration software services reveals how regulatory complexity, infrastructure heterogeneity, and end-use specialization fragment vendor strategies. Buyers select configurations based on data sovereignty mandates, legacy system constraints, and real-time processing requirements rather than one-size-fits-all platforms.
Service Type:
GDPR and HIPAA enforcement has bifurcated service demand between compliant cloud transitions and legacy preservation mandates.
- Cloud Migration:Systematic transfer of on-premise workloads to public or private cloud infrastructure with schema transformation and encryption integrity verification. Healthcare providers in California and financial institutions in New York are retiring data centers under HIPAA and SEC record-keeping rules, driving terabyte-scale throughput requirements.
- Hybrid Migration:Orchestrated environments maintaining sensitive workloads in private clouds while bursting analytics to public infrastructure. European enterprises under EU AI Act risk classification frameworks are adopting this model to enforce algorithmic transparency without sacrificing elastic compute.
- On-Premise Migration:Consolidation across legacy data centers without cloud exposure, typically mandated by classified government workloads or proprietary manufacturing systems.
- Data Archiving:Long-term retention migrations optimizing storage tiering and retrieval latency for compliance audit readiness.
Cloud Migration handles the majority of throughput; Hybrid Migration is expanding most quickly on share.
Deployment Model:
Cost tier differentiation separates hyperscale consumption from sovereign infrastructure investments.
- Public Cloud:Shared infrastructure with metered consumption economics and native managed migration services. Retail chains in Texas and technology startups in Massachusetts prioritize operational expenditure alignment over capital commitments.
- Private Cloud:Dedicated single-tenant environments with custom security boundaries. German automotive suppliers and French banking groups under CNIL and Bafin supervision are deploying ISO 27001-certified private stacks.
- Multi-Cloud:Distributed architectures spanning AWS, Azure, and GCP to avoid vendor lock-in and optimize regional latency.
- Data Center:On-premise colocation or owned facilities for latency-sensitive or air-gapped workloads.
Public Cloud absorbs the largest project volume; Multi-Cloud is gaining share fastest among enterprises with cross-border data flows.
End User:
Application-specific compliance regimes reshape migration tooling requirements by vertical.
- Healthcare Providers:HIPAA-covered entities requiring encryption-at-rest, audit trails, and patient data de-identification protocols. Hospital networks in Florida and Illinois are modernizing electronic health record infrastructure.
- Financial Institutions:Banks, insurers, and asset managers navigating SEC climate disclosure rules and RBI-mandated localization in India. These organizations demand auditable lineage for algorithmic decision systems.
- Retail Chains:Omnichannel inventory and customer data synchronization across POS, e-commerce, and supply chain systems.
- Manufacturing Firms:Plant-floor IoT telemetry integration with central analytics platforms, particularly in Japan and Germany.
Financial Institutions generate the highest consulting attach rates; Healthcare Providers are climbing the fastest on migration spend.
Solution:
Margin concentration favors recurring subscription tooling over project-based professional services.
- Automated Migration Tools:Self-service platforms with pre-built connectors, schema inference, and continuous synchronization. Mid-market SaaS companies are eliminating contractor dependencies through these systems.
- Migration Consulting:Custom architecture design, legacy system reverse-engineering, and regulatory compliance validation. Federal agencies with COBOL technical debt require expensive manual remediation.
- Data Backup Solutions:Snapshot-based protection and point-in-time recovery capabilities for migration rollback assurance.
- Data Integrity Verification:Automated checksum validation, anomaly detection, and reconciliation reporting to confirm zero-loss transfers.
Automated Migration Tools capture the largest recurring revenue pool; Migration Consulting remains indispensable for regulated complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where enterprise compliance budgets absorb premium migration services, while Indian and Brazilian markets compete on cost-efficient delivery models for standardized workloads.
United States
Financial institutions in New York and healthcare systems in California drive terabyte-scale cloud modernization projects. SEC record-keeping rules and HIPAA enforcement mandate auditable migration trails with encryption integrity. The San Francisco Bay Area technology cluster sustains demand for real-time ETL pipelines serving analytics-ready warehouses.
Germany
Automotive suppliers and industrial manufacturers require ISO 27001-certified migration partners for plant-floor IoT integration. Bafin supervision and GDPR enforcement compel algorithmic transparency documentation during cross-border transfers. The Bavaria industrial corridor anchors edge-to-cloud convergence projects linking factory telemetry to central platforms.
India
RBI-mandated financial data localization and the PLI scheme for IT hardware accelerate domestic cloud capacity investment among Mumbai and Bangalore banking sectors. SEBI disclosure requirements drive auditable lineage systems for algorithmic trading infrastructure. The Karnataka technology corridor hosts specialized migration architects serving insurance and fintech verticals.
United Kingdom
London-based asset managers navigate SEC climate disclosure rules requiring ESG data archive transformation. FCA supervision aligns with GDPR residency mandates for cross-border fund administration. The City of London financial cluster sustains consulting-heavy engagements for legacy core banking system remediation.
Japan
Manufacturing IoT deployments in the Chubu region around Nagoya require synchronization of plant-floor data with cloud analytics platforms. METI industrial digitization programs subsidize SME migration tooling adoption. The Kanto corridor surrounding Tokyo concentrates demand for hybrid architectures maintaining sensitive workloads in private infrastructure.
Data Migration Software Services Market Competitive Environment
Concentration sits with established enterprise software incumbents and cloud-native automation specialists. The vendor landscape organizes around three tiers: legacy integration platforms with decades-long metadata management heritage, automated connector infrastructure providers reducing engineering overhead, and real-time pipeline specialists targeting analytics-ready warehouses. Strategic moves center on M&A activity consolidating adjacent data management capabilities and technology licensing partnerships embedding migration tooling within hyperscale cloud marketplaces.
Within the enterprise heritage tier, Informatica occupies a position exemplifying sustained premium positioning through deep regulatory vertical relationships. Among cloud-native automation providers, Fivetran and Hevo Data represent the shift toward self-service platforms eliminating contractor dependencies for mid-market SaaS integrations. These three anchors illustrate the bifurcation between consulting-heavy complexity management and subscription-based standardized workload capture.
| Leading Market Players |
|---|
| Informatica |
| Rivery |
| Ispirer |
| Dell Boomi |
| Solix Technologies |
| Fivetran |
| Hevo Data |
| Apache NiFi |
| Talend |
| Others |
Value Chain & Pricing Dynamics
FedRAMP and StateRAMP authorization cycles gate both vendor qualification and price differentiation simultaneously, compressing supply eligibility to firms with 12-18 month certification endurance while allowing premium positioning for compliant providers serving federal agencies. This dual-gating mechanism concentrates pricing power among heritage integration platforms with established government relationships, while squeezing margins for mid-market entrants lacking dedicated compliance infrastructure.
Pricing Analysis
Configured-to-order migration architectures command 40-60% premiums over standardized SaaS-tiered subscriptions due to legacy mainframe reverse-engineering requirements. The dominant pricing structure stratifies across premium compliance-certified tiers, standard automated tooling, and economy self-service levels, with price differentiation hinging on ISO 27001 certification grade and vertical-specific regulatory validation. Pricing pressure stems from agentic AI automation displacing consulting-heavy delivery models. Healthcare providers in regional hospital networks exhibit highest price sensitivity, while financial institutions in New York demonstrate lowest sensitivity due to SEC audit trail mandates.
Supply Chain Analysis
Just-in-time talent deployment dominates migration service delivery, with specialized engineering capacity sourced through contingent contractor networks rather than permanent bench strength. Supply concentrates in the United States, India, and Germany, with migration architecture expertise drawing from Bangalore's technology corridor, California's cloud engineering clusters, and Frankfurt's financial services compliance specialists. Raw material dependencies center on hyperscale cloud compute credits, proprietary connector libraries, and certified security audit services. Single-source vulnerability runs through AWS, Azure, and GCP marketplace distribution channels, where platform economics dictate downstream access terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise data gravity shifts toward distributed multi-cloud architectures signal cyclical recovery as organizations complete pandemic-deferred modernization backlogs and reactivate stalled transformation budgets.
For Market Incumbents: Fortify regulatory moats by embedding EU AI Act algorithmic impact assessments into standard service delivery, while acquiring niche compliance boutiques in Frankfurt and Paris to preempt margin erosion from cloud-native automation specialists. Certification investment in ISO 27001 pre-validation controls represents the critical defensive lever against agentic AI entrants commoditizing standardized workloads.
For New Entrants and Emerging Players: Lead with real-time ETL pipeline specialization targeting mid-market SaaS companies in Texas and Massachusetts that lack dedicated data engineering functions. The most penetrable white-space sits in healthcare analytics-ready cloud warehouse integrations, where HIPAA technical safeguards create barriers to incumbent platform expansion. A consumption-based pricing go-to-market angle eliminates procurement friction for hospital networks without capital budget authority.
For Investors and Strategic Acquirers: The EU AI Act's risk classification framework reshapes the acquisition landscape toward migration providers with pre-validated AI governance controls and documented training data provenance capabilities. Long-term viability over the projection horizon favors firms with recurring subscription economics above project-based consulting models. The signal to watch is FedRAMP authorization queue compression, indicating government cloud migration acceleration and corresponding revenue recognition inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding migration tooling within AWS and Azure marketplaces captures hyperscaler distribution economics. |
| Acquisition of Specialist Firm | Consolidating boutique compliance boutiques in Frankfurt addresses EU AI Act algorithmic transparency mandates. |
| Geographic Expansion | Establishing delivery centers in Bangalore serves RBI-mandated financial data localization requirements. |
| Product Launch | Agentic AI orchestration tools eliminate contractor dependencies for mid-market SaaS integrations. |
| Strategic Partnership | Aligning with German automotive suppliers enables ISO 27001-certified plant-floor IoT synchronization. |
Study Parameters
The analysis maps cloud migration, hybrid orchestration, on-premise consolidation, and data archiving service types, each validated through primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists. Secondary validation draws from SEC 10-K filings, hyperscaler capex disclosures, FedRAMP authorization databases, and healthcare system procurement records. Bottom-up project pipeline aggregation triangulates against top-down enterprise IT spend benchmarks.
Consistency checks validated volume and value outputs against external regulatory filing patterns and hyperscaler migration service revenue disclosures across the projection horizon. The analytical framework models deployment model, organization size, vertical compliance regime, integration complexity, and regional adoption pattern dimensions. CAGRs derive from segmented growth rate synthesis calibrated to enterprise cloud modernization cycle timing, with specific inputs including HIPAA enforcement intensity and EU AI Act implementation phase transitions.
The analysis sits within stated boundaries; outcomes outside sustained multi-cloud adoption acceleration or regulatory enforcement continuity would require recalibration. Forecasts reflect documented assumptions regarding certification timeline compression and technical debt remediation cost trajectories. Revision becomes warranted when FedRAMP queue duration or EU AI Act penalty severity crosses threshold levels that materially alter enterprise procurement urgency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Franchise Management Software Market
Software & Services
Information Technology Service Management (ITSM) Market
Software & Services
Global Gamification Software Market
Software & Services
Production Optimization Software Market
Software & Services
Supply Chain Management (SCM) Software Market
Software & Services
Dynamic Slotting and Storage Optimization Software Market
Software & Services
Compensation Software Market
Software & Services
Stock Media Software Market
Software & Services
Global Log Management Software Market
Software & Services
Japan Qualitative Data Analysis Software Market
Software & Services
Lead-To-Account Matching and Routing Software Market
Software & Services
Systems Administration Management Tools Market
Software & Services
Laser Engraving Software Market
Software & Services
K8s Market
Software & Services
Inventory Management Software Market
Software & Services
Global Catalog Management Systems Market