
 Performance Management Software Market | 2026-2036
Performance Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Performance Management Software Market Outlook
The gap between premium enterprise suites and commodity point solutions is consolidating around AI-powered analytics and real-time workforce intelligence. SAP SE leverages deep ERP integration to anchor its position in large-scale deployments. Workday Inc. differentiates through native HCM connectivity and unified talent pipelines. ClearCompany specializes in mid-market accessibility with streamlined implementation protocols.
Performance management software encompasses digital platforms that automate goal-setting, continuous feedback collection, competency tracking, and calibration workflows through configurable rating scales, 360-degree review engines, and predictive attrition algorithms. Cloud-based deployment leads volume expansion as organizations retire legacy on-premises installations, while the employee engagement solution category captures expanding margin pools as retention analytics replace annual review cycles.
The SEC, OSHA, and GDPR collectively shape data retention, audit trail, and cross-border privacy requirements that determine product architecture and market access eligibility. ISO 30414 human capital disclosure standards further pressure vendors to embed standardized reporting frameworks. Stakeholders must weigh integration depth against deployment velocity when selecting platforms for multi-regional workforces.
Market Dynamics
Continuous feedback architectures are displacing annual review cycles as the dominant operating model, forcing vendors to reengineer data pipelines for real-time sentiment capture and predictive attrition modeling.
Growth Catalysts
- ISO 30414 Disclosure Mandates:Human capital reporting standards in the European Union and United States require auditable workforce metrics, compelling enterprises to deploy platforms with embedded compliance frameworks.
- Cloud Migration Deadlines:SEC data retention rules for financial services firms are accelerating replacement of on-premises HR systems with SaaS-native alternatives.
- AI-Powered Analytics:Machine learning models that forecast flight risk and identify competency gaps are pulling mid-market employers into premium subscription tiers.
Market Restraints
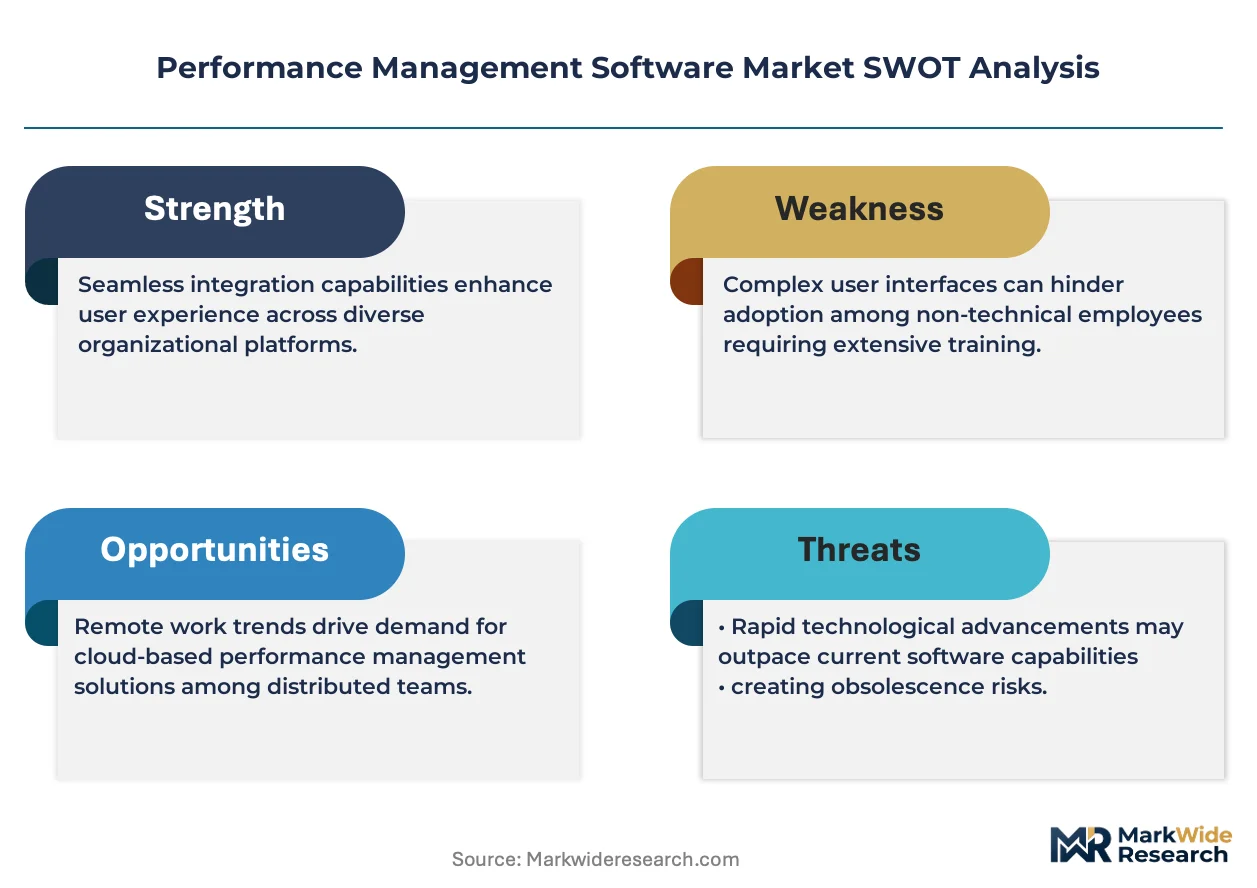
- Integration Tax:Custom API development for legacy ERP connectivity consumes 30-40% of implementation budgets, delaying ROI realization for multi-system environments.
- Data Sovereignty Fragmentation:Conflicting GDPR, HIPAA, and state-level privacy laws in the United States and European Union force redundant infrastructure deployments.
- Skill Scarcity:Shortage of organizational psychologists and people analytics specialists constrains effective platform utilization beyond basic administrative functions.
Strategic Opportunities
- Frontline Worker Expansion:Hourly and distributed workforces in retail, logistics, and healthcare remain underserved by desktop-centric legacy tools.
- Skills-Based Architecture Convergence:Integration of learning experience platforms with performance systems creates unified talent marketplaces for internal mobility.
- India and Southeast Asia:Regulatory pressure from SEBI and emerging data localization requirements are opening greenfield deployment opportunities.
Industry Challenges
- Change Management Complexity:Manager resistance to continuous feedback models and calibration transparency protocols undermines adoption rates.
- Algorithmic Bias Auditing:Emerging legal exposure around AI-driven performance ratings demands costly fairness testing and documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Performance Management Software Market |
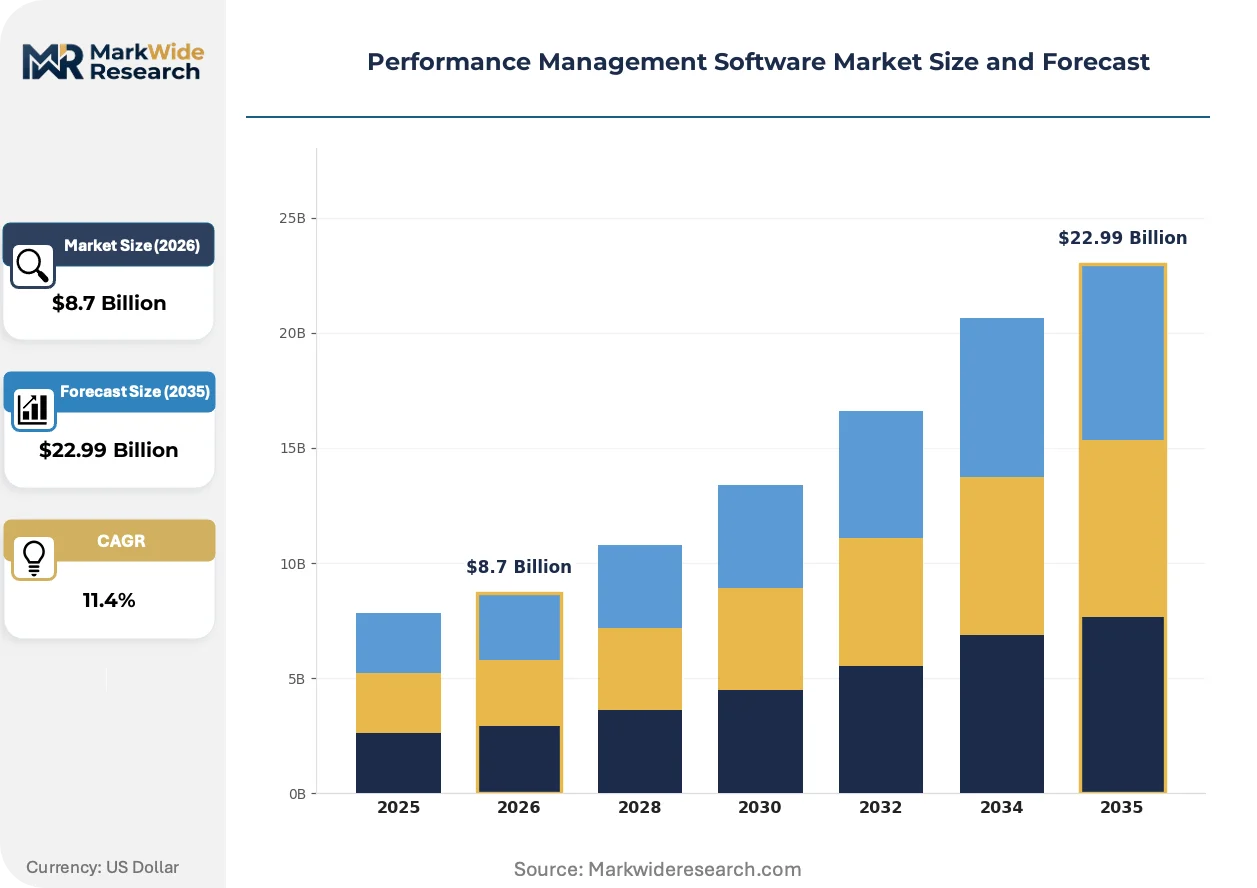
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Enterprises, SMEs, Government, Nonprofits Solution: Performance Appraisal, Goal Management, Feedback Management, Employee Engagement Integration Level: API Integration, Single Sign-On, Data Import/Export, Native Integration |
| Companies Covered | SAP SE, Oracle Corporation, IBM Corporation, Workday Inc., Anaplan Inc., Salesforce Inc., Cornerstone OnDemand, ClearCompany, OneStream Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Performance Management Software Market Strategic Shifts
Generative AI and natural language processing are fundamentally altering how performance conversations are documented, analyzed, and actioned across organizational hierarchies.
Natural language generation is rewriting how feedback gets captured and synthesized. Systems now auto-draft performance summaries from continuous conversation logs. Fortune 500 technology firms are piloting these tools at scale. The technology is rewriting managerial time allocation by compressing documentation cycles from hours to minutes.
GDPR Article 22 restrictions on automated decision-making are forcing vendors to build human-in-the-loop validation for AI-generated ratings. European Union employers must demonstrate meaningful human review of algorithmic outputs. Financial services and healthcare verticals in Germany and France are investing heavily in audit trail infrastructure to satisfy supervisory authority scrutiny.
Subscription fatigue is triggering unbundling of performance modules from full-suite HCM contracts. Mid-market buyers in the United States are procuring point solutions for 360-degree feedback and goal management separately from core HRIS. This pattern is concentrating in technology and professional services sectors where IT autonomy supports best-of-breed stacking.
Performance Management Software Market Segmentation
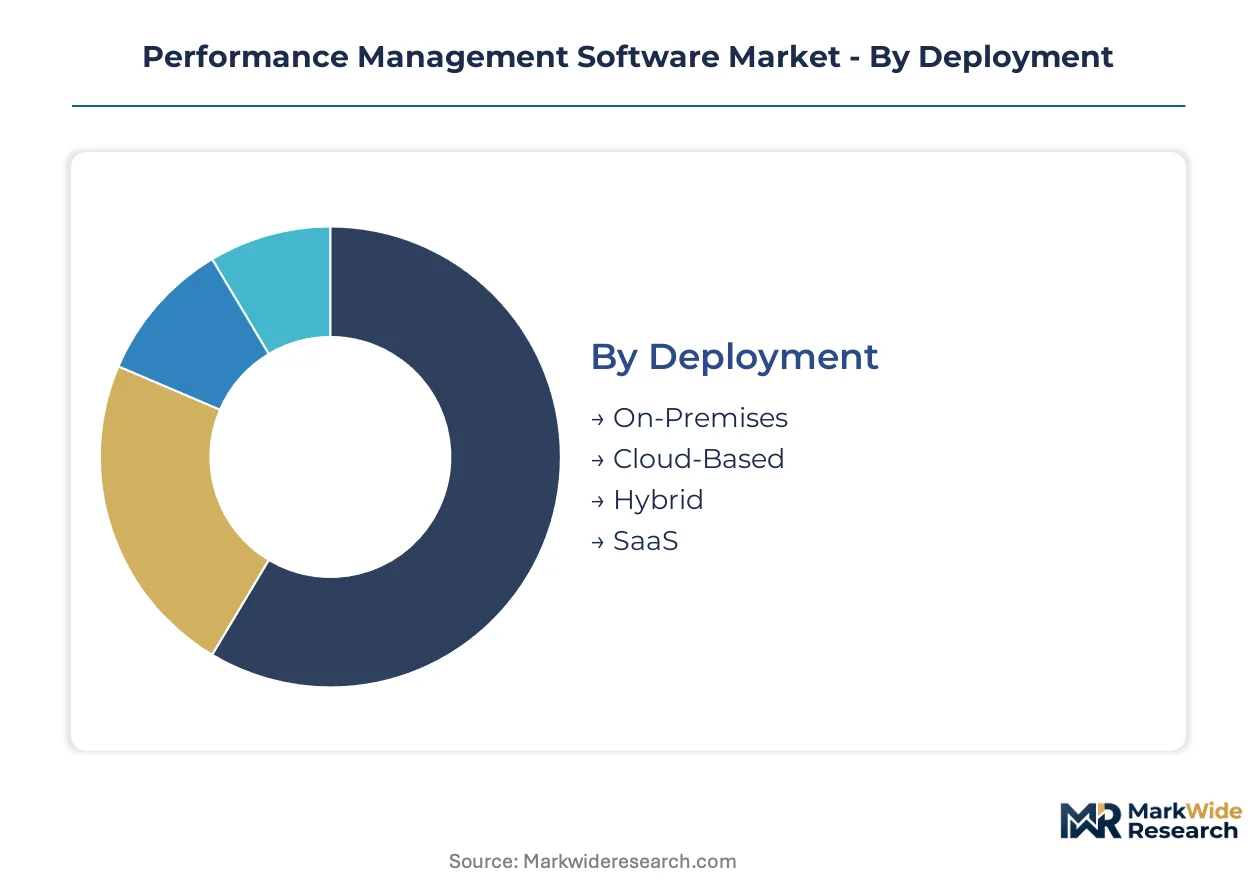
Performance management software vendors architect product portfolios around deployment flexibility, organizational scale, and integration depth. Buyers navigate trade-offs between implementation velocity and enterprise system connectivity. Segmentation reveals where replacement cycles concentrate and which configurations command premium positioning.
Deployment:
Cloud migration mandates from financial regulators are compressing replacement timelines for legacy infrastructure.
- Cloud-Based:Multi-tenant SaaS architectures with automatic compliance patching dominate new procurement in United States financial services. SEC data retention rules accelerate displacement of on-premises alternatives as audit trail automation becomes non-negotiable.
- SaaS:Subscription models with embedded ISO 30414 reporting frameworks capture mid-market employers seeking rapid deployment without dedicated IT infrastructure. European Union GDPR Article 22 compliance features differentiate premium tiers.
- On-Premises:Air-gapped installations persist in defense contractors and classified government facilities with sovereignty requirements.
- Hybrid:Split configurations separating sensitive compensation data on-premises while routing feedback workflows through cloud interfaces.
Cloud-Based sits at the top of the volume ranking, with SaaS climbing the fastest.
End User:
Budget authority and implementation complexity stratify sharply across organizational scale.
- Enterprises:Fortune 500 technology and financial services firms drive demand for predictive attrition modeling and 360-degree calibration engines. Procurement teams prioritize native ERP integration over standalone functionality.
- SMEs:Mid-market employers in professional services and healthcare adopt streamlined goal management modules with minimal configuration overhead. Price sensitivity favors point solutions over full-suite contracts.
- Government:Federal and state agencies mandate FedRAMP authorization and domestic data residency, limiting vendor eligibility.
- Nonprofits:Grant-funded organizations prioritize donor-reporting alignment and volunteer tracking capabilities over enterprise-grade analytics.
Enterprises anchor absolute revenue contribution, while SMEs expand most quickly as unbundled point solutions penetrate cost-constrained buyers.
Solution:
Functional modules compete for standalone procurement versus integrated suite attachment.
- Employee Engagement:Real-time sentiment capture and pulse survey engines with natural language processing for thematic analysis. United States technology firms pilot generative AI for auto-drafted engagement summaries.
- Feedback Management:Continuous conversation logging with manager nudges and peer recognition workflows. GDPR-compliant audit trails for European Union deployments.
- Performance Appraisal:Traditional rating scale and calibration workflows now augmented by algorithmic bias detection.
- Goal Management:OKR cascading and progress visualization with lightweight mobile interfaces for distributed workforces.
Employee Engagement leads margin capture, with Feedback Management gaining share fastest as annual review cycles fragment into ongoing dialogue systems.
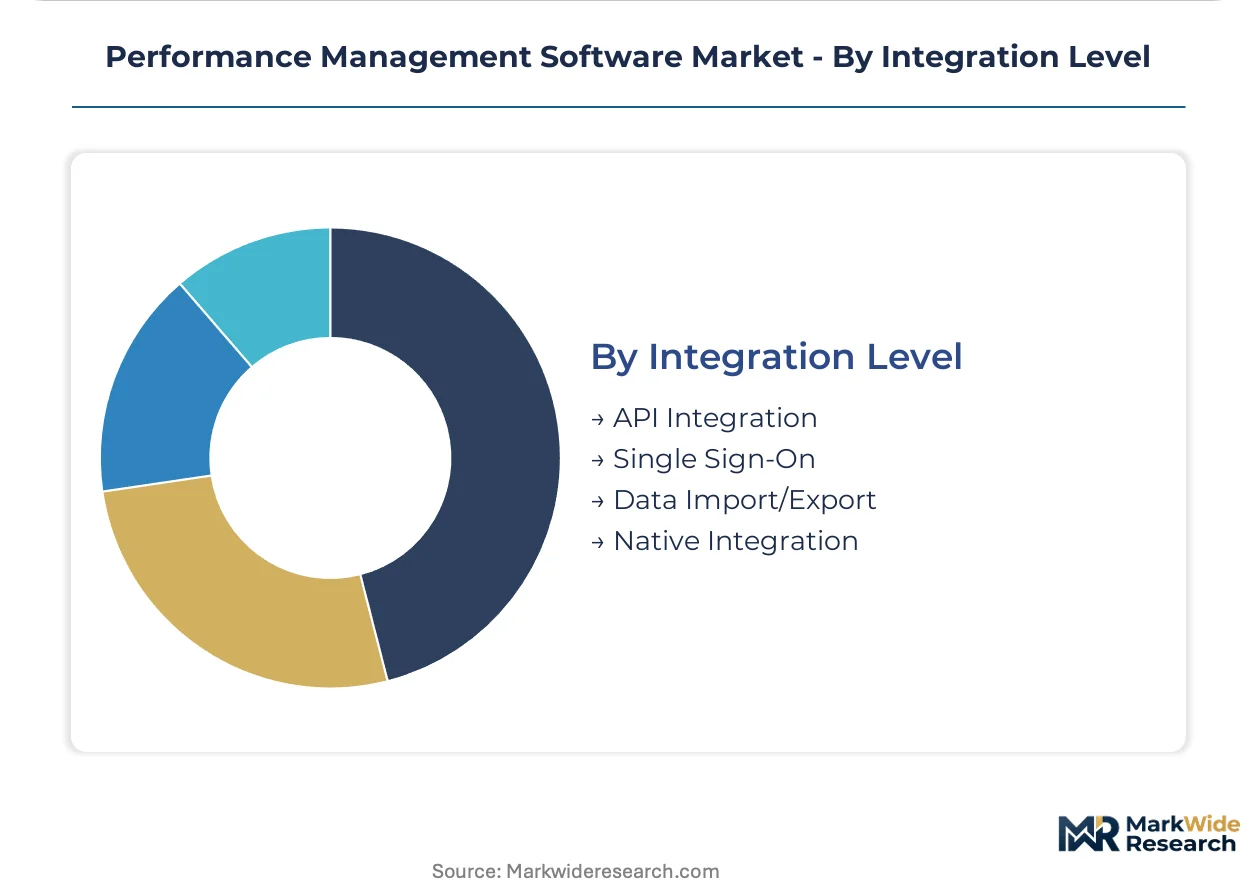
Integration Level:
Technical architecture determines implementation cost and time-to-value realization.
- Native Integration:Pre-built connectors for SAP, Workday, and Oracle HCM eliminate custom development. Large-scale deployments in Germany and France demand embedded compliance reporting for supervisory authority scrutiny.
- API Integration:RESTful and GraphQL endpoints for bespoke workflow automation in multi-system environments. Consumes 30-40% of implementation budgets in complex technology stacks.
- Single Sign-On:SAML and OIDC protocols for identity provider federation reduce administrative overhead.
- Data Import/Export:Bulk migration utilities for historical performance records and exit interview archives.
Native Integration commands the steepest pricing premium, with API Integration showing the fastest adoption growth as best-of-breed stacking proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fortune 500 technology and financial services talent clusters in the United States anchor initial platform adoption, while regulatory divergence across Germany, India, Japan, and the United Kingdom shapes deployment architectures and vendor eligibility requirements.
United States
SEC data retention mandates for financial services firms accelerate cloud migration timelines. OSHA workplace safety documentation requirements intersect with performance tracking systems in manufacturing verticals. Technology corridors in Silicon Valley and Seattle drive pilot deployments of generative AI feedback tools.
Germany
GDPR Article 22 restrictions on automated decision-making force human-in-the-loop validation architectures. Supervisory authority scrutiny from CNIL-aligned state regulators demands embedded audit trail infrastructure. Industrial employers in Baden-Württemberg and Bavaria integrate performance systems with co-determination works council protocols.
India
SEBI disclosure requirements for listed companies mirror ISO 30414 workforce reporting standards. IT services clusters in Bengaluru and Hyderabad deploy continuous feedback platforms for global delivery center management. Domestic data localization pressures from proposed personal data protection legislation reshape vendor selection criteria.
Japan
METI productivity initiatives promote HR technology adoption among mid-market manufacturers. Lifetime employment transition pressures drive demand for skills-based talent marketplace integration. Tokyo and Osaka headquarters of multinational corporations anchor regional implementation of global performance management templates.
United Kingdom
FCA conduct rules for financial services intersect with performance documentation requirements. Post-Brexit data adequacy negotiations with the EU create cross-border workforce analytics complexity. London fintech and professional services clusters favor unbundled point solutions over full-suite HCM contracts.
Performance Management Software Market Competitive Environment
Top-tier vendors anchor enterprise deployments through deep ERP integration, while mid-market specialists capture share with rapid implementation protocols. The vendor base stratifies across three tiers: full-suite HCM incumbents with native performance modules, standalone cloud-native platforms, and point solution specialists. Strategic archetypes include integration-first players, mobile-first disruptors, and compliance-centric regional specialists. Dominant competitive moves center on API ecosystem expansion and AI capability acquisition.
Within the enterprise integration tier, SAP SE and Oracle Corporation represent archetypal full-suite incumbents leveraging decades of ERP installed base relationships. Workday Inc. occupies a position exemplifying cloud-native HCM consolidation. Among standalone specialists, ClearCompany anchors the mid-market accessibility segment with streamlined deployment positioning.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| IBM Corporation |
| Workday Inc. |
| Anaplan Inc. |
| Salesforce Inc. |
| Cornerstone OnDemand |
| ClearCompany |
| OneStream Software |
| Others |
Value Chain & Pricing Dynamics
Generative AI integration into performance management platforms simultaneously compresses development costs and concentrates supplier power among hyperscale cloud providers. SaaS-native architectures reduce infrastructure expenditure while embedding dependency on AWS, Azure, and Google Cloud for GPU compute and model hosting.
Pricing Analysis
Bundle-unbundle service splits define competitive pricing dynamics. Three-tier pricing structure across premium, standard, and economy levels anchors enterprise contracts, with AI-powered predictive analytics commanding the top tier. Price differentiation rests on integration depth and compliance certification level. Pricing pressure stems from mid-market procurement of point solutions over full-suite HCM contracts. SMEs exhibit highest price sensitivity, while Fortune 500 technology firms prioritize native ERP connectivity over cost.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand, while partner networks serve mid-market deployments. Cloud infrastructure concentrates in the United States, Ireland, and Singapore. Raw material dependencies span GPU semiconductor supply from Taiwan, specialized AI training data from India and the Philippines, and compliance audit services from Germany and the United Kingdom. Single-source vulnerability around NVIDIA GPU supply creates procurement risk. Distribution runs through value-added resellers and direct sales teams with embedded implementation specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Enterprise HR departments are consolidating procurement around platforms with embedded ISO 30414 compliance and native AI capabilities.
For Market Incumbents: Deploy API ecosystem expansion as the primary defensive lever. Deepen pre-built connector libraries for SAP, Workday, and Oracle HCM to lock in integration-dependent buyers. Invest in algorithmic bias auditing infrastructure to preempt regulatory exposure from GDPR Article 22 enforcement. Counter subscription fatigue through modular pricing that unbundles point solutions without sacrificing platform stickiness. For New Entrants and Emerging Players: Capture frontline worker segments in retail, logistics, and healthcare that desktop-centric legacy tools underserve. Target mobile-first deployment protocols with lightweight feedback interfaces for hourly workforces. Penetrate India and Southeast Asia where SEBI disclosure mandates and data localization pressures create greenfield demand. Lead with rapid implementation timelines under thirty days to differentiate against enterprise suite complexity. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market specialists with proven AI feature roadmaps and FedRAMP authorization progress. Long-term viability hinges on compliance automation depth rather than feature breadth. Acquisition target archetype: cloud-native platforms with embedded workforce analytics and existing API partnerships with major HCM incumbents. Watch for inflection when SEC expands data retention mandates beyond financial services into healthcare and critical infrastructure sectors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native ERP connectivity with SAP and Workday anchors Fortune 500 retention. |
| Acquisition of Specialist Firm | AI talent marketplace providers enable skills-based architecture convergence. |
| Geographic Expansion | India and Southeast Asia deployments capture SEBI-mandated workforce reporting demand. |
| Product Launch | Generative AI feedback drafting tools compress managerial documentation cycles. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure secure GPU compute for predictive attrition models. |
Study Parameters
Multiple input streams — primary interviews with CHROs and IT procurement officers, secondary validation through SEC filings and ISO certification databases, and technical architecture reviews — were reconciled to construct segment-level demand estimates. Conversations with HR technology consultants, platform implementation specialists, and compliance audit firms informed deployment timeline assumptions. Bottom-up vendor revenue aggregation and top-down enterprise IT spending allocation were cross-checked for consistency.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, organizational scale tier, solution module type, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical replacement cycle data and cloud migration mandate schedules. Forecast inputs incorporated ISO 30414 adoption curves and SEC enforcement timeline probabilities.
Regulatory enforcement delays, AI capability commoditization, and enterprise budget contraction are the dominant revision risks. Forecasts reflect documented assumptions about compliance mandate timing and technology adoption elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Virtual Client Computing Software Market
Software & Services
Global CMDB Software Market
Software & Services
Personal Budgeting Software Market
Software & Services
Programmable Automation Controller Software Market
Software & Services
Global Server Management Software Market
Software & Services
3D Printing Medical Device Software Market
Software & Services
Exploration and Production Accounting System Software Market
Software & Services
Global Headless CMS Software Market
Software & Services
Europe Application Modernization Services Market
Software & Services
Global Quoting Software Market
Software & Services
Europe Contract Lifecycle Management Software Market
Software & Services
Global Client Portal Software Market
Software & Services
B2B Gateway Software Market
Software & Services
Global Inside Sales Software Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
Intelligent Enterprise Data Capture Software Market