
 Lab Automation Software Market | 2026-2036
Lab Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Lab Automation Software Market Outlook
North American biotech infrastructure is narrowing the gap between research throughput and software orchestration capacity. Thermo Fisher Scientific leverages its instrument-to-cloud connectivity stack to anchor enterprise deployments across multi-site laboratory networks. Danaher Corporation sustains competitive pressure through its Beckman Coulter automation division's tight hardware-software coupling. Agilent Technologies differentiates via chromatography data systems that control third-party peripherals without middleware layers.
Lab automation software comprises executable code, configuration protocols, and application programming interfaces that direct robotic liquid handlers, analytical instruments, and sample storage systems through pre-defined experimental workflows. The software encodes scheduling algorithms, error-handling routines, and audit trails to maintain chain-of-custody documentation across high-throughput screening and quality control operations. Workflow management platforms currently occupy the largest revenue pool as pharmaceutical sponsors demand protocol standardization across contract research organizations. Cloud-based deployment models represent the fastest-expanding segment because biotech startups prioritize operational expenditure models over capital-intensive on-premises installations. SaaS offerings in sample tracking and inventory management are maturing rapidly as vendors consolidate point solutions into unified laboratory information management system architectures.
FDA 21 CFR Part 11 mandates electronic signature validation and audit trail immutability, forcing vendors to embed compliance features as native modules rather than aftermarket plugins. EPA Good Automated Manufacturing Practice guidelines and ISO 15189 medical laboratory accreditation standards further constrain software architecture choices for clinical diagnostic applications. EMA's Annex 11 requirements for computerized systems in GMP environments add validation burden for European deployments. Stakeholders must monitor how emerging EU AI Act risk classification rules treat machine-learning modules embedded in analytical data interpretation workflows.
Market Dynamics
Pharmaceutical sponsors are consolidating contract research organization networks, forcing software vendors to architect multi-tenant platforms that synchronize protocol execution across dispersed laboratory sites under unified compliance frameworks.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature mandates compel pharmaceutical sponsors to replace paper-based batch records with validated software systems, expanding addressable market for compliance-native vendors.
- Cell and gene therapy manufacturing:Complex bioprocessing workflows require orchestration software that tracks patient-specific batches through sterile handling and cryogenic storage operations.
- Boston-San Francisco biotech corridor:Venture-funded startups prioritize cloud-native automation platforms to compress preclinical timelines without capital-intensive infrastructure builds.
Market Restraints
- Validation cost structure:IQ/OQ/PQ documentation requirements for GMP environments consume 18-24 months of implementation budget before production deployment.
- Instrument protocol fragmentation:Proprietary communication standards from major hardware vendors force middleware development that inflates integration timelines.
- Substitution by open-source frameworks:Academic institutions and lean startups adopt Python-based scheduling libraries for non-regulated research, capping price elasticity in basic automation segments.
Strategic Opportunities
- India's CDSCO regulatory alignment:Contract manufacturing organizations serving export markets seek software that bridges domestic and FDA validation requirements.
- AI-embedded analytical interpretation:Machine learning modules for chromatography peak identification and mass spectrometry deconvolution create upsell potential within existing instrument control platforms.
- Subscription revenue models:SaaS pricing for sample tracking and inventory management converts capital expenditure procurement into recurring operational budgets accessible to mid-tier laboratories.
Industry Challenges
- Mechatronics-engineering talent scarcity:Cross-functional teams combining software architecture with liquid handler hardware calibration expertise command premium compensation that strains vendor margins.
- Legacy LIMS integration friction:Decades-old laboratory information management systems lack API-native architectures, forcing costly custom middleware for workflow orchestration.
- EMA Annex 11 validation timelines:European deployments require additional computerized system risk assessments that extend commercialization schedules by 6-9 months relative to US installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab Automation Software Market |
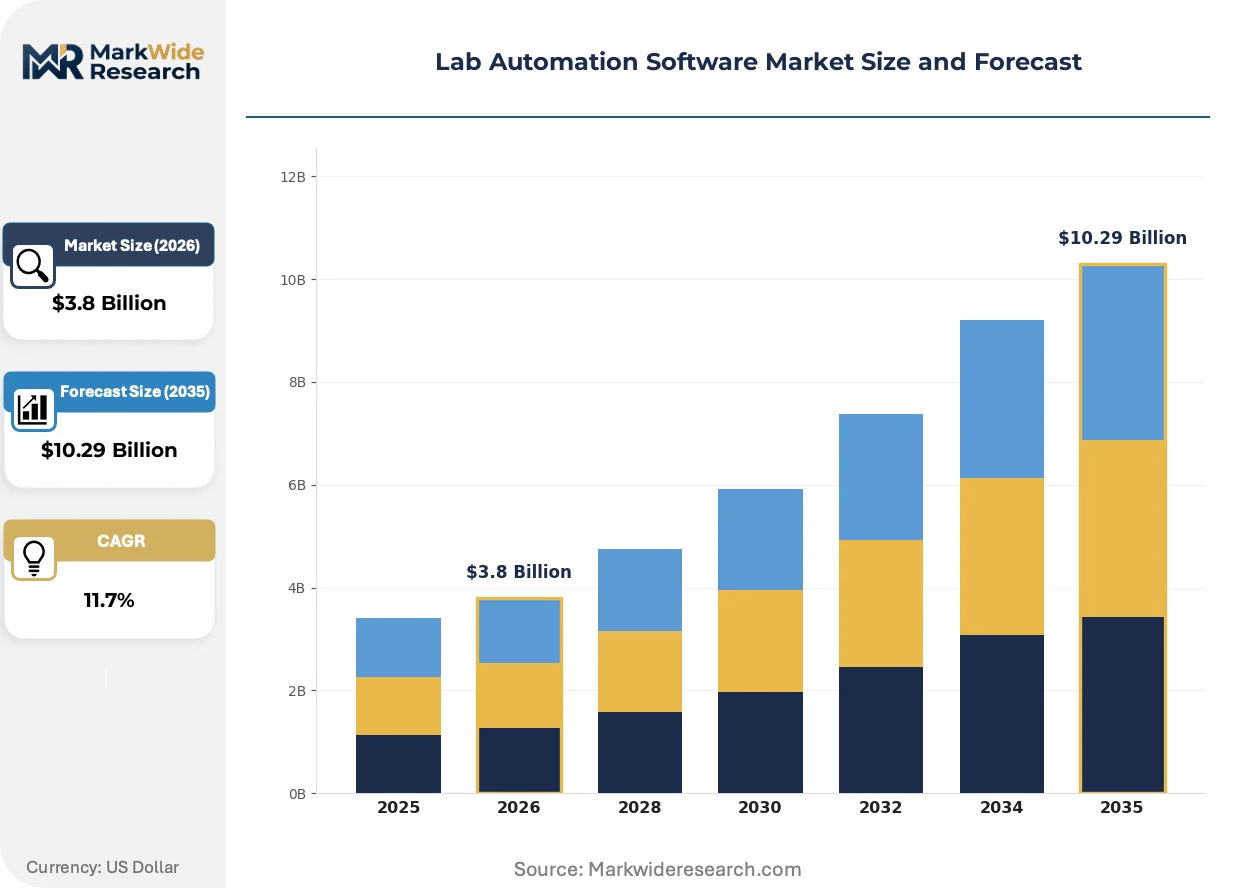
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Workflow Management, Robotics, Data Management, Instrument Integration End User: Pharmaceuticals, Biotechnology, Academic Research, Clinical Laboratories Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS Functionality: Sample Tracking, Data Analysis, Inventory Management, Reporting Tools |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, Agilent Technologies, Tecan Group, PerkinElmer, Hudson Robotics, Becton, Dickinson and Company, Eppendorf AG, Hamilton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab Automation Software Market Strategic Shifts
Software architectures are decoupling from single-vendor instrument ecosystems, enabling laboratories to compose best-of-breed automation stacks through standardized interoperability layers.
Edge computing for real-time instrument control is migrating from on-premises servers to containerized microservices deployed at laboratory sites. Biopharmaceutical quality control laboratories in Germany and Switzerland are piloting these architectures to reduce latency between analytical measurements and batch release decisions. This migration from centralized data center models is compressing the feedback loops between manufacturing execution and regulatory documentation.
The EU AI Act risk classification framework is redefining liability allocation for machine learning modules embedded in analytical data interpretation. Software vendors must now document algorithmic training data provenance and performance validation across intended use conditions. High-risk applications in clinical diagnostic workflows face conformity assessment requirements that favor established vendors with quality management system certifications.
Research sponsors are unbundling automation software procurement from instrument hardware purchases, demanding standalone licensing for workflow orchestration platforms. Contract research organizations in the United Kingdom and Netherlands now issue separate RFPs for scheduling software and liquid handling robotics. This behavioral shift pressures instrument manufacturers to open communication protocols or surrender software revenue to independent platform vendors.
Lab Automation Software Market Segmentation
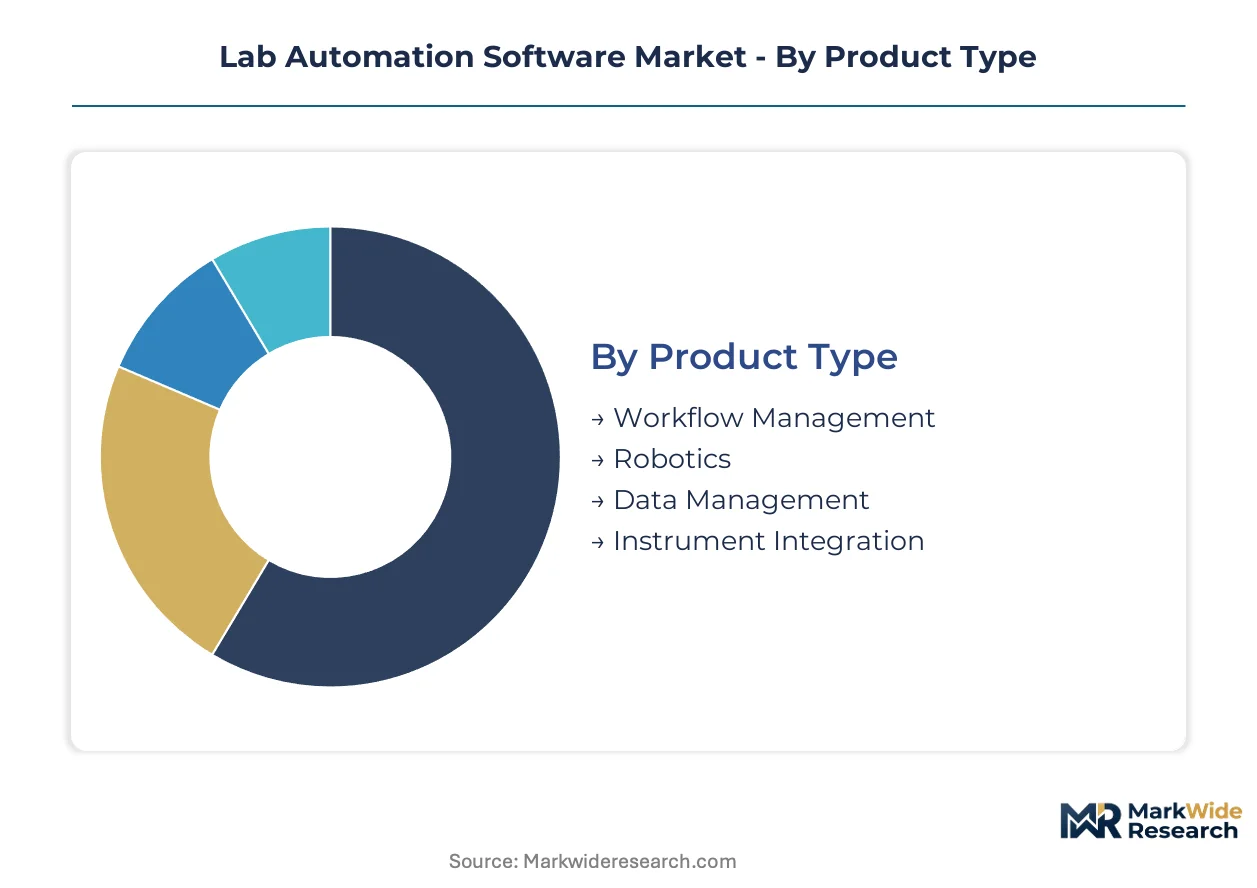
Segmentation in lab automation software reveals how procurement priorities diverge between regulated pharmaceutical sponsors and capital-constrained research institutions. Deployment architecture and functional scope determine pricing architecture, compliance burden, and integration complexity across buyer categories.
Product Type:
Cost tier determines how software procurement maps to capital allocation cycles and operational expenditure budgets across laboratory types.
- Workflow Management:Orchestration platforms encode scheduling algorithms, error-handling routines, and audit trails for high-throughput screening. Pharmaceutical sponsors in Boston and San Francisco demand protocol standardization across contract research organizations, consolidating procurement around unified compliance frameworks.
- Robotics:Control software directs liquid handlers, plate movers, and integrated workcells through pre-defined experimental sequences. Cell and gene therapy manufacturers track patient-specific batches through sterile handling operations, driving demand for closed-loop control systems with cryogenic storage integration.
- Data Management:Chromatography data systems and mass spectrometry informatics platforms with native compliance modules.
- Instrument Integration:Middleware layers bridging proprietary communication standards from major hardware vendors.
Workflow Management commands the established base. The steepest expansion runs through Robotics.
End User:
Customer type shapes validation requirements, pricing elasticity, and cloud-readiness across the demand spectrum.
- Pharmaceuticals:Enterprise sponsors replace paper-based batch records with validated software systems under FDA 21 CFR Part 11 mandates. IQ/OQ/PQ documentation consumes 18-24 months of implementation budget before production deployment, favoring vendors with native compliance architectures.
- Biotechnology:Venture-funded startups prioritize operational expenditure models over capital-intensive infrastructure builds. Cloud-native automation platforms compress preclinical timelines without requiring on-premises server investments.
- Academic Research:Python-based scheduling libraries and open-source frameworks cap price elasticity in basic automation segments.
- Clinical Laboratories:ISO 15189 accreditation standards and EPA Good Automated Manufacturing Practice guidelines constrain software architecture choices.
Pharmaceuticals anchors revenue concentration. Biotechnology climbs the fastest as venture funding flows into Boston-San Francisco corridor startups.
Deployment Model:
Maturity stage of infrastructure investment determines how laboratories balance control, latency, and capital efficiency.
- Cloud-Based:Containerized microservices deployed at laboratory sites reduce latency between analytical measurements and batch release decisions. Biopharmaceutical quality control laboratories in Germany and Switzerland pilot these architectures to compress feedback loops between manufacturing execution and regulatory documentation.
- SaaS:Subscription pricing for sample tracking and inventory management converts capital expenditure procurement into recurring operational budgets accessible to mid-tier laboratories.
- On-Premises:Legacy installations serving decades-old laboratory information management systems lacking API-native architectures.
- Hybrid:Architectures segregating regulated data on-premises while pushing non-critical workloads to cloud infrastructure.
On-Premises retains the installed base. Cloud-Based gains share fastest as biotech startups reject capital-intensive infrastructure builds.
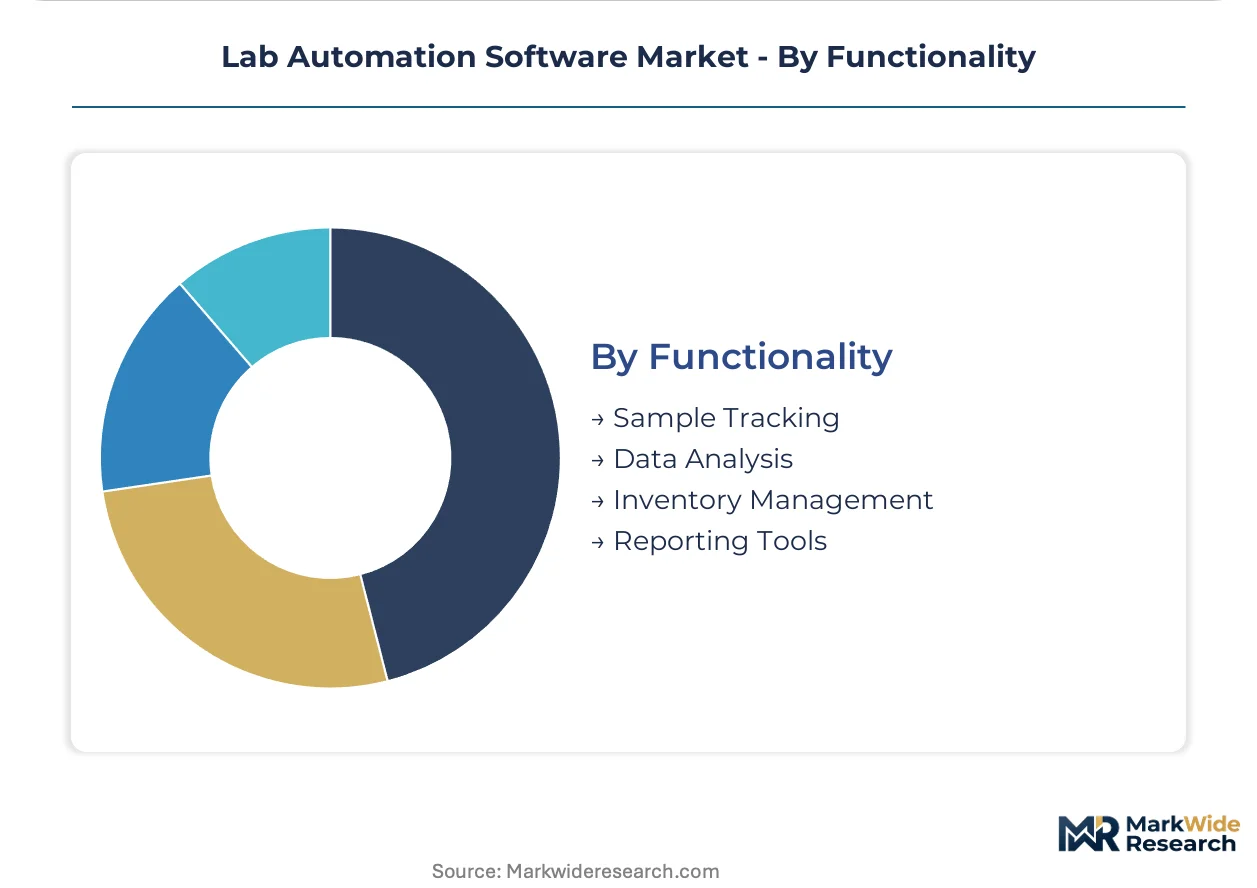
Functionality:
Application criticality within the experimental lifecycle determines integration depth and pricing premium.
- Sample Tracking:Chain-of-custody documentation maintaining audit trail immutability across high-throughput screening operations. Contract research organizations demand multi-tenant platforms synchronizing protocol execution across dispersed laboratory sites.
- Data Analysis:Machine learning modules for chromatography peak identification and mass spectrometry deconvolution face EU AI Act conformity assessment requirements. High-risk applications in clinical diagnostic workflows favor established vendors with quality management system certifications.
- Inventory Management:SaaS offerings consolidating point solutions into unified laboratory information management system architectures.
- Reporting Tools:Electronic signature validation and batch record generation for FDA submission packages.
Sample Tracking holds the dominant position. Data Analysis expands most quickly as AI-embedded analytical interpretation creates upsell potential within existing instrument control platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature pharmaceutical markets with legacy compliance burdens and emerging biotech clusters prioritizing cloud-native deployment speed over validation depth.
United States
FDA 21 CFR Part 11 mandates drive enterprise replacement of paper batch records with validated software systems across Massachusetts and California biotech corridors. Venture-funded startups in Greater Boston and San Francisco Bay Area compress preclinical timelines through SaaS automation platforms that bypass capital-intensive infrastructure builds.
Germany
Biopharmaceutical quality control laboratories in Bavaria and North Rhine-Westphalia pilot containerized microservices architectures to reduce latency between analytical measurements and batch release decisions. EMA Annex 11 computerized system risk assessments extend commercialization schedules by 6-9 months relative to US installations.
Switzerland
Swissmedic oversight of clinical diagnostic workflows favors established vendors with ISO 13485 quality management system certifications for machine learning modules. Basel and Zurich pharmaceutical clusters demand orchestration software tracking patient-specific batches through sterile handling and cryogenic storage operations in cell and gene therapy manufacturing.
India
Contract manufacturing organizations in Maharashtra and Gujarat serving export markets seek software bridging CDSCO domestic requirements with FDA validation standards. CDSCO regulatory alignment initiatives create procurement windows for multi-tenant platforms synchronizing protocol execution across dispersed laboratory sites.
United Kingdom
Contract research organizations in London and Cambridge unbundle automation software procurement from instrument hardware purchases through separate RFPs for scheduling platforms and liquid handling robotics. MHRA post-Brexit regulatory divergence pressures vendors to maintain dual validation documentation tracks for EU and UK market access.
Lab Automation Software Market Competitive Environment
Capability concentration sits with instrument-native software architects; scale advantage sits with independent platform vendors decoupling orchestration from hardware ecosystems. The market structures around three tiers: diversified life science conglomerates with embedded software divisions, pure-play automation specialists, and emerging cloud-native entrants. Consolidation pressure intensifies as pharmaceutical sponsors demand unified compliance frameworks across multi-site CRO networks. Strategic moves center on protocol standardization partnerships and API-native architecture investments that reduce middleware dependency.
Among diversified conglomerates, Thermo Fisher Scientific, Danaher Corporation, and Agilent Technologies exemplify contrasting competitive positions. Thermo Fisher leverages its instrument-to-cloud connectivity stack to anchor enterprise deployments. Danaher sustains pressure through tight hardware-software coupling within its Beckman Coulter automation division. Agilent differentiates via chromatography data systems controlling third-party peripherals without middleware layers, representing the decoupling strategy that independent platform vendors increasingly emulate.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| Agilent Technologies |
| Tecan Group |
| PerkinElmer |
| Hudson Robotics |
| Becton, Dickinson and Company |
| Eppendorf AG |
| Hamilton Company |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific shipping lanes from Shanghai to Los Angeles transmit container cost volatility directly into software licensing negotiations, compressing margins for vendors dependent on Asian hardware sourcing while amplifying price differentiation between cloud-native SaaS tiers and on-premises perpetual license models.
Pricing Analysis
Geographic price spreads between Massachusetts biotech clusters and Gujarat contract manufacturing zones exceed 40 percent for equivalent workflow orchestration platforms. Three-tier pricing structure across premium compliance-native, standard validated, and economy non-regulated levels dominates procurement. Price differentiation hinges on FDA 21 CFR Part 11 certification grade and embedded AI module depth. Pricing pressure stems from open-source Python scheduling libraries capping elasticity in academic segments. Biotechnology startups exhibit highest price sensitivity; pharmaceutical quality control laboratories demonstrate lowest.
Supply Chain Analysis
Upstream feedstock concentration in semiconductor fabrication for instrument control boards centers on Taiwan, South Korea, and the United States. Software vendors draw from specialized chipsets, precision motion controllers, and cloud infrastructure services as core inputs. Single-source vulnerability in advanced GPU supply for machine learning modules creates procurement risk. Distribution runs through direct enterprise sales teams for pharmaceutical sponsors and channel partners serving mid-tier laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
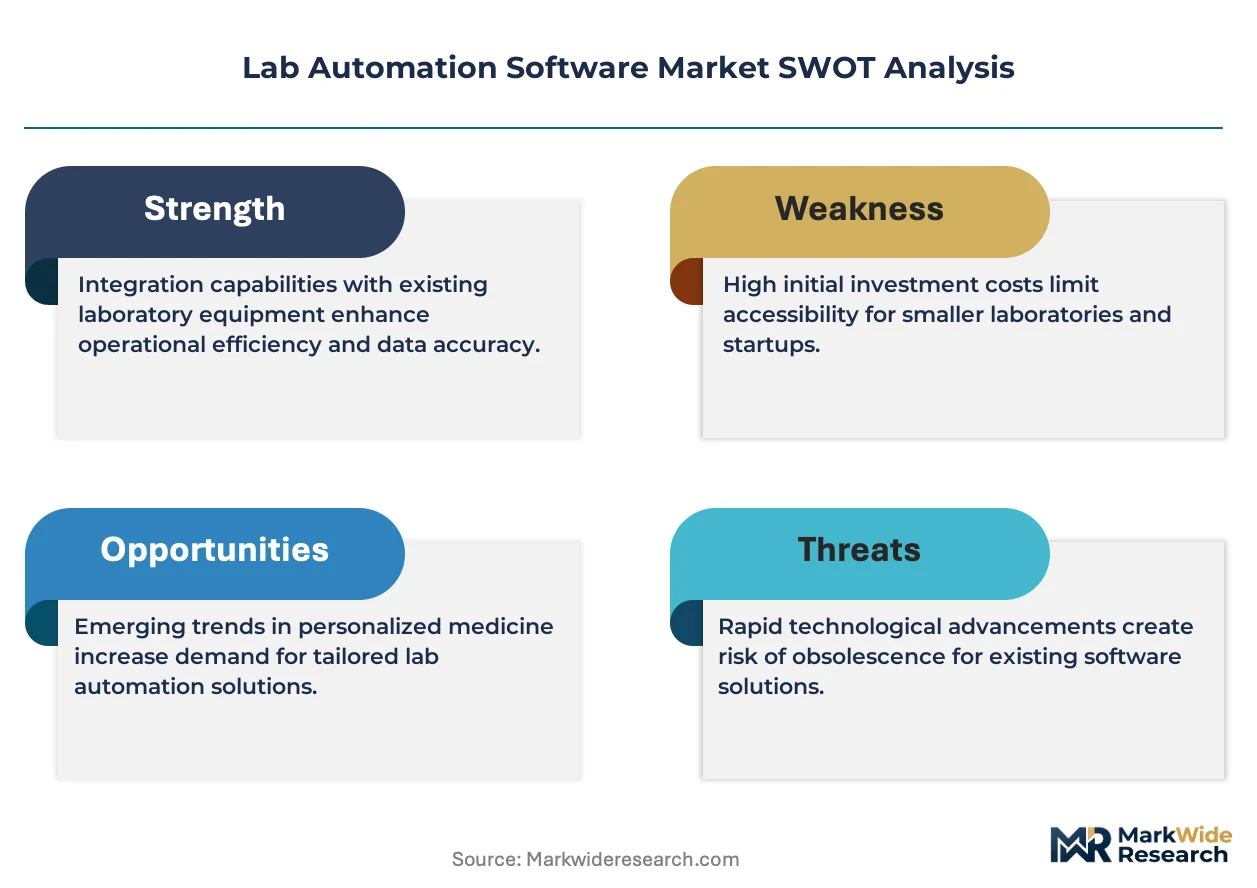
Lab automation software is recovering from a cyclical trough as pharmaceutical R&D budgets expand post-patent-cliff compression, with venture funding into Boston-San Francisco biotech corridors driving replacement demand for legacy LIMS architectures.
For Market Incumbents: Build switching-cost moats through native compliance architectures that embed FDA 21 CFR Part 11 validation as non-transferable institutional knowledge. Deepen API-native platform investments to reduce middleware dependency against emerging cloud-native entrants. Anchor multi-tenant deployments across consolidated CRO networks to capture protocol standardization mandates. For New Entrants and Emerging Players: India's CDSCO regulatory alignment gaps present underpenetrated procurement windows for software bridging domestic and FDA validation requirements. Target mid-tier contract manufacturing organizations in Maharashtra and Gujarat with SaaS pricing models that convert capital expenditure barriers into operational budgets. Pursue partnership-led go-to-market strategies with regional system integrators possessing existing pharmaceutical relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to monetize non-core software divisions amid portfolio rationalization pressures. Five-to-ten year viability favors vendors with quality management system certifications navigating EU AI Act conformity assessments. Monitor EMA Annex 11 validation timeline extensions as early signals of vendor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance-Native Architecture Investment | FDA 21 CFR Part 11 embedded modules reduce IQ/OQ/PQ documentation burdens for pharmaceutical sponsors. |
| Multi-Tenant Platform Deployment | Synchronizes protocol execution across dispersed CRO sites under unified audit frameworks. |
| AI Module Integration | Chromatography peak identification algorithms face EU AI Act risk classification scrutiny. |
| Cloud-Native SaaS Transition | Converts capital expenditure procurement into recurring revenue accessible to venture-funded startups. |
| API-First Interoperability Expansion | Decouples orchestration software from single-vendor instrument ecosystems for best-of-breed stacking. |
Study Parameters
Operator-level perspectives from laboratory informatics directors, regulatory affairs specialists, CRO procurement managers, and cloud infrastructure architects anchored the qualitative base. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA Annex 11 computerized system guidelines, ISO 15189 accreditation standards, and SEC filings of publicly traded life science conglomerates. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Scenario-bracketing framed demand projections across the modeling period. Segmentation dimensions included deployment architecture, end-user organization type, functional application scope, and regional regulatory cluster. CAGRs derived from instrument installation base growth, pharmaceutical R&D expenditure patterns, and cloud adoption velocity curves. Cell and gene therapy manufacturing expansion and EU AI Act implementation timelines served as industry-specific forecast inputs.
Practitioners should monitor CDSCO regulatory alignment progress, EMA validation timeline shifts, and venture funding flows into Boston-San Francisco biotech corridors for early signals requiring forecast revision. Cross-checking against pharmaceutical R&D budget disclosures and CRO consolidation announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Software Publishers Market
Software & Services
Remote Desktop Software Market
Software & Services
Photobooth Software Market
Software & Services
Digital Painting Software Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
Electronic Design Automation Software Market
Software & Services
Augmented Reality Software Development Kit Market
Software & Services
Enterprise Search Software Market
Software & Services
Global Development Tools Software Market
Software & Services
Collaborative Whiteboard Software Market
Software & Services
Torque Software Market
Software & Services
Middle-East Virtual Data Room Market
Software & Services
Global Ipad POS Software Market
Software & Services
Social Software As a Collaborative ERP Tool Market
Software & Services
Smartphone OS Market
Software & Services
Global Employee Recognition Software Market