
 Microsoft Office 365 Integration Services Market | 2026-2036
Microsoft Office 365 Integration Services Market Size, Share, and Industry Trends Forecast 2026-2036
Microsoft Office 365 Integration Services Market Foresight
North American cloud infrastructure providers is repositioning integration service delivery toward API-first architectures. Microsoft anchors enterprise-grade connectivity through native Graph API capabilities across Exchange Online and SharePoint. Zapier competes in the small-business segment with low-code connector libraries. Boomi specializes in hybrid deployment scenarios that bridge legacy ERP with Office 365 endpoints.
Microsoft Office 365 Integration Services encompass the design, deployment, and management of middleware that synchronizes data, applications, and workflows across the Office 365 ecosystem and external systems, typically operating through REST APIs, OAuth authentication protocols, and event-driven webhook architectures. These services enable real-time document collaboration, automated email routing, and unified identity management for commercial and institutional users. Cloud Integration leads service type revenue as enterprises migrate Exchange and Teams workloads to Azure-backed infrastructure. Workflow Automation captures the fastest expansion within industry verticals, particularly in healthcare and finance where robotic process automation reduces manual data entry. Small Businesses represent an emerging client type segment as subscription-based pricing models lower barriers to connector deployment.
The US HIPAA Security Rule shapes healthcare data integration requirements by mandating encrypted transmission and access logging for any Office 365-connected system handling protected health information. The EU AI Act imposes transparency obligations on automated decision-making workflows built through Power Automate and Copilot integrations, affecting cross-border service architectures. Stakeholders must monitor how NIST cybersecurity framework updates and emerging state-level data privacy statutes in California and Virginia will alter compliance costs for multi-tenant integration platforms.
Market Dynamics
Healthcare providers are consolidating cloud infrastructure around Microsoft 365 ecosystems, forcing integration service vendors to rebuild middleware stacks for HIPAA-compliant data exchange and real-time patient workflow automation.
Growth Catalysts
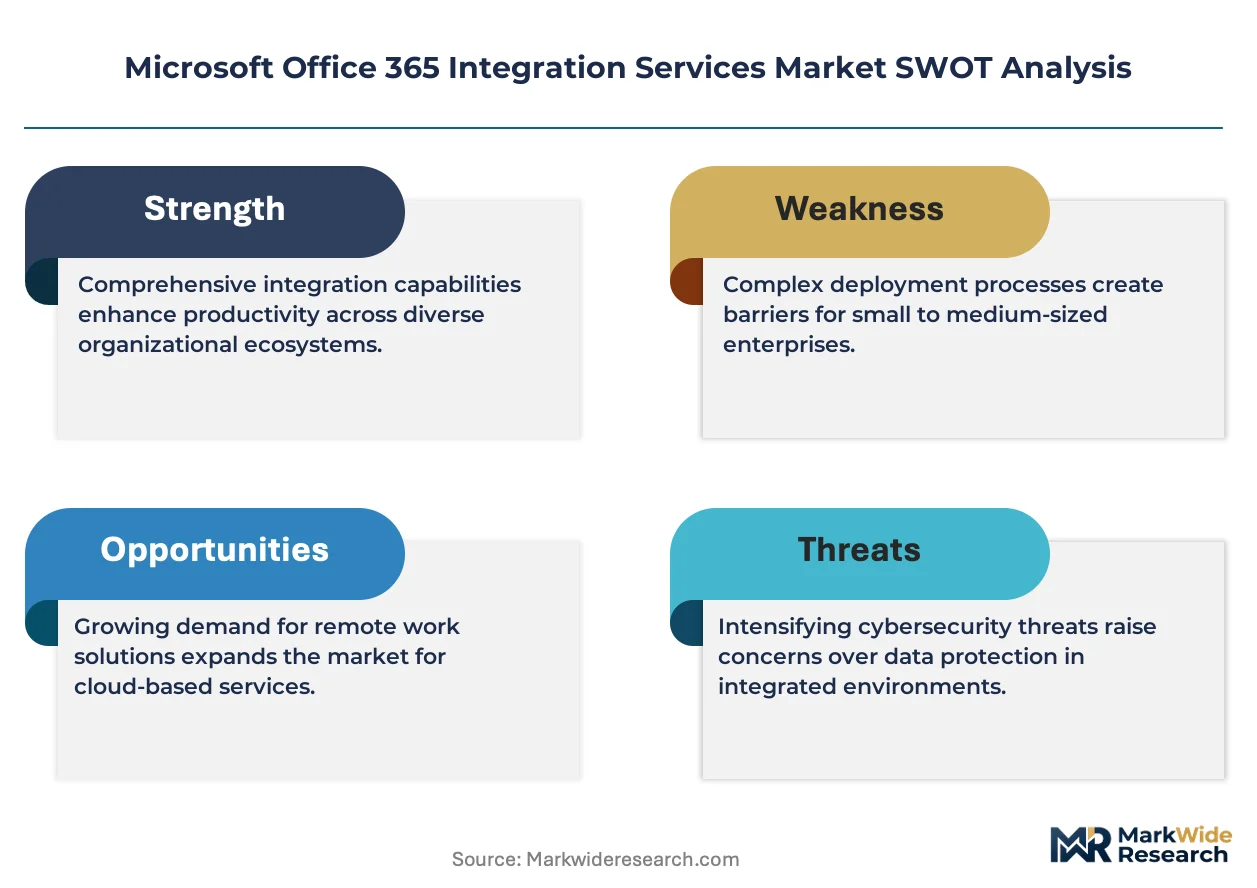
- HIPAA Security Rule mandates:Encrypted transmission requirements for protected health information are expanding the addressable market for compliant middleware solutions in US hospital systems.
- Power Automate adoption:Finance operations teams are deploying robotic process automation to eliminate manual data entry between Excel Online and external ERP systems.
- Small business cloud migration:Subscription-based connector pricing is lowering deployment barriers for professional services firms replacing on-premise Exchange servers.
Market Restraints
- API rate limiting:Microsoft Graph API throttling constraints create bottlenecks for high-volume data synchronization workloads in enterprise environments.
- OAuth token complexity:Multi-factor authentication flows increase implementation timelines and require specialized identity management expertise.
- Hybrid infrastructure drag:Legacy on-premise SharePoint farms in regulated industries resist full cloud migration, fragmenting integration architectures.
Strategic Opportunities
- EU AI Act compliance services:Transparency obligations for automated decision-making workflows create demand for audit-ready Power Automate governance tooling.
- Teams telephony integration:Voice-enabled collaboration platforms are converging with contact center infrastructure, opening new connector development verticals.
- India SME digitization:The country's PLI scheme incentives for IT adoption are accelerating Office 365 uptake among manufacturing exporters requiring supply chain integration.
Industry Challenges
- Webhook reliability engineering:Event-driven architectures require 24/7 monitoring capabilities that strain mid-tier service provider operational capacity.
- Cross-tenant data isolation:Multi-customer integration platforms face architectural complexity maintaining strict boundaries between client environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microsoft Office 365 Integration Services Market |
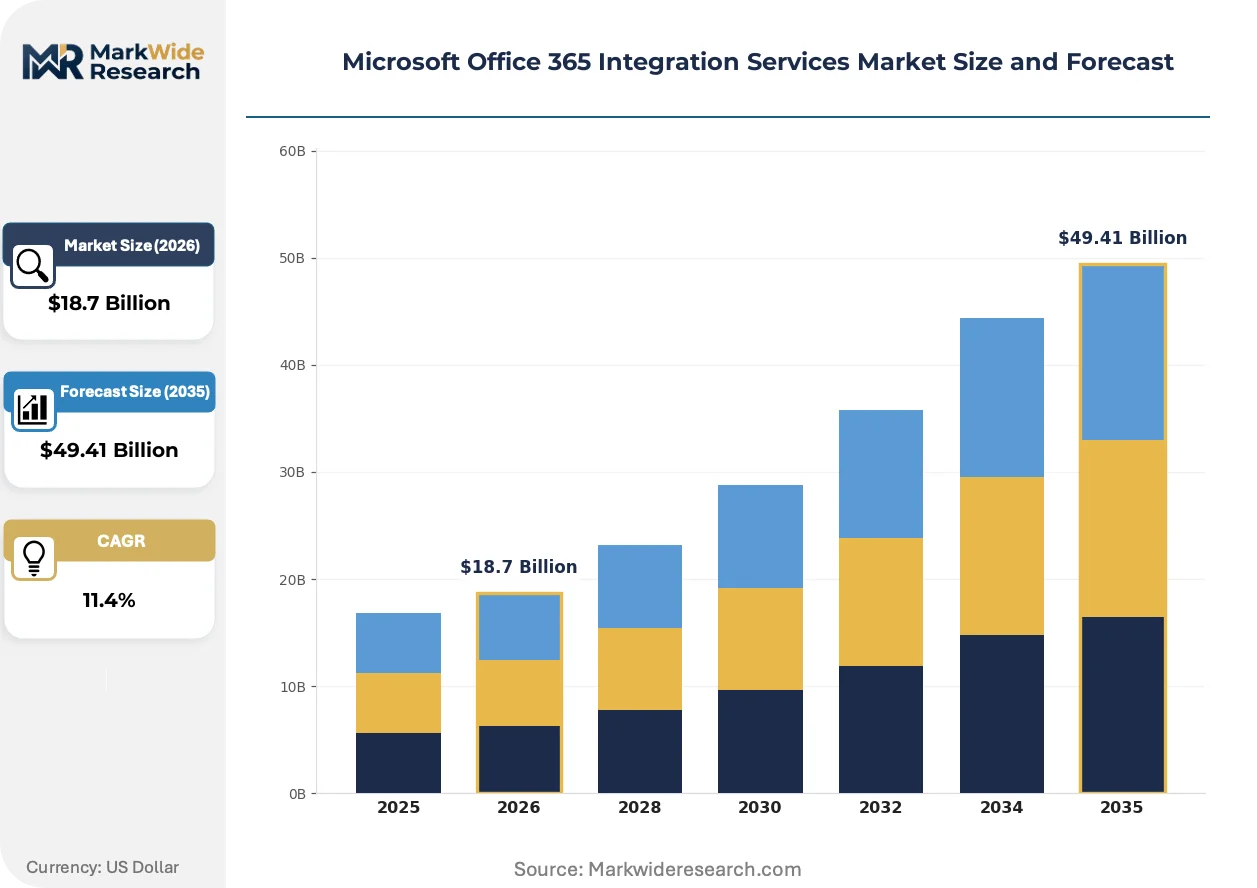
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Integration, Application Integration, Data Integration, Workflow Automation Industry Vertical: Healthcare, Education, Finance, Legal Client Type: Small Businesses, Medium Enterprises, Large Corporations, Nonprofits Deployment Model: On-Premises, Cloud-Based, Hybrid, Multi-Cloud |
| Companies Covered | Zapier, Boomi, Microsoft, Talend, Informatica, Victrix Solutions, Workato, Celigo, MuleSoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microsoft Office 365 Integration Services Market Shifts & Advancements
Artificial intelligence capabilities are embedding directly into integration middleware, compressing development cycles and enabling natural language configuration of complex data flows between Office 365 applications.
Copilot Studio is integrating custom connector development into conversational interfaces, allowing healthcare IT departments to build patient data workflows without dedicated engineering resources. Hospital systems in the United States are piloting these tools to automate referral documentation between Teams and electronic health record systems. The technology is integrating previously siloed clinical and administrative processes into unified automation pipelines.
The EU AI Act imposes documentation requirements on automated workflows processing personal data, compelling European enterprises to retrofit existing Power Automate implementations with explainability logging. Financial services firms in Germany and France are deploying middleware with built-in decision audit trails to preempt regulatory scrutiny. This restructuring is concentrating integration vendor selection around providers with pre-certified compliance architectures.
Consumption-based pricing models are displacing perpetual licensing for connector deployment, with enterprise procurement teams negotiating per-transaction fees rather than seat-based subscriptions. Managed service providers are capturing margin by bundling monitoring and support into usage-based contracts. This shift is most pronounced in the United Kingdom professional services sector, where seasonal workflow volatility makes fixed costs economically unattractive.
Microsoft Office 365 Integration Services Market Segmentation
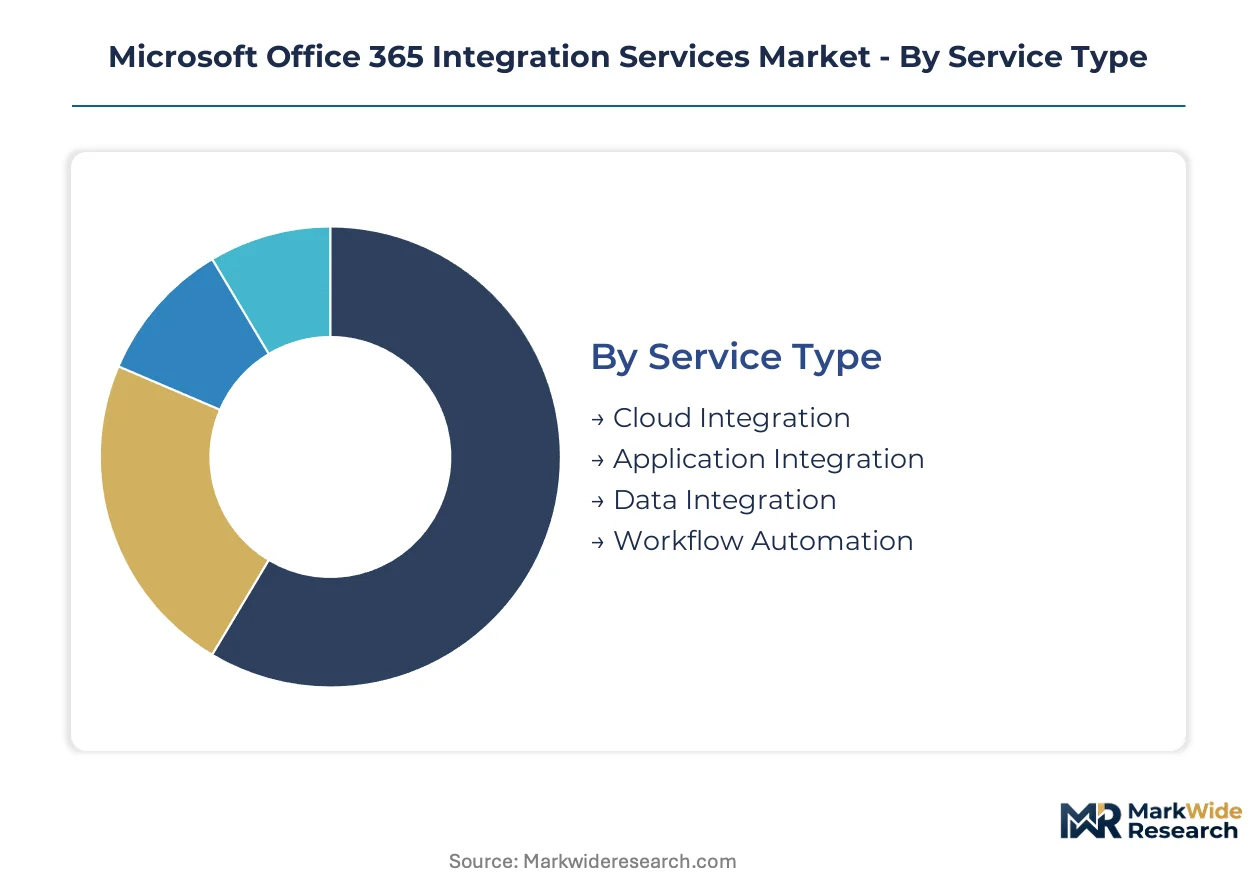
Microsoft Office 365 Integration Services vendors structure offerings around workload migration patterns and compliance complexity. Segmentation reveals where middleware investments concentrate and which customer profiles drive connector innovation.
Service Type:
Upgrade cycles from legacy Exchange servers to cloud-native architectures determine service packaging and pricing structures across this category.
- Cloud Integration:Services migrate on-premise Exchange, SharePoint, and Teams workloads to Azure-backed infrastructure with native Graph API orchestration. US hospital systems dominate demand as HIPAA Security Rule mandates accelerate decommissioning of self-hosted email servers.
- Workflow Automation:Robotic process automation connectors eliminate manual data transfer between Excel Online, Power Automate, and external ERP systems. Finance operations teams in Germany and France deploy these most aggressively under EU AI Act documentation requirements for automated decision trails.
- Application Integration:Middleware synchronizes third-party SaaS tools with Office 365 calendars, contacts, and document libraries.
- Data Integration:ETL pipelines consolidate fragmented information sources into SharePoint Online and OneDrive repositories.
Volume placements concentrate in Cloud Integration; the faster expansion belongs to Workflow Automation.
Industry Vertical:
Compliance cost tiers separate vertical adoption curves, with regulated industries absorbing premium pricing for certified middleware architectures.
- Healthcare:HIPAA-mandated encryption and access logging requirements shape integration specifications for patient data exchange between Teams and electronic health record systems. US hospital networks in Texas, California, and New York represent the largest procurement pools as health systems consolidate cloud infrastructure.
- Finance:SEC audit trails and GDPR cross-border data rules demand immutable logging for Power Automate workflows processing transaction data. German and French banking groups lead European deployment of compliance-certified connector platforms.
- Legal:Matter management systems require tamper-proof document versioning across SharePoint Online and practice management software.
- Education:Student information system integration follows semester-cycle procurement patterns with heavy summer deployment windows.
Healthcare captures the steepest expansion trajectory as HIPAA enforcement tightens; Finance maintains the deepest volume concentration.
Client Type:
Customer maturity and internal IT capacity dictate whether buyers prefer managed service bundles or self-service connector deployment.
- Large Corporations:Dedicated integration teams demand custom Graph API development and 24/7 webhook monitoring for high-availability document collaboration pipelines. These buyers negotiate enterprise-wide Microsoft EA amendments that bundle integration services with core licensing.
- Small Businesses:Subscription-based connector libraries through Zapier and Microsoft AppSource lower deployment barriers for professional services firms replacing aging on-premise Exchange servers. Seasonal workflow volatility in UK accounting practices makes consumption-based pricing economically attractive.
- Medium Enterprises:Hybrid IT departments split workloads between managed service providers and in-house Power Platform administrators.
- Nonprofits:Microsoft grant pricing and TechSoup eligibility shape procurement timelines around fiscal year funding cycles.
Large Corporations anchor current revenue; Small Businesses are climbing the fastest as seat-based pricing erodes.
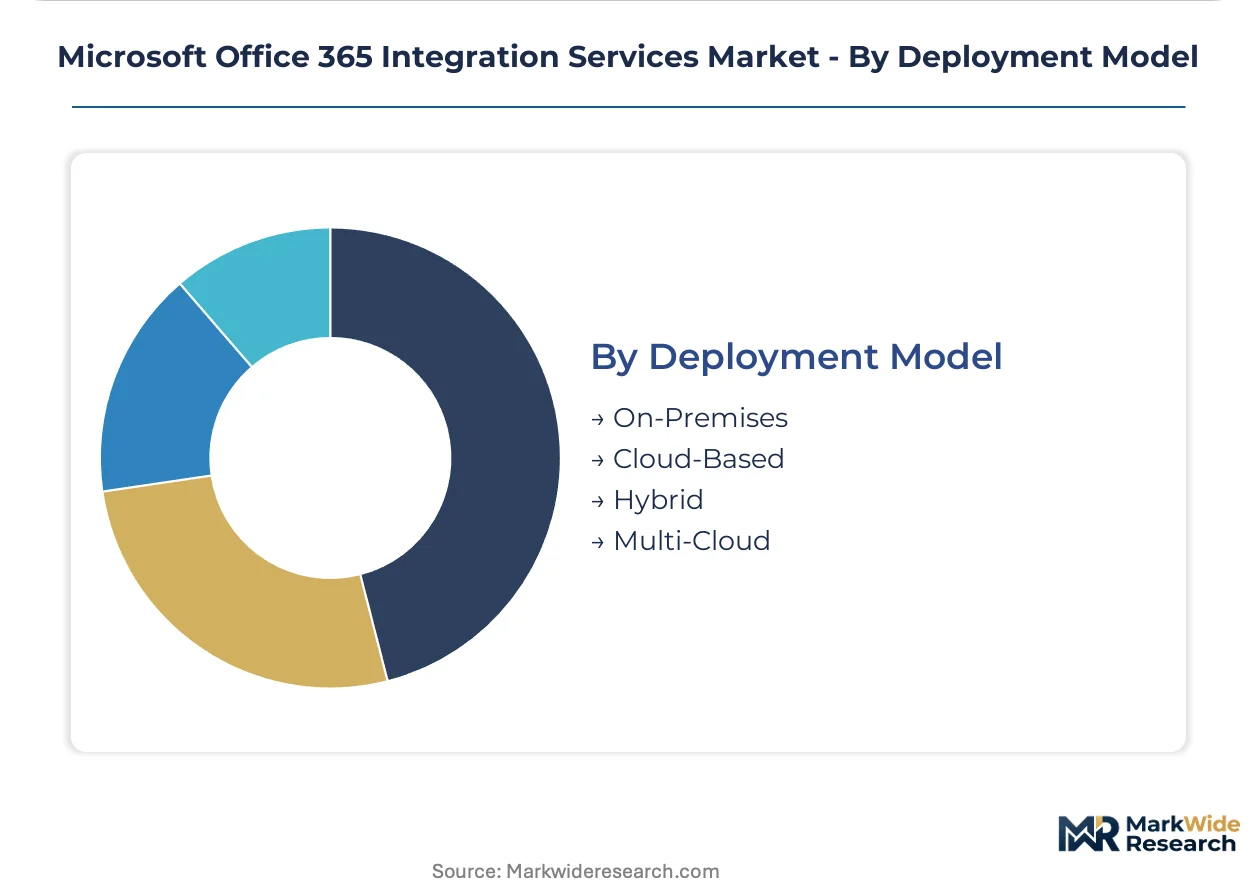
Deployment Model:
Residual on-premise infrastructure and data residency requirements fragment architecture choices across customer environments.
- Hybrid:Bridging configurations connect legacy SharePoint farms to cloud-native Teams and Exchange Online endpoints. Regulated manufacturers in India and Germany maintain this architecture to satisfy local data sovereignty rules while enabling mobile collaboration.
- Cloud-Based:Pure SaaS integration through Azure Logic Apps and Power Automate serves born-digital professional services firms with no legacy server footprint. UK legal and consulting sectors dominate this segment due to aggressive cloud-first procurement mandates.
- On-Premises:Self-hosted integration runtimes persist in defense and classified government environments with air-gapped security requirements.
- Multi-Cloud:AWS and Google Cloud co-existence strategies require cross-platform identity federation and unified logging.
Hybrid deployments retain the largest installed base; Cloud-Based configurations are gaining share fastest as legacy servers reach end-of-support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure density in the United States anchors regional deployment patterns for Office 365 integration services. Enterprise consolidation around Microsoft ecosystems drives middleware investment across North America, Europe, and Asia-Pacific markets.
United States
HIPAA Security Rule mandates and SEC audit requirements propel healthcare and finance sector adoption. Texas, California, and New York hospital networks dominate procurement for patient data exchange middleware. Boston-based health systems pilot Copilot Studio integrations for clinical workflow automation.
Germany
EU AI Act transparency obligations and GDPR cross-border data rules reshape Power Automate implementations. Frankfurt and Munich banking groups deploy compliance-certified connector platforms with immutable decision logging. Baden-Württemberg manufacturers maintain hybrid architectures for data sovereignty compliance.
United Kingdom
Consumption-based pricing models gain traction among London professional services firms with seasonal workflow volatility. FCA regulatory expectations drive audit-ready governance tooling for automated financial workflows. Southeast England consulting practices lead cloud-native integration adoption.
India
PLI scheme incentives for IT adoption accelerate Office 365 uptake among manufacturing exporters. Maharashtra and Karnataka technology corridors drive supply chain integration demand for SME digitization. Mumbai-based exporters require middleware connecting Teams to customs and logistics platforms.
Japan
METI digital transformation guidelines encourage cloud migration among legacy-heavy enterprises. Tokyo and Osaka financial institutions invest in robotic process automation for Excel Online ERP connectivity. Kanto region manufacturers bridge on-premise legacy systems with cloud-native collaboration endpoints.
Microsoft Office 365 Integration Services Market Competitive Landscape
Global majors compete with regional champions across middleware architecture and compliance specialization. The vendor base stratifies into three tiers: native platform providers with deep Graph API access, independent integration specialists with multi-cloud connectivity, and low-code connector libraries targeting price-sensitive segments. Dominant competitive moves include API-first product repositioning and vertical-specific compliance certification bundling.
Within the native platform tier, Microsoft anchors enterprise-grade connectivity through Azure-backed infrastructure. Among independent specialists, Boomi and MuleSoft occupy positions bridging legacy ERP with cloud-native endpoints. Zapier exemplifies the low-code segment with subscription-based pricing for small-business connector deployment.
| Leading Market Players |
|---|
| Zapier |
| Boomi |
| Microsoft |
| Talend |
| Informatica |
| Victrix Solutions |
| Workato |
| Celigo |
| MuleSoft |
| Others |
Supply & Pricing Matrix
Azure-certified integration architects concentrated in Bangalore and Hyderabad create labor-cost differentials that separate premium-tier managed services from self-service connector deployments. This workforce geography compresses margin spreads for mid-tier vendors while inflating pricing power for specialized HIPAA-compliance boutiques in Boston and Frankfurt.
Pricing Analysis
Warranty and 24/7 webhook monitoring bundling distinguishes enterprise contracts from unbundled self-service tiers. Consumption-based per-transaction pricing is displacing seat-based subscriptions across UK professional services firms, while HIPAA-certified middleware commands premium spreads due to audit-ready documentation requirements. Price differentiation rests on compliance certification tier and integration complexity scale. Cost compression in the small-business segment intensifies as Zapier and Microsoft AppSource commoditize basic connector libraries.
Supply Chain Analysis
Azure cloud infrastructure engineers and OAuth identity specialists cluster in India, Ireland, and the Pacific Northwest, creating talent pipeline constraints for mid-tier service providers. Middleware development draws from open-source Graph API libraries, proprietary Azure Logic Apps runtimes, and third-party webhook monitoring tools. Single-source vulnerability around Microsoft's API roadmap decisions threatens vendor business model stability. Distribution runs through direct enterprise sales teams, Microsoft partner networks, and managed service provider channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase as AI-native Copilot Studio configurations replace legacy Power Automate manual development workflows.
For Market Incumbents: Anticipate margin compression from low-code platform commoditization by deepening vertical integration into healthcare-specific compliance tooling. Defensive consolidation around pre-certified HIPAA and EU AI Act architectures protects against emerging pure-play AI workflow vendors. Channel control through Microsoft EA bundling remains the critical retention lever. For New Entrants and Emerging Players: Enter via the India SME manufacturing segment where PLI scheme incentives accelerate Office 365 uptake but integration vendor penetration remains shallow. White-space opportunity concentrates in supply chain middleware connecting Teams to customs and logistics platforms. Go-to-market leverage rests with consumption-based pricing that mirrors seasonal export documentation cycles. For Investors and Strategic Acquirers: Re-rating potential sits with vertical-specific compliance boutiques given EU AI Act transparency obligation enforcement. Long-term viability favors acquisition targets with pre-certified healthcare and finance middleware architectures rather than horizontal connector libraries. Watch Power Automate governance tooling procurement velocity as inflection signal for compliance-service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Copilot Studio Custom Connector Development | Conversational AI interfaces compress healthcare IT deployment timelines without dedicated engineering resources. |
| EU AI Act Compliance Certification | Pre-certified middleware architectures capture German and French banking procurement concentration. |
| Healthcare-Specific HIPAA Middleware | Texas and California hospital networks prioritize encrypted patient data exchange between Teams and EHR systems. |
| Consumption-Based Pricing Repositioning | Per-transaction models align with UK accounting practice seasonal workflow volatility. |
| India SME Supply Chain Integration | Maharashtra manufacturing exporters require middleware connecting Teams to customs and logistics platforms. |
Research Methodology
SEC 10-K filings, Microsoft quarterly capex disclosures, and healthcare GPO contract databases formed the secondary backbone for market sizing validation. Primary interviews with Office 365 integration specialists, healthcare IT procurement managers, Azure platform engineers, and Microsoft partner network directors combined with bottom-up service provider revenue triangulation and top-down enterprise IT spend allocation analysis.
Historical trendline analysis across cloud migration velocity and workflow automation adoption curves anchored projection modeling. Segmentation dimensions included service type complexity, industry vertical compliance tier, client type IT maturity, and deployment model architecture. CAGRs were derived from fitted growth curves calibrated against Azure Active Directory tenant expansion rates and Power Automate monthly active user trajectories.
Revisions become necessary when Microsoft Graph API throttling policy changes, HIPAA enforcement action intensity shifts, or EU AI Act implementation timeline adjustments materialize. Forecasts reflect documented assumptions regarding cloud infrastructure migration pace and regulatory compliance cost absorption capacity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Business Software Market
Software & Services
Jobsite Management Software Market
Software & Services
Global Disclosure Management Software Market
Software & Services
Europe Enterprise Resource Planning (ERP) Software Market
Software & Services
Automotive Digital Retailing Software Market
Software & Services
Orchestration Tools Market
Software & Services
Pure Play Software Testing Market
Software & Services
Proxy Services and Software Market
Software & Services
Multiphysics Software Market
Software & Services
Cloud Backup and Recovery Software Market
Software & Services
Auto Software Market
Software & Services
Enterprise Performance Management (EPM) Software Market
Software & Services
Global ERP Software Market
Software & Services
Global Product Management and Road Mapping Tool Market
Software & Services
Business Rules Management System Market
Software & Services
Global Project Software Market