
 Desktop Hypervisor Market | 2026-2036
Desktop Hypervisor Market Size, Share, and Industry Trends Forecast 2026-2036
Desktop Hypervisor Market Analysis
Enterprise IT departments are redrawing procurement priorities for desktop hypervisor platforms as government agencies and educational institutions accelerate replacement cycles. VMware (Broadcom) leverages its entrenched channel relationships with federal contractors to sustain recurring license renewals. Microsoft anchors its position through bundling Hyper-V with Windows enterprise agreements, while Citrix Systems competes on remote application delivery integration.
A desktop hypervisor is a software layer that creates and manages isolated virtual machines on endpoint hardware, typically supporting x86-64 architectures with allocated RAM pools of 4-32 GB per instance and processor virtualization extensions such as Intel VT-x or AMD-V. Its primary commercial purpose is to consolidate multiple operating environments onto single physical workstations, reducing hardware sprawl and simplifying patch management across heterogeneous software estates. Proprietary licensing still dominates revenue pools, though open-source alternatives are capturing developer-centric segments where snapshot support and virtual networking feature sets drive selection criteria. Cloud-integrated deployment models are expanding fastest among enterprises rebuilding post-pandemic infrastructure, while standalone on-premises installations retain primacy in regulated sectors where data sovereignty requirements block offloading to hyperscaler environments.
FCC guidelines on communications infrastructure security, NIST SP 800-53 controls, and GDPR data residency mandates collectively shape product roadmaps by requiring encrypted virtual machine migration paths and geographic boundary enforcement. ISO 27001 certification has become a baseline qualifier for vendor shortlists in European and North American public sector tenders. Stakeholders must weigh the trajectory of Broadcom's VMware pricing restructuring against parallel investments in Proxmox and Canonical alternatives that offer subscription models without per-socket licensing complexity.
Market Dynamics
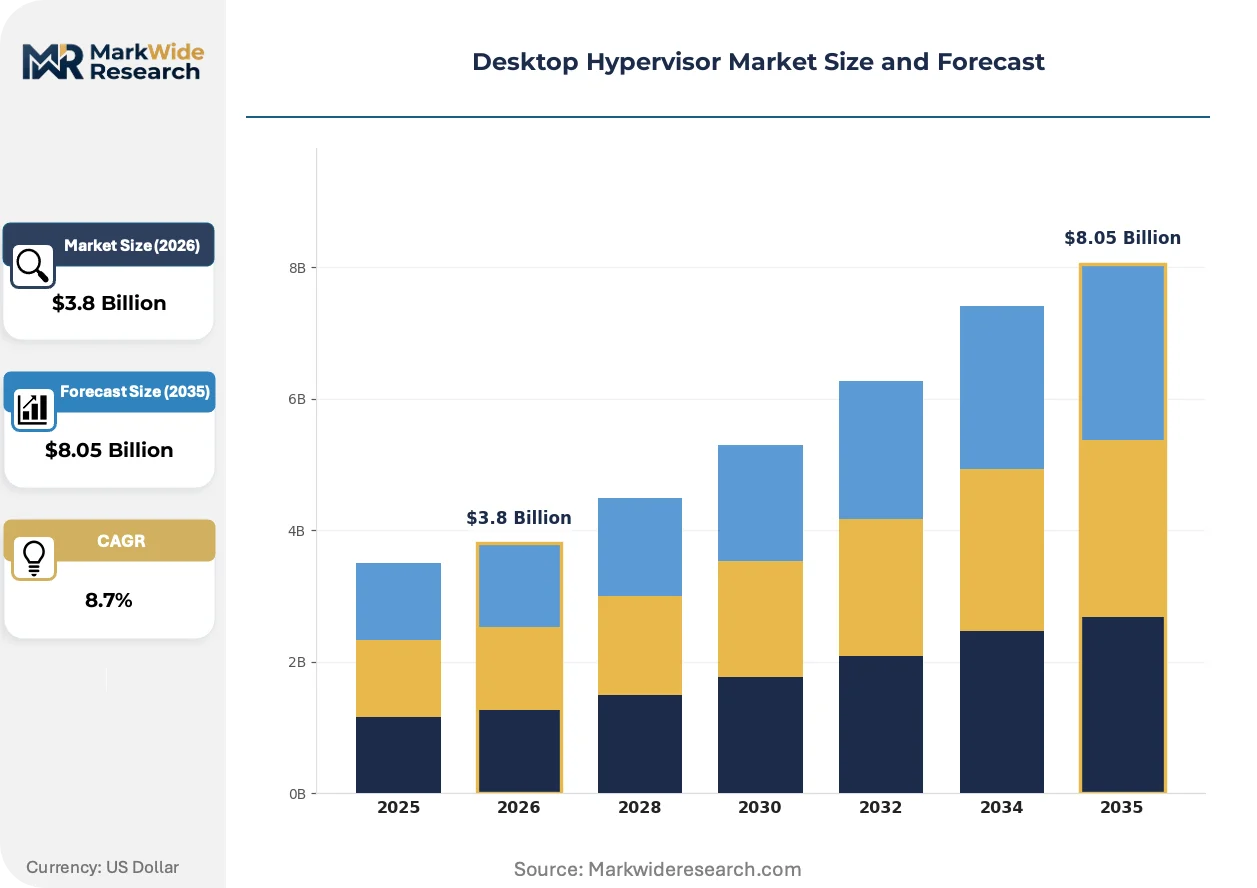
Broadcom's VMware pricing restructuring is forcing enterprise procurement teams to reassess long-term hypervisor commitments and accelerate evaluation of subscription-based alternatives.
Growth Catalysts
- NIST SP 800-53 controls:Federal agencies mandate encrypted VM migration paths, driving compliant hypervisor upgrades across US government contractors and their supply chains.
- Industrial automation clusters:German manufacturing hubs deploy on-premises hypervisors to satisfy BSI cybersecurity requirements while maintaining low-latency control systems.
- Intel VT-x and AMD-V extensions:Widespread processor virtualization support enables cost-effective endpoint consolidation without specialized hardware procurement.
Market Restraints
- Per-socket licensing complexity:Proprietary pricing models from entrenched vendors inflate total cost of ownership for multi-core workstation deployments.
- Hyperscaler concentration risk:Cloud-integrated hypervisor stacks create dependency on AWS, Azure, and GCP infrastructure pricing volatility.
- GDPR data residency friction:Cross-border VM migration restrictions complicate multinational workstation virtualization architectures.
Strategic Opportunities
- Proxmox and Canonical alternatives:Open-source subscription models without socket-based licensing attract developer-centric segments and mid-market IT departments.
- Edge computing deployments:Manufacturing and energy utilities require localized hypervisor instances for real-time operational technology isolation.
- EU AI Act compliance tooling:Automated VM provisioning with audit trails addresses emerging algorithmic governance requirements in European regulated industries.
Industry Challenges
- Virtualization architecture expertise:Shortage of engineers skilled in kernel-level hypervisor tuning and secure VM lifecycle management slows enterprise migrations.
- ISO 27001 certification timelines:Vendor qualification delays extend procurement cycles for public sector tenders in European and North American markets.
- Legacy application compatibility:32-bit and specialized hardware-dependent software resists containerization, requiring persistent VM maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desktop Hypervisor Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Source, Proprietary, Commercial, Educational Deployment Model: On-Premises, Cloud-Integrated, Hybrid, Standalone End User: Enterprises, Individual Users, Educational Institutions, Government Agencies Feature Set: Snapshot Support, Live Migration, Resource Allocation, Virtual Networking |
| Companies Covered | Oracle, Parallels, Microsoft, Canonical, Proxmox Server Solutions, VMware (Broadcom), Red Hat, Amazon, Citrix Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desktop Hypervisor Market Emerging Trajectories
Container runtime integration is blurring traditional boundaries between Type-2 hypervisors and lightweight virtualization, compressing procurement categories that IT departments previously treated as distinct.
Micro-VM architectures are decomposing monolithic desktop hypervisor deployments into ephemeral, single-purpose instances. Financial services security teams adopt this model for malware isolation workflows. The approach is decomposing traditional persistent VM management into automated, policy-driven orchestration that reduces patch surface area.
GDPR Article 44 transfer mechanism restrictions are reshaping cross-border virtualization strategies. European enterprises now enforce geographic boundary controls at the hypervisor layer. German automotive manufacturers and French healthcare providers lead this response, deploying air-gapped on-premises clusters rather than cloud-extended instances.
Subscription-based open-source alternatives are capturing procurement attention previously reserved for perpetual license negotiations. Mid-market IT departments in the United States and United Kingdom pilot Proxmox VE and Canonical LXD for developer workstation consolidation. This pattern is most visible in technology services firms rebuilding post-pandemic endpoint infrastructure without enterprise agreement lock-in.
Desktop Hypervisor Market Segmentation
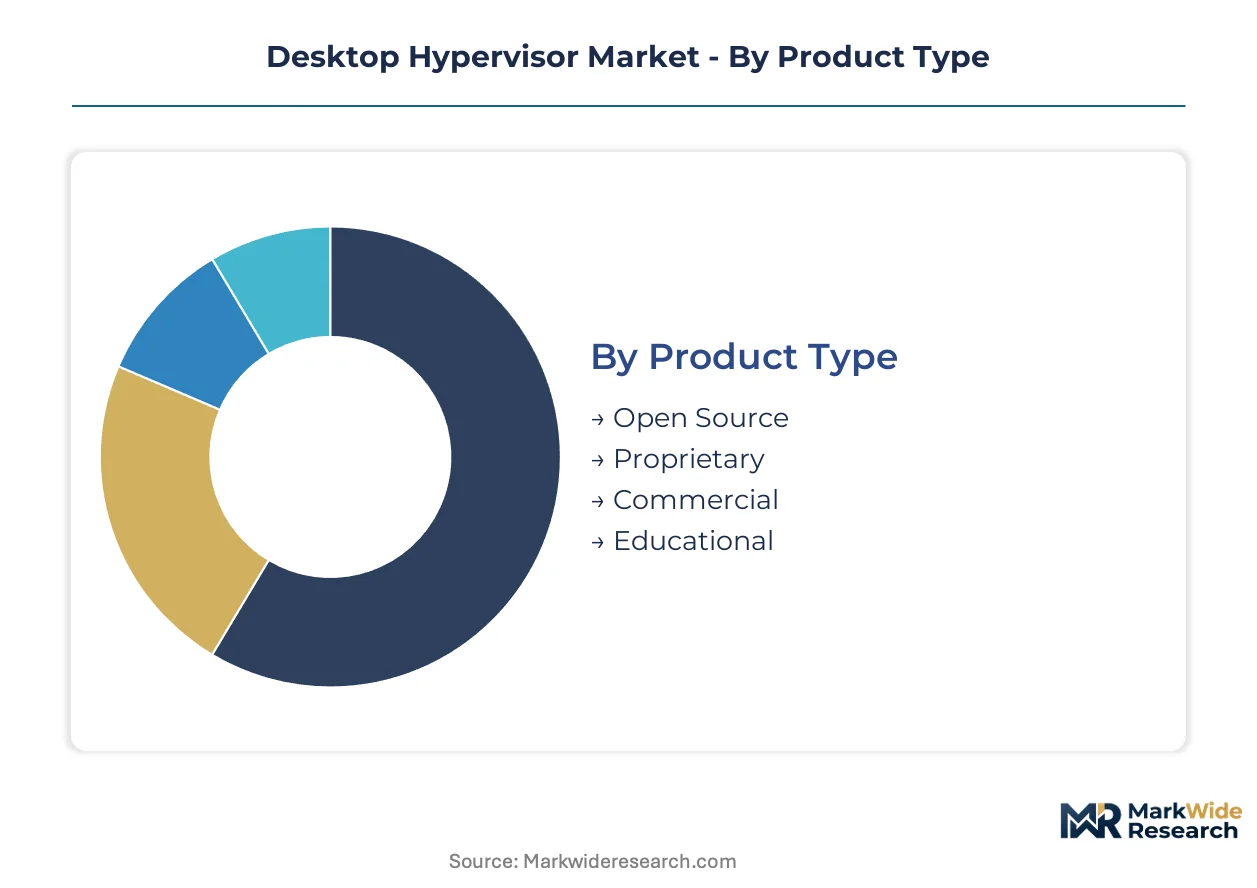
Desktop hypervisor procurement patterns diverge sharply across licensing models, infrastructure topologies, and organizational scale. Channel strategies must align with how each segment routes through direct enterprise sales, federal contractors, academic volume licensing, or self-service open-source adoption.
Product Type:
Channel economics vary dramatically by licensing philosophy, with proprietary vendors leveraging entrenched reseller networks while open-source alternatives convert through community-driven trials and subscription upgrades.
- Proprietary:Per-socket licensing with enterprise support contracts dominates Fortune 500 procurement through authorized channel partners. US federal contractors and German automotive manufacturers sustain recurring renewals despite Broadcom's pricing restructuring, as migration costs and compliance re-certification timelines lock in incumbent relationships.
- Open Source:Community editions with paid support tiers capture developer-centric evaluation cycles before IT standardization decisions. Mid-market technology services firms in the United Kingdom and United States pilot Proxmox VE and Canonical LXD to escape socket-based complexity, with subscription conversions accelerating post-pandemic endpoint rebuilds.
- Commercial:Bundled offerings through OEM workstation manufacturers address small business segments seeking pre-validated configurations without dedicated virtualization expertise.
- Educational:Volume licensing agreements through academic consortia enable university IT departments to standardize across research computing and instructional labs.
Proprietary licensing dominates installed base. Open source is where expansion concentrates.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises builds from operational expenditure models favoring cloud-integrated consumption, with hybrid architectures commanding premium pricing for orchestration complexity.
- On-Premises:Air-gapped clusters with encrypted VM migration paths satisfy BSI cybersecurity requirements in German industrial automation hubs and NIST SP 800-53 mandates across US government supply chains. French healthcare providers and German automotive manufacturers lead European deployment of geographic boundary enforcement at the hypervisor layer.
- Cloud-Integrated:Hyperscaler-managed control planes with workstation-local execution extend centralized patch management to distributed workforces. AWS, Azure, and GCP infrastructure dependencies create concentration risk that procurement teams weigh against agility gains.
- Hybrid:Policy-driven workload placement across on-premises and cloud substrates addresses seasonal capacity fluctuations without permanent infrastructure overprovisioning.
- Standalone:Single-workstation installations persist in regulated sectors where data sovereignty requirements block any external infrastructure dependency.
On-premises retains primacy in regulated verticals. Cloud-integrated deployment is climbing the fastest among enterprises rebuilding post-pandemic infrastructure.
End User:
Application intensity and compliance burden shape customer segmentation, with government and healthcare procurement cycles extending 18-24 months for ISO 27001 vendor qualification.
- Enterprises:Hybrid work model support drives consolidation of heterogeneous software estates onto single physical workstations, with IT departments prioritizing snapshot support and virtual networking for developer productivity.
- Government Agencies:Federal mandates for encrypted VM migration paths and geographic boundary enforcement reshape product roadmaps, with NIST frameworks and GDPR Article 44 restrictions requiring compliant hypervisor upgrades across contractor supply chains.
- Educational Institutions:Research computing and instructional standardization needs combine with constrained capital budgets to favor volume licensing and open-source evaluation.
- Individual Users:Enthusiast and freelance developer segments drive adoption of lightweight Type-2 hypervisors for legacy application compatibility and malware isolation workflows.
Enterprises command the largest transaction values. Government agencies represent the steepest expansion trajectory as replacement cycles accelerate.
Feature Set:
Maturity differentiation separates baseline virtualization from advanced orchestration capabilities that command premium positioning in enterprise tenders.
- Snapshot Support:Point-in-time VM state capture enables rapid rollback for patch validation and malware recovery, with financial services security teams adopting micro-VM architectures for ephemeral isolation workflows.
- Live Migration:Zero-downtime VM relocation across physical hosts underpins maintenance windows and load balancing in production environments, requiring Intel VT-x or AMD-V processor extensions for hardware-assisted memory shadowing.
- Resource Allocation:Dynamic RAM pools of 4-32 GB per instance and processor scheduling govern consolidation density and performance isolation.
- Virtual Networking:Software-defined overlay networks with micro-segmentation address east-west traffic inspection requirements in zero-trust architectures.
Snapshot support and live migration dominate RFP requirements. Virtual networking with micro-segmentation is gaining share fastest as zero-trust mandates propagate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based hypervisor vendors export subscription platforms to European industrial automation clusters, while German manufacturers import encrypted migration technologies to satisfy BSI cybersecurity mandates.
United States
Federal contractors and enterprise IT departments drive procurement of NIST SP 800-53 compliant platforms. FCC guidelines on communications infrastructure security reshape product roadmaps for encrypted VM migration paths. Silicon Valley technology services firms and Washington DC-area government contractors anchor domestic demand for hybrid deployment architectures.
Germany
Industrial automation clusters in Bavaria and Baden-Württemberg require low-latency control systems with on-premises isolation. BSI cybersecurity standards and GDPR Article 44 restrictions enforce geographic boundary controls at the hypervisor layer. Stuttgart automotive manufacturers and Munich industrial equipment builders deploy air-gapped clusters rather than cloud-extended instances.
United Kingdom
Mid-market technology services firms in London and Manchester pilot open-source alternatives to escape socket-based licensing complexity. ISO 27001 certification timelines extend procurement cycles for public sector tenders. Financial services security teams in the City of London adopt micro-VM architectures for malware isolation workflows.
France
Healthcare providers in Paris and Lyon enforce data residency through standalone on-premises installations. GDPR mandates block offloading patient data to hyperscaler environments. French automotive suppliers in the Île-de-France region deploy localized hypervisor instances for operational technology isolation.
Japan
Enterprise IT departments in Tokyo and Osaka consolidate heterogeneous software estates onto single physical workstations. METI industrial policy encourages domestic cybersecurity capability development. Osaka manufacturing hubs and Yokohama technology corridors represent concentrated evaluation zones for snapshot-enabled developer productivity platforms.
Desktop Hypervisor Market Vendor Landscape
Listed leaders compete with private specialists across licensing philosophy and deployment model dimensions. The vendor base stratifies into three tiers: proprietary incumbents with entrenched channel relationships, open-source subscription providers capturing mid-market evaluations, and hyperscaler-integrated platforms bundling control plane services. Dominant competitive moves include M&A-driven portfolio consolidation and geographic expansion through federal contractor partnerships.
Within the proprietary tier, VMware (Broadcom) and Microsoft exemplify entrenched positioning through enterprise agreement bundling and channel density. Among open-source specialists, Proxmox Server Solutions and Canonical occupy the subscription-conversion vector that attracts developer-centric segments. Red Hat represents the hybrid archetype bridging community editions with paid support tiers for regulated industries.
| Leading Market Players |
|---|
| Oracle |
| Parallels |
| Microsoft |
| Canonical |
| Proxmox Server Solutions |
| VMware (Broadcom) |
| Red Hat |
| Amazon |
| Citrix Systems |
| Others |
Supply Flow & Price Mechanics
Subscription-based licensing's displacement of perpetual socket-based contracts is redrawing vendor economics and procurement geography simultaneously, compressing margins for incumbent proprietary platforms while redistributing supply chain influence toward open-source distribution networks and cloud-native orchestration layers.
Pricing Analysis
Current-generation cloud-integrated hypervisor stacks command premium positioning over prior-generation on-premises perpetual licenses, while next-generation micro-VM architectures are entering at mid-market price points. Three-tier pricing structure across enterprise, mid-market, and developer tiers dominates, with differentiation driven by support SLAs and compliance certification depth. Cost compression in the proprietary tier is intensifying because Broadcom's VMware restructuring has triggered procurement team resistance. Mid-market IT departments exhibit highest price sensitivity, while federal contractors demonstrate lowest elasticity due to re-certification lock-in.
Supply Chain Analysis
Just-in-time software distribution through direct download and automated provisioning portals has displaced physical media and channel stockpiling across the desktop hypervisor value chain. Supply concentrates in the United States, Germany, and the United Kingdom for proprietary platform development, with India and Ireland anchoring technical support operations. Raw material dependencies center on Intel and AMD processor virtualization extensions, encryption chipset availability, and hyperscaler infrastructure capacity. Single-source vulnerability in Broadcom's VMware channel network creates concentration risk. Distribution runs through authorized reseller networks for proprietary tiers and community-driven direct adoption for open-source alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a switching-cost moat, with regulatory re-certification timelines and legacy VM compatibility requirements creating defensive barriers that extend customer retention beyond pure feature competition.
For Market Incumbents: Shield installed base relationships by accelerating ISO 27001 certification refresh cycles and embedding deeper into federal contractor compliance workflows. Prioritize backward integration into encryption chipset partnerships to secure VM migration path differentiation against Proxmox and Canonical subscription erosion.
For New Entrants and Emerging Players: Anchor in mid-market technology services firms rebuilding post-pandemic endpoint infrastructure without enterprise agreement lock-in. White-space concentrates in German industrial automation clusters seeking BSI-compliant alternatives to VMware. Developer-centric community conversion through snapshot-enabled trial workflows offers the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed open-source subscription platforms possessing established community-to-paid conversion funnels but lacking federal channel density. Long-term viability hinges on regulatory entrenchment depth rather than feature velocity alone. Watch for NIST SP 800-53 re-certification cycle acceleration as inflection signal for incumbent vulnerability windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Container runtime convergence with Type-2 hypervisors compresses procurement categories previously treated as distinct infrastructure layers. |
| Acquisition of Specialist Firm | Micro-VM security startups with financial services deployment credentials accelerate malware isolation workflow penetration. |
| Geographic Expansion | Federal contractor partnerships in Washington DC metro extend NIST-compliant platform reach through defense supply chain mandates. |
| Strategic Partnership | Hyperscaler control plane alliances address cloud-integrated deployment demand while mitigating infrastructure pricing volatility exposure. |
| Product Launch | EU AI Act-compliant automated VM provisioning with audit trail capabilities captures emerging algorithmic governance requirements. |
Methodological Framework
Initial hypotheses were tested against primary input from enterprise IT procurement officers, federal contractor virtualization architects, open-source community contributors, and channel partner technical leads and refined through secondary validation against SEC 10-K filings, hyperscaler capex disclosures, NIST publication repositories, and GDPR enforcement case databases. Bottom-up deployment model sizing triangulated against top-down addressable workstation population estimates.
Variance decomposition across deployment model, licensing philosophy, organization scale, vertical compliance burden, and regional regulatory cluster informed analytical framework construction throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic IT spending elasticity assumptions. Forecast inputs incorporated BSI cybersecurity mandate expansion timelines and Intel VT-x/AMD-V processor penetration curves.
Decision-makers should treat outputs as directional under assumptions of sustained federal compliance spending and stable hyperscaler infrastructure pricing; material deviation would warrant model refresh. Revision becomes warranted when Broadcom's VMware pricing restructuring triggers accelerated migration velocity thresholds or when EU AI Act enforcement reshapes VM audit trail requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
APAC Interior Design Software Market
Software & Services
Sales Dialer Software Market
Software & Services
Europe Business Software Market
Software & Services
Global Test Data Management Market
Software & Services
Global Online Community Management Software Market
Software & Services
Poland IT Software and Service Market
Software & Services
Global ERP Software Market
Software & Services
Global Software Asset Management Market
Software & Services
Global Animation Software Market
Software & Services
Sales Coaching Software Market
Software & Services
Parametric Design Software Market
Software & Services
Dynamic Slotting and Storage Optimization Software Market
Software & Services
Customer Advocacy Software Market
Software & Services
Global Online Survey Software Market
Software & Services
Lead Management Software Market
Software & Services
Systems Administration Management Tools Market