
 Calorie Metering Software Market | 2026-2036
Calorie Metering Software Market Size, Share, and Industry Trends Forecast 2026-2036
Calorie Metering Software Market Insights
The capability gap between cloud-native platforms and legacy desktop tools is reorganizing competitive dynamics across the calorie metering software landscape. MyFitnessPal leverages its extensive food database and community network to sustain engagement across fitness enthusiasts and casual users. Cronometer specializes in micronutrient tracking precision, positioning the platform for dietitians and clinical nutrition workflows.
Calorie metering software encompasses digital platforms that quantify, log, and analyze energy intake through searchable food databases, barcode scanning, and algorithmic portion estimation, typically operating with macronutrient breakdown accuracy within 5-10% variance. The technology serves commercial purposes spanning personal weight management, clinical dietary intervention, and employer-sponsored wellness program administration. Mobile applications dominate transaction volume due to smartphone ubiquity and real-time logging convenience, while cloud-based deployment captures the fastest expansion as SaaS models reduce upfront infrastructure costs for enterprise wellness buyers. Integrated platforms command premium positioning by connecting calorie data with wearable biometrics, electronic health records, and insurance reimbursement systems.
FDA digital health software guidance shapes clinical-grade product validation requirements, while HIPAA compliance mandates govern protected health information handling across employer wellness deployments. The EU AI Act introduces algorithmic transparency obligations for automated dietary recommendation engines serving European users. Stakeholders must monitor evolving interoperability standards between calorie platforms and national health record architectures to secure reimbursement eligibility and clinical credibility.
Market Dynamics
The convergence of AI-enabled food recognition with HIPAA-compliant cloud architectures is compressing product development cycles and forcing legacy desktop providers toward SaaS reinvention. Enterprise wellness buyers now mandate real-time biometric integration, reshaping vendor capability requirements across clinical and commercial segments.
Growth Catalysts
- Employer-Sponsored Prevention Mandates:United States corporate wellness programs now subsidize calorie tracking platforms as diabetes prevention infrastructure, expanding covered employee populations.
- FDA Digital Health Guidance:The FDA's Software as a Medical Device framework creates validation pathways for clinical-grade dietary intervention tools, opening reimbursement channels.
- Computer Vision Algorithms:On-device food recognition models reduce manual logging friction, accelerating adoption among casual users previously deterred by data entry burden.
Market Restraints
- Cloud Infrastructure Concentration:AWS, Google Cloud, and Microsoft Azure control enterprise hosting costs, creating margin pressure for independent platform operators.
- Micronutrient Database Licensing:Proprietary food composition datasets from USDA and commercial aggregators impose recurring royalty structures on specialized tracking features.
- EU AI Act Transparency Mandates:Algorithmic explanation requirements for automated dietary recommendations increase compliance engineering overhead for European deployments.
Strategic Opportunities
- Medicaid Expansion States:United States jurisdictions expanding public health coverage present untapped channels for clinically validated calorie intervention platforms.
- Wearable Biometric Convergence:Integration with continuous glucose monitors and metabolic sensors creates premium subscription tiers for prediabetic user segments.
- Pharmacy Distribution Partnerships:CVS Health and Walgreens storefront networks offer physical channel access for Medicare-eligible populations seeking digital nutrition tools.
Industry Challenges
- Registered Dietitian Integration:Clinical workflow embedding requires HIPAA Business Associate Agreement negotiations with thousands of independent practitioner offices.
- Legacy Electronic Health Record Interoperability:HL7 FHIR implementation gaps between calorie platforms and Epic, Cerner, and MEDITECH systems delay hospital system procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calorie Metering Software Market |
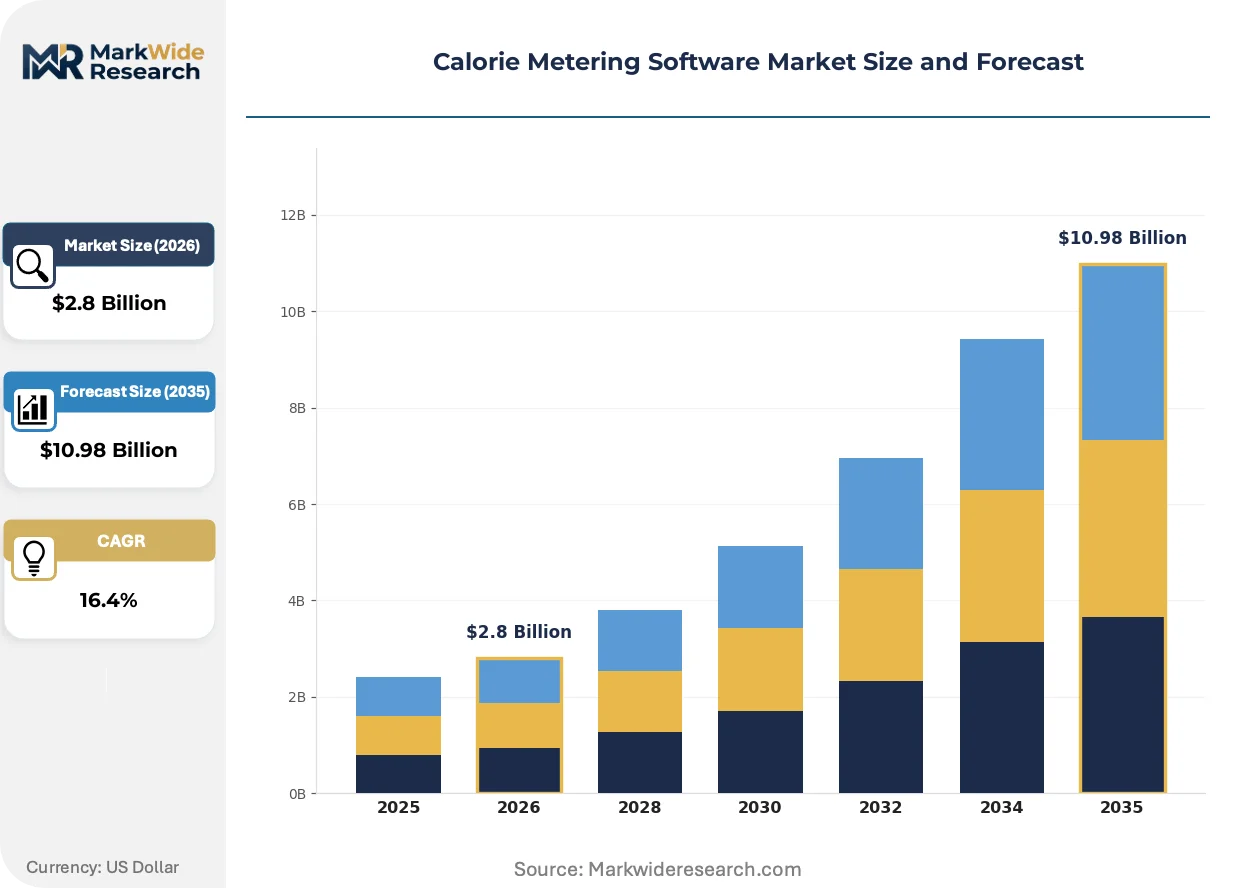
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web Applications, Mobile Applications, Desktop Software, APIs End User: Fitness Enthusiasts, Nutritionists, Health Coaches, Dietitians Deployment: Cloud-Based, On-Premises, Hybrid Models, SaaS Integration Level: Standalone Solutions, Integrated Platforms, Partnerships, Ecosystem Integrations |
| Companies Covered | MyFitnessPal, Lose It!, Noom, FatSecret, Cronometer, Lifesum, MyNetDiary, Calory, MacroFactor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calorie Metering Software Market Trends and Innovations
Generative AI and edge computing are compressing the latency between food consumption and metabolic feedback, transforming calorie metering from retrospective logging into real-time intervention systems. This shift demands new hardware-software architectures and regulatory frameworks.
On-device neural networks for food image classification is supplanting cloud-based recognition pipelines. Fitness-focused application developers are embedding TensorFlow Lite models directly into iOS and Android binaries to eliminate network latency and reduce API costs. This architecture shift is enabling offline functionality for rural users with intermittent connectivity while compressing server infrastructure spend for mid-tier vendors.
The EU AI Act's risk classification system for health-related algorithmic decision-making imposes documentation and human oversight obligations on automated meal planning features. European calorie platforms must now maintain technical files demonstrating bias testing across demographic cohorts. Germany and France represent the strictest enforcement environments, with national regulators already requesting conformity assessments from market entrants.
Subscription unbundling is fragmenting the traditional all-inclusive pricing model. Enterprise wellness buyers now demand modular procurement separating basic calorie logging from clinical coaching, biometric integration, and administrative analytics. This pattern is most pronounced among Fortune 500 self-insured employers in the United States, where benefits administrators negotiate component-level contracts with multiple specialized vendors rather than single-platform solutions.
Calorie Metering Software Market Segmentation
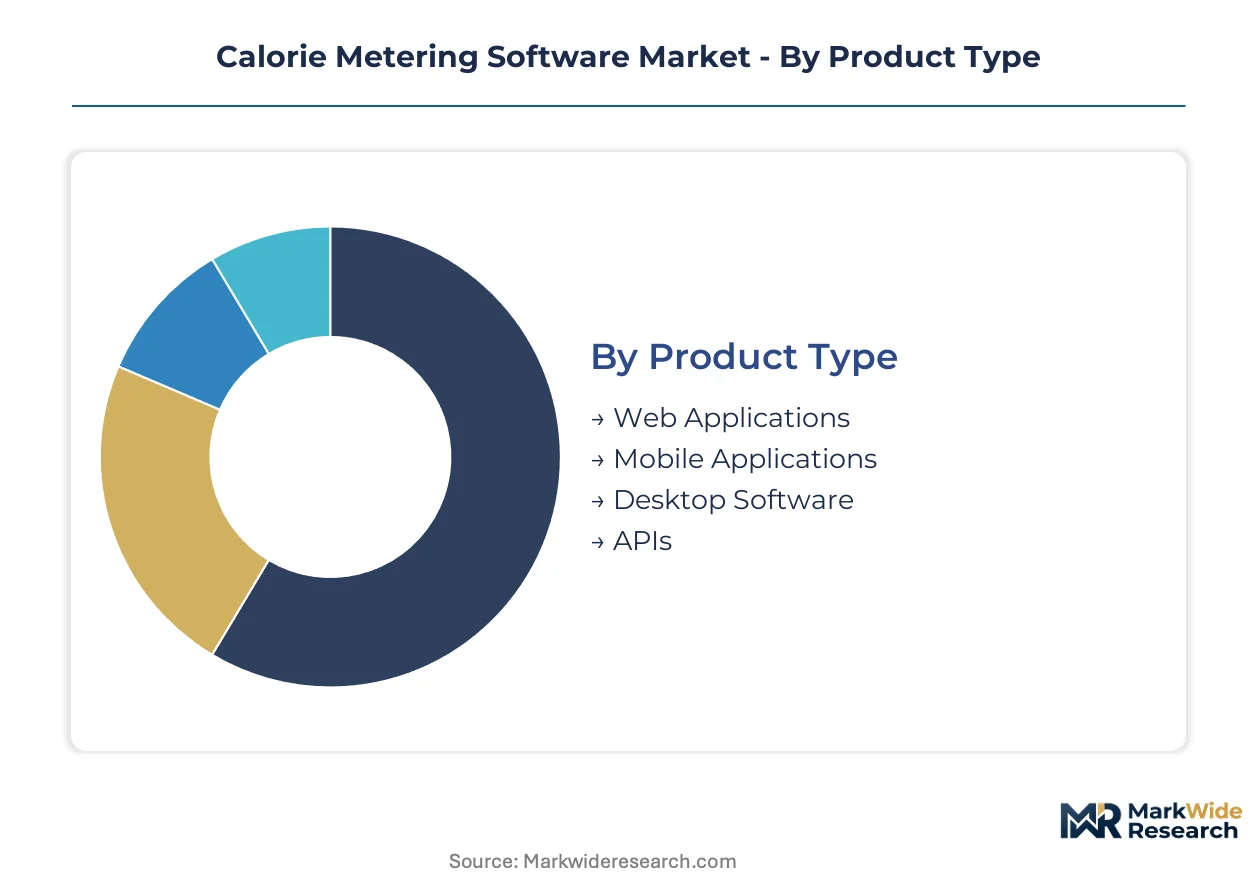
Segmentation in calorie metering software reveals how vendor economics shift across delivery modes and buyer sophistication. Substitution threats from adjacent health-tech categories reshape which product formats command sustainable margins.
Product Type:
Mobile applications face the most intense substitution pressure from native smartphone health suites, while desktop software confronts obsolescence as cloud migration accelerates.
- Mobile Applications:Native iOS and Android binaries dominate transaction volume through real-time food logging convenience and camera-based portion estimation. Fitness enthusiasts in the United States drive the majority of downloads, though retention rates suffer from competing wellness app clutter.
- Web Applications:Browser-based platforms serve enterprise wellness administrators requiring centralized dashboard access across distributed employee populations. Corporate procurement in the United States favors web interfaces for HIPAA audit trails and SSO integration.
- Desktop Software:Legacy Windows and macOS clients persist among clinical nutritionists requiring offline database access, though maintenance costs erode vendor profitability.
- APIs:RESTful and GraphQL interfaces enable third-party developers to embed calorie calculation engines into telehealth and fitness hardware ecosystems.
Mobile applications anchor the volume base while APIs gain share at the steepest rate.
End User:
Cost tier differentiation separates consumer self-service tools from clinical-grade platforms requiring professional credentialing workflows.
- Fitness Enthusiasts:Casual users prioritize gamification and social features over micronutrient precision, creating price sensitivity that favors freemium acquisition models.
- Nutritionists:Licensed practitioners demand batch client management, meal plan templating, and insurance documentation exports that justify premium subscription tiers.
- Health Coaches:Non-clinical wellness advisors seek motivational tracking tools without diagnostic liability, occupying a mid-market position between consumer and clinical functionality.
- Dietitians:Registered professionals require HIPAA-compliant data handling and EHR interoperability that only a subset of platforms certify, concentrating procurement among specialized vendors.
Fitness enthusiasts generate the largest user base while dietitians command the highest revenue per seat.
Deployment:
Volume concentration favors cloud architectures as enterprise buyers abandon capital expenditure models for operational flexibility.
- Cloud-Based:Multi-tenant SaaS architectures reduce upfront infrastructure costs for employer wellness programs and enable automatic feature updates without client IT involvement.
- On-Premises:Self-hosted deployments persist among hospital systems with strict data residency requirements, though maintenance burdens shift liability to internal IT departments.
- Hybrid Models:Split architectures process sensitive PHI locally while leveraging cloud analytics for population health insights, appealing to cautious mid-market employers.
- SaaS:Pure subscription delivery captures the fastest expansion as benefits administrators negotiate component-level contracts rather than perpetual licenses.
Cloud-based deployment anchors the volume base while SaaS gains share at the steepest rate.
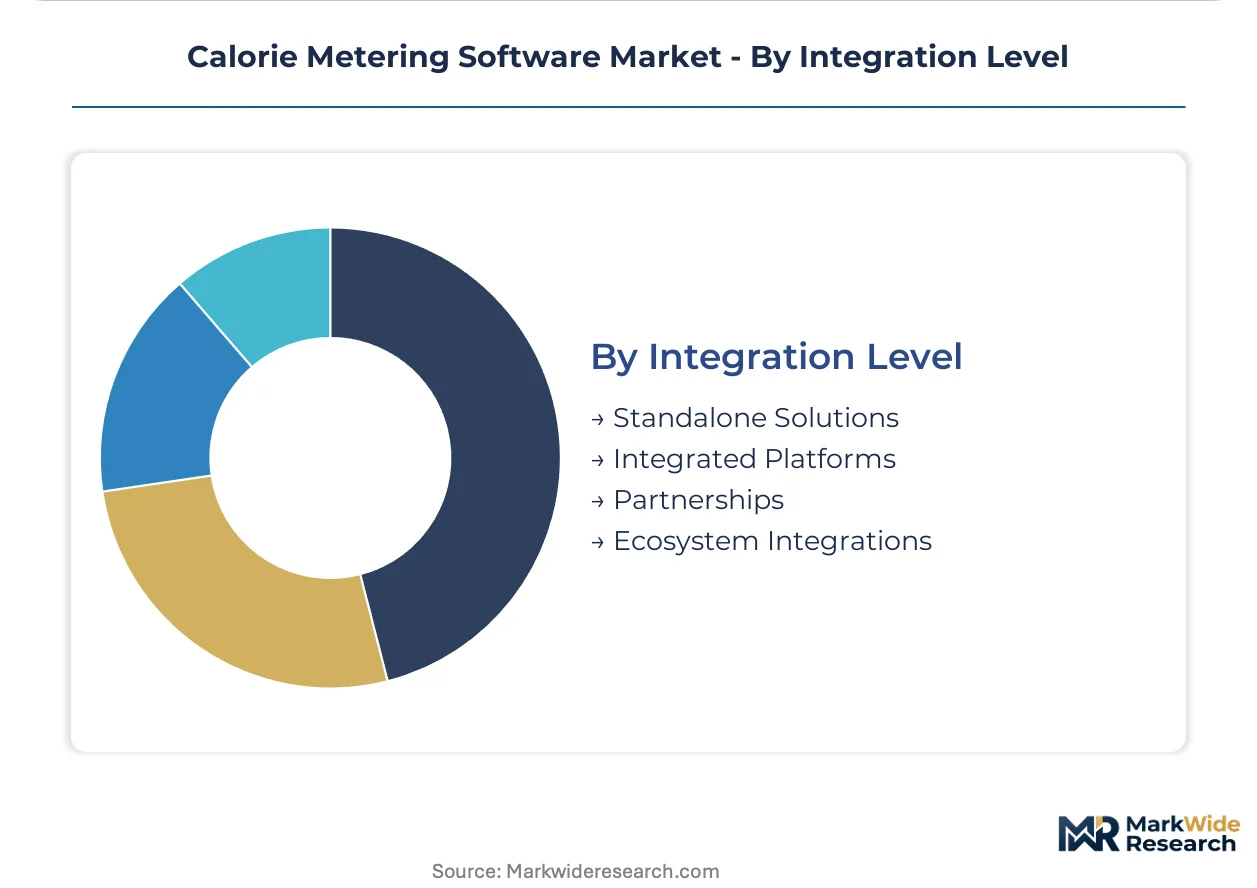
Integration Level:
Supply concentration among EHR and wearable vendors forces calorie platforms into partnership hierarchies that determine market access.
- Standalone Solutions:Independent applications without external data feeds serve price-sensitive consumers but suffer churn when users demand biometric convergence.
- Integrated Platforms:Native connections to Apple Health, Fitbit, and continuous glucose monitors command premium positioning among prediabetic user segments seeking closed-loop metabolic feedback.
- Partnerships:Formal alliances with pharmacy chains and telehealth providers create physical and digital distribution channels for Medicare-eligible populations.
- Ecosystem Integrations:Deep embedding within employer benefits marketplaces and insurance reimbursement systems requires HL7 FHIR compliance that filters out smaller vendors.
Standalone solutions anchor the volume base while ecosystem integrations gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer wellness subsidies in the United States create the least price-sensitive demand pool, while fitness enthusiasts in India and Southeast Asia gravitate toward freemium tiers with heavy ad support. This elasticity spread shapes how vendors architect regional go-to-market strategies.
United States
Fortune 500 self-insured employers and Medicare Advantage plans drive procurement of clinical-grade calorie platforms with biometric integration. FDA Software as a Medical Device guidance enables reimbursement pathways for diabetes prevention tools. The Boston-Cambridge corridor hosts specialized vendors targeting hospital system EHR interoperability requirements.
Germany
Techniker Krankenkasse and other statutory health insurers pilot digital nutrition prescriptions for prediabetic policyholders. The EU AI Act imposes algorithmic transparency documentation on automated meal planning features. Berlin and Munich clusters concentrate engineering talent for on-device food recognition model development.
United Kingdom
NHS Digital Weight Management Programme procurement creates institutional demand for platforms with health coach integration. MHRA alignment with FDA software guidance accelerates clinical validation timelines. London fintech-wellness hybrids embed calorie tracking into employee benefits marketplaces.
Japan
Metabo Law compliance requirements sustain corporate wellness spending on metabolic syndrome prevention tools. PMDA consults on software-as-medical-device classifications for glucose-integrated nutrition apps. Tokyo and Osaka metropolitan employers mandate platform adoption for annual health screening participants.
India
Corporate HR departments in IT services and banking sectors subsidize wellness app subscriptions for desk-bound workforces. FSSAI digital health initiatives lack enforcement specificity, creating regulatory ambiguity for clinical claims. Bengaluru and Hyderabad startups localize AI food recognition for regional cuisine databases.
Calorie Metering Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper stratum commanding ecosystem integration premiums and the lower tier competing on feature granularity. The market structure bifurcates between platforms with FDA validation pathways and consumer-grade tools dependent on advertising revenue. Three archetypes dominate: database-centric incumbents with community network effects, micronutrient-precision specialists for clinical workflows, and AI-native entrants leveraging on-device computer vision. Competitive moves concentrate on partnership formation with pharmacy chains and continuous glucose monitor manufacturers, plus unbundling of subscription tiers to capture modular enterprise procurement.
Within the database-centric tier, MyFitnessPal and Lose It! occupy positions sustained by food catalog breadth and user-generated content network effects. Cronometer exemplifies the clinical-precision archetype, anchoring dietitian workflow segments where micronutrient accuracy commands premium pricing. Noom represents the coaching-integrated model, sitting within employer wellness procurement channels that separate behavioral content from logging infrastructure.
| Leading Market Players |
|---|
| MyFitnessPal |
| Lose It! |
| Noom |
| FatSecret |
| Cronometer |
| Lifesum |
| MyNetDiary |
| Calory |
| MacroFactor |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation contracts with AWS, Google Cloud, and Microsoft Azure lock in compute pricing visibility for SaaS vendors while binding them to three-year infrastructure commitments. This structure concentrates procurement leverage among hyperscalers and compresses margin flexibility for independent platform operators serving enterprise wellness buyers.
Pricing Analysis
Enterprise coaching and biometric integration tiers drive lifetime value beyond base subscription fees. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade HIPAA-compliant deployments from consumer freemium tools. Cost compression in the standard tier intensifies because native smartphone health suites absorb casual users without dedicated app downloads. Fitness enthusiasts exhibit the highest price sensitivity, while Fortune 500 benefits administrators negotiating modular contracts show the least.
Supply Chain Analysis
Zero inventory models dominate software delivery, though food database licensing imposes fixed content refresh cycles. Engineering talent concentrates in the United States, Germany, and India, with Bengaluru and Hyderabad clusters specializing in regional cuisine AI model training. Proprietary nutrient datasets from USDA and commercial aggregators create single-source vulnerability for micronutrient-precision features. Distribution runs through employer benefits marketplaces and pharmacy chain digital storefronts rather than direct consumer acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI and edge computing inflections are compressing product development cycles and opening reimbursement pathways through FDA Software as a Medical Device guidance.
For Market Incumbents: Shield core database network effects by deepening exclusive partnerships with continuous glucose monitor manufacturers and securing HL7 FHIR certifications ahead of hospital system procurement cycles. Invest in on-device model compression to reduce API dependency on hyperscaler infrastructure. Defensive priority rests on locking in registered dietitian workflow integrations before clinical-grade competitors consolidate practitioner relationships. For New Entrants and Emerging Players: Anchor in Medicaid expansion states where clinically validated platforms lack established vendor relationships and reimbursement infrastructure remains underdeveloped. Target pharmacy distribution partnerships with CVS Health and Walgreens for Medicare-eligible population access. Go-to-market angle should emphasize offline functionality for rural users with intermittent connectivity, a capability gap legacy cloud-native incumbents have neglected. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors specialized vendors with FDA validation pathways and EHR interoperability certifications. Long-term viability across the next decade hinges on reimbursement eligibility rather than consumer download velocity. Acquisition target archetype includes micronutrient-precision platforms with existing HIPAA Business Associate Agreements and hospital system pilot contracts. Signal to watch is CMS Medicare Advantage plan expansion of digital nutrition benefit categories.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native embedding within Epic and Cerner EHR systems accelerates hospital procurement cycles. |
| Strategic Partnership | Alliances with Dexcom and Abbott continuous glucose monitors unlock prediabetic user premiums. |
| Acquisition of Specialist Firm | Purchasing regional cuisine database providers localizes AI food recognition for India and Southeast Asia. |
| Product Launch | On-device TensorFlow Lite models eliminate network latency for rural and intermittent connectivity users. |
| Geographic Expansion | Entry into Germany and France requires EU AI Act conformity assessments for automated meal planning features. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with CTOs at calorie metering platforms, benefits administrators at Fortune 500 self-insured employers, registered dietitians in clinical practice, and integration specialists at EHR vendors; and secondary validation against FDA 510(k) filings, CMS Medicare Advantage plan benefit disclosures, App Annie mobile download metrics, and hyperscaler capex reports. Bottom-up triangulation across deployment model, end-user sophistication, and integration complexity segments converged with top-down market sizing.
Across the analysis window, value projections incorporated SaaS subscription tiers, enterprise coaching modules, and biometric integration premiums. Segmentation dimensions modeled include product type, deployment architecture, end-user credentialing level, and ecosystem integration depth. CAGRs were derived from adoption curve analysis and reimbursement pathway maturation timelines. Forecast inputs included employer wellness subsidy expansion rates and FDA Software as a Medical Device classification velocity.
Material uncertainties — regulatory delays in EU AI Act enforcement, hospital system EHR interoperability standardization, and hyperscaler pricing renegotiation cycles — sit outside the modeled envelope. Forecasts reflect documented assumptions about reimbursement eligibility expansion and clinical validation cost trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Enterprise-Grade Saas Market
Software & Services
IT Services Market
Software & Services
Architectural Rendering Software Market
Software & Services
Predictive Dialer Software Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Design Engineering Software Market
Software & Services
Global Organizational Change Management Software Market
Software & Services
Jobsite Management Software Market
Software & Services
Office Software Market
Software & Services
Global Saas Backup Software Market
Software & Services
Mobile Application Stores Market
Software & Services
Global Product Lifecycle Management Software Market
Software & Services
Sales Enablement Software Market
Software & Services
North America Telecom Expense Management Services Software Market
Software & Services
Automotive Hypervisor Market
Software & Services
Global Digital Experience Management Software Market