
 Cloud-Based Payroll Software Market | 2026-2036
Cloud-Based Payroll Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud-Based Payroll Software Market Analysis
Certified payroll administrators is redrawing competitive dynamics as labor shortages force employers toward automated compliance engines. ADP leverages its scale across tax jurisdictions to sustain service density that mid-market rivals struggle to match. Paychex anchors its position through deep channel control in the sub-1,000-employee segment where switching costs remain elevated. Workday differentiates by extending its HCM suite into payroll, occupying the large-corporation tier where integration with financial planning modules drives retention.
Cloud-based payroll software delivers wage calculation, tax withholding, and regulatory filing through remotely hosted infrastructure with API connectivity to HRIS and accounting systems, typically processing multi-state or multi-country pay cycles through centralized rule engines. Its primary commercial purpose is to replace on-premise payroll systems with scalable, automatically updated compliance layers that reduce penalty exposure from missed filing deadlines. Public cloud deployment leads volume adoption among small and medium enterprises seeking minimal IT overhead, while hybrid cloud configurations capture margin pools in regulated industries requiring data residency controls. The compliance reporting solution segment is expanding fastest as real-time audit trails and automated GDPR documentation become standard procurement requirements across European buyers.
FDA guidelines on software-as-a-service quality systems, combined with GDPR data processing agreements and state-level wage transparency laws in California and New York, are reshaping vendor certification requirements and buyer due diligence checklists. The SEC's emerging disclosure rules on human capital management metrics are further extending payroll data into executive reporting workflows, tightening integration demands between payroll platforms and financial systems. Stakeholders must monitor whether emerging AI-powered wage prediction tools trigger new algorithmic accountability frameworks before committing to long-term platform contracts.
Market Dynamics
Real-time wage transparency mandates and algorithmic accountability requirements are compressing vendor certification timelines while elevating integration demands between payroll engines and financial reporting systems.
Growth Catalysts
- GDPR Documentation Automation:European employers now mandate automated audit trails for employee data processing, forcing payroll platform upgrades that embed consent management and data residency controls by default.
- Multi-State Tax Complexity:Remote work normalization has fragmented employee tax jurisdictions, accelerating demand for centralized rule engines that calculate withholdings across California, New York, and Texas simultaneously.
- API-First Architecture:Cloud-native payroll systems now expose modular endpoints for HRIS and accounting connectivity, reducing implementation friction for mid-sized enterprises with heterogeneous software stacks.
Market Restraints
- Data Residency Compliance Costs:Germany's Federal Data Protection Act and France's CNIL localization requirements force hybrid cloud configurations that inflate infrastructure expenditure versus pure public deployment.
- Certified Administrator Scarcity:Labor shortages in credentialed payroll operations constrain implementation velocity, particularly for complex multi-country configurations requiring jurisdiction-specific expertise.
- Legacy System Entrenchment:On-premise payroll installations in regulated industries carry elevated switching costs due to historical customization depth and union-negotiated process dependencies.
Strategic Opportunities
- AI-Powered Wage Prediction:Machine learning models forecasting overtime liability and seasonal staffing costs are penetrating the 100-500 employee segment where manual workforce planning dominates.
- Embedded Finance Integration:Earned wage access and on-demand pay features are creating new revenue pools through banking-as-a-service partnerships that attach to core payroll workflows.
- CSRD Human Capital Disclosure:The EU Corporate Sustainability Reporting Directive's workforce metrics requirements are extending payroll data into ESG reporting suites, tightening platform stickiness among European multinationals.
Industry Challenges
- Algorithmic Accountability Uncertainty:Pending regulatory frameworks for automated wage determination create procurement hesitation as legal teams assess liability exposure from AI-driven pay recommendations.
- Cross-Border Data Fragmentation:Conflicting data localization requirements between European GDPR, California's CCPA, and emerging state mandates complicate single-instance payroll architectures for distributed workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud-Based Payroll Software Market |
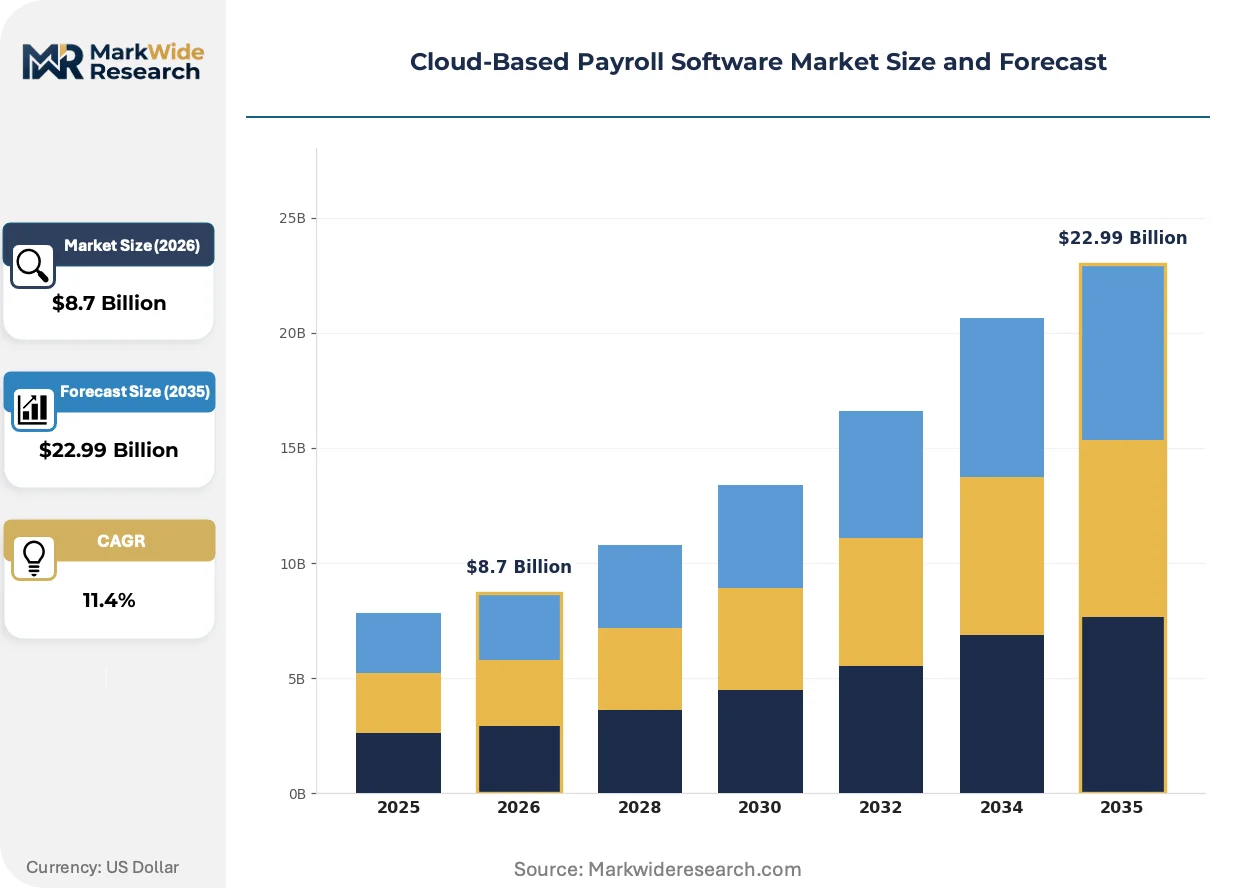
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Small Enterprises, Medium Enterprises, Large Corporations, Startups Solution: Time Tracking, Employee Self-Service, Tax Management, Compliance Reporting Functionality: Payroll Processing, Direct Deposit, Benefits Administration, Reporting Tools |
| Companies Covered | ADP, Paychex, Paycor, Workday, Intuit, Gusto, Paylocity, Sage Group, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud-Based Payroll Software Market Emerging Trajectories
Embedded compliance intelligence and predictive workforce analytics are displacing retrospective payroll processing, compressing the gap between wage accrual and regulatory filing while elevating real-time data quality requirements.
Continuous payroll calculation engines are miniaturizing the traditional biweekly pay cycle into on-demand wage streaming. Mid-sized employers in hospitality and logistics are piloting daily pay disbursement to reduce turnover. This compression is miniaturizing the historical batch-processing architecture that dominated enterprise payroll for three decades.
California's wage transparency law and New York's pay range disclosure requirements are mandating real-time compensation benchmarking visibility. Vendors must now embed external market data feeds directly into employee self-service portals. Large employers with distributed workforces face the steepest compliance burden as they reconcile conflicting state-level disclosure thresholds.
Subscription pricing for compliance modules is displacing perpetual licensing for core payroll engines. Mid-market buyers now expect automatic regulatory updates bundled into annual contracts rather than paying upgrade fees for tax table revisions. This shift is most visible among professional employer organizations serving the 50-500 employee segment where internal tax expertise is scarce.
Cloud-Based Payroll Software Market Segmentation
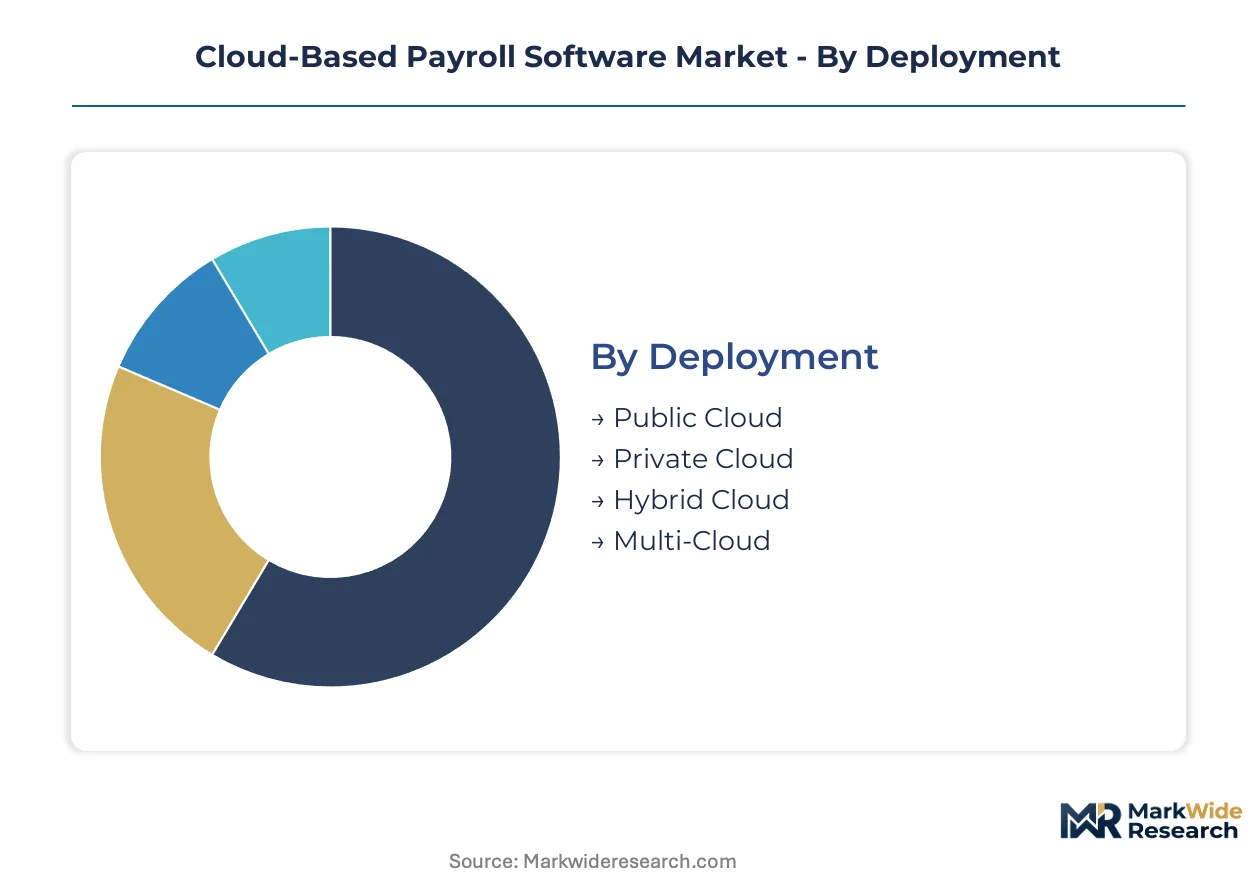
Cloud-based payroll software segments diverge sharply between compliance-heavy configurations for regulated industries and lightweight deployments for cost-sensitive buyers. Understanding these fault lines clarifies where vendor R&D investments concentrate and which buyer archetypes drive margin expansion.
Deployment:
Geographic data sovereignty requirements split deployment choices between domestic-hosted and export-oriented configurations. European buyers favor localized infrastructure, while North American adopters prioritize scalability over residency controls.
- Public Cloud:Shared infrastructure with automatic software updates and minimal IT overhead. Demand concentrates among United States-based small enterprises seeking rapid onboarding without capital expenditure, though GDPR constraints limit European uptake.
- Hybrid Cloud:Split architecture keeping sensitive payroll data on-premise while leveraging cloud scalability for non-critical workloads. German manufacturers and French public sector employers favor this model to satisfy CNIL and Federal Data Protection Act mandates.
- Private Cloud:Dedicated single-tenant environments with custom security policies. Banking and healthcare sectors in Switzerland and the United Kingdom specify these for audit trail isolation.
- Multi-Cloud:Distributed workloads across AWS, Azure, and Google Cloud to mitigate vendor lock-in. Technology sector employers with distributed engineering teams across California, Texas, and Washington State pilot these configurations for resilience.
Public Cloud commands the established base. The steepest expansion runs through Hybrid Cloud.
End User:
Buyer sophistication and integration complexity scale inversely with organization size, reshaping vendor sales motion and implementation timelines.
- Medium Enterprises:Organizations with 100 to 2,500 employees represent the most contested segment. These buyers demand API connectivity to existing HRIS investments while lacking internal payroll expertise, creating stickiness for vendors offering embedded compliance engines.
- Large Corporations:Multi-entity employers with complex union agreements and multi-country operations require jurisdiction-specific rule engines. Integration with financial planning modules drives retention, particularly among publicly traded firms responding to SEC human capital disclosure pressures.
- Small Enterprises:Sub-50-employee businesses prioritize mobile-first interfaces and automated tax filing over customization. Channel partnerships with accounting firms dominate distribution.
- Startups:Venture-backed companies with volatile headcount growth favor month-to-month contracts and rapid international expansion support. Equity compensation tracking and 409A valuation integrations differentiate winning vendors.
Medium Enterprises anchor current revenue. Large Corporations are climbing the fastest as ESG reporting mandates extend payroll data into executive dashboards.
Solution:
Module bundling strategies separate compliance-mandatory offerings from discretionary productivity tools.
- Compliance Reporting:Automated audit trails, consent management workflows, and regulatory filing documentation. European GDPR enforcement and California wage transparency laws make this mandatory for multinational employers.
- Tax Management:Multi-jurisdictional withholding calculations, remittance scheduling, and amendment handling. Remote work fragmentation across United States state lines accelerates demand for real-time tax engine updates.
- Time Tracking:Hourly wage calculation, overtime accrual, and PTO integration. Hospitality and logistics verticals in Germany and France adopt these for shift-based workforce management.
- Employee Self-Service:Pay stub access, tax form retrieval, and benefits election portals. Mobile-first implementations gain traction among younger workforces in technology and retail sectors.
Tax Management retains the core installed base. Compliance Reporting is gaining share fastest as regulatory documentation becomes a procurement gate.
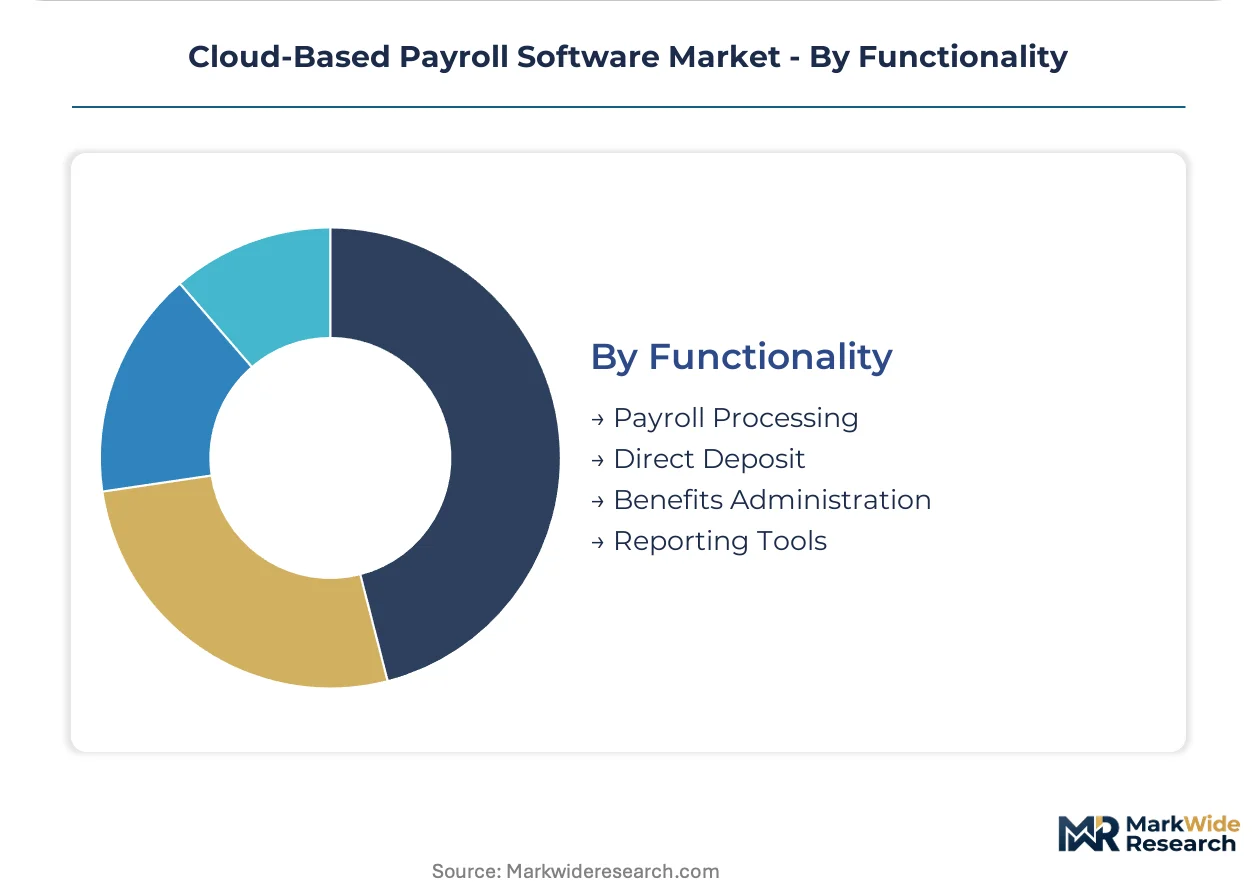
Functionality:
Core processing capabilities versus value-added services define vendor tier positioning and pricing power.
- Payroll Processing:Gross-to-net calculation, deduction management, and pay cycle execution. This foundational capability determines vendor eligibility for RFPs but offers limited differentiation.
- Benefits Administration:Health insurance enrollment, retirement contribution tracking, and COBRA management. United States employers with complex carrier integrations prioritize these modules for HR consolidation.
- Direct Deposit:Automated ACH transfers, split disbursement, and early wage access. Banking-as-a-service partnerships create new revenue pools through earned wage access features.
- Reporting Tools:Custom analytics, workforce cost projections, and executive dashboards. CSRD alignment in the European Union elevates these from operational tools to strategic planning inputs.
Payroll Processing holds the dominant position. Benefits Administration is expanding most quickly as employers seek single-platform HR consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC disclosure rules on human capital management metrics anchor United States demand, while GDPR enforcement across the European Union forces parallel upgrade cycles. Mid-sized employers in both jurisdictions face compressed procurement timelines as wage transparency mandates multiply.
United States
Multi-state tax complexity from remote work fragmentation drives platform upgrades among employers with distributed teams. California's wage transparency law and New York's pay range disclosure requirements force real-time compensation benchmarking into employee portals. Technology sector employers in Austin and Seattle pilot multi-cloud configurations for resilience across state lines.
Germany
GDPR documentation automation and Federal Data Protection Act compliance elevate hybrid cloud demand among manufacturers with unionized workforces. CNIL-aligned data residency controls restrict public cloud adoption for payroll processing. Industrial employers in Bavaria and Baden-Württemberg favor split architectures keeping sensitive data on-premise.
United Kingdom
Post-Brexit regulatory divergence from EU frameworks complicates payroll architectures for multinationals with cross-border workforces. FCA-aligned disclosure expectations extend payroll data into executive reporting workflows. Financial services employers in London and Edinburgh prioritize private cloud deployments for audit trail isolation.
India
Digital infrastructure expansion and startup ecosystem growth accelerate cloud-native payroll adoption among venture-backed employers. RBI data localization guidelines influence vendor selection for banking sector implementations. Technology employers in Bangalore and Hyderabad demand rapid international expansion support and equity compensation tracking.
Japan
Labor force contraction and aging demographics push employers toward automated compliance engines as certified administrator availability tightens. METI productivity initiatives encourage HR technology modernization among traditional manufacturers. Employers in Tokyo and Osaka prioritize integration with legacy enterprise resource planning systems.
Cloud-Based Payroll Software Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages in tax jurisdiction coverage separating the two levels. The upper tier commands premium positioning through embedded compliance engines and API connectivity breadth. Specialist competitors compete on vertical customization and regional regulatory depth. Consolidation pressure intensifies as mid-market buyers demand single-platform consolidation. Strategic partnerships with banking-as-a-service providers and embedded finance integrations represent the dominant competitive vectors.
Within the integrated tier, ADP and Workday exemplify scale-driven positioning through HCM suite extension and multi-country tax engine density. Paychex anchors the specialist segment with channel control in sub-1,000-employee configurations where switching costs remain elevated. Sage Group represents European-centric regulatory depth, particularly among mid-market buyers navigating GDPR and CSRD disclosure requirements simultaneously.
| Leading Market Players |
|---|
| ADP |
| Paychex |
| Paycor |
| Workday |
| Intuit |
| Gusto |
| Paylocity |
| Sage Group |
| Oracle Corporation |
| Others |
Supply Flow & Price Mechanics
Annual subscription contracts with automatic regulatory update clauses lock in multi-year revenue visibility for cloud payroll vendors while capping buyer exposure to tax table revision fees. This contract structure concentrates pricing power with established platforms serving mid-sized employers in the United States and Germany where compliance module bundling now dominates procurement decisions.
Pricing Analysis
Per-employee-per-month SaaS tiers anchor the dominant pricing structure across the cloud payroll sector. Price differentiation separates premium configurations with embedded AI wage prediction from standard offerings with basic tax automation. Pricing pressure stems from banking-as-a-service partnerships commoditizing earned wage access features previously sold as add-ons. Small enterprises with sub-50 employees exhibit the highest price sensitivity, while large corporations prioritize integration breadth over per-seat cost.
Supply Chain Analysis
Certified payroll administrator scarcity in the United States and Germany constitutes the primary talent chokepoint constraining implementation velocity for complex multi-jurisdictional deployments. Cloud infrastructure provisioning draws from hyperscaler data centers concentrated in Virginia, Frankfurt, and Dublin, with API connectivity modules sourcing from specialized fintech enablers in London and Singapore. Single-source vulnerability runs through concentrated banking-as-a-service provider relationships for earned wage access features. Distribution runs through direct enterprise sales teams for large accounts and accounting firm channel partnerships for small business penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based payroll software operates as a high-switching-cost defensive moat where regulatory entrenchment protects incumbent positions. Multi-jurisdictional tax engine density creates network effects that compound with each new geography added.
For Market Incumbents: Consolidate API connectivity breadth through targeted acquisition of niche HRIS integration specialists serving verticals like healthcare and construction. Deepen embedded finance partnerships with banking-as-a-service providers before fintech entrants capture earned wage access margins. Regulatory entrenchment in GDPR documentation automation and SEC human capital disclosure workflows remains the priority defensive lever against platform challengers.
For New Entrants and Emerging Players: Earned wage access integration gaps in the 100-500 employee segment represent the most penetrable white-space where incumbent platforms under-serve hospitality and logistics verticals. AI-powered overtime liability forecasting for seasonal employers offers a second entry vector with limited incumbent coverage. A channel partnership strategy with professional employer organizations unlocks rapid scale without direct enterprise sales infrastructure.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-market specialists with dense tax jurisdiction coverage and proven API connectivity to heterogeneous software stacks. Long-term viability hinges on regulatory update automation capabilities that compound switching costs across the projection horizon. The signal to watch is algorithmic accountability framework finalization in the European Union, which will separate compliant platforms from liability-exposed challengers.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API connectivity to Workday and SAP HCM suites captures large-corporation procurement cycles. |
| Strategic Partnership | Banking-as-a-service alliances with Stripe and Plaid unlock earned wage access revenue pools. |
| Acquisition of Specialist Firm | Vertical tax engine specialists in construction and healthcare deepen regulatory moats. |
| Geographic Expansion | GDPR-compliant data centers in France and Germany satisfy CNIL localization mandates. |
| Product Launch | Continuous payroll calculation engines displace biweekly batch processing in hospitality verticals. |
Methodological Framework
Initial hypotheses were tested against primary input from payroll operations directors, HR technology procurement officers, compliance officers at multinationals, and channel partners at accounting firms and refined through secondary validation. SEC human capital disclosure filings, GDPR enforcement actions by European data protection authorities, state-level wage transparency law texts, and hyperscaler infrastructure expansion announcements supplied quantitative anchors. Bottom-up sizing of vendor-reported seat counts and top-down triangulation against employer establishment data converged on segment-level estimates.
Variance decomposition across deployment models, organization size tiers, solution modules, and regional regulatory clusters shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Integration complexity scores and compliance module attach rates served as industry-specific forecast inputs throughout the modeling period.
Material uncertainties — algorithmic accountability framework finalization, cross-border data localization rule divergence, and certified administrator labor supply shocks — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and remote work tax jurisdiction stability. Practitioners should keep alternative scenarios live as AI wage determination liability standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Content As a Service (Caas) Market
Software & Services
Global Corporate Wellness Software Market
Software & Services
Europe HR Payroll Software Market
Software & Services
Global Rapid Application Development Market
Software & Services
Global Email Software Market
Software & Services
Global Budgeting Software Market
Software & Services
Virtual Fitting Software Market
Software & Services
Lease Accounting and Management Software Market
Software & Services
Proxy Services and Software Market
Software & Services
Test Management Software Market
Software & Services
Global Accreditation Management Software Market
Software & Services
Programming Language Market
Software & Services
Data Migration Software Services Market
Software & Services
Global Webinar Software Market
Software & Services
Global Brand Management Software Market
Software & Services
Global Configuration Management Software Market