
 Stone Analysis Software Market | 2026-2036
Stone Analysis Software Market Size, Share, and Industry Trends Forecast 2026-2036
Stone Analysis Software Market Analytics
North American clinical software developers is rebalancing capacity toward cloud-native architectures that support real-time renal stone characterization. Thermo Fisher Scientific leverages its analytical instrumentation heritage to anchor enterprise laboratory deployments. Beckman Coulter sustains competitive positioning through deep integration with automated urinalysis hardware. Agilent Technologies specializes in spectroscopy-linked software modules that dominate research-oriented installations.
Stone analysis software comprises digital platforms that process mineralogical, chemical, and morphological data from kidney stone samples to classify composition and guide treatment selection. These systems typically operate at 5-10 micrometer spatial resolution using Raman or infrared spectral libraries matched against clinical databases. Cloud-based deployment is capturing the fastest expansion as hospitals seek to minimize on-site IT infrastructure while enabling multi-site access to analytical results. AI-powered analysis is concentrating margin pools where vendors bundle proprietary algorithms with subscription pricing, whereas desktop software retains dominance in resource-constrained settings with limited connectivity.
FDA oversight of clinical decision support software under the 21st Century Cures Act is forcing developers to document algorithmic transparency and validation datasets prior to commercial distribution. HIPAA security rule enforcement shapes cloud architecture requirements for patient data handling across hospital networks. ISO 13485 quality management expectations extend to software-as-a-medical-device classifications in multiple jurisdictions. Stakeholders must monitor evolving regulatory distinctions between research-use-only and clinical-grade analytical platforms to avoid compliance gaps that restrict market access.
Market Dynamics
Cloud-native deployment architectures are compressing software delivery timelines while forcing vendors to reengineer validation protocols for real-time renal stone characterization across distributed hospital networks.
Growth Catalysts
- 21st Century Cures Act enforcement:FDA clinical decision support software requirements are accelerating algorithmic transparency investments among developers seeking 510(k) clearance pathways.
- University medical center procurement:German urology departments are embedding spectroscopy-linked analysis into routine diagnostic workflows, creating reference-site effects for vendor expansion.
- Raman spectral library expansion:Mineralogical database refinement is enabling compositional classification at 5-10 micrometer resolution previously requiring destructive testing.
Market Restraints
- IT infrastructure heterogeneity:Hospital laboratory legacy system fragmentation forces costly middleware development for each enterprise deployment.
- Spectroscopy hardware concentration:Analytical instrument supply chains cluster in German and Japanese manufacturing centers, exposing procurement to single-source risk.
- Validation dataset scarcity:Rare stone compositions lack sufficient training samples for FDA-compliant algorithmic performance documentation.
Strategic Opportunities
- Subscription pricing penetration:AI-powered bundled offerings are capturing margin pools in research-oriented installations seeking turnkey analytical capabilities.
- Multi-site network architectures:Cloud deployment models enable centralized pathology review across rural hospital clusters lacking on-site mineralogical expertise.
- ISO 13485 software-as-a-medical-device pathways:Quality management certification expansion creates regulatory arbitrage opportunities in jurisdictions with harmonized medical device frameworks.
Industry Challenges
- Computational pathology skill scarcity:Hospital IT departments lack personnel trained in spectral data preprocessing and machine learning model interpretation.
- Legacy urinalysis integration friction:Automated hardware from Beckman Coulter and similar vendors requires proprietary API negotiation for seamless workflow embedding.
- Research-use-only boundary enforcement:Vendors face compliance surveillance distinguishing investigational platforms from clinical-grade analytical tools.
Report Scope
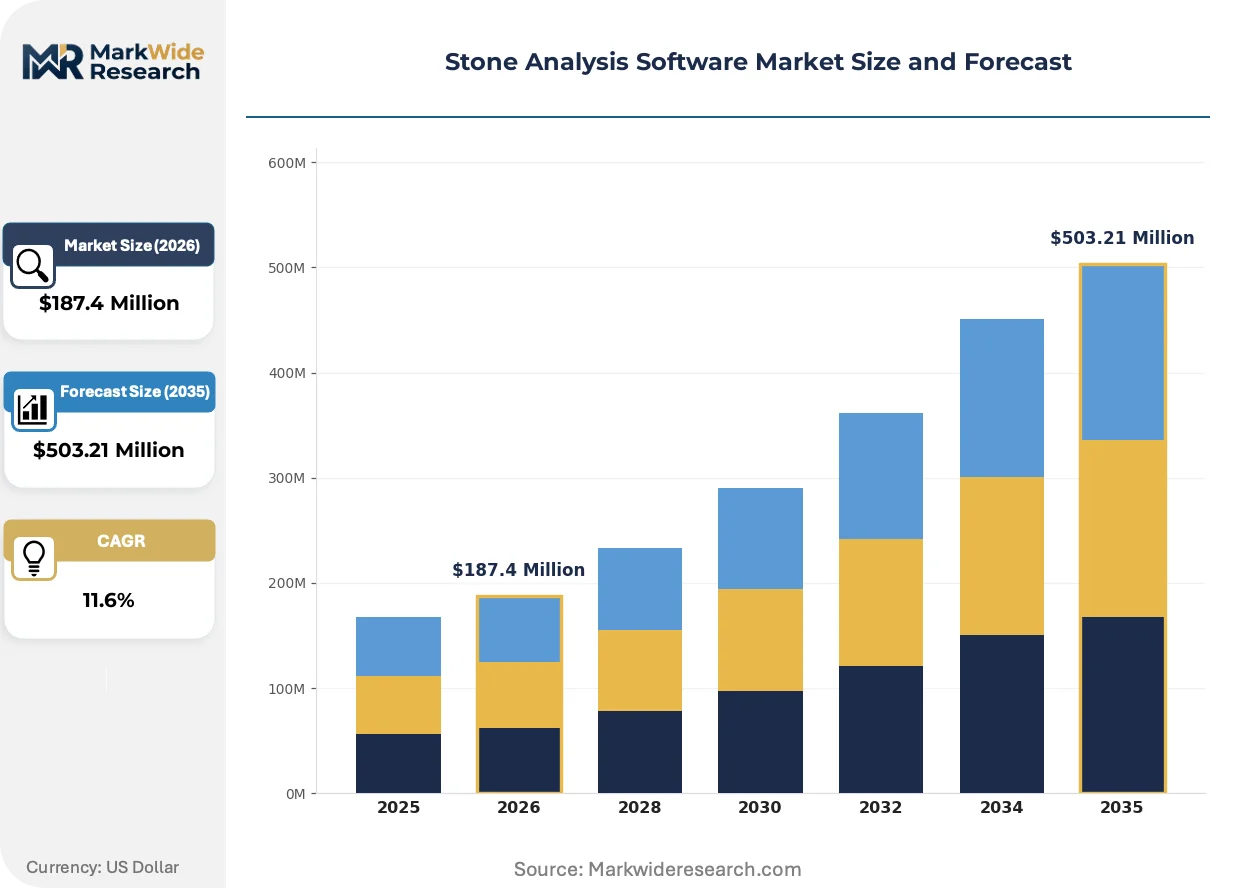
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stone Analysis Software Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Software, Mobile App, Online Platform, Hybrid Solution Deployment: On-Premise, Cloud-Based, SaaS, Dedicated Server End User: Laboratories, Hospitals, Research Institutions, Educational Entities Technology: AI-Powered Analysis, Machine Learning, Data Visualization, Real-Time Processing |
| Companies Covered | Thermo Fisher Scientific, Beckman Coulter, Agilent Technologies, Bruker Corporation, Bio-Rad Laboratories, Siemens Healthineers, Olympus Corporation, Stryker Corporation, GE HealthCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stone Analysis Software Market Evolving Landscape
Artificial intelligence integration is restructuring competitive differentiation around proprietary algorithm performance rather than spectral hardware specifications alone.
Deep learning convolutional networks trained on morphological stone imaging are automating compositional classification previously requiring manual pathologist review. Hospital laboratories in the United States are deploying these systems within six-month procurement cycles, compressing diagnostic turnaround from days to hours. This automation is displacing regional reference laboratory outsourcing relationships.
EU Medical Device Regulation (MDR) software classification rules are extending quality management obligations to cloud-hosted analytical platforms previously exempt under legacy directives. European urology centers are demanding CE-marked algorithmic modules with documented training dataset provenance. German university hospitals are leading compliance investments, creating competitive separation from research-only installations.
Subscription-based access models are replacing perpetual license structures as dominant procurement mechanisms for multi-site health systems. Hospital procurement departments are unbundling hardware acquisition from software service fees, favoring vendors with transparent usage-based pricing. This shift concentrates vendor selection authority in centralized IT governance committees rather than individual laboratory directors.
Stone Analysis Software Market Segmentation
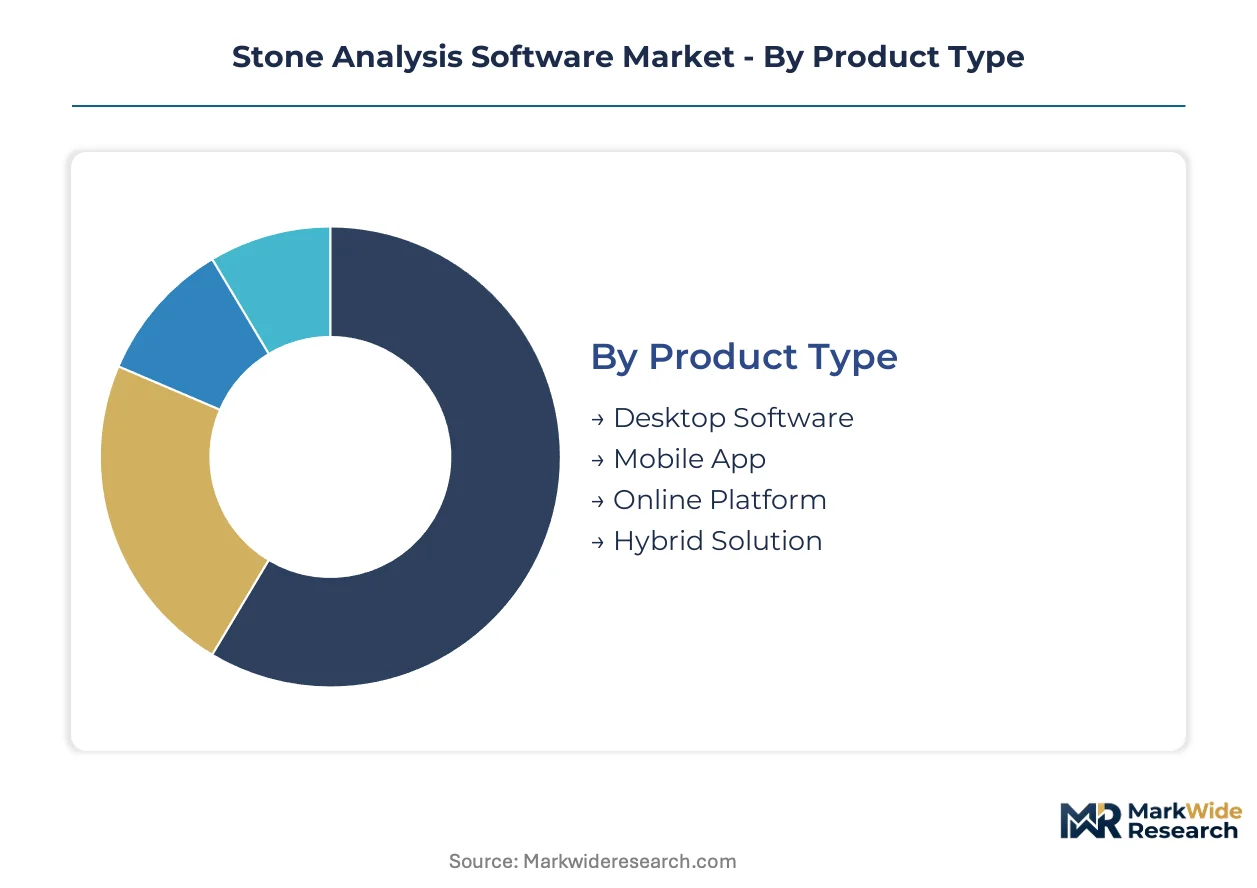
Stone analysis software vendors configure product architectures around three competing pressures: regulatory validation burden, IT infrastructure heterogeneity, and end-user technical sophistication. Segmentation strategy determines whether vendors capture margin through premium AI-powered subscriptions or volume through standardized desktop licenses.
Product Type:
The customization-standardization spectrum spans from rigid desktop installations to modular hybrid architectures that blend local processing with cloud analytics.
- Desktop Software:Perpetual license models dominate resource-constrained hospital laboratories with limited connectivity. FDA validation documentation concentrates here due to fixed algorithm versioning and offline operation. Demand clusters in rural United States health systems prioritizing data sovereignty over analytical sophistication.
- Hybrid Solution:Local spectral preprocessing paired with cloud-based classification algorithms enables real-time renal stone characterization across distributed networks. German university medical centers are expanding procurement of these architectures to integrate multi-site pathology review without sacrificing latency performance.
- Mobile App:Point-of-care image capture for preliminary morphological assessment. Research institutions deploy these for field collection in epidemiological studies.
- Online Platform:Browser-accessible analysis without local installation. Educational entities favor this format for training pathology residents on standardized case libraries.
Most installed capacity flows through Desktop Software. Expansion is steepest in Hybrid Solution.
Deployment:
Cost tier stratification separates enterprise health systems with dedicated infrastructure from mid-sized laboratories seeking operational expenditure flexibility.
- Cloud-Based:Multi-tenant architectures minimize on-site IT footprint while enabling centralized algorithm updates. Hospital procurement committees in the United States are mandating HIPAA-compliant cloud configurations with business associate agreements covering spectral data storage. This tier captures the fastest margin pool expansion where vendors bundle AI modules with usage-based pricing.
- On-Premise:Air-gapped installations serve facilities with strict data residency requirements or unreliable connectivity. Research institutions with proprietary spectral libraries prefer this model to retain control over training dataset provenance.
- SaaS:Subscription licensing with automatic feature updates. Mid-sized urology clinics lacking dedicated IT staff select this to outsource infrastructure maintenance.
- Dedicated Server:Single-tenant cloud instances for health systems requiring physical isolation without full on-premise burden. University medical centers in Germany specify these for EU MDR compliance documentation.
Procurement volume concentrates in Cloud-Based. Margin capture is strongest in SaaS.
End User:
Application maturity varies sharply across customer types, from regulated clinical diagnostics to exploratory research workflows.
- Laboratories:High-throughput mineralogical analysis integrated with automated urinalysis hardware. Reference laboratories in the United States are displacing manual pathologist review with AI-powered classification to compress turnaround from days to hours.
- Hospitals:Point-of-care deployment for immediate treatment guidance. German urology departments embed spectroscopy-linked software into routine diagnostic workflows, creating reference-site effects for vendor expansion.
- Research Institutions:Investigational platforms for rare stone composition database expansion. FDA 510(k) pathway constraints limit clinical deployment of algorithms trained on insufficient validation samples.
- Educational Entities:Training environments for pathology resident competency development. Morphological case libraries with annotated ground truth support curriculum standardization.
Revenue concentration sits with Laboratories. Adoption velocity is climbing fastest in Hospitals.
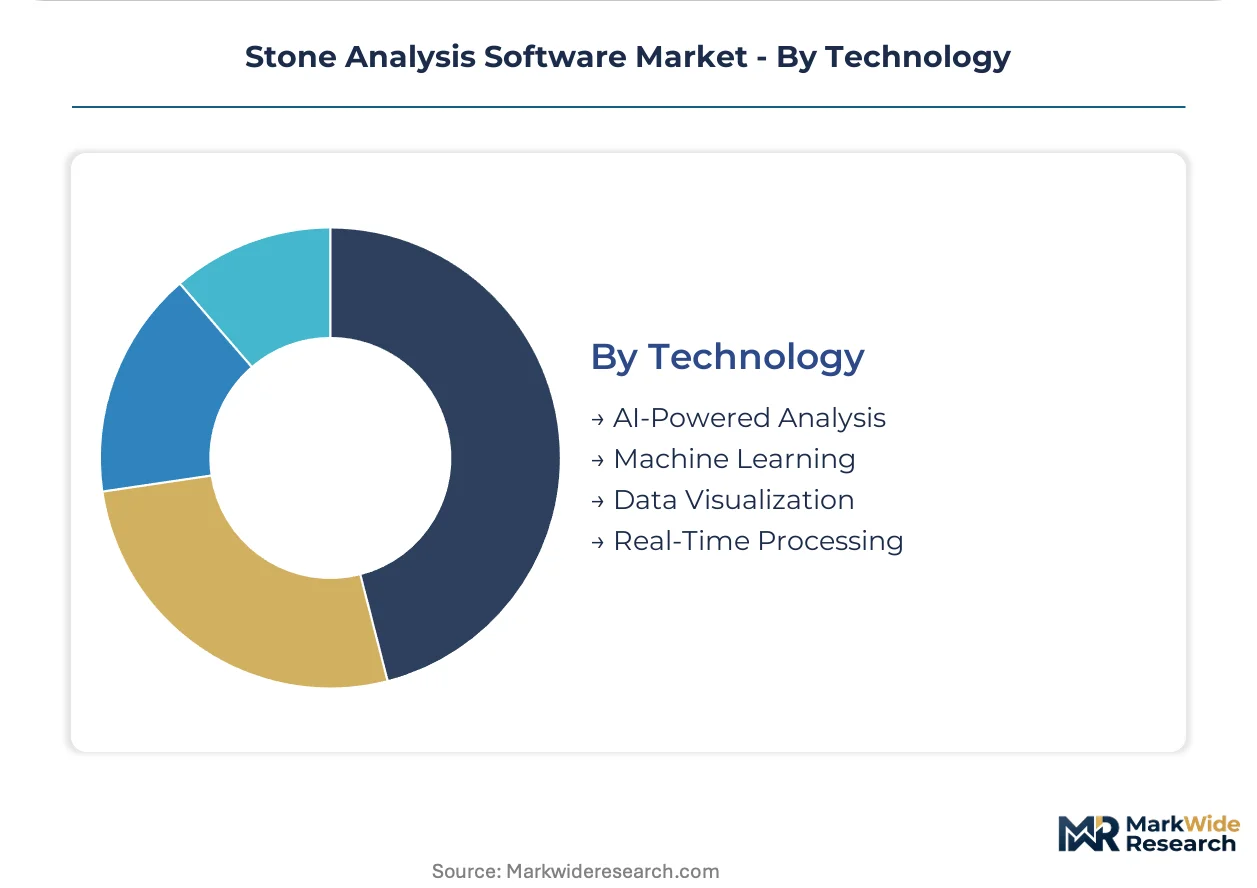
Technology:
Customer type determines whether buyers prioritize algorithmic performance transparency or turnkey analytical accessibility.
- AI-Powered Analysis:Proprietary convolutional networks trained on morphological imaging automate compositional classification. Vendors bundle these with subscription pricing to capture recurring revenue from research-oriented installations seeking turnkey capabilities.
- Real-Time Processing:Spectral data interpretation within seconds of sample acquisition. Hospital laboratories deploy these systems within compressed procurement cycles to eliminate reference laboratory outsourcing relationships.
- Machine Learning:Supervised classification with documented training dataset provenance. EU MDR compliance investments concentrate here for CE-marked algorithmic modules.
- Data Visualization:Mineralogical composition reporting for clinician communication. Educational entities prioritize intuitive interfaces for resident training.
Development investment concentrates in AI-Powered Analysis. Regulatory validation throughput is expanding most quickly in Real-Time Processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates university medical center procurement for AI-powered stone analysis, while United States hospital laboratories drive cloud-native deployment adoption at faster procurement cycles.
United States
FDA 510(k) clearance pathways for clinical decision support software are tightening validation protocols for algorithmic transparency. Hospital laboratories across the Midwest and Southeast are expanding digital pathology workflows to compress diagnostic turnaround from days to hours. Reference laboratories in Texas and Illinois are displacing manual pathologist review with automated classification systems.
Germany
EU Medical Device Regulation software classification rules extend quality management obligations to cloud-hosted analytical platforms. University medical centers in Bavaria and Baden-Württemberg are integrating spectroscopy-linked analysis into routine urology workflows. The KBA medical device oversight framework shapes procurement specifications for CE-marked algorithmic modules.
Japan
PMDA software-as-a-medical-device pathways govern clinical-grade analytical platform distribution. METI digital health initiatives accelerate hospital IT infrastructure modernization for spectral data interpretation. Medical device clusters in the Kansai region around Osaka are deploying Raman spectral library systems for mineralogical classification.
United Kingdom
MHRA post-Brexit medical device regulations create parallel compliance tracks for stone analysis software vendors. NHS procurement frameworks favor cloud-based deployment models with transparent usage-based pricing. London and Southeast England health systems are centralizing pathology review across rural hospital clusters lacking on-site mineralogical expertise.
India
CDSCO medical device rules are harmonizing with international standards for software validation documentation. Private hospital chains in Maharashtra and Karnataka are adopting subscription-based access models to outsource infrastructure maintenance. Diagnostic laboratory networks in Delhi-NCR are deploying hybrid architectures blending local preprocessing with cloud classification.
Stone Analysis Software Market Competitive Landscape
United States producers anchor one tier; German and Japanese specialists hold differentiated positions in analytical instrumentation integration. Market structure concentrates around three to five dominant platform vendors with deep laboratory informatics heritage, while mid-tier players compete on modular AI bundling. Two strategic archetypes predominate: diversified life science conglomerates leveraging hardware-software integration, and pure-play software vendors pursuing subscription pricing penetration. Competitive moves center on cloud-native architecture reengineering and proprietary spectral database expansion.
Within the diversified instrumentation tier, Thermo Fisher Scientific and Beckman Coulter exemplify archetypes built on analytical hardware heritage extending into enterprise laboratory deployments. Agilent Technologies occupies a position representing spectroscopy-linked specialization for research-oriented installations. These three anchors demonstrate how vendor selection authority is shifting toward centralized IT governance committees under subscription pricing models.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Beckman Coulter |
| Agilent Technologies |
| Bruker Corporation |
| Bio-Rad Laboratories |
| Siemens Healthineers |
| Olympus Corporation |
| Stryker Corporation |
| GE HealthCare |
| Others |
Value Network & Pricing Analysis
EU MDR software classification mandates gate qualified supply for CE-marked algorithmic modules, concentrating premium-tier pricing access among vendors with documented ISO 13485 quality management systems. Hospital procurement committees in Germany and the United States now require compliant cloud architectures, bifurcating the vendor base into certified premium suppliers and research-only economy tiers.
Pricing Analysis
Capacity additions in United States cloud infrastructure are reshaping price floors for HIPAA-compliant stone analysis deployments. Subscription-SaaS tiered pricing dominates enterprise health systems, with differentiation resting on FDA 510(k) certification tier and AI module bundling depth. Cost compression in desktop software intensifies because rural hospital clusters prioritize data sovereignty over analytical sophistication. Research institutions exhibit lowest price sensitivity; mid-sized urology clinics face tightest budget constraints.
Supply Chain Analysis
Refurbishment flows for analytical instrumentation concentrate in German manufacturing centers, creating reverse-logistics value recovery for Raman and infrared spectral hardware. Component sourcing draws from German, Japanese, and United States precision optics suppliers. Single-source vulnerability runs through Japanese laser module manufacturers. Distribution runs through direct enterprise sales teams for hospital laboratories, with channel partners serving research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stone analysis software functions as a geographic-arbitrage play: FDA validation costs in the United States run substantially higher than CE marking pathways in Germany, creating cost-advantaged entry points for European vendors.
For Market Incumbents: To counter pure-play AI vendors bundling subscription algorithms, Thermo Fisher Scientific and Beckman Coulter should deepen hardware-software integration through proprietary API control over automated urinalysis workflows. Certification investment in EU MDR compliance documentation creates defensive moats against research-only platforms seeking clinical-grade expansion.
For New Entrants and Emerging Players: CDSCO harmonization with international software validation standards in India opens a window for SaaS-native vendors to capture mid-sized hospital chains in Maharashtra and Karnataka. White-space targets include rural United States health systems lacking on-site IT infrastructure and educational entities seeking browser-accessible training platforms. Go-to-market should emphasize transparent usage-based pricing to displace perpetual license incumbents.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play software vendors lacking analytical hardware heritage. Long-term viability hinges on regulatory clearance velocity across multiple jurisdictions. Acquisition targets should display proprietary spectral database depth and cloud-native architecture completion. Monitor FDA 510(k) submission volume from AI-powered entrants as inflection indicator for competitive intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Migration | Enables real-time renal stone characterization across distributed German hospital networks. |
| Proprietary Spectral Database Expansion | Raman library refinement at 5-10 micrometer resolution displaces destructive testing workflows. |
| FDA 510(k) Clearance Pathway Investment | Algorithmic transparency documentation satisfies tightened clinical decision support software requirements. |
| University Medical Center Partnership | Bavaria and Baden-Württemberg reference sites create procurement pull effects across EU urology departments. |
| Subscription Pricing Model Transition | Usage-based fees concentrate vendor selection authority in centralized United States IT governance committees. |
Research Methodology
Bottom-up hospital laboratory modeling reconciled against top-down analytical instrumentation tracking forms the analytical core. Primary interviews with urology department heads, hospital IT procurement officers, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and SEC disclosures from listed life science conglomerates. Triangulation between deployment volume estimates and vendor revenue segmentation ensures consistency.
Historical trendline analysis across installed base expansion and algorithmic performance improvement rates informed projection parameters. Segmentation dimensions span deployment model, end-user type, technology tier, and regional regulatory cluster. CAGRs derive from compound growth trajectory fitting against validated anchor points. Forecast inputs incorporate cloud adoption velocity in United States health systems and EU MDR compliance investment pacing among German university medical centers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA enforcement shifts or spectroscopy hardware supply disruptions. Practitioners should monitor CDSCO rule implementation progress and PMDA software-as-a-medical-device pathway developments for early signals of geographic demand redistribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Objectives & Key Results (OKR) Software Market
Software & Services
MCAD Software Market
Software & Services
Global Contract Lifecycle Management Software Market
Software & Services
B2B Price Optimization and Management Software Market
Software & Services
Content Moderation Software Market
Software & Services
Construction Software Market
Software & Services
Time Series Databases Software Market
Software & Services
Global Intellectual Property Management Software Market
Software & Services
Africa Financial Services Software Market
Software & Services
Middleware Market
Software & Services
Global Knowledge Management Software Market
Software & Services
Engineering Software Market
Software & Services
Solar Rooftop Design Software Market
Software & Services
3D Modeling Software Market
Software & Services
Commissioning Software Market
Software & Services
Workflow Automation and Optimization Software Market