
 Runtime Software Market | 2026-2036
Runtime Software Market Size, Share, and Industry Trends Forecast 2026-2036
Runtime Software Market Insights
The capital-intensity divergence between cloud-native platform builders and legacy on-premise maintainers is bifurcating competitive dynamics in runtime software. Siemens leverages its industrial automation installed base to sustain premium positioning in edge runtime environments. Red Hat competes through upstream control over container orchestration standards that anchor enterprise Linux subscriptions. Dassault Systèmes differentiates by embedding runtime engines within digital-twin workflows that dominate aerospace simulation pipelines.
Runtime software constitutes the execution-layer infrastructure that enables application code to operate on target hardware or virtualized environments, encompassing interpreters, virtual machines, and container runtimes that manage memory allocation, thread scheduling, and system call abstraction. Its primary commercial purpose is to abstract hardware complexity so developers can deploy consistent performance across heterogeneous compute substrates. Cloud-based deployment models are capturing the fastest expansion as enterprises migrate batch workloads to Kubernetes-orchestrated environments, while on-premise installations retain margin concentration in regulated sectors requiring air-gapped operation. Middleware segments lead revenue contribution by serving as the integration fabric between legacy SCADA systems and modern microservices architectures.
The EU AI Act imposes conformity assessment requirements on runtime components embedded in high-risk automation systems, while FDA software-as-medical-device guidance mandates traceability across runtime version chains for healthcare deployments. Germany's BSI IT-Grundschutz standards and Japan's METI cybersecurity framework for critical infrastructure further fragment compliance obligations across supply chains. Stakeholders must monitor divergence between regional certification regimes when architecting multi-tenant runtime platforms that serve both European automotive and North American healthcare verticals.
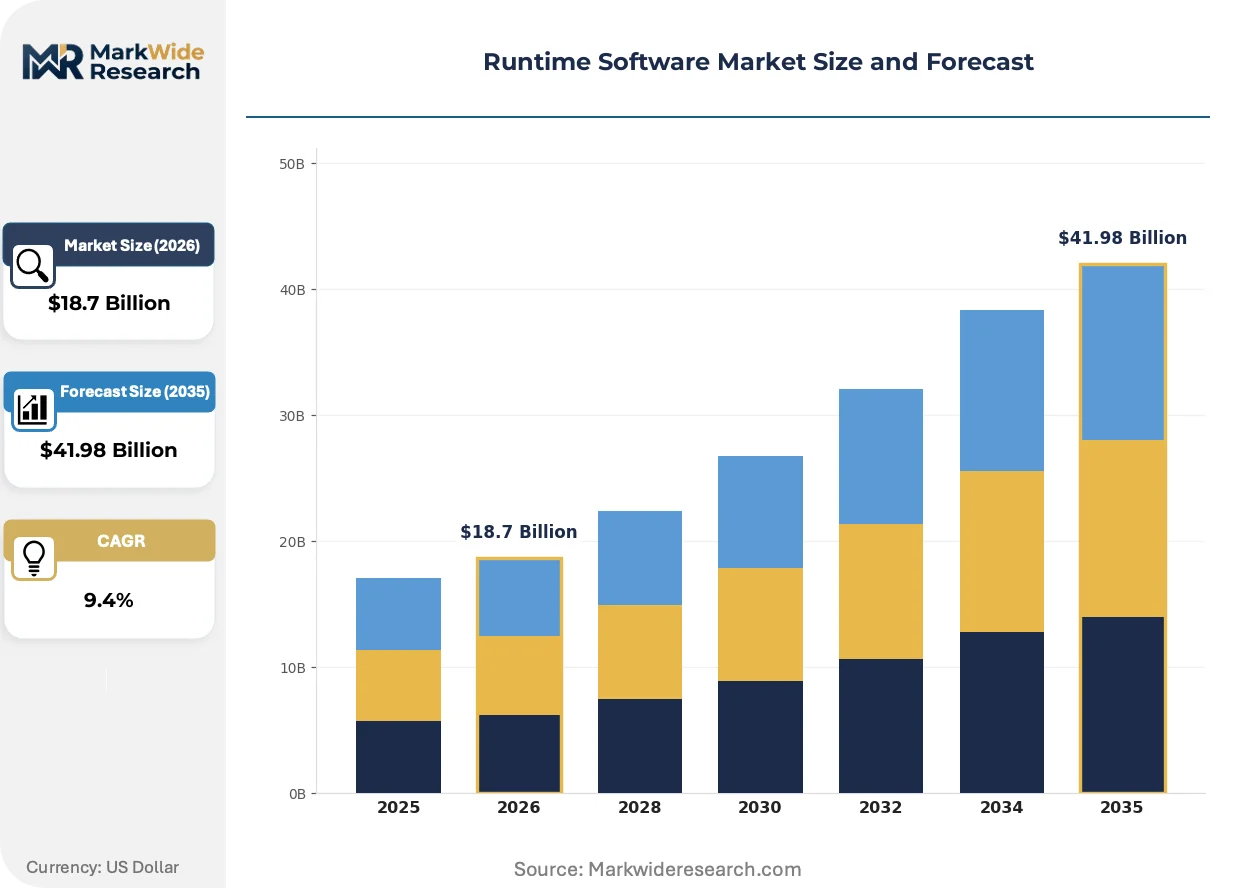
Market Dynamics
Container runtime abstraction is compressing hardware-specific development cycles as enterprises consolidate heterogeneous compute estates under Kubernetes-orchestrated control planes, forcing legacy virtualization vendors to reposition toward edge-native execution environments.
Growth Catalysts
- EU AI Act conformity assessments:High-risk automation deployments in Germany and France now require certified runtime chains, creating mandatory upgrade cycles for industrial middleware vendors serving automotive and medical device manufacturers.
- Edge AI inference expansion:Autonomous driving programs at BMW, Volkswagen, and Mercedes-Benz are procuring embedded runtime platforms that guarantee deterministic latency for sensor fusion pipelines.
- Industrial automation cluster density:Bavaria's Munich-Stuttgart corridor concentrates demand for real-time operating systems that bridge legacy SCADA with containerized microservices.
Market Restraints
- Specialized engineering talent scarcity:Safety-critical runtime certification requires engineers fluent in DO-178C and ISO 26262, with fewer than four thousand qualified practitioners available across Europe.
- Silicon supply concentration:Arm-based embedded processor allocation prioritizes consumer electronics, constraining automotive runtime platform production timelines.
- Legacy codebase entrenchment:Decades of COBOL and Fortran runtime dependencies in financial services block migration to modern orchestration stacks.
Strategic Opportunities
- Healthcare runtime-as-medical-device:FDA software-as-medical-device guidance creates first-mover advantage for vendors building traceable version chains into diagnostic imaging and patient monitoring systems.
- WebAssembly edge deployment:Convergence of Wasm sandboxing with Kubernetes scheduling enables near-native performance in resource-constrained factory floor gateways.
- Japan METI cybersecurity framework:Critical infrastructure operators in energy and transportation must upgrade runtime environments to meet 2025 attestation deadlines.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous EU AI Act, FDA, and BSI IT-Grundschutz approvals extend product launch cycles by fourteen to eighteen months for safety-critical runtime platforms.
- Legacy integration complexity:OPC-UA and Modbus protocol stacks in existing industrial plants resist seamless containerization, requiring costly protocol gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Runtime Software Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: IT Services, Telecommunications, Healthcare, Automotive Software Type: Middleware, Application Software, System Software, Frameworks Programming Language: Java, Python, C++, JavaScript |
| Companies Covered | Siemens, Rockwell Automation, Dassault Systèmes, Red Hat, Dell Technologies, PTC, Autodesk, Cloud Foundry, Diamanti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Runtime Software Market Trends and Innovations
Unikernel architectures are stripping away general-purpose operating system overhead to deliver single-purpose runtime environments with attack surfaces measured in thousands rather than millions of lines of code.
WebAssembly runtime engines are miniaturizing deployment artifacts to kilobyte-scale binaries while preserving sandboxed execution guarantees. Automotive Tier-1 suppliers at Bosch and Continental are piloting Wasm modules for in-vehicle infotainment isolation. This compression is miniaturizing the boundary between edge sensors and cloud training pipelines, collapsing latency budgets from hundreds to tens of milliseconds.
REACH substance restrictions and RoHS compliance deadlines are forcing runtime hardware partners to eliminate lead-based solders and halogenated flame retardants from embedded processor modules. Industrial automation OEMs must requalify thermal management designs before 2026 certification renewals. German machine builders are responding by shifting procurement to domestic PCB fabricators with established green chemistry credentials.
Subscription-based runtime licensing is displacing perpetual seat models as cloud-native buyers demand consumption-aligned cost structures. Siemens and Red Hat now price edge runtime environments by container-hour rather than socket count. This pivot is most visible among North American automotive startups lacking capital for upfront enterprise agreements.
Runtime Software Market Segmentation
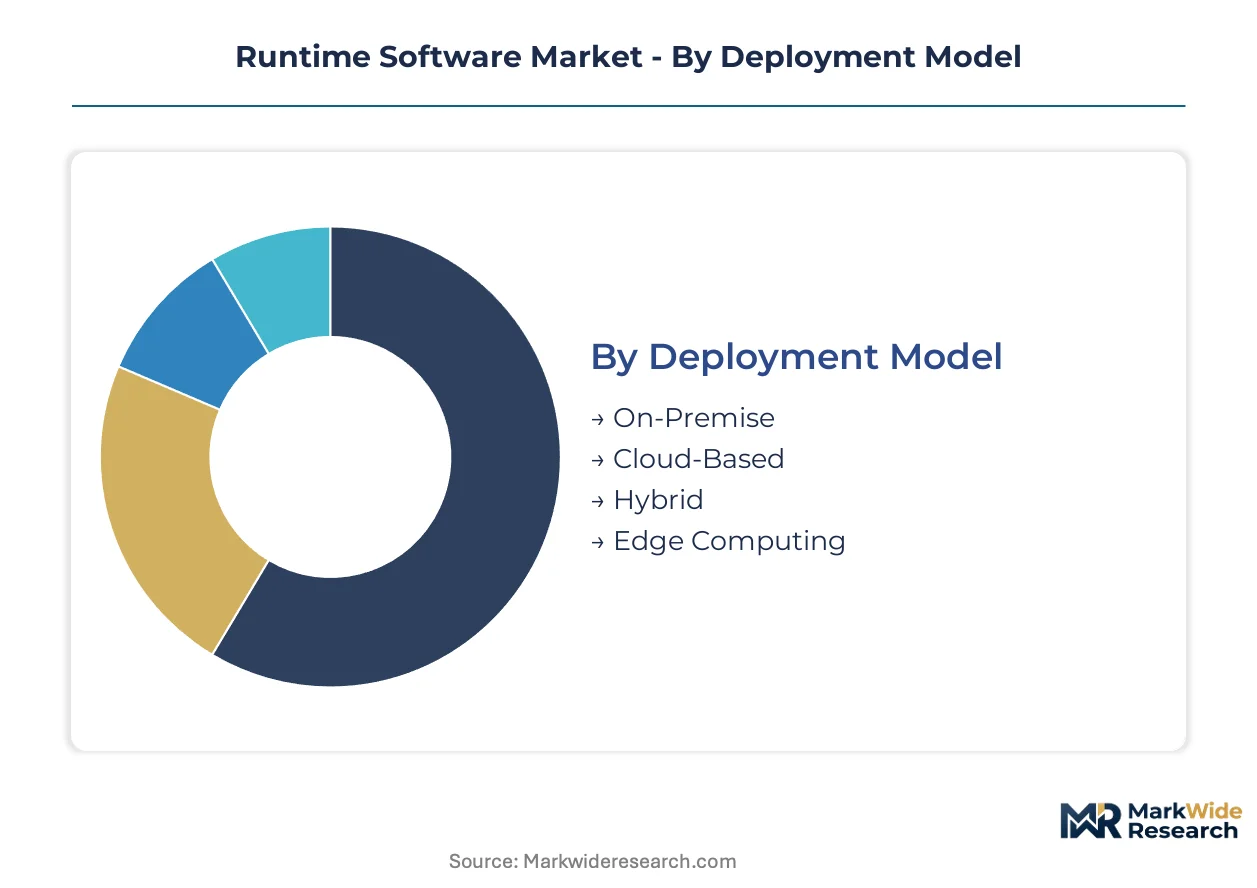
Runtime software segmentation reveals how compliance architecture and compute topology intersect. Deployment models determine certification pathways, while end-user verticals impose divergent latency and safety requirements.
Deployment Model:
EU AI Act conformity assessments split procurement between certified edge runtimes and exempt cloud-native stacks. German industrial buyers prioritize attested on-premise environments for high-risk automation.
- On-Premise:Air-gapped execution environments satisfy BSI IT-Grundschutz requirements for critical infrastructure operators. Bavarian automotive suppliers deploy these in sensor fusion pipelines where deterministic latency is mandatory.
- Cloud-Based:Kubernetes-orchestrated container runtimes abstract heterogeneous compute estates. North American healthcare startups lacking capital for upfront licenses gravitate toward consumption-aligned hourly pricing.
- Hybrid:Split workloads across certified edge nodes and scalable cloud burst capacity.
- Edge Computing:Embedded runtime platforms guarantee millisecond-scale inference for autonomous driving systems.
On-Premise handles the majority of throughput; Edge Computing is the fastest mover on share.
End User:
Customer archetypes range from capital-constrained startups to compliance-heavy multinationals with captive engineering teams.
- IT Services:Managed service providers orchestrate multi-tenant runtime platforms across client estates. These vendors absorb certification complexity for mid-market enterprises lacking in-house DO-178C expertise.
- Automotive:BMW, Mercedes-Benz, and Volkswagen procurement teams specify embedded runtimes for autonomous driving programs. FDA software-as-medical-device guidance simultaneously shapes healthcare runtime specifications.
- Telecommunications:5G network function virtualization drives container runtime adoption at edge PoPs.
- Healthcare:Diagnostic imaging and patient monitoring systems require traceable version chains.
IT Services captures the broadest addressable base; Automotive climbs the fastest on contract value.
Software Type:
Margin concentration varies with abstraction depth and integration burden.
- Middleware:Integration fabric between legacy SCADA and modern microservices architectures. Munich-Stuttgart industrial automation clusters drive enterprise procurement of real-time middleware bridging OPC-UA protocol stacks.
- System Software:Virtual machines and container runtimes managing memory allocation and thread scheduling.
- Application Software:Domain-specific execution engines for vertical workloads.
- Frameworks:Developer productivity layers abstracting hardware complexity.
Middleware dominates revenue contribution; Frameworks show steepest expansion trajectory among cloud-native buyers.
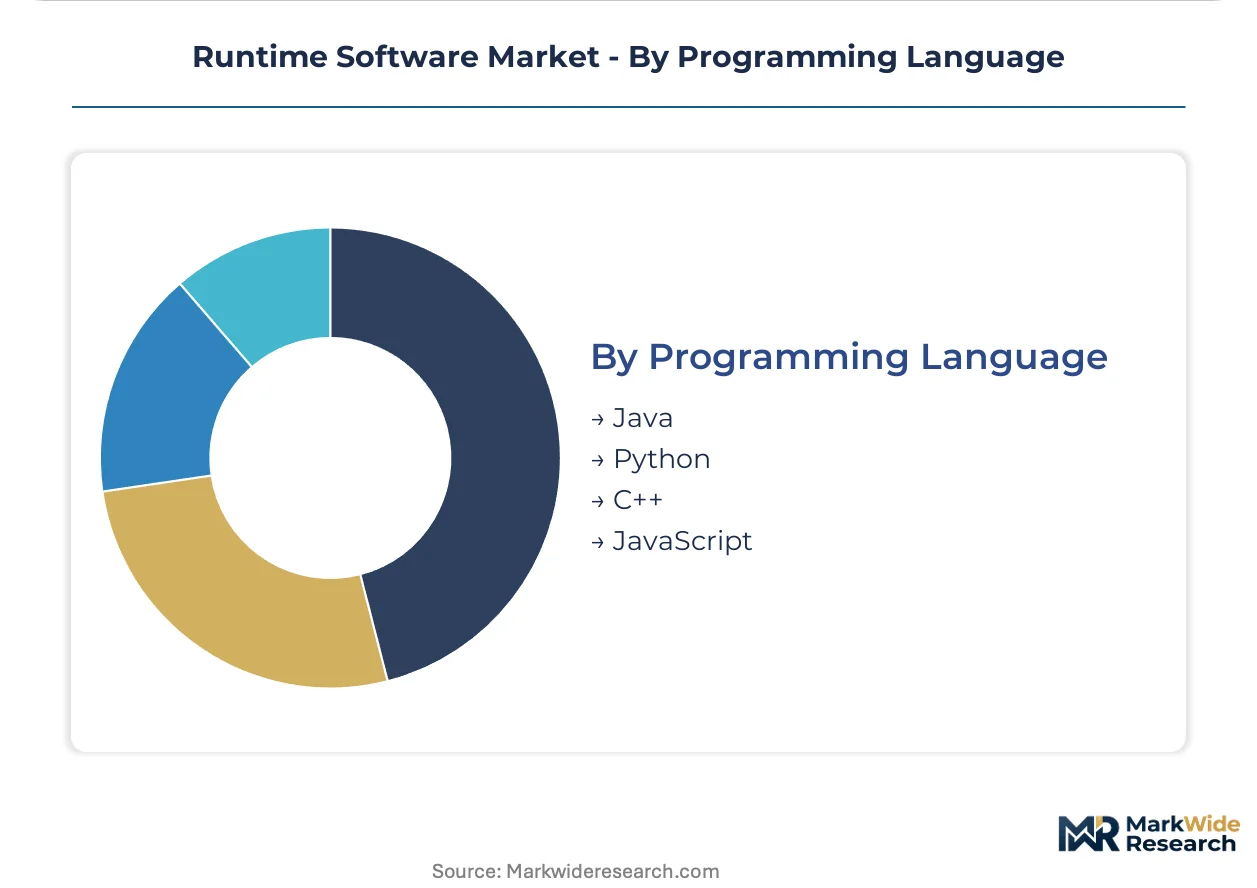
Programming Language:
Runtime engine selection constrains talent pools and safety certification pathways.
- Java:Enterprise JVM deployments retain dominance in financial services middleware. Decades of COBOL and Fortran runtime dependencies nonetheless block migration to modern Java orchestration stacks.
- C++:Deterministic performance for automotive and aerospace safety-critical systems.
- Python:Data science and AI/ML inference workloads.
- JavaScript:WebAssembly compilation targets for edge sandboxing.
Java maintains installed base leadership; JavaScript gains share fastest via WebAssembly miniaturization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation clusters command premium pricing for certified edge runtimes, while North American cloud-native buyers negotiate consumption-aligned hourly rates. Japan's METI cybersecurity deadlines compress procurement timelines for critical infrastructure operators. India's IT services exporters absorb multi-jurisdiction compliance complexity for mid-market enterprises lacking captive engineering teams.
Germany
Bavaria's Munich-Stuttgart corridor concentrates demand for real-time operating systems bridging legacy SCADA with containerized microservices. BSI IT-Grundschutz standards mandate air-gapped execution environments for critical infrastructure operators. Baden-Württemberg automotive suppliers deploy attested on-premise runtimes in sensor fusion pipelines where deterministic latency is mandatory.
United States
FDA software-as-medical-device guidance shapes healthcare runtime specifications for diagnostic imaging and patient monitoring systems. HIPAA requirements constrain multi-tenant platform architectures serving North American healthcare verticals. Detroit-area automotive programs procure embedded runtime platforms for autonomous driving sensor fusion.
Japan
Tokyo-based critical infrastructure operators in energy and transportation must upgrade runtime environments to meet METI cybersecurity framework attestation deadlines. Chubu region manufacturing clusters drive enterprise middleware procurement for industrial automation retrofits. Osaka-area telecommunications providers deploy container runtimes at 5G network edge points of presence.
India
Bengaluru and Hyderabad IT services hubs orchestrate multi-tenant runtime platforms across client estates, absorbing EU AI Act and FDA certification complexity. BIS standards for electronics manufacturing influence embedded processor module procurement. Maharashtra industrial zones pilot WebAssembly edge deployment for factory floor gateway miniaturization.
China
MIIT cybersecurity regulations for critical information infrastructure mandate domestic runtime certification pathways. Yangtze River Delta manufacturing clusters integrate edge AI inference platforms for quality control automation. Shenzhen-based automotive electronics suppliers source Arm-based embedded processors for in-vehicle runtime environments.
Runtime Software Market Competitive Landscape
Concentration sits with industrial automation incumbents leveraging installed bases to sustain premium positioning in edge runtime environments. The vendor landscape splits between cloud-native platform builders and legacy on-premise maintainers, with middleware specialists occupying the integration layer between SCADA and microservices. Strategic moves center on M&A for safety-critical certification capabilities and geographic expansion into German industrial clusters.
Among Germany-based industrial software providers, Siemens AG exemplifies the automation incumbent archetype, while Dassault Systèmes S.A. occupies a position within digital-twin-integrated runtime engines. Red Hat represents the cloud-native platform builder archetype through upstream container orchestration influence. These three anchors illustrate the competitive tension between edge-certified premium positioning and cloud-native consumption models.
| Leading Market Players |
|---|
| Siemens |
| Rockwell Automation |
| Dassault Systèmes |
| Red Hat |
| Dell Technologies |
| PTC |
| Autodesk |
| Cloud Foundry |
| Diamanti |
| Others |
Pricing and Supply Chain Analysis
EU AI Act conformity assessments gate both supplier qualification and price differentiation simultaneously, forcing runtime vendors to absorb certification costs into tiered offerings while buyers in Germany's industrial clusters pay premiums for attested edge environments.
Pricing Analysis
Configured-to-order pricing for safety-certified runtime stacks commands spreads of forty to sixty percent above standard cloud-native subscriptions. Subscription models now dominate, with Siemens and Red Hat pricing by container-hour rather than perpetual socket licenses. Price differentiation rests on certification depth—DO-178C and ISO 26262 attested tiers extract premiums from automotive procurement teams—while cost compression in exempt cloud tiers intensifies as North American healthcare startups negotiate consumption-aligned rates. Capital-constrained buyers in cloud-native segments exhibit highest price sensitivity; German automotive OEMs demonstrate lowest sensitivity where deterministic latency is mandatory.
Supply Chain Analysis
Arm-based embedded processor allocation from Taiwan and South Korea creates a chokepoint constraining automotive runtime platform production timelines. Runtime hardware partners draw from Chinese PCB fabrication, German precision component suppliers, and Japanese semiconductor packaging. Single-source vulnerability concentrates in Arm architecture licensing, where automotive Tier-1 suppliers face allocation rationing. Distribution runs through direct enterprise sales for certified edge stacks and hyperscaler marketplaces for cloud-native container runtimes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Runtime software demand is recovering from cyclical compression in industrial capital expenditure, with EU AI Act compliance deadlines now triggering mandatory upgrade cycles across German and French manufacturing bases.
For Market Incumbents: Compound certification moats by acquiring specialist safety-critical engineering boutiques in Bavaria and Baden-Württemberg. Deepen upstream control over container orchestration standards to anchor enterprise Linux subscription renewal rates against emerging Wasm-native challengers.
For New Entrants and Emerging Players: Mid-market IT services providers in India absorb multi-jurisdiction compliance complexity without captive DO-178C expertise, creating a service-layer gap for runtime-as-a-service orchestration. Penetrate North American healthcare startups lacking capital for upfront enterprise agreements through consumption-aligned hourly pricing and pre-validated FDA software-as-medical-device version chains.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native runtime segments as container-hour consumption models displace perpetual license infrastructure. Long-term viability favors vendors with installed bases in safety-critical verticals where certification timelines deter new entrants. Watch for WebAssembly runtime engine consolidation as the inflection signal—pilot deployments at Bosch and Continental suggest enterprise readiness acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | DO-178C certification capabilities compress fourteen-month approval timelines for automotive runtime deployments. |
| Platform Integration | Embedding Wasm engines within Kubernetes control planes collapses latency budgets for factory floor gateways. |
| Geographic Expansion | Munich-Stuttgart corridor concentration demands local engineering presence for BSI IT-Grundschutz compliance support. |
| Strategic Partnership | Hyperscaler alliances channel cloud-native runtime consumption to capital-constrained healthcare startups. |
| Product Launch | Traceable version chain tooling addresses FDA software-as-medical-device guidance for diagnostic imaging systems. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with industrial automation procurement managers, platform engineering leads at automotive OEMs, healthcare IT compliance officers, and embedded systems architects. Secondary validation drew from FDA software-as-medical-device guidance documents, EU AI Act implementing acts, BSI IT-Grundschutz certification registries, and hyperscaler capex disclosures. Bottom-up sizing of container runtime deployments triangulated against top-down industrial software market estimates.
Across the analysis window, projections segmented by deployment model, end-user vertical, software type, and regional regulatory cluster generated volume and value trajectories. CAGRs derived from regression against industrial capital expenditure cycles, compliance deadline schedules, and cloud migration penetration curves. Edge AI inference deployment timelines and WebAssembly runtime engine adoption rates served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU AI Act, FDA, and BSI IT-Grundschutz regimes; material policy shifts would require re-modeling. Semiconductor allocation rationing and safety-critical engineering talent scarcity represent specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as METI cybersecurity framework deadlines and REACH substance restriction enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Absence and Leave Management Software Market
Software & Services
Global Invoice Automation Software Market
Software & Services
Embedded Software Market
Software & Services
K8s Market
Software & Services
Nonconformance Management Software Market
Software & Services
PCB Layout Software Market
Software & Services
Account-Based Data Software Market
Software & Services
Global Church Management Software Market
Software & Services
ELD Compliance Software Market
Software & Services
Global Recreation Management Software Market
Software & Services
Global Internal Communications Software Market
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Global Continuous Testing Market
Software & Services
Global CMDB Software Market
Software & Services
Retail Core Banking Solution Market
Software & Services
Global Text to Speech (TTS) Software Market