
 Global Demand Planning Software Market | 2026-2036
Global Demand Planning Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Demand Planning Software Market Foresight
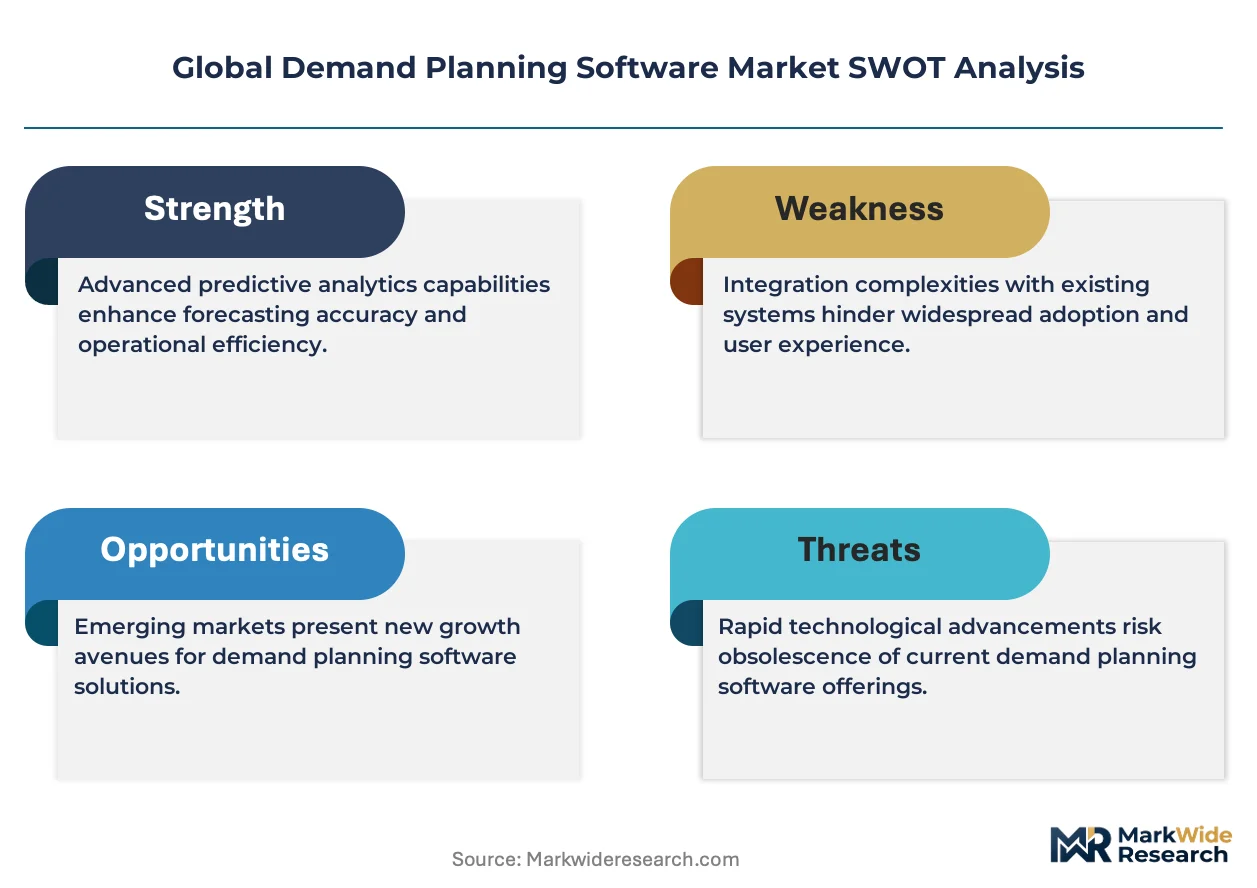
GDPR enforcement is decoupling data residency from software licensing in European procurement. Blue Yonder leverages its cloud-native architecture to anchor multi-tenant deployments across the region. SAP Integrated Business Planning dominates on-premise installations in regulated industries. o9 Solutions specializes in AI-driven scenario modeling for complex supply networks.
Demand planning software encompasses algorithmic platforms that synthesize historical sales, external signals, and inventory positions to generate statistically derived forecasts, typically operating through machine learning pipelines with refresh cycles under 24 hours for demand sensing applications. Cloud-based deployment leads solution delivery as enterprises retire legacy ERP modules, while demand sensing represents the fastest-expanding solution type as retailers seek granular SKU-level responsiveness. Inventory optimization commands premium pricing due to its direct linkage to working capital reduction metrics.
The EU AI Act, FDA 21 CFR Part 11, and India's DPDP Bill are elevating audit trail and explainability requirements across deployment modes. These frameworks compel vendors to embed governance layers that document forecast lineage and bias testing. Stakeholders must evaluate whether their current platforms satisfy emerging algorithmic accountability mandates before contract renewals.
Market Dynamics
Retail chains are consolidating procurement around demand sensing modules that compress forecast refresh cycles below 24 hours, while the EU AI Act forces vendors to embed algorithmic governance layers that document forecast lineage and bias testing.
Growth Catalysts
- Demand Sensing Technology:Machine learning pipelines processing external signals and inventory positions enable SKU-level responsiveness for retailers managing complex omnichannel networks.
- EU AI Act:Algorithmic transparency mandates are accelerating vendor investment in explainable forecasting models, creating competitive differentiation for compliant platforms.
- Cloud Migration:Enterprises retiring legacy ERP modules are driving multi-tenant deployments, with working capital reduction metrics directly linking inventory optimization to procurement decisions.
Market Restraints
- Data Residency Complexity:GDPR enforcement is decoupling software licensing from data location requirements, forcing architectural redesigns for European deployments.
- Integration Friction:On-premise installations in regulated industries face extended validation timelines against FDA 21 CFR Part 11 audit trail requirements.
- Skill Scarcity:Shortages of data scientists capable of tuning machine learning pipelines for supply network complexity limit enterprise adoption velocity.
Strategic Opportunities
- India's DPDP Bill:Emerging data protection frameworks create first-mover advantages for vendors establishing compliant cloud infrastructure ahead of enforcement.
- AI-Driven Scenario Modeling:Convergence of digital twin technology with predictive analytics opens white space for complex supply network optimization.
- Mid-Market Penetration:Underpenetrated manufacturing clusters in Germany present expansion opportunities for modular, rapidly deployable demand planning suites.
Industry Challenges
- Legacy System Entanglement:SAP Integrated Business Planning deployments in regulated sectors create switching costs that compress vendor margins during renewal negotiations.
- Algorithmic Accountability:Documentation of forecast bias testing and model drift monitoring requires dedicated governance functions that strain mid-market IT organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Demand Planning Software Market |
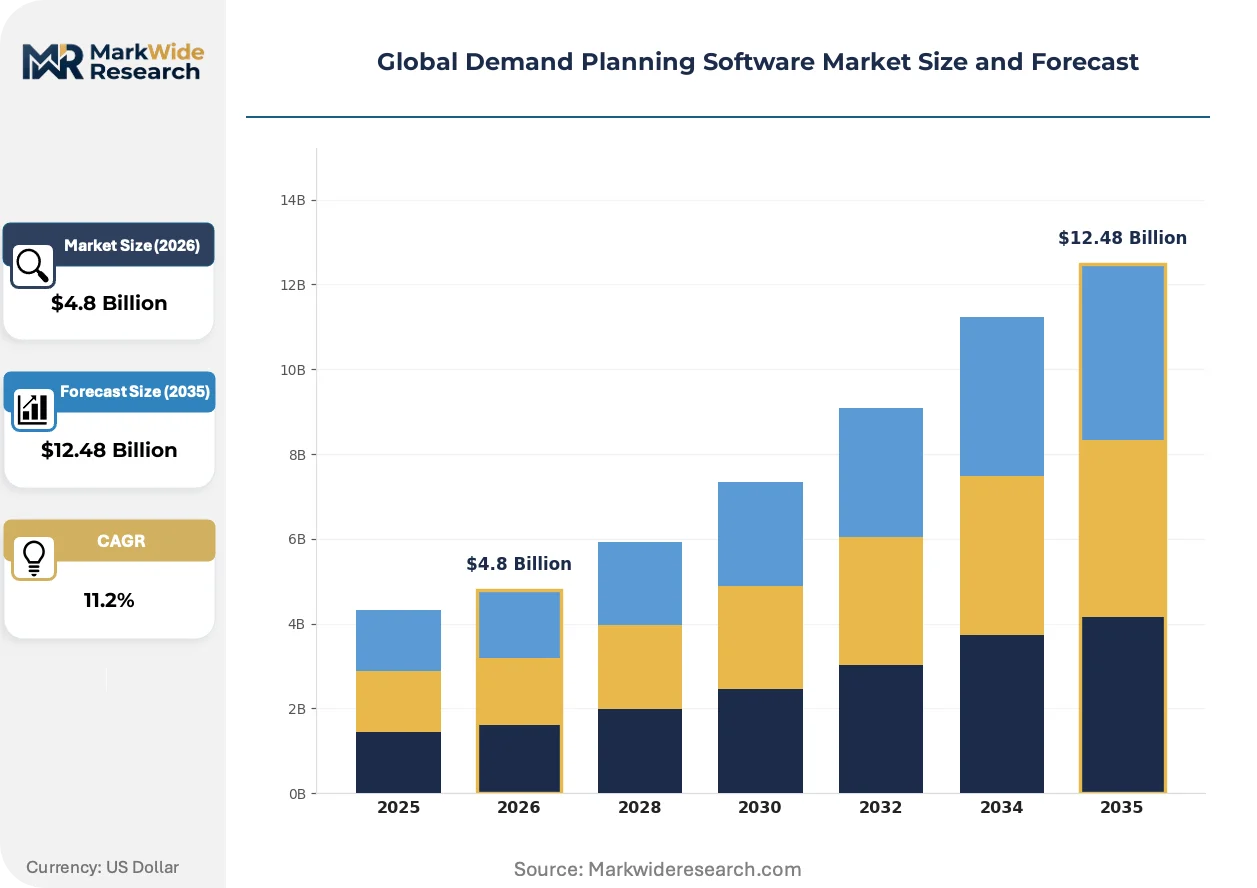
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
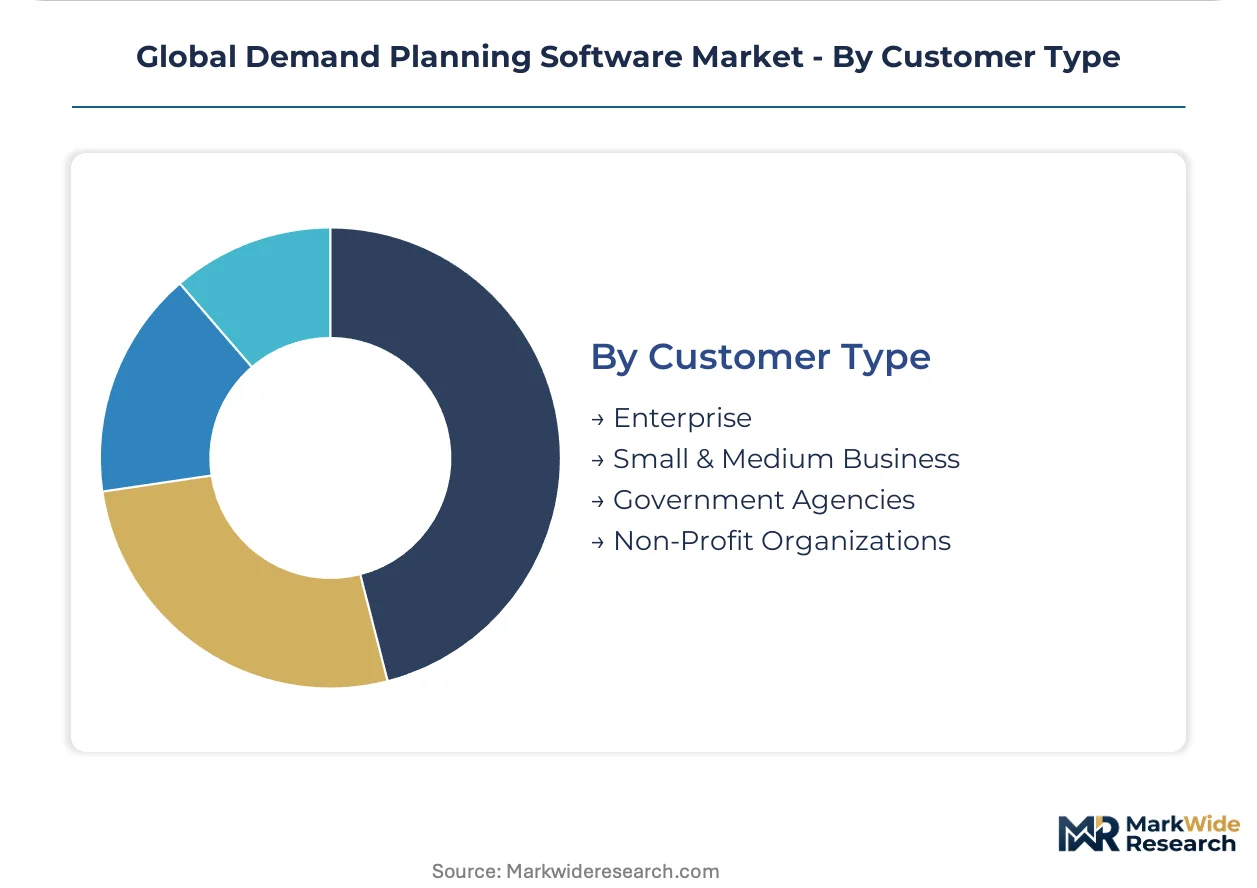
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, SaaS Solution Type: Forecasting, Inventory Optimization, Sales & Operations Planning, Collaborative Planning, Demand Sensing Application: Retail Chains, Manufacturing Facilities, Distribution Centers, E-Commerce Platforms, Wholesale Suppliers Customer Type: Enterprise, Small & Medium Business, Government Agencies, Non-Profit Organizations |
| Companies Covered | o9 Solutions, Oracle Demantra, Anaplan, Infor Demand Planning, IBM Planning Analytics, Blue Yonder, Kinaxis, Board, SAP Integrated Business Planning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Demand Planning Software Market Shifts & Advancements
Federated learning architectures and edge computing are redistributing computational load across supply networks, while regulatory pressure on algorithmic transparency intensifies vendor differentiation strategies.
Edge-based demand sensing is decentralizing forecast generation by pushing machine learning inference to retail store locations and manufacturing plants. Grocery chains and fast-moving consumer goods manufacturers are deploying these architectures to reduce latency in inventory repositioning decisions. This topology is decentralizing control over demand signals away from centralized cloud data warehouses toward distributed nodes that respond to local stockout risks.
The EU AI Act's risk classification framework is elevating documentation requirements for predictive analytics used in critical supply decisions. Vendors must now maintain technical files demonstrating conformity with transparency and human oversight obligations. High-risk deployment scenarios in pharmaceutical and food supply chains face the steepest compliance ramps, with procurement teams demanding pre-contractual evidence of algorithmic governance.
Enterprise buyers are consolidating vendor relationships around platforms that unify demand planning with inventory optimization and supply network visualization. This bundling preference is displacing point solutions that lack embedded optimization engines. The pattern is most visible in United States-based retail and industrial conglomerates pursuing procurement simplification.
Global Demand Planning Software Market Segmentation
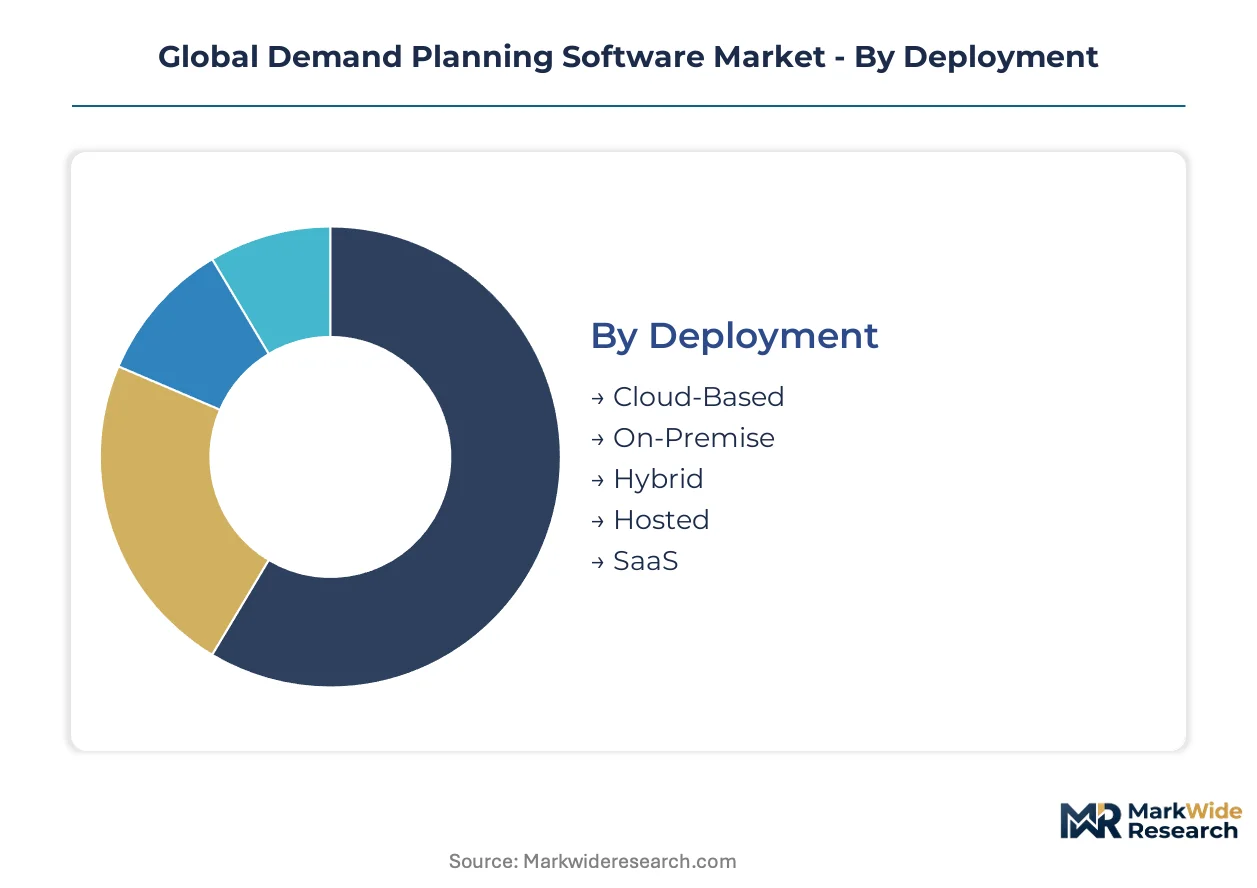
Segmentation in demand planning software reveals how regulatory compliance burdens, cloud migration trajectories, and customer scale requirements fragment procurement patterns across deployment modes and solution architectures.
Deployment:
Certification requirements diverge sharply across deployment modes, with FDA 21 CFR Part 11 imposing audit trail mandates on on-premise pharmaceutical installations while GDPR and the EU AI Act reshape cloud governance for European multi-tenant architectures.
- Cloud-Based:Multi-tenant architectures with sub-24-hour refresh cycles dominate retail and FMCG procurement. United States-based enterprise buyers are consolidating vendor relationships around platforms that unify demand sensing with inventory optimization, driven by working capital reduction metrics and procurement simplification mandates.
- On-Premise:Regulated industries—pharmaceutical manufacturing under FDA jurisdiction, food processing under EFSA oversight—maintain air-gapped installations to satisfy validation timelines and audit trail requirements. SAP Integrated Business Planning anchors these deployments, creating switching costs that compress vendor margins during renewal negotiations.
- Hybrid:Split architectures partition sensitive demand data on-premise while pushing computational workloads to cloud inference nodes.
- Hosted:Single-tenant managed deployments serve mid-market manufacturers lacking internal DevOps capacity.
- SaaS:Pure subscription models with embedded algorithmic governance layers address EU AI Act transparency obligations for mid-market European retailers.
Leading the category by volume: Cloud-Based. Growing fastest: SaaS.
Solution Type:
Cost tier differentiation separates premium-priced inventory optimization modules—linked directly to working capital metrics—from standardized forecasting tools facing commoditization pressure.
- Inventory Optimization:Embedded optimization engines command premium pricing through direct linkage to days-of-inventory and cash conversion cycle improvements. Germany's automotive suppliers and United States industrial conglomerates bundle these capabilities with supply network visualization, displacing point solutions lacking integrated engines.
- Demand Sensing:Machine learning pipelines processing external signals enable SKU-level responsiveness for omnichannel retail networks. Grocery chains in the United States and fast-moving consumer goods manufacturers deploy edge-based architectures to reduce latency in stockout-risk responses.
- Forecasting:Statistical baseline modules face margin compression as ML-augmented alternatives penetrate mid-market.
- Sales & Operations Planning:Cross-functional alignment platforms integrate financial planning with supply constraints.
- Collaborative Planning:Supplier-customer data sharing tools struggle against data residency friction under GDPR enforcement.
Highest margin capture: Inventory Optimization. Steepest expansion trajectory: Demand Sensing.
Application:
Volume concentration tracks retail digitalization intensity, with e-commerce platforms and retail chains driving refresh cycle compression while manufacturing facilities prioritize stability over responsiveness.
- Retail Chains:Omnichannel networks compress forecast refresh cycles below 24 hours through demand sensing modules. European retail procurement now demands pre-contractual evidence of EU AI Act algorithmic governance, elevating documentation requirements for predictive analytics in critical supply decisions.
- E-Commerce Platforms:Real-time inventory repositioning across distributed fulfillment nodes requires edge computing architectures. India's emerging DPDP Bill compliance creates first-mover positioning for vendors establishing cloud infrastructure ahead of enforcement.
- Manufacturing Facilities:Regulated production environments under FDA or EMA jurisdiction prioritize validation stability over sensing speed.
- Distribution Centers:Hub-and-spoke network optimization focuses on transshipment efficiency rather than demand signal processing.
- Wholesale Suppliers:Longer planning horizons and lower SKU granularity limit advanced analytics adoption velocity.
Deepest technology penetration: Retail Chains. Fastest capability upgrade cycle: E-Commerce Platforms.
Customer Type:
Maturity curves separate enterprise buyers with dedicated governance functions from resource-constrained mid-market organizations struggling to operationalize algorithmic accountability mandates.
- Enterprise:Consolidated procurement around unified platforms with embedded optimization and visualization capabilities. These buyers demand forecast lineage documentation and bias testing evidence under EU AI Act and emerging DPDP Bill frameworks, straining vendor professional services capacity.
- Small & Medium Business:Modular, rapidly deployable suites target underpenetrated manufacturing clusters in Germany. Skill scarcity in data science talent limits adoption velocity, creating whitespace for automated ML pipeline tuning.
- Government Agencies:Public procurement frameworks prioritize audit transparency over predictive accuracy.
- Non-Profit Organizations:Humanitarian supply chains adopt simplified forecasting for donor-funded inventory positioning.
Revenue concentration: Enterprise. Fastest onboarding improvement: Small & Medium Business.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in the United States, Germany, and India concentrate procurement for demand planning platforms, with each geography presenting distinct regulatory and deployment requirements that reshape vendor go-to-market strategies.
United States
Retail chains and industrial conglomerates drive cloud migration as enterprises retire legacy ERP modules. FDA 21 CFR Part 11 imposes audit trail mandates on pharmaceutical manufacturers, forcing extended validation timelines for on-premise installations. The Southeast manufacturing corridor and California tech clusters anchor multi-tenant deployments for demand sensing applications.
Germany
Automotive suppliers and industrial machinery producers bundle inventory optimization with supply network visualization capabilities. The EU AI Act's risk classification framework elevates documentation requirements for predictive analytics in critical supply decisions. Bavaria's automotive engineering clusters and North Rhine-Westphalia's chemical processing hubs prioritize platforms with embedded algorithmic governance layers.
India
E-commerce platforms and fast-moving consumer goods manufacturers deploy edge-based architectures for real-time inventory repositioning. The Digital Personal Data Protection Bill creates first-mover positioning for vendors establishing compliant cloud infrastructure ahead of enforcement. Karnataka's Bengaluru tech corridor and Maharashtra's Mumbai-Pune industrial belt concentrate procurement for mid-market manufacturing suites.
United Kingdom
Financial services and retail procurement teams demand pre-contractual evidence of GDPR-aligned data residency and algorithmic transparency. The UK Information Commissioner's Office guidance on automated decision-making shapes vendor disclosure requirements. London's fintech ecosystem and the Midlands manufacturing belt drive adoption of hybrid deployment architectures.
Japan
Electronics manufacturers and precision machinery producers prioritize supply network stability over sensing speed in forecast refresh cycles. METI's supply chain resilience initiatives encourage domestic cloud infrastructure investment. The Kanto region around Tokyo and the Chubu industrial corridor anchor deployments of AI-driven scenario modeling for complex supplier networks.
Global Demand Planning Software Market Competitive Landscape
United States producers anchor one tier of the competitive structure; European specialists hold differentiated positions around regulatory compliance capabilities. The vendor base organizes into three tiers: cloud-native platforms with embedded optimization engines, legacy ERP-integrated suites with entrenched on-premise footprints, and modular mid-market offerings with rapid deployment cycles. Consolidation pressure intensifies as enterprise buyers unify procurement around platforms combining demand sensing, inventory optimization, and supply visualization. M&A activity targets AI-native scenario modeling capabilities, while strategic partnerships address data residency requirements across GDPR and emerging DPDP Bill jurisdictions.
Within the cloud-native tier, Blue Yonder exemplifies multi-tenant architectural leadership across European deployments. SAP Integrated Business Planning occupies a position anchoring regulated industry installations with deep ERP integration requirements. o9 Solutions represents the AI-driven scenario modeling archetype for complex supply network optimization. These three companies illustrate how competitive positioning diverges across deployment mode specialization, regulatory compliance depth, and supply network complexity handling.
| Leading Market Players |
|---|
| o9 Solutions |
| Oracle Demantra |
| Anaplan |
| Infor Demand Planning |
| IBM Planning Analytics |
| Blue Yonder |
| Kinaxis |
| Board |
| SAP Integrated Business Planning |
| Others |
Supply & Pricing Matrix
Backward integration into cloud infrastructure and data residency architecture anchors pricing power for vendors serving European and Indian enterprise buyers. SAP Integrated Business Planning's captive on-premise deployments in regulated pharmaceutical manufacturing create switching-cost premiums that compress competitor margins during renewal cycles.
Pricing Analysis
Volume concentrates in standardized SaaS tiers while margin capture flows to inventory optimization modules with embedded governance layers. Three-tier pricing structure across premium, standard, and economy levels separates AI-driven scenario modeling capabilities from baseline statistical forecasting tools. Cost compression in mid-market forecasting tiers is intensifying because machine learning pipeline commoditization erodes differentiation. Small and medium businesses exhibit highest price sensitivity, while enterprise buyers prioritize algorithmic accountability documentation over per-seat economics.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure mandate multi-supplier qualification across United States, Germany, and India data center footprints. Software development draws from specialized machine learning engineering talent pools concentrated in Bengaluru, Berlin, and California tech corridors. Single-source vulnerability in GPU compute allocation for edge-based demand sensing creates procurement bottlenecks. Distribution runs through direct enterprise sales organizations supplemented by hyperscaler marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained data science talent propels pricing for automated ML pipeline tuning capabilities. Cloud infrastructure capacity bottlenecks in EU-regulated jurisdictions anchor premium positioning for compliant multi-tenant architectures.
For Market Incumbents: Deploy algorithmic governance certification as a defensive moat against cloud-native challengers. Extend professional services capacity to satisfy EU AI Act documentation demands from enterprise procurement teams. Fortify ERP integration depth in pharmaceutical manufacturing to exploit FDA 21 CFR Part 11 validation switching costs. For New Entrants and Emerging Players: Launch via modular, rapidly deployable suites targeting underpenetrated mid-market manufacturing clusters in Germany. Penetrate the small and medium business segment through automated ML pipeline tuning that offsets skill scarcity. Position against compliance burden by offering pre-configured EU AI Act technical file templates. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by hyperscalers seeking supply chain software adjacencies. Five-to-ten-year viability hinges on embedded optimization engine differentiation rather than standalone forecasting modules. Monitor India's DPDP Bill enforcement timeline as inflection indicator for compliant cloud infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unification of demand sensing with inventory optimization displaces point solutions lacking embedded engines. |
| Acquisition of Specialist Firm | AI-native scenario modeling capabilities command premium multiples in complex supply network optimization. |
| Strategic Partnership | Data residency alliances with regional cloud providers satisfy GDPR and emerging DPDP Bill requirements. |
| Product Launch | Edge-based demand sensing architectures reduce latency for grocery chains managing distributed fulfillment nodes. |
| Geographic Expansion | First-mover cloud infrastructure in Karnataka and Maharashtra captures India's DPDP Bill compliance demand. |
Research Methodology
Multi-period observation of forecast refresh cycle compression and algorithmic governance investment anchored the trend analysis, supplemented by interviews with supply chain executives, IT procurement officers, platform engineers, and data science directors. Primary fieldwork combined with secondary validation from SEC filings, hyperscaler capex disclosures, EU regulatory submissions, and trade databases. Bottom-up deployment mode sizing and top-down enterprise spending triangulation cross-verified volume estimates.
Input-output matrix framing connected machine learning pipeline complexity, regulatory compliance tier, and customer scale assumptions to revenue projections across the analysis window. Segmentation dimensions modeled include deployment architecture, solution type, customer maturity tier, and regional regulatory cluster. CAGRs derived from slope analysis of technology adoption curves and procurement consolidation patterns. Forecast inputs incorporated edge computing infrastructure deployment rates and EU AI Act enforcement trajectory.
Regulatory enforcement delays, cloud infrastructure capacity constraints, and data science talent availability are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding procurement consolidation velocity and compliance cost pass-through elasticity. A model refresh is warranted upon material change in EU AI Act high-risk classification implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Model Based Testing Tools Market
Software & Services
Global Polling Software Market
Software & Services
Output Management Software Market
Software & Services
HPC Software Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Content Moderation Software Market
Software & Services
Global Call Tracking Software Market
Software & Services
Global Guidewire Market
Software & Services
UK Point of Sale Software Market
Software & Services
Global Reporting Software Market
Software & Services
Interactive Digital Signage Software Market
Software & Services
Global Email Management Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Global Managed File Transfer (MFT) Software and Service Market
Software & Services
Global Product Information Management (PIM) Software Market
Software & Services
Data Visualization Software Market