
 Automated Storage and Retrieval Systems in Laboratories Market | 2026-2036
Automated Storage and Retrieval Systems in Laboratories Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Storage and Retrieval Systems in Laboratories Market Outlook
The FDA's 21 CFR Part 11 is realigning validation requirements for electronic records and signatures, forcing laboratories to retire manual inventory systems and adopt automated platforms with audit trails. Thermo Fisher Scientific leverages its cryogenic automation portfolio to dominate biobank deployments across North American research hospitals. Danaher Corp sustains competitive positioning through integrated informatics that connect storage hardware with LIMS workflows. LiCONiC AG specializes in ultra-low temperature automated storage, anchoring its presence in European pharmaceutical quality control labs.
Automated storage and retrieval systems in laboratories comprise electromechanical platforms that manipulate specimen containers, reagent vials, and chemical inventories within temperature-controlled environments, typically operating between ambient conditions and minus 150 degrees Celsius for cryogenic preservation, with throughput rates measured in picks per hour and positional accuracy within fractions of a millimeter. These systems serve primarily to eliminate human error in sample tracking, reduce occupational exposure to hazardous materials, and maximize storage density per square meter of expensive laboratory real estate. Vertical lift modules command the largest installed base among product types due to their proven reliability in high-throughput clinical diagnostics, while artificial intelligence-enabled predictive maintenance is emerging as the fastest-expanding technology segment as laboratories seek to minimize unplanned downtime during critical research cycles. Pharmaceutical laboratories represent the most margin-rich end-user category, driven by stringent chain-of-custody requirements for clinical trial materials and biologics.
The EPA's hazardous waste manifest regulations and OSHA's laboratory safety standards collectively shape equipment specifications for chemical storage modules, mandating secondary containment, fire suppression integration, and automated access logging. In Europe, the CE marking requirements under the Machinery Directive and the EU AI Act's risk classification framework for automated decision systems are creating dual compliance obligations for vendors deploying intelligent retrieval platforms. Stakeholders must monitor how evolving cybersecurity standards for connected laboratory infrastructure reshape procurement criteria and vendor qualification timelines.
Market Dynamics
The FDA's 21 CFR Part 11 mandate is forcing laboratories to replace manual inventory systems with validated automated platforms, compressing procurement cycles and elevating audit-trail capabilities from optional to mandatory specifications.
Growth Catalysts
- Biologics cold-chain expansion:Pharmaceutical laboratories are scaling cryogenic storage infrastructure to accommodate temperature-sensitive cell therapies and gene editing materials.
- 21 CFR Part 11 compliance deadlines:The FDA's electronic records validation requirements are accelerating replacement of legacy manual systems in United States clinical and quality control labs.
- GLP-GMP facility upgrades:Germany and China are witnessing intensive capital deployment into automated storage as precision medicine investments drive facility modernization.
Market Restraints
- Specialized component supply concentration:Precision linear motion systems and cryogenic-rated sensors concentrate among Japanese and German component suppliers, creating vulnerability.
- Capital intensity barriers:Automated storage platforms require substantial upfront investment in temperature-controlled enclosures and robotic manipulators, limiting mid-tier laboratory adoption.
- Technical integration limitations:Legacy laboratory information management systems lack API architectures that enable seamless data exchange with modern automated retrieval platforms.
Strategic Opportunities
- Underpenetrated Indian pharmaceutical quality control:CDSCO's tightening manufacturing standards are creating demand for validated automated storage in domestic generic drug production facilities.
- AI-enabled predictive maintenance convergence:Machine learning algorithms combined with vibration sensing are emerging as a service layer that reduces unplanned downtime during critical research cycles.
- EU AI Act risk classification:The automated decision-system framework is creating dual compliance obligations that favor vendors with integrated validation documentation.
Industry Challenges
- Mechatronics engineering talent scarcity:Laboratories struggle to recruit technicians capable of maintaining robotic manipulators operating across ambient to cryogenic temperature ranges.
- Validation timeline compression:FDA qualification protocols and IQ-OQ-PQ documentation requirements extend deployment schedules by months, delaying operational returns.
- Legacy system integration complexity:Retrofitting automated retrieval into existing freezer farms requires custom mechanical interfaces that inflate project costs and technical risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Storage and Retrieval Systems in Laboratories Market |
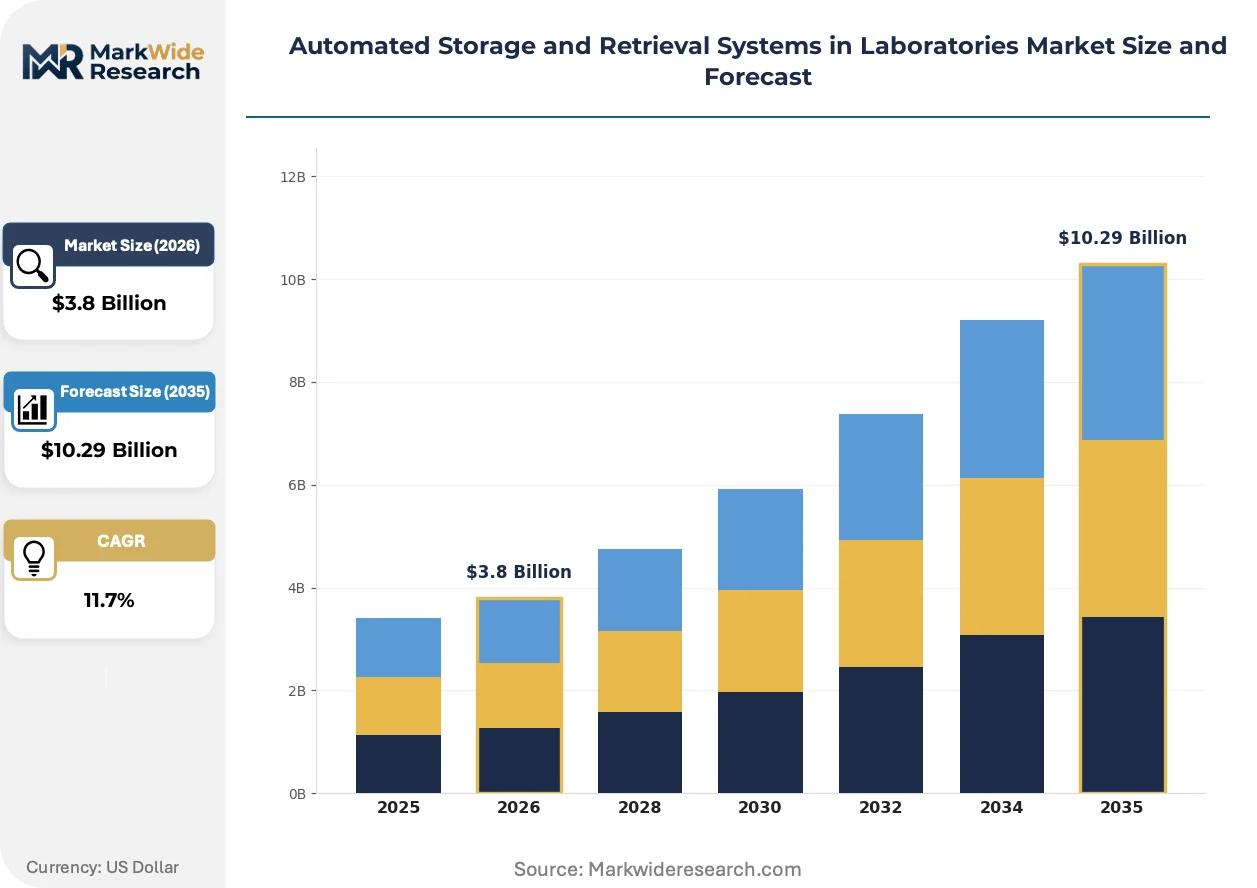
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Vertical Lift Modules, Mini Load Systems, Horizontal Carousels End User: Pharmaceutical Laboratories, Research Institutions, Clinical Laboratories, Industrial Labs Technology: RFID, Barcode Scanning, Artificial Intelligence, Robotics Application: Sample Management, Chemical Storage, Inventory Control, Data Management |
| Companies Covered | Thermo Fisher Scientific, Danaher Corp, Roche Holding AG, Honeywell International, Siemens Healthineers, LiCONiC AG, Azenta, SPT Labtech Ltd, MICRONIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Storage and Retrieval Systems in Laboratories Market Strategic Shifts
Artificial intelligence is penetrating laboratory infrastructure at the maintenance and optimization layer, shifting competitive advantage from hardware reliability toward predictive operational continuity. This transformation is compressing traditional service models and redefining procurement evaluation criteria.
Machine learning-based predictive maintenance is electrifying competitive positioning in the automated storage sector. These algorithms analyze vibration patterns, motor current signatures, and temperature cycling data to forecast component failures before they trigger sample integrity breaches. Pharmaceutical biobanks and clinical diagnostics laboratories are adopting these capabilities fastest, recognizing that unplanned downtime during longitudinal studies destroys irreplaceable specimen collections. The technology is compressing traditional break-fix service contracts toward outcome-based uptime guarantees.
The EU AI Act's risk classification framework for automated decision systems is reshaping vendor qualification requirements across European pharmaceutical quality control facilities. Systems that autonomously prioritize sample retrieval sequences or optimize storage density algorithms now face documentation burdens previously reserved for medical devices. German and Swiss laboratory equipment suppliers are responding by pre-integrating algorithmic transparency tools and human-in-the-loop override protocols into platform designs.
Service unbundling is fragmenting traditional procurement relationships in North American research hospital networks. Large academic medical centers are separating hardware acquisition from validation services, maintenance contracts, and software subscriptions, treating each as independently negotiable spend categories. This disaggregation is most visible in United States biobank deployments, where procurement teams now benchmark predictive maintenance algorithms separately from electromechanical platform specifications.
Automated Storage and Retrieval Systems in Laboratories Market Segmentation
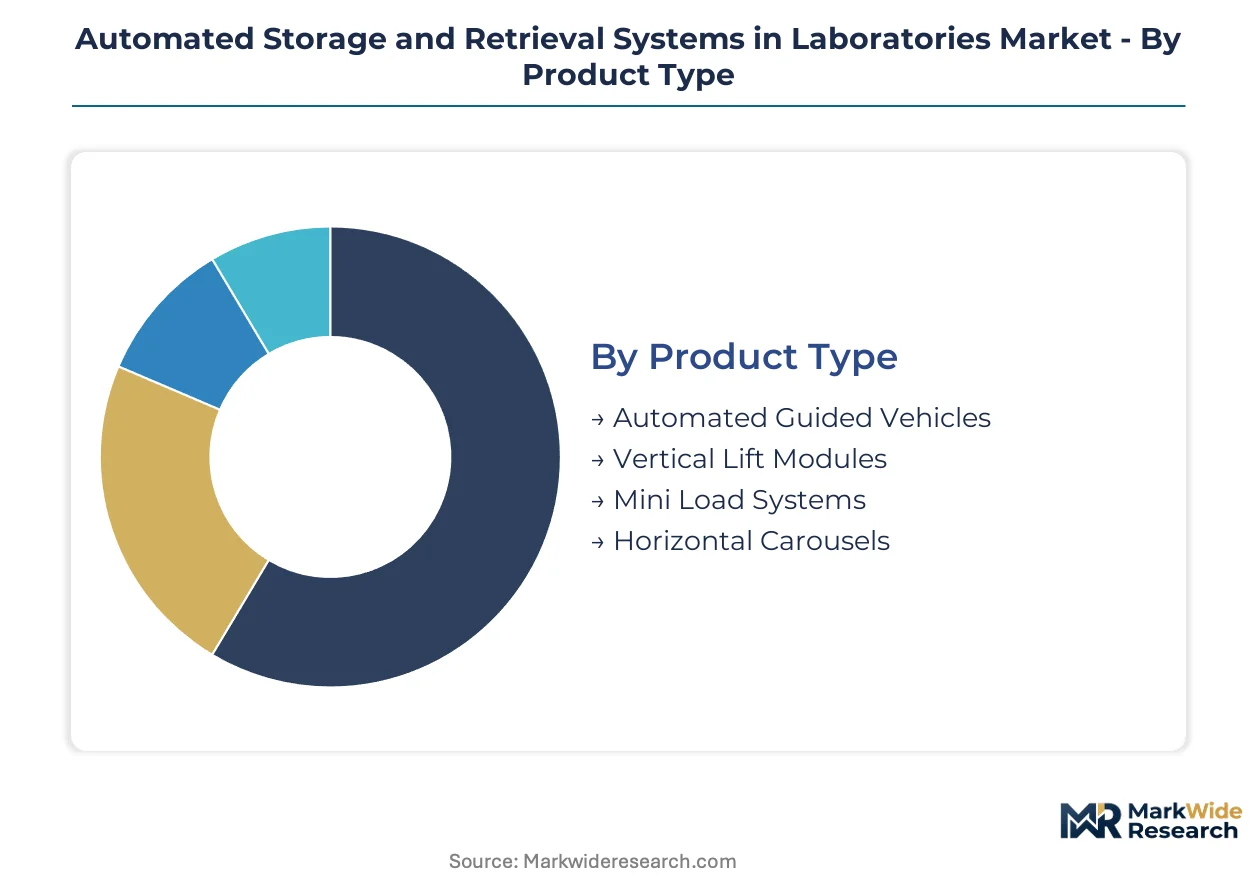
Laboratory automation procurement splits across hardware configurations, operational domains, and intelligence layers. Each segmentation axis reflects distinct capital deployment patterns and compliance obligations that reshape vendor qualification criteria.
Product Type:
Upgrade cycles favor platforms that retrofit into existing facility footprints without structural modification.
- Automated Guided Vehicles:Mobile robotic platforms transport specimen containers across laboratory zones, operating on magnetic tape or laser-guided navigation. Pharmaceutical laboratories in Germany deploy these for flexible biobank expansion without fixed infrastructure investment.
- Vertical Lift Modules:Enclosed column-based systems retrieve trays from vertical storage towers using internal extractors, maximizing cubic meter efficiency. Clinical diagnostics laboratories in the United States favor these for high-throughput specimen archiving where floor space commands premium lease rates.
- Mini Load Systems:Compact shuttle-based architectures handle small-lot reagent storage with sub-meter retrieval precision.
- Horizontal Carousels:Rotating shelf systems bring inventory to fixed operator stations, dominating legacy chemical storage retrofits.
Volume placements concentrate in Vertical Lift Modules; the faster expansion belongs to Automated Guided Vehicles.
End User:
Margin profiles diverge sharply based on chain-of-custody stringency and sample irreplaceability.
- Pharmaceutical Laboratories:GMP-validated environments store clinical trial materials and biologics under FDA 21 CFR Part 11 audit requirements. These facilities command the highest per-unit pricing due to qualification documentation burdens and cryogenic temperature specifications.
- Research Institutions:Academic biobanks and university core facilities prioritize specimen integrity for longitudinal studies over throughput velocity.
- Clinical Laboratories:Hospital-based diagnostics operations emphasize 24/7 uptime guarantees and rapid turnaround for patient-critical testing workflows.
- Industrial Labs:Quality control facilities in chemical and food sectors balance regulatory compliance with capital efficiency constraints.
Revenue concentration sits with Pharmaceutical Laboratories; Research Institutions are climbing the fastest as precision medicine funding expands specimen collection scale.
Technology:
Intelligence integration separates commodity hardware from differentiated platform offerings.
- Artificial Intelligence:Predictive algorithms optimize retrieval sequencing and forecast mechanical failures before sample integrity breaches occur. North American research hospitals are adopting these capabilities fastest to protect irreplaceable longitudinal specimen collections.
- Robotics:Multi-axis manipulators handle cryogenic vials and hazardous reagents across temperature extremes from ambient to minus 150 degrees Celsius.
- RFID:Radio-frequency identification enables non-line-of-sight inventory tracking through metal enclosures and liquid nitrogen vapor phases.
- Barcode Scanning:Optical verification systems remain the default for cost-sensitive installations with lower throughput requirements.
Deployment frequency peaks with Barcode Scanning; Artificial Intelligence is gaining share fastest as laboratories seek to minimize unplanned downtime during critical research cycles.
Application:
Use-case specificity determines temperature range, access control, and integration architecture requirements.
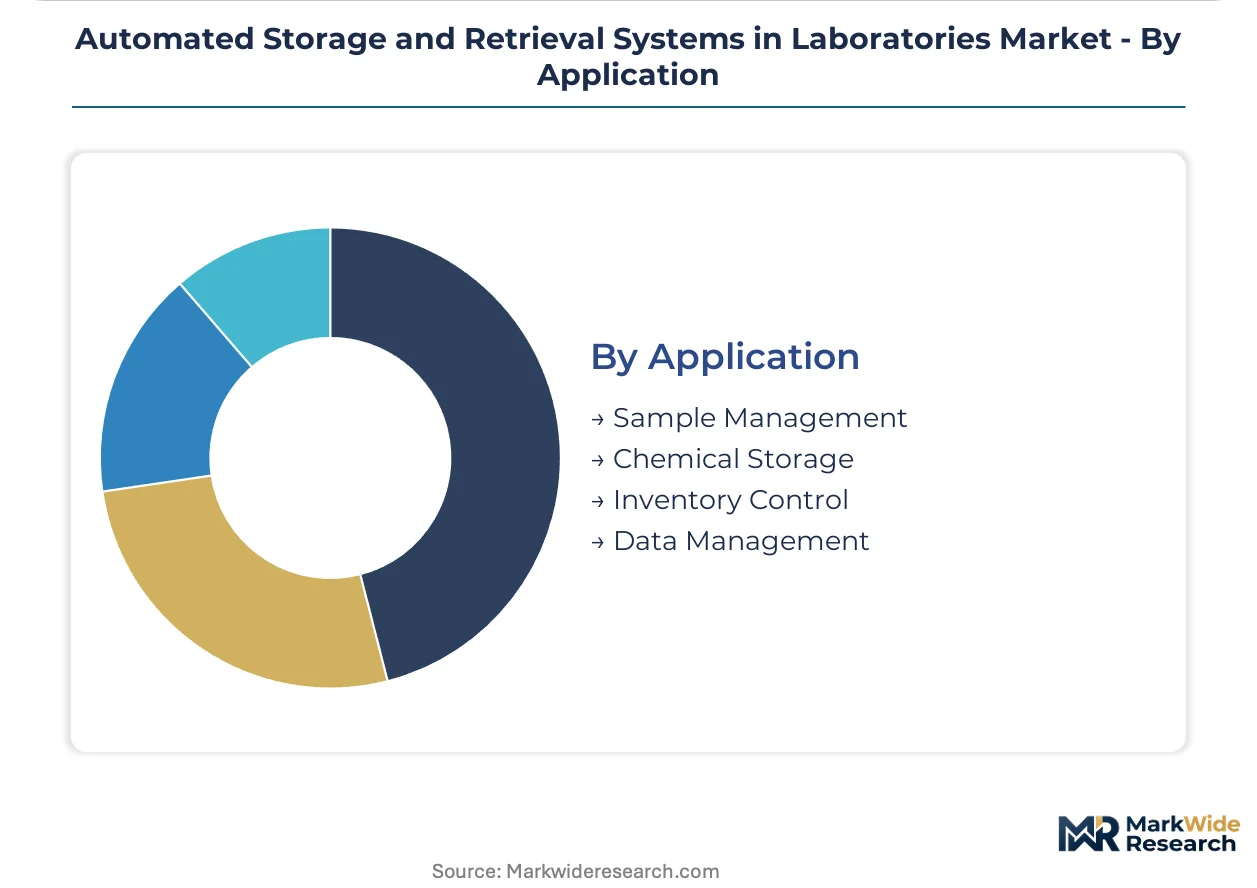
- Sample Management:Biobank operations track specimen provenance across decades-long storage horizons, mandating cryogenic preservation and immutable audit trails. These applications drive the most complex integration demands with LIMS and electronic health record systems.
- Chemical Storage:Hazardous material repositories require fire suppression integration, secondary containment, and automated access logging under EPA manifest regulations.
- Inventory Control:Reagent and consumable tracking systems emphasize real-time depletion monitoring and automated reorder triggers.
- Data Management:Storage platforms with embedded edge computing handle local data processing and cybersecurity hardening for connected laboratory infrastructure.
Implementation density clusters in Sample Management; Chemical Storage is expanding most quickly as OSHA enforcement intensifies and EPA waste regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmaceutical research zones in Massachusetts and North Carolina concentrate automated biobank deployments, while German chemical clusters and Chinese precision medicine parks drive parallel infrastructure buildouts across three continents.
United States
FDA 21 CFR Part 11 compliance deadlines and biologics cold-chain expansion dominate procurement decisions. The Research Triangle Park in North Carolina hosts intensive GLP-GMP facility upgrades for clinical trial material storage. Boston's Kendall Square biotech corridor anchors cryogenic automation deployments for cell therapy developers.
Germany
Precision medicine investments and pharmaceutical quality control modernization accelerate capital deployment. The EU AI Act's risk classification framework imposes dual compliance obligations on automated decision systems. Baden-Württemberg's pharmaceutical manufacturing belt concentrates LiCONiC AG installations for ultra-low temperature applications.
China
NMPA regulatory harmonization and domestic biologics manufacturing scale-up drive facility automation. The country's dual carbon goals incentivize energy-efficient vertical storage architectures. Shanghai's Zhangjiang Hi-Tech Park hosts the densest concentration of automated sample management installations for gene therapy research.
Switzerland
Swissmedic's stringent chain-of-custody requirements elevate audit-trail specifications for clinical material storage. Basel's pharmaceutical research corridor anchors high-margin deployments serving multinational drug development pipelines. The country's precision manufacturing heritage supports mechatronics integration for cryogenic robotic systems.
India
CDSCO's tightening manufacturing standards for generic drug production create demand for validated automated storage. The country's pharmaceutical quality control sector remains underpenetrated relative to production volume. Hyderabad's Genome Valley and Ahmedabad's formulation belt concentrate initial automation deployments.
Automated Storage and Retrieval Systems in Laboratories Market Competitive Environment
United States producers anchor the diversified conglomerate tier; Swiss and German specialists hold the precision-engineering segment. The market structure bifurcates between integrated life science platforms and dedicated automation fabricators. Three archetypes dominate: full-spectrum laboratory infrastructure suppliers, cryogenic storage specialists, and robotics-focused automation engineers. Competitive moves concentrate on strategic partnerships with LIMS vendors and geographic expansion into underpenetrated Asian pharmaceutical quality control markets.
Among diversified life science conglomerates, Thermo Fisher Scientific and Danaher Corp exemplify the integrated platform archetype, combining storage hardware with informatics workflows. LiCONiC AG anchors the specialized cryogenic tier, occupying a position defined by ultra-low temperature engineering depth. These three entities represent distinct competitive vectors: scale-driven portfolio breadth, precision-focused thermal engineering, and vertically integrated service capabilities.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corp |
| Roche Holding AG |
| Honeywell International |
| Siemens Healthineers |
| LiCONiC AG |
| Azenta |
| SPT Labtech Ltd |
| MICRONIC |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up automation specialists have consolidated component sourcing across precision linear motion and cryogenic sensor suppliers, compressing procurement leverage for mid-tier laboratories while concentrating pricing power among integrated platform vendors serving FDA-validated pharmaceutical facilities.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent deployments from scheduled installations, with pharmaceutical laboratories paying premiums for validated platforms delivering within compressed FDA compliance windows while academic biobanks capture standard-tier economics through extended procurement cycles. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification burdens, cryogenic temperature specifications, and after-sales service bundling. Cost compression in standard-tier vertical lift modules is intensifying because Japanese and German component suppliers command fixed pricing on precision electromechanics. Clinical diagnostics laboratories exhibit highest price sensitivity due to capital efficiency mandates, whereas cell therapy developers demonstrate lowest sensitivity given irreplaceable specimen value.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical demand while specialized distributors serve mid-tier research institutions requiring fragmented validation services. Manufacturing concentrates in Germany, Switzerland, and the United States for precision mechatronics, with cryogenic-rated sensors and linear motion systems drawing from Japanese component specialists. Supply chain risk centers on single-source vulnerability for minus 150 degrees Celsius-rated robotic manipulators, where qualified vendors number fewer than five globally. Distribution runs through certified system integrators who bundle hardware with IQ-OQ-PQ documentation for FDA-regulated end users.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over predictive maintenance algorithms and LIMS connectivity layers determines margin capture, with upstream software capabilities now commanding valuation premiums over commoditized electromechanical hardware.
For Market Incumbents: Cement dominance in cryogenic automation by acquiring specialized informatics vendors who own biobank data architectures, while expanding captive service capabilities to capture recurring revenue from predictive maintenance subscriptions. Thermo Fisher Scientific's integrated platform model demonstrates how hardware-software bundling displaces pure-play automation vendors in North American research hospital procurement. For New Entrants and Emerging Players: CDSCO's tightening manufacturing standards for generic drug production in India opens a window for validated automated storage platforms priced below European and North American incumbent offerings. Target domestic pharmaceutical quality control facilities in Hyderabad and Ahmedabad with modular vertical lift configurations that retrofit into existing freezer farms without structural modification. For Investors and Strategic Acquirers: FDA warning letters citing 21 CFR Part 11 violations in manual inventory systems are the leading indicator that replacement demand acceleration is imminent across United States clinical laboratories. Position for platform consolidation by identifying mid-cap automation specialists with pre-validated algorithmic transparency tools that satisfy EU AI Act risk classification requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Algorithm Development | Machine learning capabilities protect irreplaceable longitudinal specimen collections in pharmaceutical biobanks. |
| LIMS Integration Partnership | Seamless data exchange with laboratory information management systems accelerates FDA 21 CFR Part 11 compliance. |
| Cryogenic Robotics Engineering Acquisition | Ultra-low temperature manipulation expertise anchors positioning in cell therapy and gene editing storage. |
| Validation Service Unbundling | Separating hardware from IQ-OQ-PQ documentation captures procurement flexibility in academic medical centers. |
| Indian Pharmaceutical QC Market Entry | CDSCO manufacturing standards create first-mover advantage in underpenetrated generic drug automation. |
Study Parameters
Document review covered FDA 21 CFR Part 11 guidance documents, EU AI Act implementation texts, and EPA hazardous waste manifest regulations, complemented by interviews with laboratory automation procurement managers, biobank operations directors, GMP facility validation specialists, and predictive maintenance software engineers. Secondary sources included SEC filings from diversified life science conglomerates, customs data on precision electromechanics trade flows, and hospital procurement database extracts. Bottom-up installation tracking across pharmaceutical, clinical, and research laboratory segments was triangulated against top-down capital expenditure forecasts from precision medicine funding announcements.
Cross-referencing historical replacement cycles with expert panel input on FDA compliance deadline impacts shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type configuration, end-user regulatory environment, technology integration layer, and application-specific temperature range requirements. CAGRs were derived through regression analysis of capital deployment patterns against biologics cold-chain expansion trajectories, with cryogenic storage infrastructure buildouts and AI-enabled service layer adoption serving as primary forecast inputs.
Caveats apply where NMPA regulatory harmonization delays, EU AI Act enforcement variability, or specialized mechatronics engineering talent scarcity could materially shift the outlook for deployment timelines and vendor qualification success rates. Periodic stress-testing of base assumptions against actual FDA inspection citation patterns and pharmaceutical capital allocation announcements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Data Backup and Recovery Market
Storage Solutions
Mexico Data Center Storage Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Asia Pacific Automated Storage and Retrieval System Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Global in Memory Data Grid Market
Storage Solutions
Denmark Data Center Storage Market
Storage Solutions
Global Ethernet Storage Fabric Market
Storage Solutions
Public Cloud Storage Services Market
Storage Solutions
Hong Kong Data Center Storage Market
Storage Solutions
Cloud Block Storage Market
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Cloud Storage Gateways Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
United Arab Emirates Data Center Storage Market