
 Cloud Block Storage Market | 2026-2036
Cloud Block Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Block Storage Market Analysis
Platform licensing revenue from managed storage services is reshaping margin pools away from raw capacity sales. Amazon Web Services leverages its hyperscale infrastructure to dominate enterprise block storage provisioning. Microsoft Azure anchors hybrid cloud workloads through tight integration with on-premises Windows Server environments. Google Cloud specializes in performance-optimized NVMe block volumes for analytics and AI training pipelines.
Cloud block storage delivers persistent, low-latency data volumes to virtual machines and containers over networked protocols, typically guaranteeing sub-10 millisecond response times for random read operations. Its primary commercial purpose centers on supporting transactional databases, virtualized workloads, and stateful container applications requiring durable, attachable storage independent of compute lifecycle. Public cloud deployment captures the dominant revenue share as enterprises exit owned data centers, while hybrid cloud architectures represent the fastest-expanding segment as regulated industries mandate on-premises data residency for sensitive workloads. Disaster recovery services command premium pricing due to stringent recovery-point objectives in financial and healthcare sectors.
ISO 27001 certification and SOC 2 Type II attestation shape vendor qualification criteria for enterprise procurement, while GDPR and the EU AI Act impose data localization and audit-trail requirements that favor regional cloud zones. The Federal Risk and Authorization Management Program in the United States restricts federal agency purchases to pre-authorized cloud providers. Stakeholders must evaluate sovereignty-aligned storage zones against latency requirements as data residency regulations proliferate across jurisdictions.
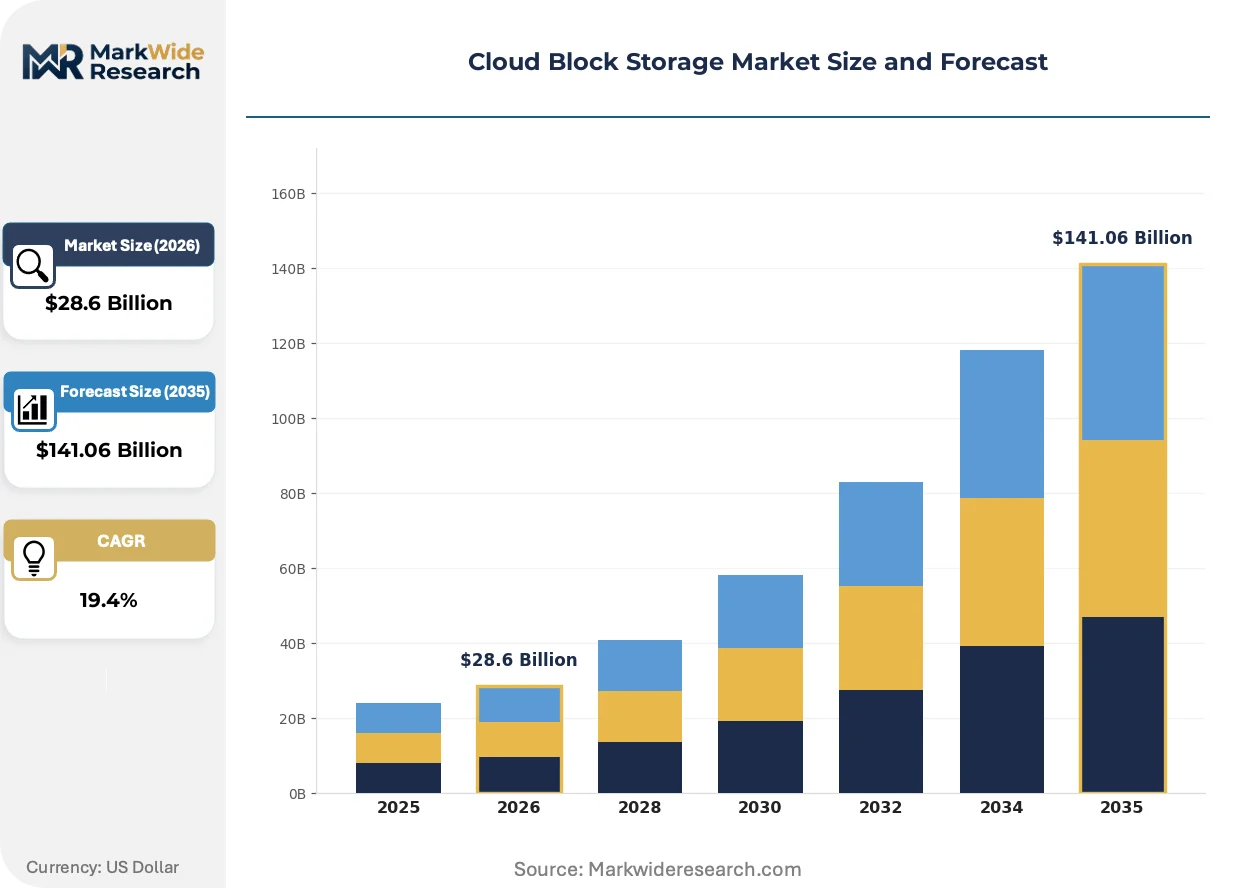
Market Dynamics
Enterprise migration from owned data centers to hyperscale infrastructure is compressing traditional storage vendor margins while elevating platform-native block storage services to primary procurement targets.
Growth Catalysts
- EU AI Act data sovereignty mandates:Financial services firms across Germany and France must maintain audit-ready data residency, accelerating compliant cloud zone deployment.
- Real-time transaction processing:Payment networks and trading platforms require sub-10 millisecond persistent storage, pulling NVMe block volumes into core architecture.
- Container state persistence:Kubernetes workloads need durable attachable storage independent of pod lifecycle, expanding addressable volume for cloud-native block services.
Market Restraints
- Hyperscale supply concentration:Three US-based cloud providers control the majority of enterprise block storage provisioning, creating vendor lock-in risk and limited negotiation leverage.
- Federal authorization barriers:FedRAMP pre-authorization requirements restrict US federal agency purchases to a narrow provider list, segmenting the public sector addressable market.
- Legacy SAN replacement friction:Enterprises with substantial on-premises Fibre Channel investments face technical debt and staff retraining costs during cloud migration.
Strategic Opportunities
- Singapore financial hub expansion:Southeast Asian banking regulators are clarifying cross-border data flow rules, opening compliant cloud block storage deployment for regional transaction processing.
- Healthcare disaster recovery unbundling:HIPAA-covered entities are separating backup infrastructure from primary storage contracts, creating specialized DR-as-a-service opportunities with premium recovery-point guarantees.
- AI training pipeline convergence:The intersection of high-throughput NVMe block storage with GPU cluster orchestration is creating new performance-tier pricing for machine learning workloads.
Industry Challenges
- ISO 27001 certification timeline:Vendor attestation processes stretch 12-18 months, delaying enterprise procurement cycles and freezing competitive entry for mid-tier providers.
- Multi-cloud orchestration complexity:Storage administrators lack standardized tooling for consistent policy enforcement across AWS, Azure, and Google Cloud block services simultaneously.
- GDPR audit trail engineering:Implementing immutable logging for data access patterns requires architectural redesign of existing block volume metadata systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Block Storage Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $141.06 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Backup, Disaster Recovery, Archiving, File Storage End User: SMBs, Enterprises, Government, Educational Institutions Storage Capacity: 1TB-10TB, 11TB-50TB, 51TB-100TB, 100TB+ |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, IBM, Oracle, Dell Technologies, Hewlett Packard Enterprise, NetApp, Huawei Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Block Storage Market Emerging Trajectories
Storage-class memory integration and automated tiering algorithms are redrawing performance-per-dollar boundaries, while regulatory data localization hardens into architectural requirements rather than compliance checkboxes.
Computational storage drives with embedded processing capabilities are collapsing the traditional separation between storage and compute layers. Database vendors and analytics platforms are deploying these devices to push predicate filtering and aggregation closer to physical media. This compression of the data path is collapsing latency budgets for real-time workloads and forcing hyperscale providers to redesign their block volume service tiers.
The EU AI Act's training data documentation requirements are mandating immutable provenance chains for machine learning datasets. Cloud providers operating in European zones must implement cryptographic verification of data lineage from ingestion through model training. German automotive and French pharmaceutical manufacturers are prioritizing block storage contracts with built-in audit immutability, reshaping vendor qualification criteria.
Consumption-based billing with granular per-IOP metering is displacing provisioned-capacity contracts in enterprise procurement. Buyers in the US financial sector are negotiating rate cards tied to actual read-write operations rather than allocated terabytes. This behavioral shift rewards workload optimization and compresses margins for providers unable to offer fine-grained usage visibility.
Cloud Block Storage Market Segmentation
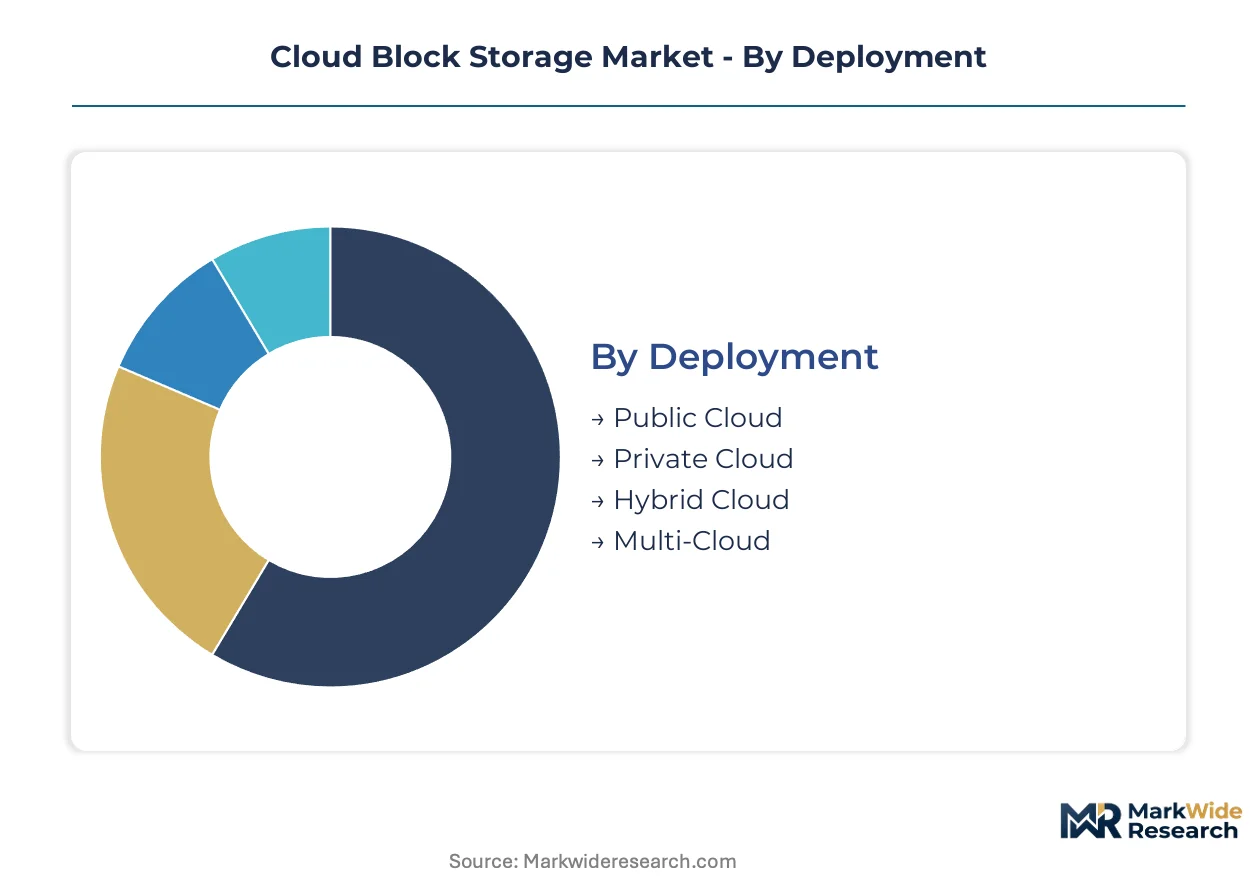
Cloud block storage segmentation reveals distinct procurement patterns across deployment architectures, workload types, and organizational scale. Each dimension carries specific compliance, performance, and cost implications that shape vendor selection and contract structuring.
Deployment:
Deployment mode determines data residency capabilities, latency boundaries, and operational control levels for storage administrators.
- Public Cloud:Hyperscale providers operate shared infrastructure with standardized SLAs and pay-as-you-go metering. Financial services firms in Singapore and Germany are expanding public cloud block volumes for non-sensitive transaction processing, driven by EU AI Act documentation requirements for training data provenance.
- Hybrid Cloud:Split architectures place hot transactional data on-premises while bursting analytics workloads to cloud NVMe tiers. HIPAA-covered entities and German automotive manufacturers prioritize hybrid deployments to satisfy GDPR localization mandates without sacrificing elastic compute access.
- Private Cloud:Dedicated infrastructure serves classified workloads and sovereign cloud zones. US federal agencies under FedRAMP authorization requirements default to private cloud block storage for controlled unclassified information.
- Multi-Cloud:Orchestrated distribution across AWS, Azure, and Google Cloud reduces vendor lock-in risk. Enterprises with containerized stateful applications deploy multi-cloud block services to maintain workload portability.
The dominant share belongs to Public Cloud, while Hybrid Cloud is gaining share fastest as regulated industries architect compliant data residency.
Service Type:
Service tier selection maps directly to recovery objectives, access frequency, and regulatory retention schedules.
- Backup:Scheduled snapshot replication with point-in-time recovery capabilities. US healthcare systems under HIPAA business associate agreements negotiate backup contracts with 15-minute recovery point objectives.
- Disaster Recovery:Geographically separated synchronous replication for mission-critical databases. French banking regulators mandate DR site separation exceeding 100 kilometers for payment system resilience.
- Archiving:Immutable cold storage for litigation hold and long-term audit compliance. German pharmaceutical manufacturers archive clinical trial data under EMA Good Clinical Practice guidelines.
- File Storage:POSIX-compliant shared access for legacy application migration. Educational institutions in the United States deploy file storage gateways during on-premises NAS retirement.
Disaster Recovery commands premium pricing, while Archiving expands most quickly under tightening data retention regulations.
End User:
Organizational scale dictates procurement sophistication, compliance exposure, and contract negotiation leverage.
- Enterprises:Global 2000 organizations with dedicated storage engineering teams and multi-year enterprise agreements. These buyers demand ISO 27001 certification, custom encryption key management, and API access for infrastructure-as-code provisioning.
- SMBs:Mid-market companies purchasing through managed service providers or direct self-service portals. Singapore fintech startups represent concentrated SMB demand for compliant block storage with minimal administrative overhead.
- Government:Federal, state, and municipal agencies with sovereign data requirements. US federal purchases are restricted to FedRAMP-authorized providers, segmenting this addressable market.
- Educational Institutions:Universities and research consortia with grant-funded storage needs. European academic clouds under GÉANT federation prioritize GDPR-compliant block services for cross-border research collaboration.
Enterprises retain the dominant procurement volume, though Government is climbing the fastest as sovereign cloud programs accelerate.
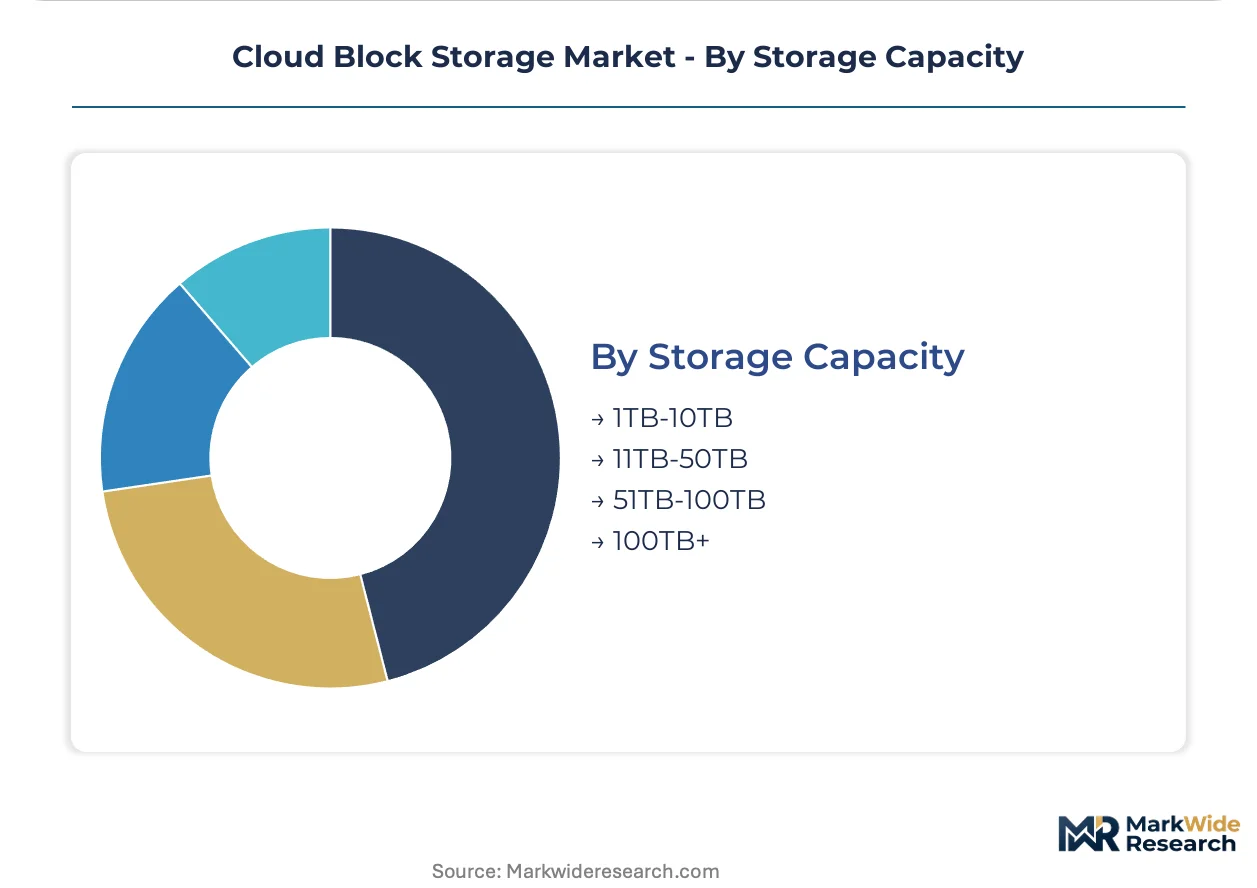
Storage Capacity:
Capacity tier selection reflects data lifecycle stage, performance requirements, and cost optimization discipline.
- 100TB+:Hyperscale database deployments and AI training data lakes. German automotive manufacturers provisioning autonomous vehicle simulation clusters drive demand for petabyte-scale NVMe block volumes with sub-millisecond latency.
- 51TB-100TB:Enterprise data warehouse and analytics platform workloads. US financial services firms in this tier negotiate consumption-based contracts tied to actual IOPS rather than provisioned capacity.
- 11TB-50TB:Departmental applications and development environments. French pharmaceutical mid-caps select this range for clinical data management systems under ANSM inspection readiness requirements.
- 1TB-10TB:Small production databases and container persistent volumes. Singapore digital banking licenses and US healthcare startups populate this entry tier during initial cloud migration.
The 100TB+ segment leads absolute revenue, while 1TB-10TB shows the steepest expansion trajectory as cloud-native application deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Singapore deploy cloud block storage predominantly for real-time transaction processing with strict data residency, while the United States emphasizes hybrid architectures bridging on-premises SAN investments with elastic cloud capacity.
United States
Financial services firms in New York and Chicago drive NVMe block volume procurement for sub-millisecond trading execution. FedRAMP authorization requirements restrict federal agency purchases to pre-authorized providers, segmenting the public sector addressable market. Silicon Valley hyperscale campuses anchor enterprise migration from owned data centers to platform-native storage services.
Germany
Automotive manufacturers in Stuttgart and Munich provision petabyte-scale block storage for autonomous vehicle simulation clusters. The EU AI Act mandates immutable training data provenance chains, forcing cloud providers to implement cryptographic verification. Frankfurt's financial district concentrates compliant cloud zone deployment for cross-border payment processing.
Singapore
Southeast Asian banking regulators are clarifying data flow rules, opening compliant block storage for regional transaction hubs. The Monetary Authority of Singapore's digital banking licenses populate entry-tier cloud volumes for fintech startups. Marina Bay data centers serve as the primary infrastructure node for ASEAN financial institutions.
France
Pharmaceutical manufacturers under ANSM inspection readiness requirements select mid-range block tiers for clinical data management. French banking regulators mandate 100-kilometer DR site separation for payment system resilience. Paris-based cloud zones prioritize GDPR-compliant architectures with built-in audit immutability.
Cloud Block Storage Market Vendor Landscape
Capability concentration sits with hyperscale infrastructure operators; scale advantage sits with platform-integrated storage services. Three US-based cloud providers control the majority of enterprise block storage provisioning, creating tiered vendor access rather than fragmented competition. Strategic archetypes include hyperscale platform operators, legacy infrastructure vendors pivoting to cloud-adjacent services, and regional sovereign cloud specialists. Dominant competitive moves encompass M&A for container storage orchestration capabilities and strategic partnerships for multi-cloud data mobility.
Within the hyperscale tier, Amazon Web Services, Microsoft Azure, and Google Cloud occupy positions defined by infrastructure breadth rather than specialization depth. Amazon Web Services exemplifies the platform-native archetype through enterprise agreement dominance. Microsoft Azure anchors hybrid workload positioning through Windows Server integration. Google Cloud represents the performance-optimized vector with NVMe block volume specialization for analytics pipelines.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| IBM |
| Oracle |
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| Huawei Cloud |
| Others |
Supply Flow & Price Mechanics
Hyperscale supply concentration across three US-based cloud providers creates asymmetric pricing power that compresses margins for mid-tier competitors while elevating platform-native services to premium tiers. This structural dependency simultaneously shapes contract structures and forces procurement teams to accept limited negotiation leverage in enterprise agreements.
Pricing Analysis
Long-term enterprise agreements dominate cloud block storage procurement, with consumption-based billing displacing provisioned-capacity contracts across US financial services. Price differentiation hinges on ISO 27001 certification tier and NVMe performance grade, with sub-millisecond latency volumes commanding substantial premiums over standard SSD tiers. Pricing pressure stems from granular per-IOP metering that rewards workload optimization and erodes margins for providers lacking fine-grained usage visibility. SMBs purchasing through self-service portals exhibit highest price sensitivity, while Global 2000 enterprises with dedicated storage engineering teams leverage multi-year agreements for volume discounts.
Supply Chain Analysis
Extended payment terms from hyperscale operators to NAND flash and controller semiconductor suppliers have reshaped working capital requirements across the storage hardware tier. Supply concentrates in Taiwan, South Korea, and China for solid-state drive components, with specialized foundries in these jurisdictions producing custom ASICs for computational storage devices. Raw material dependencies span silicon wafers, rare earth elements for drive magnets, and high-purity substrates for 3D NAND fabrication. Single-source vulnerability in advanced node semiconductor manufacturing creates chokepoint risk for performance-optimized NVMe volumes. Distribution runs through direct hyperscale provisioning channels and managed service provider intermediaries serving regulated industries with compliance requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of multi-cloud orchestration expertise and FedRAMP authorization capability has concentrated competitive advantage among established hyperscale operators, leaving limited entry paths for specialists lacking platform breadth or sovereign cloud credentials.
For Market Incumbents: Insulate enterprise relationships by embedding storage services deeper into workload orchestration layers, particularly Kubernetes persistent volume provisioning where switching costs compound. Pursue backward integration into computational storage hardware to collapse latency budgets for real-time transaction processing. Defensive certification investment in EU AI Act-compliant audit immutability will preempt regulatory displacement by regional sovereign cloud specialists. For New Entrants and Emerging Players: Southeast Asian financial hubs with clarifying cross-border data flow rules represent the most penetrable geography for compliant cloud block storage deployment. Target healthcare disaster recovery unbundling as the fastest-expanding service type, where HIPAA-covered entities separate backup infrastructure from primary storage contracts. A channel partnership strategy with managed service providers serving regulated mid-market verticals bypasses direct hyperscale competition while capturing premium recovery-point guarantees. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors container storage orchestration specialists with multi-cloud abstraction capabilities. Long-term viability across the projection horizon rests on differentiation through sovereign cloud zone deployment or AI training pipeline performance optimization rather than raw capacity provisioning. Acquisition target archetypes include regional compliance-focused providers with established GDPR audit trail engineering and established FedRAMP authorization pathways. The signal to watch is hyperscale capex allocation toward NVMe-over-Fabrics infrastructure, which would accelerate margin compression for legacy connectivity-dependent entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Tight Windows Server anchoring captures hybrid cloud workloads from German automotive manufacturers. |
| Strategic Partnership | Multi-cloud data mobility alliances reduce vendor lock-in friction for containerized stateful applications. |
| Acquisition of Specialist Firm | Container storage orchestration capabilities deepen Kubernetes persistent volume provisioning control. |
| Geographic Expansion | Frankfurt and Singapore sovereign zones satisfy EU AI Act and MAS digital banking compliance mandates. |
| Product Launch | Computational storage drives with embedded processing collapse latency for French pharmaceutical analytics. |
Methodological Framework
Operator-level perspectives from cloud infrastructure architects, storage engineering directors, and regulated industry procurement officers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation across hyperscaler capex disclosures, SEC filings from legacy storage vendors, and EU regulatory documentation from EMA and GDPR enforcement actions. Bottom-up demand modeling triangulated against top-down infrastructure spend estimates from enterprise IT budget surveys.
Scenario-bracketing framed the analytical approach across the projection horizon, with deployment architecture, service tier, and organizational scale as core segmentation dimensions. CAGRs derived from elasticity-adjusted adoption curves incorporating FedRAMP authorization timelines and ISO 27001 certification cycle impacts. Industry-specific forecast inputs included GPU cluster orchestration growth for AI training pipeline storage and cross-border payment processing volume expansion in ASEAN financial hubs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by sovereign cloud specialists or accelerated computational storage adoption by database vendors would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Europe Data Center Storage Market
Storage Solutions
Global Storage As a Service Market
Storage Solutions
Public Cloud Storage Services Market
Storage Solutions
Global Server Storage Area Network Market
Storage Solutions
Consumer Cloud Storage Services Market
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Europe in-Memory Database Market
Storage Solutions
Cloud Native Storage Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Software Defined Storage Market
Storage Solutions
Automated Storage and Retrieval Systems in Laboratories Market
Storage Solutions
Network Attached Storage (NAS) Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Stand Alone Cloud Storage Market
Storage Solutions
Brazil Data Center Storage Market