
 Austria Data Center Storage Market | 2026-2036
Austria Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Austria Data Center Storage Market Insights
Hyperscale cloud operators are redrawing procurement patterns in Austria's data center storage landscape, pulling capacity away from traditional enterprise IT capital budgets toward utility-scale consumption models. Dell Technologies leverages its integrated server-storage portfolio to anchor large enterprise refresh cycles across Austrian banking and insurance sectors. Hewlett Packard Enterprise competes through composable infrastructure architectures that disaggregate storage resources from compute silos. Interxion Austria sustains its position by controlling premium colocation space in Vienna, where cross-connect density creates captive demand for adjacent storage services.
Austria data center storage encompasses disk arrays, solid-state systems, and software-defined platforms engineered to retain, protect, and serve structured and unstructured information workloads across enterprise and service provider facilities. These systems employ NVMe over Fabrics protocols to slash latency below 100 microseconds while scaling petabyte namespaces across distributed architectures. Object storage deployments are accelerating fastest among Austrian media and research institutions managing exponential unstructured data growth, while SAN configurations retain the largest installed base in transactional finance workloads. Hybrid deployment models capture expanding margin pools as organizations balance sovereign data requirements against cloud elasticity, with colocation providers bundling managed storage layers to extend customer lifetime value.
Austria's Federal Ministry for Climate Action enforces efficiency benchmarks under the EU Energy Efficiency Directive, compelling operators to document power usage effectiveness ratios and prioritize SSD and NVMe technologies over mechanical disk tiers. BIS alignment with ISO 27001 and the EU AI Act's data governance provisions shapes product certification pathways and cross-border data handling protocols for storage vendors. Stakeholders must monitor how forthcoming EU Critical Entities Resilience Act implementation timelines reshape redundancy and geographic distribution requirements for Austrian facility operators.
Market Dynamics
Hyperscale cloud operators are consolidating procurement authority in Austria's data center storage sector, redirecting enterprise capital expenditure toward utility-scale consumption frameworks anchored in Vienna and Linz.
Growth Catalysts
- EU Green Deal efficiency mandates:Austria's Federal Ministry for Climate Action enforces power usage effectiveness documentation, accelerating flash-based storage deployments over mechanical disk infrastructure.
- Hyperscale facility clustering:Cloud service providers are expanding storage procurement across Vienna's commercial corridor and Linz's industrial zone, creating concentrated demand pools for high-density systems.
- NVMe over Fabrics protocol adoption:Austrian banking and insurance sectors are deploying sub-100 microsecond latency architectures to support real-time transactional workloads.
Market Restraints
- Input cost volatility in NAND flash:Memory chip pricing fluctuations compress margin predictability for storage system integrators serving Austrian enterprise customers.
- Supply concentration in Asian component fabrication:Dependency on concentrated semiconductor manufacturing regions creates vulnerability in storage hardware lead times.
- Technical limitation in mechanical disk density:Areal density plateaus in HDD technology restrict cost-effective cold storage scaling for archival workloads.
Strategic Opportunities
- Emerging sovereign cloud requirements:EU AI Act data governance provisions create demand for Austria-based storage infrastructure that maintains jurisdictional control over sensitive datasets.
- Liquid-cooled storage convergence:Integration of direct-to-chip cooling with high-density flash arrays enables operators to exceed 50kW per rack without thermal throttling.
- Object storage for research institutions:Austrian media and scientific computing centers managing exponential unstructured data growth represent underpenetrated demand for scalable namespace architectures.
Industry Challenges
- Specialized engineering skill scarcity:Shortage of technicians certified in NVMe fabric administration and software-defined storage orchestration constrains deployment velocity.
- Legacy SAN integration friction:Financial services institutions face complex migration pathways from Fibre Channel architectures to converged Ethernet-based storage networks.
- ISO 27001 certification timeline compression:Accelerated audit cycles for colocation providers strain documentation and control implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria Data Center Storage Market |
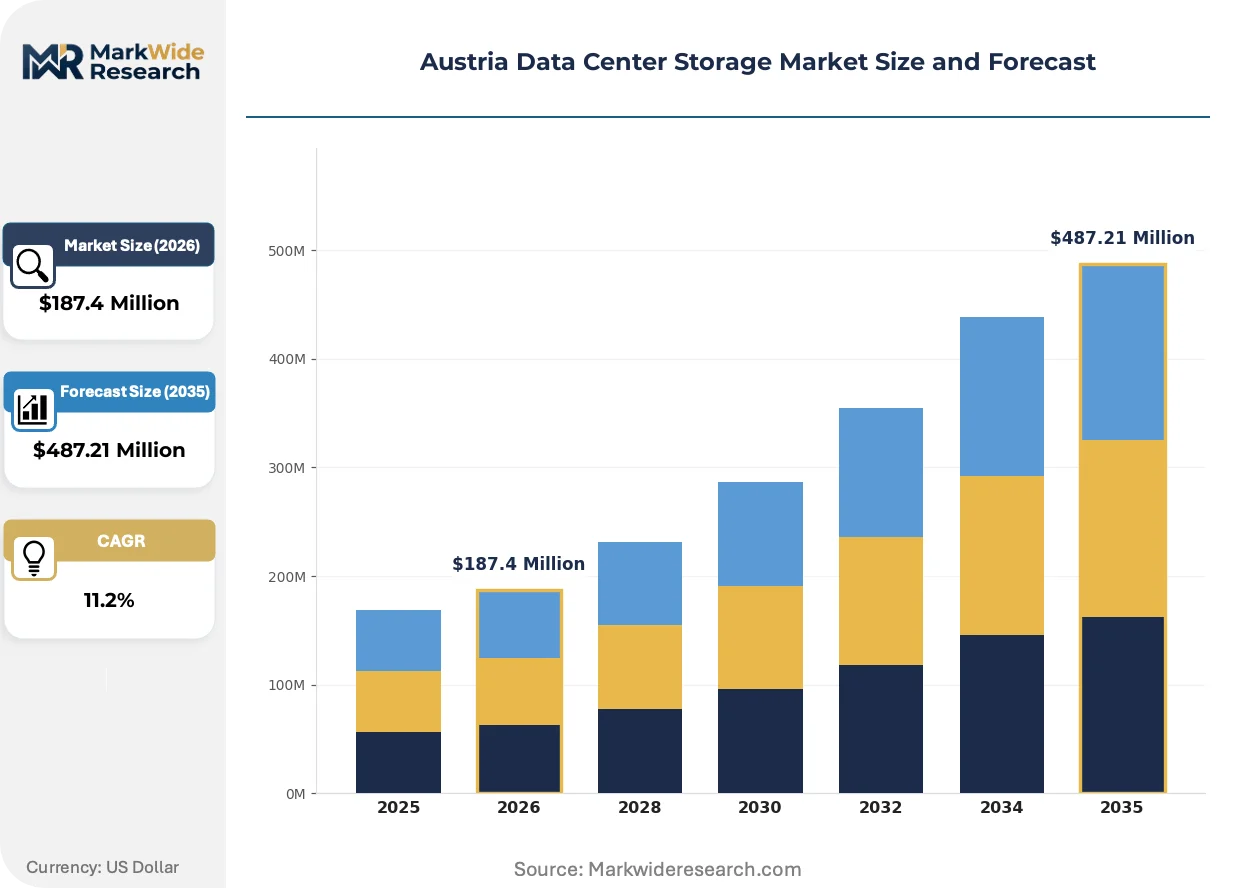
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $487.21 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: SAN, NAS, DAS, Object Storage Deployment Model: On-Premises, Cloud, Hybrid, Colocation End User: Enterprises, Managed Service Providers, Government, Telecommunications Technology: SAS, SATA, SSD, NVMe |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, NetApp, IBM, Interxion Austria, Digital Realty Austria, NTT Austria, A1 Telekom Austria, Microsoft Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria Data Center Storage Market Trends and Innovations
Software-defined storage architectures are decomposing traditional hardware-centric procurement patterns across Austrian data center operations. Three interconnected developments are compressing technology refresh cycles and reshaping vendor competitive positioning.
Composable infrastructure is decomposing fixed server-storage relationships into disaggregated resource pools that Austrian enterprises allocate dynamically across workloads. Large financial institutions in Vienna are piloting these architectures to eliminate stranded capacity in traditional three-tier deployments. The structural consequence is collapsing differentiation between server and storage vendor categories as resource federation software governs procurement decisions.
Austria's alignment with the EU AI Act establishes mandatory data governance protocols for storage systems processing training datasets and model outputs. The regulation compels operators to implement lineage tracking and residency controls that favor sovereign cloud deployments over hyperscale public alternatives. Colocation providers in Vienna are responding by certifying managed storage layers against these provisions to capture compliance-sensitive workloads.
Utility-based consumption models are displacing capital-intensive ownership structures among Austrian mid-market enterprises. Managed service providers are bundling storage-as-a-service offerings that transfer refresh risk and capacity planning to vendor balance sheets. This pattern concentrates most visibly in Salzburg and Graz, where regional enterprises lack dedicated infrastructure teams but require enterprise-grade data protection.
Austria Data Center Storage Market Segmentation
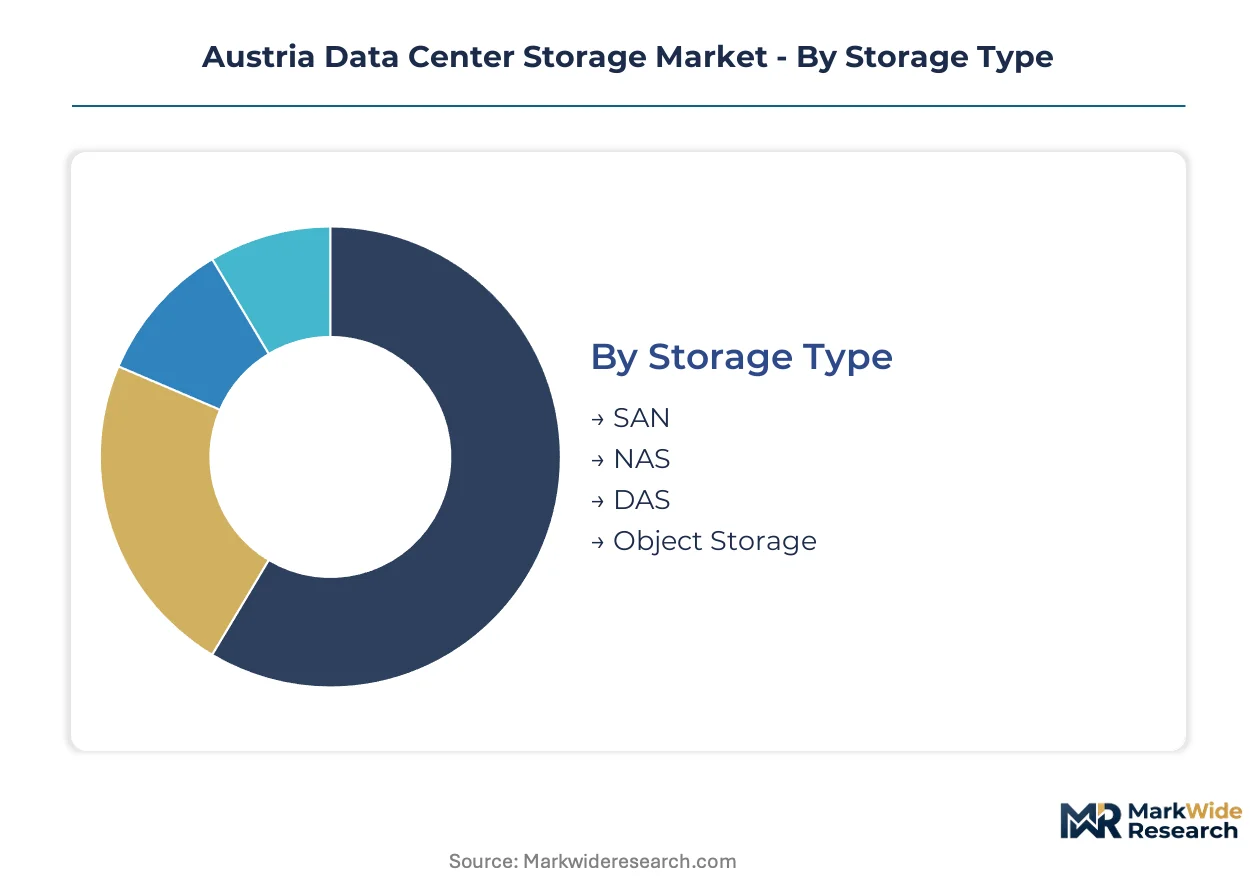
Segmentation in Austria's data center storage market reveals distinct procurement pathways that align storage architectures with workload governance requirements. Channel dynamics vary sharply across deployment models, with hyperscale cloud operators bypassing traditional value-added distributors while enterprise customers retain multi-tier procurement relationships.
Storage Type:
Channel flow diverges by architecture complexity, with SAN and NAS systems moving through systems integrators while object storage increasingly routes through direct hyperscale procurement.
- SAN:Fibre Channel architectures with dedicated storage networks isolate block-level traffic for transactional workloads. Austrian banking clusters in Vienna deploy these systems for core banking platforms where latency consistency governs service level agreements.
- Object Storage:Flat namespace architectures distribute unstructured data across commodity nodes with erasure coding protection. Research institutions in Linz and Graz are scaling these systems for genomic and climate simulation datasets where petabyte expansion is routine.
- NAS:File-level access protocols serve departmental shares and content repositories through standard Ethernet connectivity.
- DAS:Direct-attached configurations persist in edge compute nodes and legacy application silos requiring dedicated spindle isolation.
SAN dominates installed base. Object storage is where expansion concentrates.
Deployment Model:
Cost tier stratification shapes vendor engagement models, with on-premises deployments commanding premium support contracts and cloud consumption shifting margin to operational expenditure frameworks.
- Hybrid:Workload portability across on-premises and cloud infrastructure demands unified data services with consistent APIs. Austrian manufacturers with fluctuating compute requirements favor this model for seasonal demand spikes without permanent capacity overbuild.
- Colocation:Third-party facility space with customer-managed or provider-managed storage layers bridges sovereignty requirements and capital efficiency. Vienna's Interxion and Linz's industrial parks anchor this segment through cross-connect density and power availability.
- On-Premises:Fully owned infrastructure retains dominance in defense, critical infrastructure, and financial services with strict data residency mandates.
- Cloud:Public hyperscale storage services capture development environments and analytics sandboxes with elastic scaling requirements.
On-premises retains the largest revenue pool. Hybrid deployments are climbing the fastest as workload portability becomes standard architecture.
End User:
Customer type determines solution complexity and sales cycle duration, with government procurement extending timelines through certification requirements while telecommunications operators prioritize throughput density.
- Enterprises:Diverse sector requirements span high-frequency trading platforms to batch analytics, with procurement authority consolidating under infrastructure platform teams rather than discrete storage specialists.
- Managed Service Providers:Multi-tenant architectures demand storage systems with robust quality-of-service isolation and chargeback granularity. Salzburg and Graz host expanding MSP clusters serving mid-market enterprises without dedicated infrastructure teams.
- Government:Federal and provincial agencies enforce BIS-aligned security certifications with data residency constraints.
- Telecommunications:5G core network functions and subscriber data management drive low-latency storage requirements at network edge locations.
Enterprises anchor volume commitments. Managed service providers are gaining share fastest through consumption-based service bundling.
Technology:
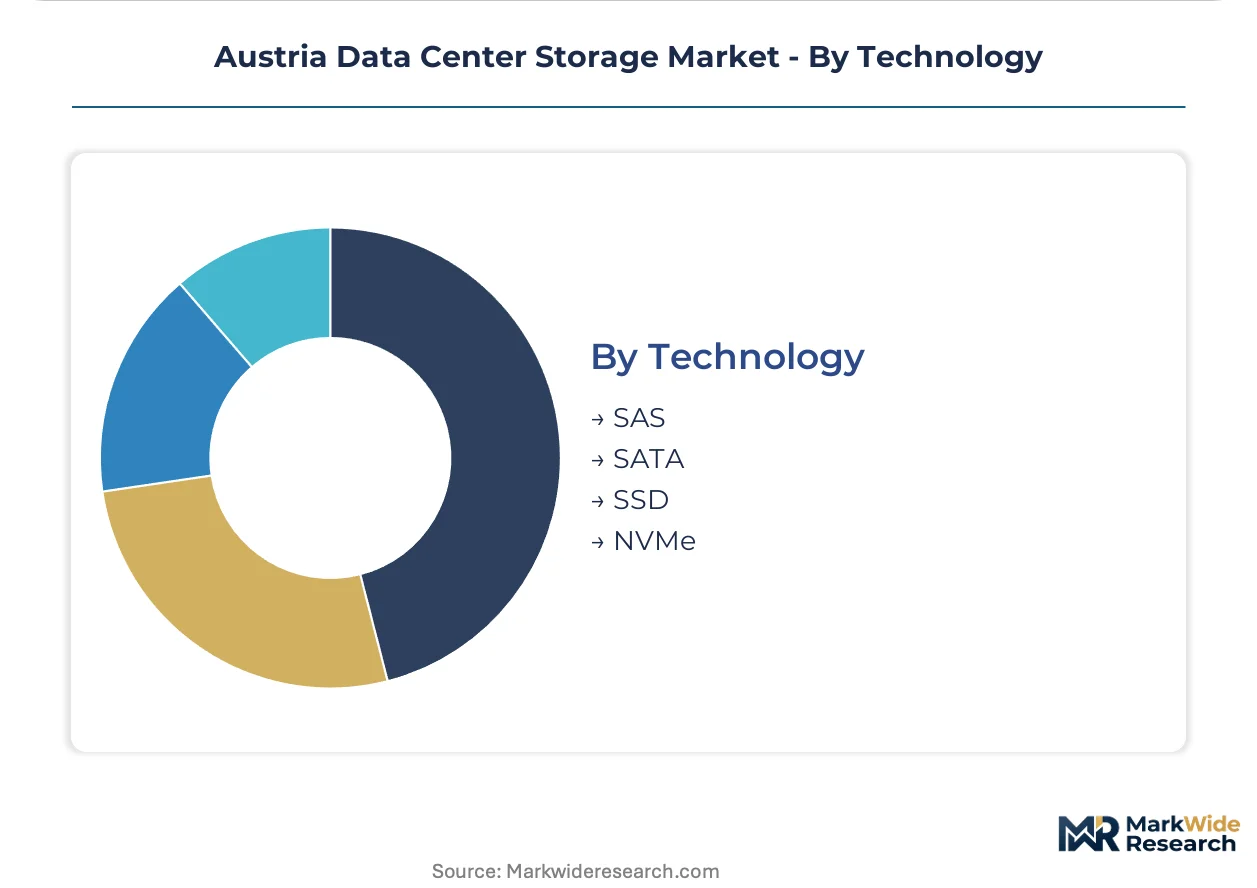
Supply concentration in NAND flash fabrication creates margin pressure dynamics that differentiate technology tiers, with NVMe commanding premium positioning and SATA facing commoditization.
- NVMe:PCIe-attached flash protocols eliminate SCSI translation overhead to deliver sub-100 microsecond latency. Austrian insurance real-time risk engines and securities trading platforms in Vienna's financial district mandate these systems for competitive execution speed.
- SSD:SATA and SAS interface flash drives bridge performance and cost for mainstream workloads with moderate latency tolerance. Enterprise refresh cycles across Lower Austria are standardizing on these systems for primary storage tiers.
- SAS:Serial-attached SCSI persists in legacy array retrofits and environments with established drive sled investments.
- SATA:Cost-optimized rotating media and entry flash serve archival and backup targets where access frequency is minimal.
SSD commands the largest installed capacity. NVMe is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component fabrication for storage systems concentrates in East Asian semiconductor foundries, creating geographic asymmetry between supply origins and European deployment sites. Austrian operators navigate this dependency through strategic inventory positioning and diversified sourcing channels.
Germany
Hyperscale cloud operators are expanding Frankfurt and Munich facilities, pulling storage procurement toward utility-scale frameworks. The Federal Network Agency enforces critical infrastructure resilience standards under the IT Security Act. Bavaria's Munich-Ingolstadt corridor hosts Europe's densest colocation cluster, where Interxion and Digital Realty operate flagship campuses.
Switzerland
Financial services institutions in Zurich and Geneva mandate sub-100 microsecond latency storage for algorithmic trading platforms. FINMA's operational resilience requirements shape data localization and redundancy architectures. The Zurich-West industrial zone anchors cross-border storage deployments serving EU banking subsidiaries.
Netherlands
Amsterdam's AMS-IX internet exchange density creates captive demand for adjacent storage services among content delivery networks. The Dutch Authority for Digital Infrastructure implements NIS2 directive provisions for data center cybersecurity certification. North Holland's Schiphol-Rijk corridor concentrates hyperscale facility investments from Microsoft and Google.
France
Paris-Saclay research institutions are scaling object storage namespaces for genomic and climate simulation datasets. ANSM and CNIL jointly enforce health data hosting certification (HDS) requirements for sensitive storage workloads. The Greater Paris metropolitan area hosts sovereign cloud initiatives competing with hyperscale alternatives for public sector contracts.
Italy
Milan's financial district drives SAN refresh cycles for core banking platforms with strict latency consistency requirements. AGID's Cloud Italia strategy mandates public administration data residency on certified national infrastructure. Lombardy's Cremona-Mantua industrial corridor attracts edge storage deployments for manufacturing IoT analytics.
Austria Data Center Storage Market Competitive Landscape
Concentration sits with integrated infrastructure vendors and hyperscale facility operators who control procurement gateways. The vendor landscape exhibits tiered structure, with full-stack server-storage portfolios anchoring enterprise refresh cycles against disaggregated composable alternatives. Three archetypes dominate: integrated hardware vendors, colocation platform operators, and hyperscale cloud service providers. Competitive moves center on portfolio convergence and vertical capability stacking rather than pure price competition.
Within the integrated infrastructure tier, Dell Technologies and Hewlett Packard Enterprise exemplify full-stack positioning that collapses server and storage procurement decisions. Among facility-based operators, Interxion Austria occupies a position controlling premium Vienna colocation space where cross-connect density creates adjacent storage service demand. NetApp represents the software-defined specialist archetype, anchoring hybrid cloud storage fabric deployments across Austrian banking and research institutions.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| IBM |
| Interxion Austria |
| Digital Realty Austria |
| NTT Austria |
| A1 Telekom Austria |
| Microsoft Corporation |
| Others |
Pricing and Supply Chain Analysis
Inventory buffers extending to 90-120 days among Austrian system integrators signal supply-chain adaptation to NAND flash volatility while compressing pricing power at the distribution tier. This lead-time band reflects strategic positioning against component shortages that reshape procurement economics across Vienna and Linz deployment corridors.
Pricing Analysis
The EU Energy Efficiency Directive dictates the pricing tier structure across Austrian data center storage deployments, separating liquid-cooled NVMe arrays from air-cooled SATA configurations. Pricing stratifies across premium, standard, and economy tiers based on certification grade under BIS alignment and volume scale of hyperscale procurement. Cost compression in mechanical disk tiers is intensifying because areal density plateaus restrict archival scaling economics. Mid-market enterprises without dedicated infrastructure teams exhibit highest price sensitivity, while hyperscale operators anchor long-term offtake agreements that stabilize vendor margins.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for flash memory modules and controller silicon destined for Austrian integration facilities. Component fabrication concentrates in Taiwan, South Korea, and China, with raw material dependencies spanning NAND wafers, DRAM chips, and specialized cooling fluids. Single-source vulnerability in advanced node semiconductor manufacturing creates exposure to geopolitical disruption. Distribution runs through value-added distributors for enterprise SAN deployments while hyperscale operators engage direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Austria's data center storage market sits in early-cycle expansion as EU AI Act data governance provisions accelerate sovereign cloud infrastructure deployment beyond current penetration levels.
For Market Incumbents: Fortify position through backward integration into liquid-cooled system design to capture premium positioning under Federal Ministry for Climate Action efficiency mandates. Deepen channel control in Vienna's colocation corridor where cross-connect density creates captive demand, while investing in ISO 27001 certification acceleration to compress audit timelines against emerging competitors.
For New Entrants and Emerging Players: Anchor in object storage deployments for Linz and Graz research institutions managing genomic and climate simulation datasets, the most penetrable white-space segment. Pursue managed service provider partnerships in Salzburg as the go-to-market angle, bundling consumption-based offerings for mid-market enterprises lacking dedicated infrastructure teams.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-premium play because jurisdictional data sovereignty requirements under EU AI Act provisions structurally favor Austria-based infrastructure over hyperscale alternatives. Acquisition targets should demonstrate software-defined storage orchestration capabilities and established BIS certification pathways. Monitor hyperscale facility announcement velocity in Vienna's commercial corridor as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid-Cooled Storage Integration | Direct-to-chip cooling enables rack densities exceeding 50kW under EU Green Deal mandates. |
| Software-Defined Storage Platform Launch | Composable architectures disaggregate resources for dynamic allocation across Austrian financial workloads. |
| Sovereign Cloud Certification Program | BIS alignment with EU AI Act provisions captures compliance-sensitive public sector contracts. |
| Strategic Partnership with Colocation Operators | Cross-connect density at Interxion Vienna creates adjacent managed storage service demand. |
| Acquisition of NVMe Fabric Specialist | Sub-100 microsecond latency expertise addresses banking and insurance real-time transactional requirements. |
Research Methodology
Cross-validation between hyperscaler capex disclosures and colocation provider facility announcements anchors the qualitative findings on procurement pattern shifts. Primary interviews with data center infrastructure directors, storage system procurement officers, and managed service provider executives combined with secondary validation through SEC filings, EU regulatory databases, and hyperscaler sustainability reports. Bottom-up deployment tracking across Vienna and Linz facilities triangulates against top-down market sizing from component shipment data.
Sensitivity analysis around NAND flash pricing volatility and EU regulatory implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include storage architecture type, deployment model, end-user category, and interface technology tier. CAGRs derive from fitted adoption curves for NVMe over Fabrics and liquid-cooled systems, with inputs spanning Federal Ministry for Climate Action efficiency mandate compliance schedules and hyperscale facility expansion announcements.
Material uncertainties — NAND flash supply concentration, EU Critical Entities Resilience Act implementation timing, and specialized engineering certification scarcity — sit outside the modeled envelope. Forecasts reflect assumptions about continued hyperscale investment in Vienna and Linz and stable EU regulatory alignment. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Brazil Data Center Storage Market
Storage Solutions
Global Data Erasure Solutions Market
Storage Solutions
Switzerland Data Center Storage Market
Storage Solutions
Global Cloud Storage Software Market
Storage Solutions
Belgium Data Center Storage Market
Storage Solutions
Copy Data Management Software Market
Storage Solutions
Cloud Block Storage Market
Storage Solutions
Cloud Native Storage Market
Storage Solutions
Network File System Market
Storage Solutions
5D Data Storage Market
Storage Solutions
Cloud Storage Gateways Market
Storage Solutions
Global in Memory Data Grid Market
Storage Solutions
Global Storage As a Service Market
Storage Solutions
Asia Pacific Automated Storage and Retrieval System Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market