
 Spain Data Center Storage Market | 2026-2036
Spain Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Data Center Storage Market Insights
Data center engineering talent scarcity in Spain is rotating enterprise procurement toward vendors with embedded managed services capabilities. Dell Inc. leverages its Barcelona technical support hub to sustain direct relationships with Iberian banking clients. Pure Storage Inc. competes through all-flash specialization that reduces rack-space requirements in Madrid's power-constrained facilities. Huawei Technologies Co. Ltd. anchors public-sector tenders with aggressive pricing on software-defined arrays despite geopolitical headwinds.
Spain data center storage encompasses electromechanical and solid-state systems designed for 24/7 availability in climate-controlled facilities, typically operating across temperature ranges of 10°C to 35°C with N+1 redundancy on power and cooling subsystems. These systems archive transactional records, virtual machine images, and analytics datasets for enterprises requiring sub-10 millisecond access latencies. Solid state drives command premium positioning in financial services deployments where microseconds determine trading outcomes, while hard disk drives retain cost advantages in archival tiers serving Spain's public healthcare imaging repositories. Software-defined storage is displacing traditional SAN architectures as Telefónica and regional banks consolidate multi-site infrastructure under unified control planes.
Spain's national cybersecurity strategy and BIS-equivalent standards on critical infrastructure resilience mandate encrypted-at-rest protocols for operators of essential services. The Spanish Data Protection Agency enforces GDPR-aligned retention and deletion rules that shape storage procurement specifications across healthcare and education verticals. National digital transformation subsidies under the Recovery Plan condition funding on energy efficiency metrics that favor flash over mechanical media. Stakeholders must weigh sovereign cloud mandates against total cost of ownership when selecting between domestic colocation providers and hyperscale platforms.
Market Dynamics
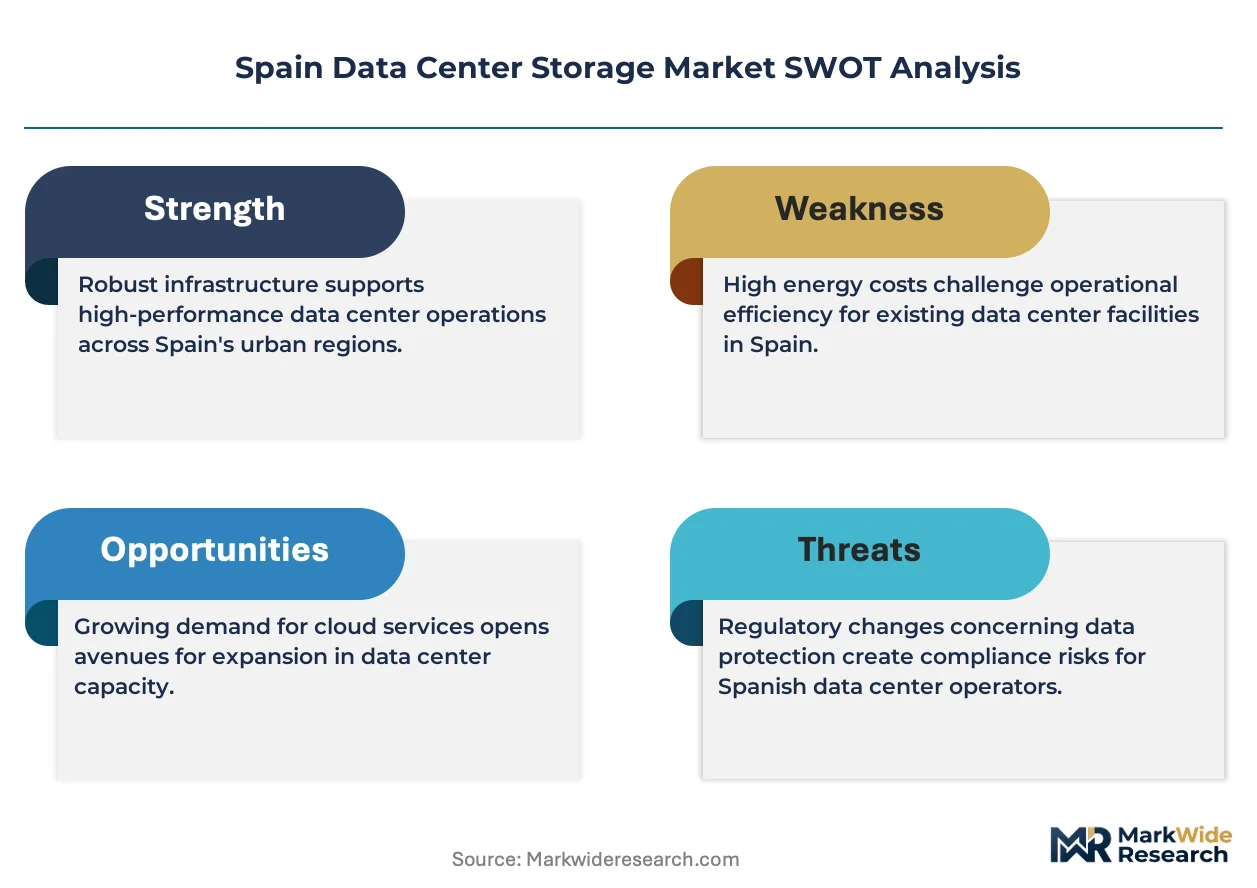
Spanish financial institutions face ECB digital operational resilience mandates that compress storage procurement cycles and favor all-flash architectures capable of sub-millisecond latency guarantees. This regulatory pressure layer compounds with Madrid's power density constraints to reshape vendor selection criteria.
Growth Catalysts
- ECB DORA compliance deadlines:Spanish banks must demonstrate fault-tolerant storage infrastructure by 2025, accelerating replacement of mechanical disk arrays with solid-state systems.
- Hyperscale clustering in Madrid-Barcelona corridor:Concentrated cloud facility construction creates localized demand spikes for high-density storage configurations.
- All-flash price-performance crossover:Declining NAND costs per terabyte now position flash storage competitively against hybrid arrays for primary workloads.
Market Restraints
- Specialized engineering scarcity:Spain produces insufficient data center infrastructure technicians, forcing enterprises toward vendor-managed service contracts.
- Power grid saturation in Madrid metro:Utility interconnection queues stretch 18-24 months, capping storage expansion at existing facilities.
- Geopolitical friction on Chinese equipment:Huawei's dominance in public-sector tenders faces mounting scrutiny under EU supply chain security frameworks.
Strategic Opportunities
- Andalusian secondary market development:Málaga's emerging tech corridor offers lower land and power costs for disaster recovery sites serving Madrid-based financials.
- Recovery Plan efficiency subsidies:Spain's national digital transformation funding favors flash storage deployments meeting strict PUE and carbon intensity thresholds.
- Software-defined convergence:Unified storage-compute-networking platforms reduce rack-space requirements in Barcelona's premium colocation facilities.
Industry Challenges
- Legacy SAN migration complexity:Regional banks operating 15-year-old Fibre Channel infrastructures face disruptive forklift upgrades to NVMe fabrics.
- GDPR retention-deletion workflow engineering:Spanish healthcare providers struggle to implement automated policy enforcement across petabyte-scale imaging archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Data Center Storage Market |
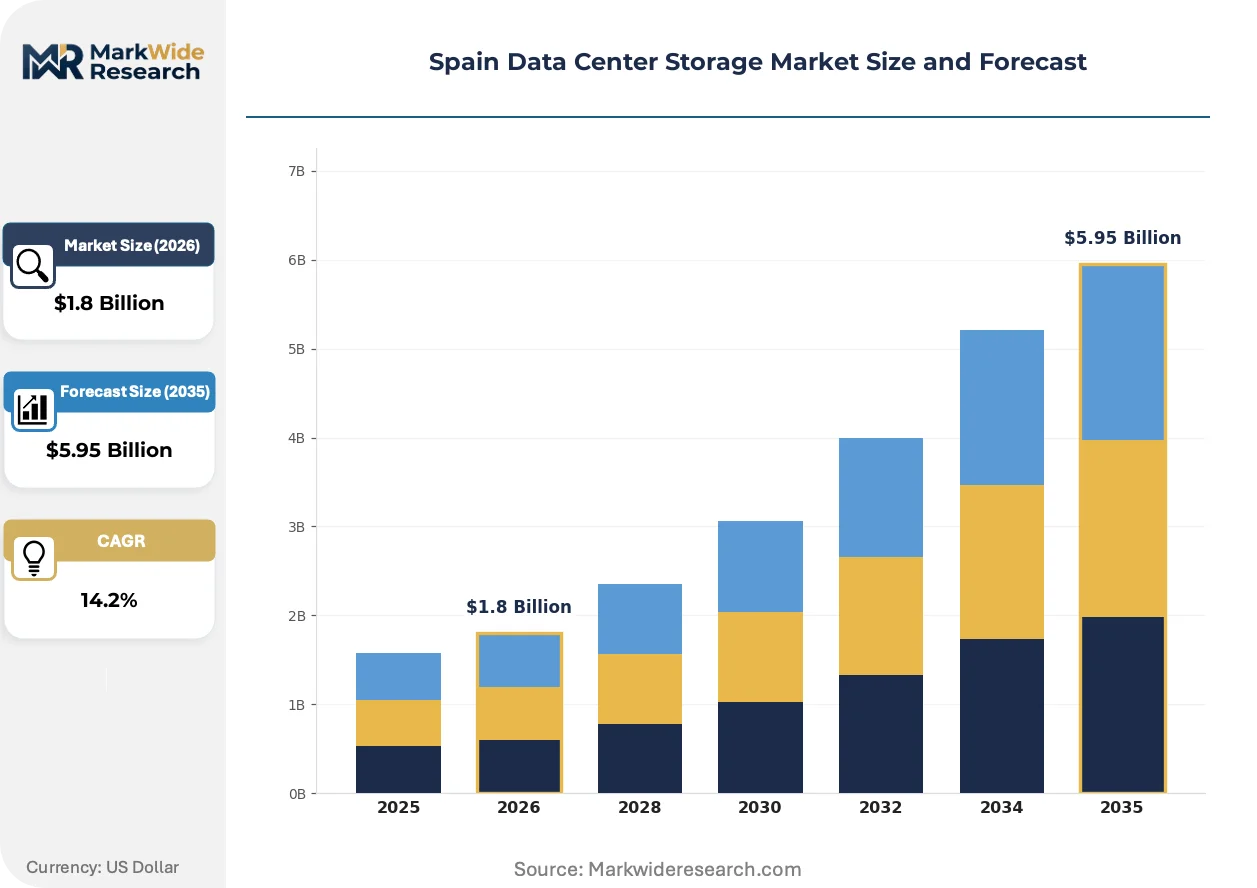
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Disk Drives, Solid State Drives, Tape Storage, Hybrid Storage Technology: Cloud Storage, On-Premises Storage, Software-Defined Storage, Object Storage End User: Telecommunications, Financial Services, Healthcare, Education Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud |
| Companies Covered | Dell Inc., Hewlett Packard Enterprise, Huawei Technologies Co. Ltd., Hitachi Vantara LLC, Kingston Technology Company Inc., Pure Storage Inc., Infinidat Ltd., NetApp Inc., Nutanix Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Data Center Storage Market Trends and Innovations
Storage architecture in Spain is pivoting toward disaggregated designs that separate compute and media resources. This structural shift responds to power constraints and regulatory mandates simultaneously.
NVMe-over-Fabrics is displacing traditional SCSI-based protocols in Madrid's financial services data centers. CaixaBank and Santander's Iberian operations have completed core trading platform migrations to NVMe-oF fabrics. This protocol transition is displacing legacy Fibre Channel switching infrastructure and collapsing storage network tiers from three layers to one.
Spain's national cybersecurity strategy mandates encrypted-at-rest protocols for operators of essential services. The Spanish Data Protection Agency enforces GDPR-aligned technical specifications that storage vendors must certify against. Healthcare verticals in Catalonia and Madrid are most affected, with hospital consortia now requiring FIPS 140-2 validated self-encrypting drives as standard procurement terms.
Spanish enterprises are consolidating multi-site storage under single control planes managed by domestic system integrators. Telefónica's cloud division and regional VARs are capturing procurement decisions previously executed through direct vendor relationships. This channel shift concentrates most visibly in Basque Country manufacturing clusters, where industrial IoT data lakes require localized support capabilities that hyperscale platforms cannot match.
Spain Data Center Storage Market Segmentation
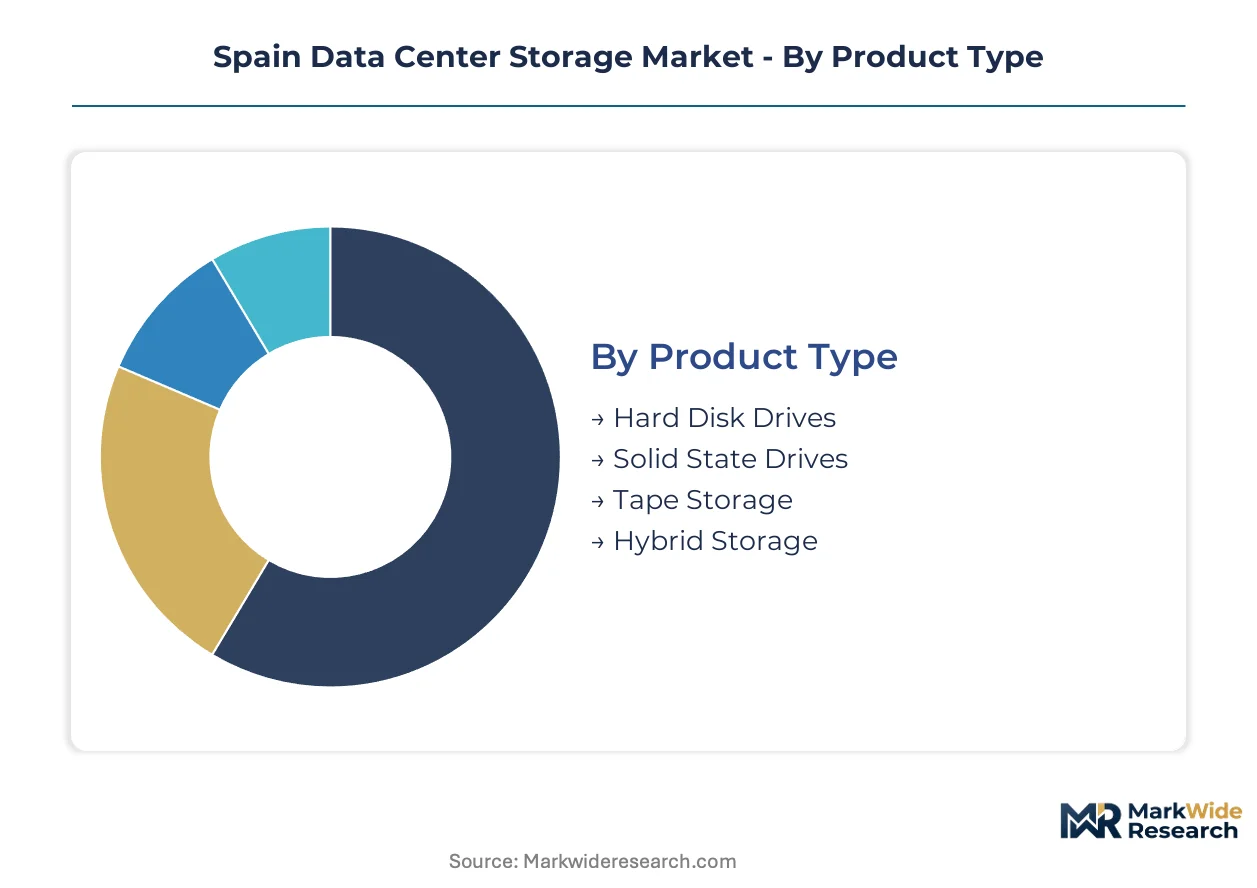
Spain's data center storage procurement channels favor different segment combinations based on workload criticality and compliance posture. Vendor selection criteria vary sharply between hyperscale cloud gateways and regulated on-premises deployments.
Product Type:
Channel mix splits between direct enterprise sales for high-performance tiers and distributor-led fulfillment for commodity capacity expansion. Madrid's financial services procurement teams source solid-state systems through vendor technical support hubs, while regional healthcare networks acquire hard disk arrays via systems integrators.
- Solid State Drives:NAND-based flash media delivering sub-millisecond latency for transactional workloads. CaixaBank and Santander's Madrid trading floors specify NVMe enterprise drives to meet ECB DORA fault-tolerance mandates. Power density advantages prove decisive where Madrid metro utility interconnection queues stretch 18-24 months.
- Hard Disk Drives:Electromechanical rotating media optimized for cost-per-terabyte in archival tiers. Catalonia's hospital consortia deploy helium-filled high-capacity drives for petabyte-scale medical imaging repositories subject to GDPR retention rules. Mechanical arrays retain procurement share where Recovery Plan efficiency subsidies do not apply.
- Tape Storage:Linear magnetic media for air-gapped compliance archives in Basque Country manufacturing clusters.
- Hybrid Storage:Tiered flash-disk controllers automating data placement between performance and capacity layers.
Hard disk drives dominate installed base. Solid state drives are where expansion concentrates.
Technology:
Margin structure varies by control plane architecture — unified software-defined platforms command premium pricing over discrete hardware procurement.
- Software-Defined Storage:Decoupled control and data planes enabling commodity hardware consumption. Telefónica's cloud division and regional banks consolidate multi-site infrastructure under single management layers. Barcelona's power-constrained colocation facilities favor this architecture for rack-space efficiency.
- Cloud Storage:Hyperscale object and block services delivered from Madrid-Barcelona corridor facilities. Financial services institutions accelerate procurement to meet compressed DORA compliance deadlines. Sovereign cloud mandates from Spain's national cybersecurity strategy shape vendor eligibility.
- On-Premises Storage:Dedicated hardware deployments in enterprise-controlled facilities.
- Object Storage:Flat-namespace architectures for unstructured data lakes.
On-premises storage retains majority revenue share. Cloud storage is climbing the fastest as regulated workloads migrate to certified facilities.
End User:
Application criticality determines storage class selection — microseconds determine trading outcomes in financial services, while healthcare prioritizes encrypted-at-rest compliance over raw performance.
- Financial Services:Trading platforms and core banking systems requiring fault-tolerant sub-millisecond latency. Spanish institutions face ECB-mandated infrastructure overhauls with hard deadlines. All-flash procurement accelerates as NAND price-performance crosses competitive thresholds against hybrid alternatives.
- Healthcare:Diagnostic imaging archives and electronic health record systems. Catalonia and Madrid hospital consortia require FIPS 140-2 validated self-encrypting drives under Spanish Data Protection Agency enforcement. Automated GDPR retention-deletion workflows strain legacy SAN architectures.
- Telecommunications:Network function virtualization and subscriber data management.
- Education:Research computing and administrative systems with subsidy-dependent procurement cycles.
Financial services drives premium tier revenue. Healthcare represents the steepest expansion trajectory as imaging volumes compound regulatory storage mandates.
Deployment:
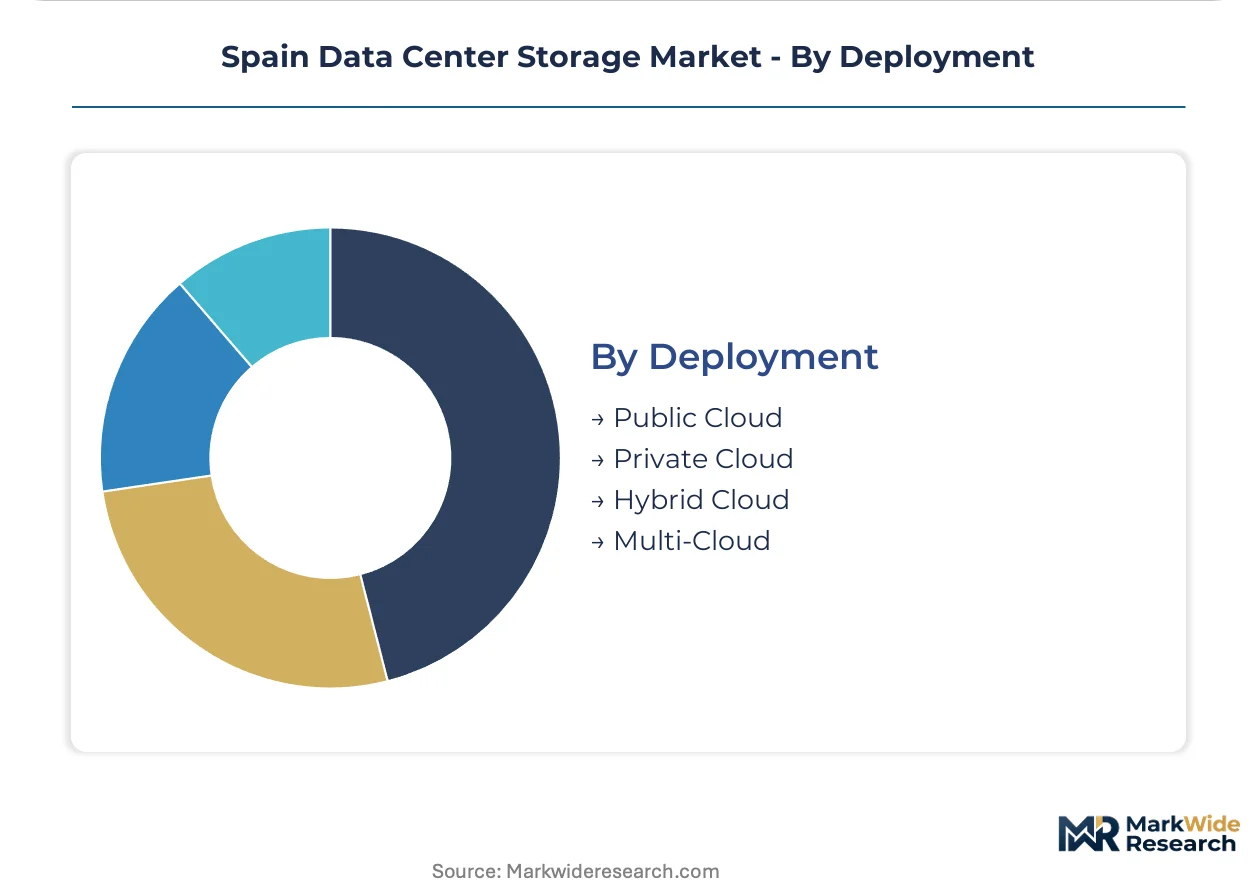
Customer IT maturity and data sovereignty requirements partition procurement between single-cloud and distributed architectures.
- Hybrid Cloud:Workload portability between on-premises and hyperscale resources. Spanish enterprises balance Recovery Plan subsidy eligibility against hyperscale operational efficiency. Unified control planes from domestic system integrators capture decisions previously executed through direct vendor relationships.
- Multi-Cloud:Deliberate distribution across competing hyperscale platforms to mitigate concentration risk. Andalusian secondary markets including Málaga's emerging tech corridor attract disaster recovery deployments serving Madrid-based financials.
- Public Cloud:Shared infrastructure consumption from hyperscale providers.
- Private Cloud:Dedicated resources within single-tenant facilities.
Hybrid cloud dominates current procurement cycles. Multi-cloud is gaining share fastest as operational resilience mandates drive architectural diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's data center storage consumption diverges sharply from broader European patterns, with Madrid and Barcelona metros absorbing disproportionate all-flash capacity for financial services compliance while secondary regions specialize in cost-optimized archival tiers for healthcare and manufacturing workloads.
Madrid
Spain's capital anchors the national financial services storage footprint, with CaixaBank and Santander's trading floors driving NVMe enterprise drive procurement to meet ECB DORA fault-tolerance mandates. The Spanish Data Protection Agency enforces encrypted-at-rest protocols that shape vendor certification requirements. Power grid saturation stretches utility interconnection queues to 18-24 months, capping expansion at existing hyperscale facilities clustered in the metro corridor.
Catalonia
Barcelona's technical support hub sustains direct vendor relationships with Iberian banking clients while the city's power-constrained colocation facilities favor software-defined architectures for rack-space efficiency. Catalonia's hospital consortia deploy helium-filled high-capacity drives for petabyte-scale medical imaging repositories subject to GDPR retention rules. The regional government channels Recovery Plan subsidies toward flash storage meeting strict PUE and carbon intensity thresholds.
Basque Country
Industrial IoT data lakes in this northern manufacturing cluster require localized support capabilities that hyperscale platforms cannot match, consolidating procurement under domestic system integrators. Tape storage retains procurement share for air-gapped compliance archives serving automotive and aerospace suppliers. Regional VARs capture decisions previously executed through direct vendor relationships.
Andalusia
Málaga's emerging tech corridor offers lower land and power costs for disaster recovery sites serving Madrid-based financial institutions, attracting multi-cloud deployments deliberately distributed to mitigate concentration risk. The regional development agency coordinates with national digital transformation funding to position the metro as a secondary market alternative. Cloud facility construction here lags Madrid-Barcelona by approximately 36 months.
Valencia
This eastern coastal region specializes in education and research computing procurement cycles dependent on subsidy timing, with universities deploying hybrid storage configurations balancing Recovery Plan efficiency eligibility against legacy system compatibility. The regional innovation cluster lacks the financial services density that drives all-flash premium tier revenue elsewhere. Public healthcare networks here mirror Catalonia's GDPR-driven encryption mandates at lower deployment scale.
Spain Data Center Storage Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Spain's data center storage market, with consolidated procurement power concentrated among Madrid-based financial institutions and Barcelona hyperscale operators. The vendor base separates into three strategic archetypes: full-stack infrastructure incumbents with embedded managed services capabilities, all-flash specialists competing on latency guarantees, and price-aggressive challengers anchoring public-sector tenders. Dominant competitive moves include geographic expansion through technical support hub establishment and portfolio diversification into software-defined control planes.
Within the integrated infrastructure tier, Dell Inc. and Hewlett Packard Enterprise occupy positions shaped by direct enterprise sales relationships and channel depth across Iberian banking clients. Pure Storage Inc. exemplifies the all-flash specialist archetype, while Huawei Technologies Co. Ltd. represents the price-competitive challenger segment despite geopolitical headwinds under EU supply chain security frameworks.
| Leading Market Players |
|---|
| Dell Inc. |
| Hewlett Packard Enterprise |
| Huawei Technologies Co. Ltd. |
| Hitachi Vantara LLC |
| Kingston Technology Company Inc. |
| Pure Storage Inc. |
| Infinidat Ltd. |
| NetApp Inc. |
| Nutanix Inc. |
| Others |
Pricing and Supply Chain Analysis
Hyperscale facility utilization rates exceeding 85 percent in Madrid and Barcelona corridors concentrate procurement leverage among a handful of cloud operators, compressing price floors for enterprise storage arrays while elevating premiums for power-efficient NVMe configurations in supply-constrained metro zones.
Pricing Analysis
Long-term capacity reservation contracts dominate procurement between Spanish financial institutions and storage vendors, with CaixaBank and Santander negotiating three-year all-flash array offtakes that lock in volume pricing against NAND spot market volatility. Price differentiation separates FIPS 140-2 validated self-encrypting drives from standard enterprise SSDs, with GDPR compliance premiums widening as the Spanish Data Protection Agency tightens enforcement. Cost compression in archival HDD tiers intensifies because helium-filled high-capacity drive manufacturing scales faster than flash foundry expansion. Regional healthcare networks exhibit highest price sensitivity due to Recovery Plan subsidy dependency, while Madrid trading floors prioritize latency guarantees over unit economics.
Supply Chain Analysis
Just-in-time NAND flash inventory strategies prevail among Spanish system integrators, though strategic stockpiling of enterprise drives is emerging as Madrid power-constraint delays stretch deployment timelines. Component supply concentrates in South Korea, Taiwan, and Japan for advanced memory fabrication, with controller silicon sourcing anchored in the United States and China. Raw material dependencies span silicon wafers, rare earth elements for drive magnetics, and specialty gases for semiconductor etching. Single-source vulnerability concentrates in advanced node NAND production, where two foundry groups supply 80 percent of enterprise-grade flash. Distribution runs through Barcelona technical support hubs for direct enterprise fulfillment, with distributor-led channels serving regional healthcare and education verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across Spain's data center storage landscape as ECB DORA compliance deadlines fragment procurement authority between central IT and line-of-business risk officers, creating niche openings for specialized compliance-focused vendors.
For Market Incumbents: Compound defensive moats by embedding managed services capabilities deeper into Barcelona technical support operations, directly countering engineering scarcity that forces Spanish banks toward vendor-managed contracts. Acquire or partner with domestic system integrators in Basque Country manufacturing clusters before channel consolidation completes. Prioritize certification investment for FIPS 140-2 and sovereign cloud eligibility under Spain's national cybersecurity strategy.
For New Entrants and Emerging Players: Lead with software-defined storage architectures targeting Andalusian secondary markets, where Málaga's emerging tech corridor offers lower land and power costs for disaster recovery sites serving Madrid-based financials. The most penetrable white space sits in automated GDPR retention-deletion workflow tools for Catalonia and Madrid hospital consortia struggling with petabyte-scale imaging archive compliance. Pursue channel partnerships with regional VARs rather than direct enterprise sales.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors all-flash specialists with proven NVMe-over-Fabrics deployments, as protocol transition from legacy Fibre Channel creates durable differentiation through installed base switching refresh cycles. Long-term viability rests on software control plane ownership rather than commodity hardware assembly. Watch for inflection when Madrid utility interconnection queue lengths compress below twelve months, signaling power constraint relief that would shift procurement priority from density back toward raw cost-per-terabyte.
| Strategic Initiative | Industry Significance |
|---|---|
| Managed Services Embedding | Barcelona technical support hubs capture Iberian banking relationships previously lost to channel partners. |
| Software-Defined Convergence | Unified control planes reduce rack-space requirements in power-constrained Madrid colocation facilities. |
| Andalusian Geographic Expansion | Málaga disaster recovery sites exploit land and power cost arbitrage against Madrid metro saturation. |
| GDPR Workflow Automation | Automated retention-deletion tools address Spanish healthcare providers' petabyte-scale compliance strain. |
| Sovereign Cloud Certification | Spanish national cybersecurity strategy mandates shape vendor eligibility for public-sector tenders. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center infrastructure directors at Madrid financial institutions, procurement leads at Catalonia hospital consortia, technical architects at Barcelona hyperscale facilities, and channel managers at Iberian systems integrators. Secondary validation drew from ECB digital resilience guidance documents, Spanish Data Protection Agency enforcement notices, Recovery Plan subsidy allocation records, and hyperscaler capex disclosure filings. Bottom-up installation tracking across Madrid-Barcelona corridor facilities was triangulated against top-down vendor shipment estimates.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, deployment architecture, end-user vertical, and regional metro cluster. Segmentation dimensions included solid-state versus mechanical media, software-defined versus hardware-centric control planes, financial services versus healthcare versus telecommunications verticals, and Madrid-Catalonia-Basque-Andalusia-Valencia regional splits. CAGRs were derived from installation base growth rates, replacement cycle compression under DORA deadlines, and NAND price elasticity assumptions calibrated to foundry utilization data.
Forecasts assume regulatory continuity in ECB operational resilience frameworks and Spanish national cybersecurity strategy implementation; material policy shifts would require re-modeling. Revision becomes warranted when Madrid utility interconnection queue durations compress below twelve months or when EU supply chain security frameworks materially restrict Chinese equipment eligibility in public-sector tenders.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Copy Data Management Software Market
Storage Solutions
Public Cloud Storage Services Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Media and Entertainment Storage Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
Poland Data Center Storage Market
Storage Solutions
Hong Kong Data Center Storage Market
Storage Solutions
New Zealand Data Center Storage Market
Storage Solutions
Italy Data Center Storage Market
Storage Solutions
South Africa Data Center Storage Market
Storage Solutions
Cloud Storage Market
Storage Solutions
Global All-Flash Array Market
Storage Solutions
Global in-Memory Database Market
Storage Solutions
Cloud Block Storage Market
Storage Solutions
Virtual Machine Backup and Recovery Market