
 India Data Center Storage Market | 2026-2036
India Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
India Data Center Storage Market Insights
Project finance through infrastructure investment trusts is narrowing the competitive field for data center storage procurement. Dell Inc. leverages its direct sales force and local manufacturing presence to anchor large enterprise contracts across Mumbai and Bangalore. Hewlett Packard Enterprise competes through its GreenLake as-a-service platform, which sustains recurring revenue relationships with mid-market colocation operators. Pure Storage Inc. specializes in all-flash arrays, positioning its portfolio for latency-sensitive workloads in financial services and digital payment gateways.
India data center storage encompasses solid-state drives, hard disk drives, hybrid arrays, and tape systems engineered for petabyte-scale data persistence, redundancy, and sub-millisecond access in enterprise and cloud environments. Enterprise SSD deployments now dominate new capacity additions as hyperscalers prioritize IOPS density and power efficiency over cost-per-gigabyte economics. Deployment model segmentation reveals cloud-based and colocation storage as the fastest-expanding categories, while on-premises retention persists in BFSI and government verticals constrained by data localization mandates. End user industry analysis shows IT and telecom operators capturing the largest share of storage procurement volume, though healthcare is emerging as a high-margin segment driven by diagnostic imaging archives and electronic health record retention requirements.
BIS certification requirements for electronic storage equipment, combined with MeitY's data center guidelines and state-level power tariff incentives, are compressing deployment timelines for domestic manufacturers while raising compliance costs for imported hardware. CEA grid connectivity standards and state electricity regulatory commission directives on renewable energy purchase obligations are forcing operators to co-locate storage infrastructure with solar or captive power assets. Stakeholders must monitor evolving localization thresholds under the PLI scheme for IT hardware, as these rules will determine which vendors can participate in government and public sector digital infrastructure tenders without penalty.
Market Dynamics
Hyperscale cloud operators are compressing procurement cycles for petabyte-scale storage infrastructure, forcing legacy vendors to reconfigure distribution models around as-a-service consumption frameworks.
Growth Catalysts
- MeitY Data Center Guidelines:India's Ministry of Electronics and Information Technology mandates Tier III certification for government cloud deployments, accelerating replacement of aging disk arrays in public sector facilities.
- AI/ML Training Clusters:GPU-intensive workloads for large language model development require NVMe-oF fabric architectures, pulling all-flash storage into captive facilities across Hyderabad and Mumbai.
- State Power Tariff Incentives:Gujarat and Telangana offer concessional electricity rates for data center operators, lowering total cost of ownership for storage-heavy deployments in these clusters.
Market Restraints
- NAND Flash Supply Concentration:Korean and Taiwanese foundries control wafer output, exposing Indian system integrators to price volatility and allocation constraints during supply shocks.
- BIS Certification Delays:Bureau of Indian Standards testing timelines for imported solid-state drives extend deployment schedules by 8-14 weeks, compressing project windows for hyperscale builds.
- Tape Archive Substitution:Cold storage tiering to object storage on commodity hardware is displacing robotic tape libraries in backup and archival applications, eroding a traditional revenue stream for incumbent vendors.
Strategic Opportunities
- Edge Micro-Data Centers:5G rollouts and autonomous vehicle testing corridors in Tamil Nadu and Karnataka create demand for ruggedized, software-defined storage nodes outside traditional metro clusters.
- Healthcare Imaging Archives:Diagnostic centers in tier-2 cities require petabyte-scale picture archiving and communication systems, opening a greenfield segment beyond saturated BFSI procurement.
- PLI Scheme Localization:Production-linked incentive thresholds for IT hardware assembly incentivize domestic manufacturing of storage controllers and enclosure subsystems, qualifying vendors for government tenders.
Industry Challenges
- Embedded Firmware Talent Scarcity:Indian engineering institutes produce limited graduates with expertise in flash translation layer optimization and NVMe driver development, constraining domestic R&D expansion.
- Legacy SAN Integration Complexity:Financial institutions with decade-old Fibre Channel fabrics face forklift upgrade costs when adopting cloud-native storage protocols, slowing modernization timelines.
- Renewable Energy Synchronization:CEA grid standards mandate solar co-location, forcing operators to engineer storage power supplies around intermittent generation profiles rather than stable grid feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Data Center Storage Market |
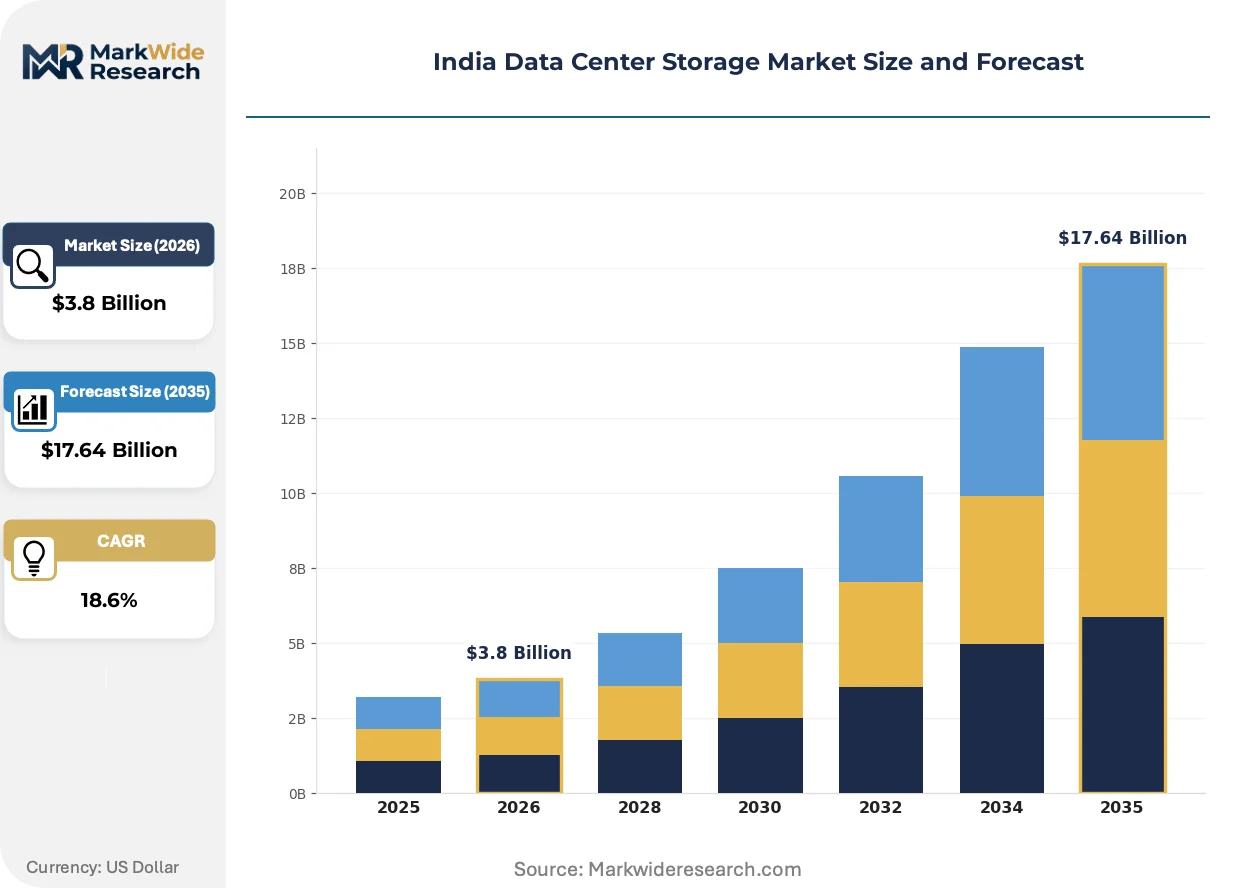
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: SSD, HDD, Hybrid Storage, Tape Storage Deployment Model: On-Premises, Colocation, Cloud-Based, Managed Services End User Industry: IT & Telecom, BFSI, Healthcare, Government Data Management Technology: Virtualization, Backup & Recovery, Cloud Storage, Disaster Recovery |
| Companies Covered | Dell Inc., Hewlett Packard Enterprise, NetApp Inc., Hitachi Vantara LLC, Kingston Technology Company Inc., Pure Storage Inc., Lenovo Group Limited, Fujitsu Limited, Oracle Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Data Center Storage Market Trends and Innovations
Storage architecture is converging around disaggregated, software-defined platforms that separate compute from persistent media, enabling hyperscalers to optimize resource utilization across heterogeneous hardware generations.
Computational storage drives with onboard processing capability are digitizing data reduction and encryption workloads that previously consumed host CPU cycles. Fintech payment processors in Mumbai are deploying these devices to achieve sub-100 microsecond latency for real-time fraud detection. This compression of processing hierarchy is eliminating the need for dedicated acceleration cards in high-frequency trading infrastructure.
BIS certification requirements for electronic storage equipment are tightening import documentation and testing protocols for solid-state drives entering Indian customs. Domestic assemblers with in-house testing laboratories are capturing procurement contracts from hyperscale operators seeking to bypass extended clearance timelines. State-level electronics manufacturing clusters in Uttar Pradesh and Tamil Nadu are absorbing this compliance-driven production shift.
Consumption-based financing models are displacing capital-intensive ownership structures among mid-market colocation providers. Storage vendors now offer capacity-as-a-service contracts with minimum commitment tiers, transferring utilization risk from operator to supplier. This restructuring is most visible in Noida and Pune, where second-tier data center operators lack balance sheet capacity for petabyte-scale flash deployments.
India Data Center Storage Market Segmentation
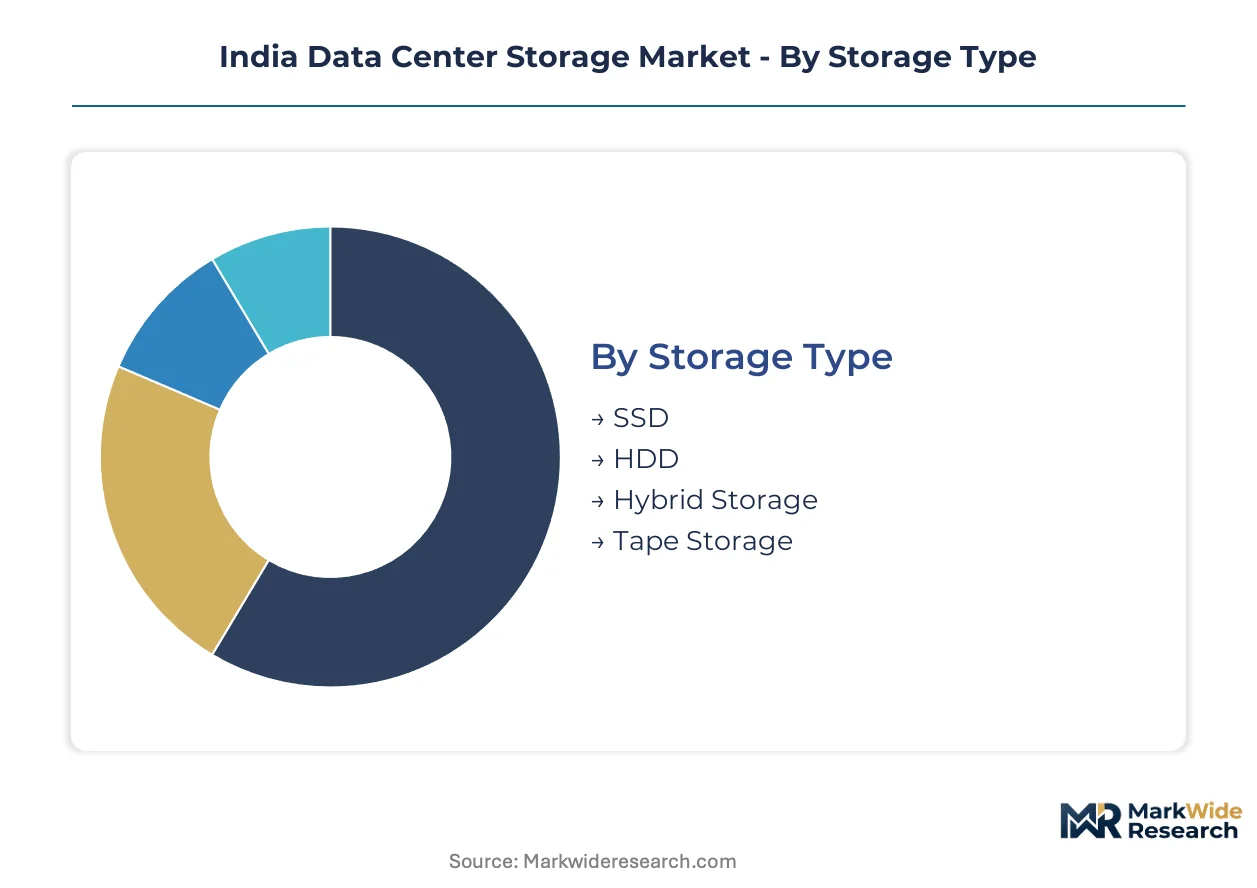
Storage procurement patterns across India diverge sharply by workload latency requirements and compliance constraints. Understanding these segment boundaries enables vendors to align product roadmaps with the diverging refresh cycles of hyperscale cloud operators versus regulated government facilities.
Storage Type:
Replacement velocity separates the storage media categories, with flash arrays cycling every 36-48 months while tape systems persist for 7-10 years in archival tiers.
- SSD:NAND-based solid-state drives deliver sub-millisecond latency and IOPS density critical for real-time payment processing and AI training clusters. Mumbai fintech operators and Hyderabad hyperscale facilities are absorbing the bulk of enterprise SSD procurement as they phase out mechanical disks for latency-sensitive workloads.
- HDD:Mechanical hard disk drives retain cost-per-gigabyte advantages for sequential read workloads and warm data tiers. Tier-2 colocation operators in Pune and Chennai continue deploying high-capacity helium-filled drives for bulk storage where access patterns tolerate 5-10 millisecond seek times.
- Hybrid Storage:Tiered architectures combining flash cache with disk capacity balance performance and economics for mixed workloads.
- Tape Storage:Linear tape-open systems and robotic libraries serve long-term compliance archives in government and BFSI verticals with 30-year retention mandates.
SSD anchors the volume base while tape storage gains share at the steepest rate among compliance-driven buyers seeking air-gapped ransomware protection.
Deployment Model:
Capital intensity and operational control requirements stratify deployment choices, with cloud-based models minimizing upfront investment while on-premises retention satisfies data localization mandates.
- On-Premises:Captive storage infrastructure within enterprise-owned facilities persists in BFSI and defense sectors where RBI and MeitY regulations mandate domestic data residency. State Bank of India and HDFC Bank maintain petabyte-scale private arrays for core banking systems.
- Cloud-Based:Object and block storage delivered via hyperscale provider APIs enables elastic capacity scaling for SaaS startups and ecommerce platforms. Bangalore and Delhi-NCR software companies are displacing owned infrastructure with consumption-based cloud storage contracts.
- Colocation:Leased rack space with cross-connected storage in certified Tier III facilities offers mid-market enterprises physical control without facility ownership burdens.
- Managed Services:Fully outsourced storage operations including backup orchestration and capacity planning appeal to healthcare diagnostic chains lacking internal IT depth.
Cloud-based deployment expands most quickly among venture-backed technology firms while on-premises retention maintains pricing power in regulated verticals.
End User Industry:
Procurement sophistication and contract scale vary dramatically across buyer verticals, with IT operators negotiating petabyte commitments and healthcare organizations navigating fragmented purchasing authority.
- IT & Telecom:Reliance Jio and Bharti Airtel drive storage procurement for subscriber data repositories, content delivery caches, and network function virtualization infrastructure. These operators prioritize NVMe-oF fabrics and software-defined storage to support 5G core deployments.
- BFSI:HDFC Bank, ICICI Bank, and insurance majors combine high-frequency trading storage with immutable audit logs for regulatory examination. RBI's data localization directives compel domestic storage infrastructure for all customer transaction records.
- Healthcare:Apollo Hospitals and diagnostic chains like SRL Diagnostics are digitizing radiology archives and pathology slides, creating petabyte-scale picture archiving requirements in tier-2 cities.
- Government:MeitY's India Stack and state data centers under the Digital India program mandate Tier III-certified storage for citizen service delivery platforms.
BFSI commands the steepest pricing premiums for low-latency tiers while healthcare climbs fastest as diagnostic digitization penetrates beyond metro hospitals.
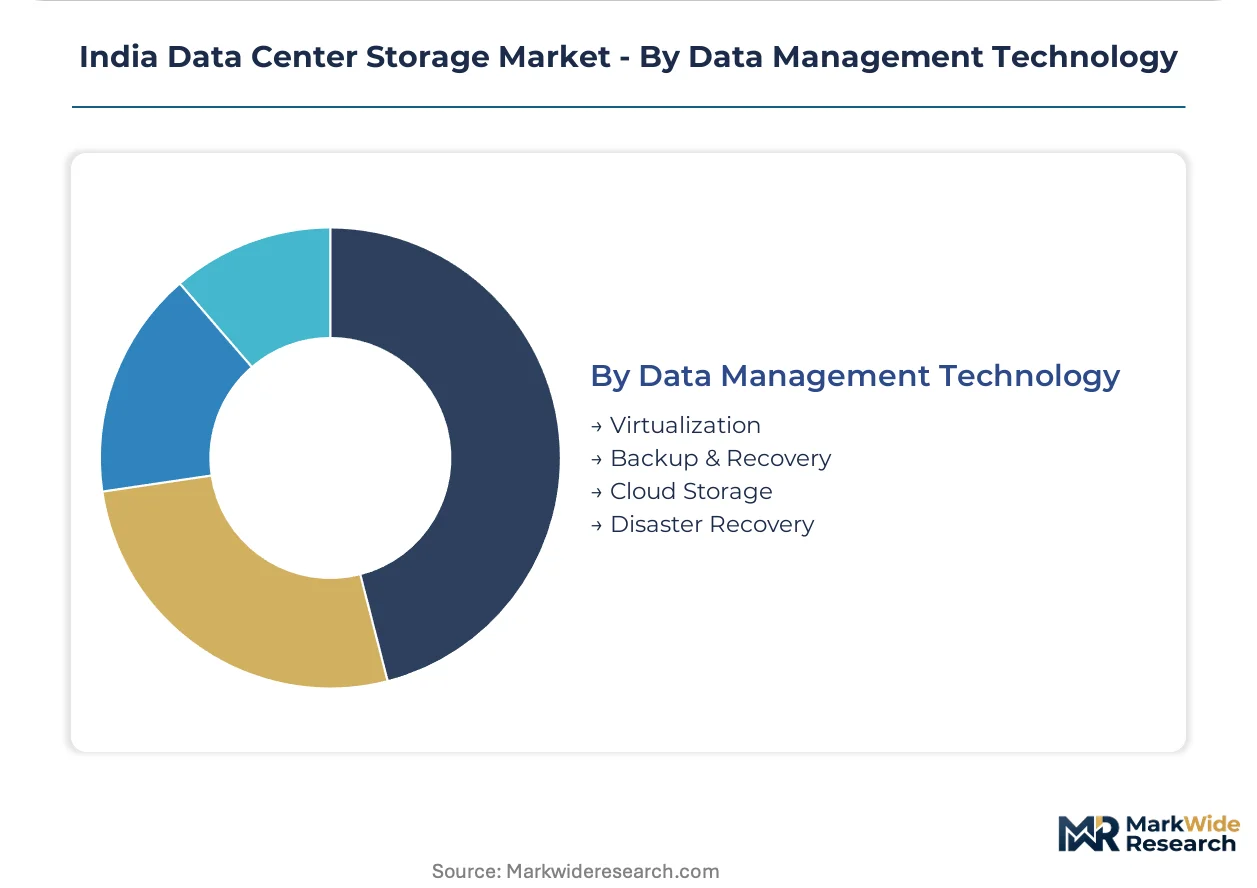
Data Management Technology:
Functional complexity and integration depth distinguish these technology layers, with virtualization forming the foundational abstraction and disaster recovery demanding the most intricate orchestration.
- Virtualization:Storage hypervisors and software-defined platforms abstract physical media into pooled resources, enabling hyperscalers to mix drive generations without application disruption. VMware vSAN and open-source Ceph deployments dominate private cloud builds.
- Disaster Recovery:Synchronous replication across availability zones and asynchronous geo-redundancy protect against facility-level failures. BFSI operators in Mumbai maintain DR sites in Hyderabad and Chennai with sub-15 minute recovery point objectives.
- Backup & Recovery:Snapshot orchestration and incremental backup software manage point-in-time recovery for ransomware resilience and operational error correction.
- Cloud Storage:Multi-cloud data management platforms unify access across AWS, Azure, and domestic providers like Jio Cloud and Yotta.
Virtualization underpins the broadest deployment base while disaster recovery commands the fastest expansion as ransomware attacks intensify board-level resilience mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra commands pricing premiums for Tier IV-certified storage infrastructure while Gujarat undercuts through concessional power tariffs and land allocations. This asymmetry is reshaping procurement geography across western India.
Maharashtra
Mumbai's BFSI concentration drives demand for sub-millisecond latency arrays in high-frequency trading and core banking systems. RBI's data localization mandates require domestic storage infrastructure for all customer transaction records. The Mumbai-Pune corridor hosts the majority of India's certified Tier III and Tier IV facilities serving HDFC Bank, ICICI Bank, and insurance majors.
Gujarat
Gandhinagar's state data center policy offers 100% electricity duty exemption and subsidized land leases for hyperscale builds. The state's Electronics Policy 2022-27 mandates BIS-compliant domestic assembly for storage equipment qualifying for government tenders. GIFT City near Ahmedabad is absorbing fintech and payment gateway operators seeking cost arbitrage on power-intensive flash deployments.
Telangana
Hyderabad's AI/ML training clusters require NVMe-oF fabric architectures for GPU-intensive workloads. TSIIC's data center policy provides single-window clearance and dedicated power feeders for facilities exceeding 10 MW capacity. The city's HITEC City and Genome Valley corridors concentrate hyperscale captive storage for pharmaceutical R&D and genomic data archives.
Karnataka
Bangalore's SaaS and ecommerce platforms are displacing owned infrastructure with consumption-based cloud storage contracts. The state's Electronics, IT and BT policy offers reimbursement of state GST for data center equipment manufactured within Karnataka. Whitefield and Electronic City host the densest concentration of colocation operators serving venture-backed technology firms.
Tamil Nadu
Chennai's 5G rollout and autonomous vehicle testing corridors create demand for ruggedized edge storage nodes. TANFAC's electronics manufacturing cluster incentives support domestic assembly of storage controllers and enclosure subsystems. Sriperumbudur and Oragadam industrial belts are absorbing compliance-driven production shifts from import-dependent vendors.
India Data Center Storage Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying NAND modules and controller silicon. The vendor base stratifies across three tiers: global systems houses with direct sales forces, regional assemblers leveraging PLI scheme localization, and pure-play flash vendors targeting latency-sensitive verticals. Dominant competitive moves include backward integration into domestic manufacturing and as-a-service consumption frameworks that transfer utilization risk from operator to supplier.
Within the global systems tier, Dell Inc. and Hewlett Packard Enterprise occupy positions anchored by direct enterprise relationships and local manufacturing presence. Pure Storage Inc. exemplifies the specialized flash architecture archetype, sitting apart from generalist portfolios. These three represent distinct competitive vectors: scale-driven platform breadth, recurring-revenue service wrap, and performance-optimized vertical specialization.
| Leading Market Players |
|---|
| Dell Inc. |
| Hewlett Packard Enterprise |
| NetApp Inc. |
| Hitachi Vantara LLC |
| Kingston Technology Company Inc. |
| Pure Storage Inc. |
| Lenovo Group Limited |
| Fujitsu Limited |
| Oracle Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Korean NAND foundries is compressing spot pricing for flash memory modules while simultaneously extending payment terms for Indian system integrators, creating divergent cash-flow pressures across the storage value chain.
Pricing Analysis
Configured-to-order pricing commands a 15-25% premium over standard SKUs in enterprise flash arrays, reflecting engineering validation and firmware customization for BFSI latency requirements. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and volume commitment, with hyperscale cloud operators extracting steepest discounts through petabyte-scale offtake agreements. Cost compression in mid-market hybrid arrays is intensifying because domestic assemblers are absorbing BIS certification overhead to bypass import delays. Government verticals show least price sensitivity due to data localization mandates, while SaaS startups in Bangalore negotiate aggressively on per-terabyte consumption rates.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for NAND module procurement, with supply-chain finance facilities bridging working capital gaps for Tier-2 system integrators in Noida and Chennai. Component sourcing draws from South Korea, Taiwan, and Japan for flash wafers, controllers, and enterprise-grade capacitors respectively. Single-source vulnerability concentrates in Korean foundry output for advanced NAND nodes, exposing Indian vendors to allocation constraints during supply shocks. Distribution runs through authorized distributor networks serving Mumbai and Hyderabad, with direct procurement relationships emerging for hyperscale operators exceeding 10 petabyte annual volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
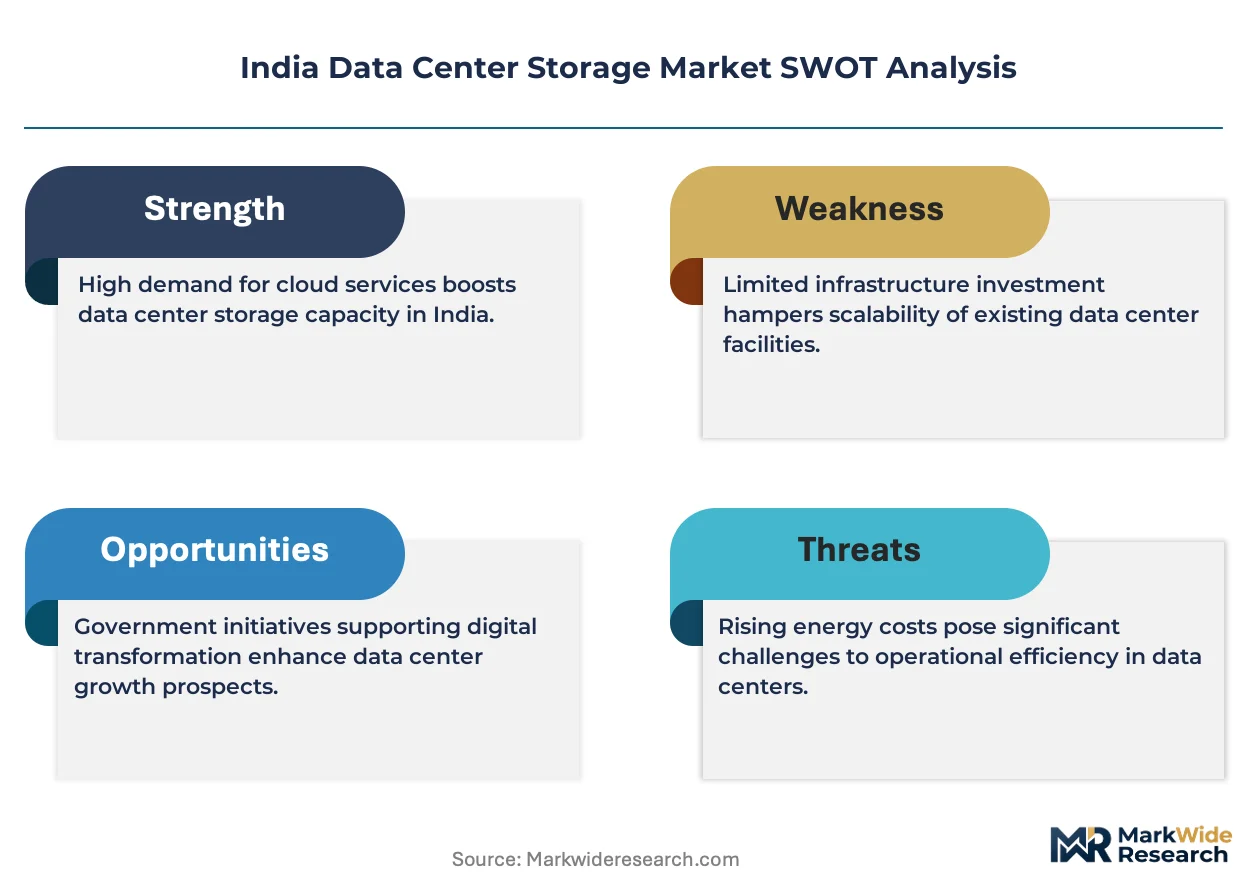
India's data center storage market sits in early-cycle expansion, with AI/ML training cluster deployment acting as the primary demand accelerator pulling NVMe-oF infrastructure into captive facilities.
For Market Incumbents: Insulate core BFSI relationships through in-house production of storage controllers qualifying for PLI scheme benefits, while accelerating as-a-service consumption frameworks that transfer utilization risk to balance-sheet-constrained colocation operators. Tape archive substitution by object storage represents a named threat requiring defensive portfolio repositioning toward immutable backup software layers. For New Entrants and Emerging Players: Tier-2 healthcare diagnostic centers in cities like Indore and Lucknow offer the most penetrable white-space, with picture archiving requirements outpacing local IT infrastructure depth. A software-defined storage node optimized for edge micro-data center deployments in Tamil Nadu's 5G corridors provides a distinct go-to-market angle against incumbent rack-scale systems. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-based deployment models as consumption financing displaces ownership structures, compressing return thresholds for hardware-heavy business models. Acquisition targets should emphasize domestic BIS certification capabilities and established relationships with state data center authorities. The signal to monitor is hyperscaler procurement cycle compression below 12 months, indicating infrastructure build-out acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Localization | BIS-compliant assembly qualifies vendors for MeitY tenders under PLI scheme thresholds. |
| NVMe-oF Fabric Deployment | GPU-intensive AI clusters in Hyderabad require sub-100 microsecond latency infrastructure. |
| Consumption-Based Financing Models | Capacity-as-a-service contracts transfer utilization risk from Noida colocation operators. |
| Healthcare Imaging Archive Specialization | Diagnostic digitization in tier-2 cities creates petabyte-scale PACS requirements. |
| Renewable Energy Co-location | CEA grid standards mandate solar pairing for storage power supplies in Gujarat facilities. |
Research Methodology
The analysis maps solid-state drive, hard disk drive, hybrid array, and tape storage sub-sectors, each validated through primary interviews with data center infrastructure heads, storage procurement officers at BFSI institutions, colocation facility operators, and MeitY policy officials. Secondary sources include BIS certification records, state electronics manufacturing cluster filings, CEA grid connectivity standards, and hyperscaler capex disclosures. Bottom-up capacity installation tracking triangulates against top-down spend analysis across the analysis window.
Assumptions held fixed include prevailing BIS certification timelines, state power tariff incentive continuity, and RBI data localization directive enforcement intensity. The modeling framework segments by storage type, deployment model, end-user industry, and data management technology, with CAGRs derived from regression against server shipment correlations and storage capacity-per-rack density trends. Forecast inputs incorporate NAND wafer supply schedules and state-level data center policy implementation pace.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Korean foundries into system-level assembly would shift outcomes. Macroeconomic deviation in venture capital flows to SaaS operators, regulatory acceleration of data localization scope, or breakthroughs in computational storage architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Global Server Storage Area Network Market
Storage Solutions
Global Data Erasure Solutions Market
Storage Solutions
Cloud Block Storage Market
Storage Solutions
Consumer Network Attached Storage Market
Storage Solutions
Cloud Native Storage Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Global in-Memory Database Market
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Storage in Big Data Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market
Storage Solutions
Switzerland Data Center Storage Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
Europe in-Memory Database Market
Storage Solutions
Consumer Cloud Storage Services Market
Storage Solutions
New Zealand Data Center Storage Market
Storage Solutions
Indonesia Data Center Storage Market