
 Earth Observation Satellite Market | 2026-2036
Earth Observation Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
Earth Observation Satellite Market Analysis
China is rewriting the competitive map for Earth observation constellations through accelerated state-funded deployment of high-resolution optical and radar satellites. Airbus Defence and Space leverages European institutional backing to sustain dual-use imaging capacity across civil and defense programs. Maxar Technologies Inc. anchors Western geospatial intelligence supply chains through its high-resolution archive and direct government relationships. Planet Labs PBC competes via daily global coverage from its Dove and SkySat fleets, differentiating on temporal revisit rates rather than spatial resolution alone.
Earth observation satellites are spacecraft equipped with electro-optical, radar, or multispectral sensors that collect geospatial data from altitudes ranging from low Earth orbit to geostationary positions, with spatial resolutions spanning sub-meter to kilometer scales depending on mission design. Their primary purpose spans environmental monitoring, disaster response, agricultural yield forecasting, and national security reconnaissance. Imaging satellites lead current fleet deployments due to mature sensor supply chains and established commercial imagery markets, while synthetic aperture radar technology represents the fastest-expanding segment because cloud-penetrating capability unlocks all-weather revenue streams in defense and maritime domains. Low Earth orbit deployment dominates new constellation launches as ride-share opportunities and standardized bus platforms compress unit economics for operators.
The Federal Aviation Administration governs U.S. commercial launch licensing while the National Oceanic and Atmospheric Administration regulates remote sensing spacecraft under the Land Remote Sensing Policy Act, creating a dual-track compliance environment for American operators. In Europe, the European Union Space Programme Agency coordinates Copernicus data policy while national regulators enforce ITAR-aligned export controls on high-resolution imagery. China's Ministry of Industry and Information Technology and National Space Administration jointly supervise domestic constellation licensing with explicit priority for sovereign data security. Stakeholders must monitor evolving debris mitigation mandates and spectrum allocation rulings that could constrain constellation density or impose costly maneuvering requirements on satellite operators.
Market Dynamics
Reusable rocket economics are collapsing launch costs below $2,000 per kilogram to low Earth orbit, triggering a fleet expansion race among sovereign and commercial operators who previously faced prohibitive per-satellite deployment expenses.
Growth Catalysts
- Synthetic aperture radar (SAR) payloads:Cloud-penetrating radar sensors unlock all-weather revenue streams for defense ministries monitoring maritime chokepoints and tracking ground movements regardless of atmospheric conditions.
- Copernicus data policy:The European Union Space Programme Agency's free and open data mandate subsidizes downstream application development across precision agriculture, carbon accounting, and infrastructure monitoring verticals.
- China:State-funded deployment of Gaofen and Haiyang constellation satellites compresses revisit intervals for high-resolution optical imaging, forcing Western operators to compete on temporal coverage rather than spatial resolution alone.
Market Restraints
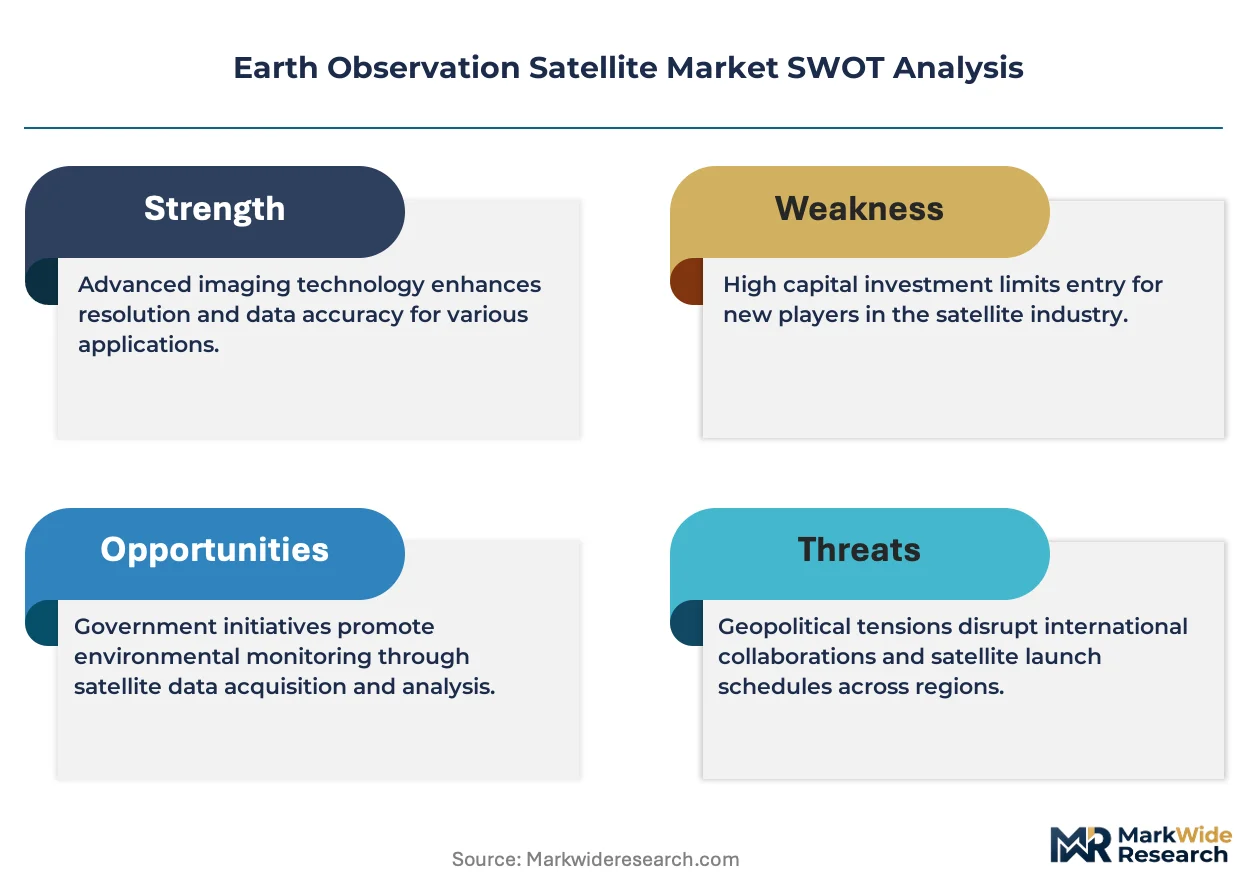
- Launch slot scarcity:Ride-share manifest congestion at Cape Canaveral and Vandenberg Space Force Base extends deployment timelines for commercial constellation operators lacking dedicated launch contracts.
- Sensor component concentration:German and Japanese suppliers dominate high-precision star tracker and reaction wheel markets, exposing non-integrated operators to single-source supply risk and extended lead times.
- ITAR-aligned export controls:United States Munitions List restrictions on sub-meter resolution imagery fragment data markets, preventing seamless cross-border licensing of defense-grade geospatial products.
Strategic Opportunities
- India:ISRO's commercial arm Antrix offers polar orbit launch services at cost structures 40% below Western alternatives, attracting European and Southeast Asian constellation operators seeking deployment diversification.
- Hyperspectral-synthetic aperture radar fusion:Combined sensor platforms enable mineral identification through vegetation canopy and soil moisture profiling for agricultural insurers, opening subscription revenue models beyond traditional imagery licensing.
- Carbon credit verification mandates:European Union Green Deal compliance requirements for satellite-measured reforestation and methane leak detection create guaranteed demand pools for hyperspectral analytics providers.
Industry Challenges
- Orbital mechanics expertise scarcity:Constellation operators compete for limited talent pools capable of optimizing distributed autonomous scheduling algorithms across hundreds of satellites.
- Debris mitigation maneuvering costs:FCC and ESA collision avoidance protocols require propellant reserves that reduce operational lifespans and compress revenue windows for low-margin CubeSat fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earth Observation Satellite Market |
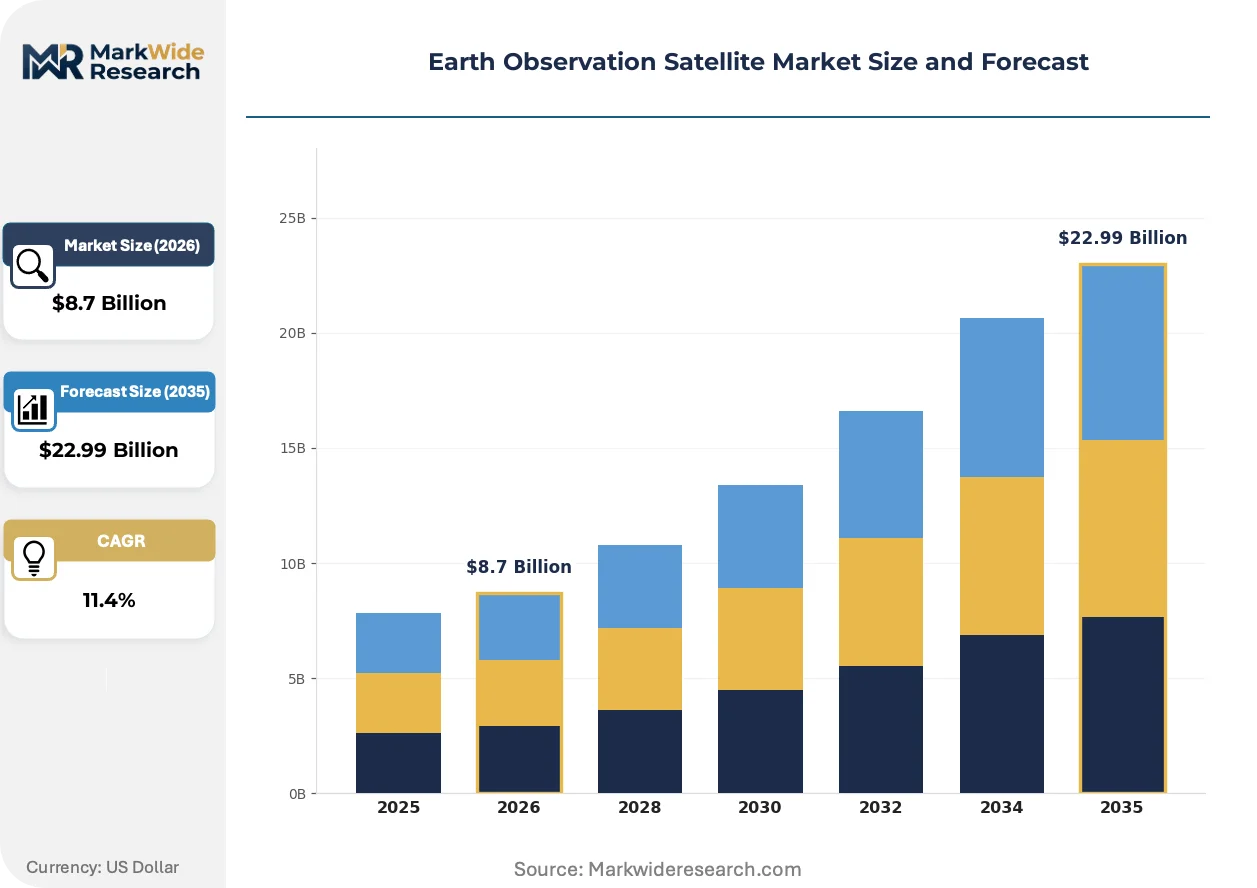
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
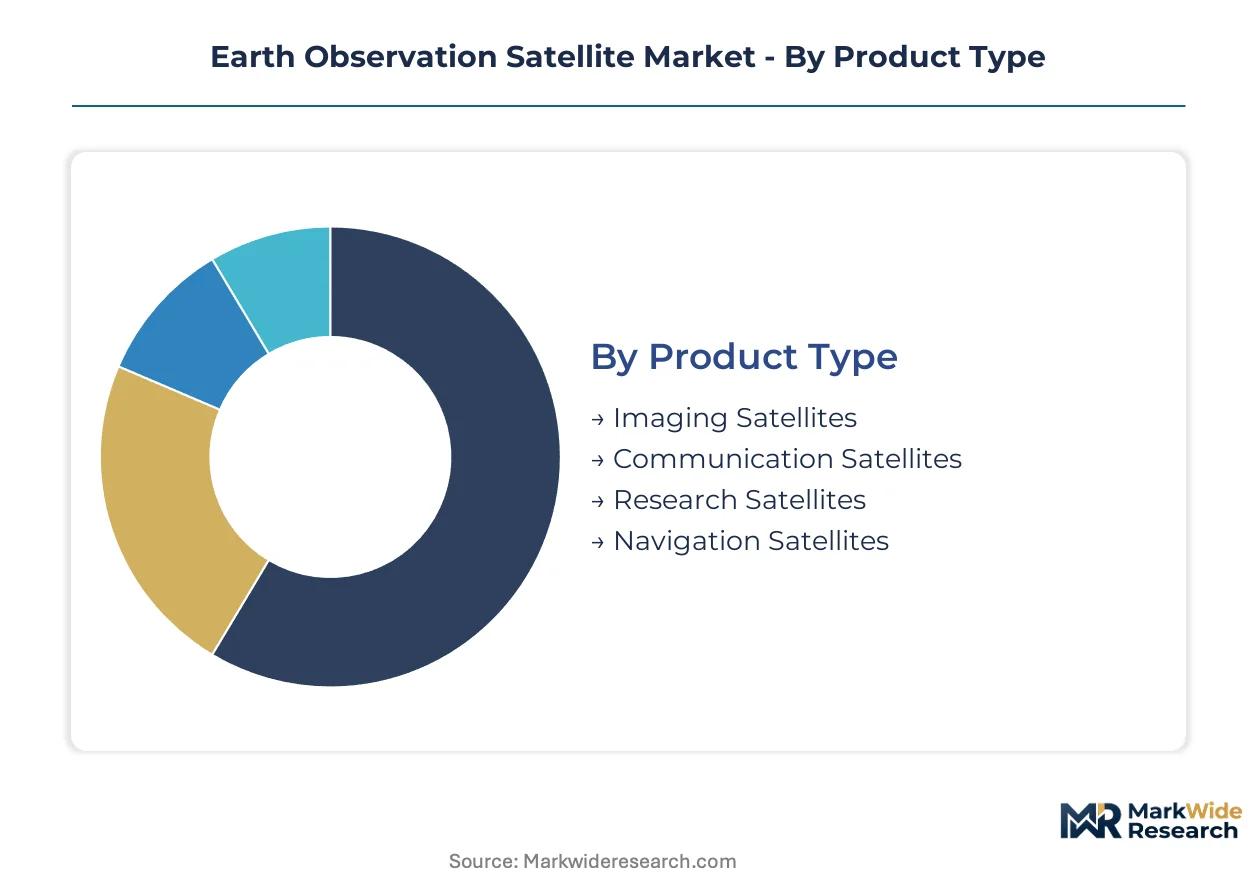
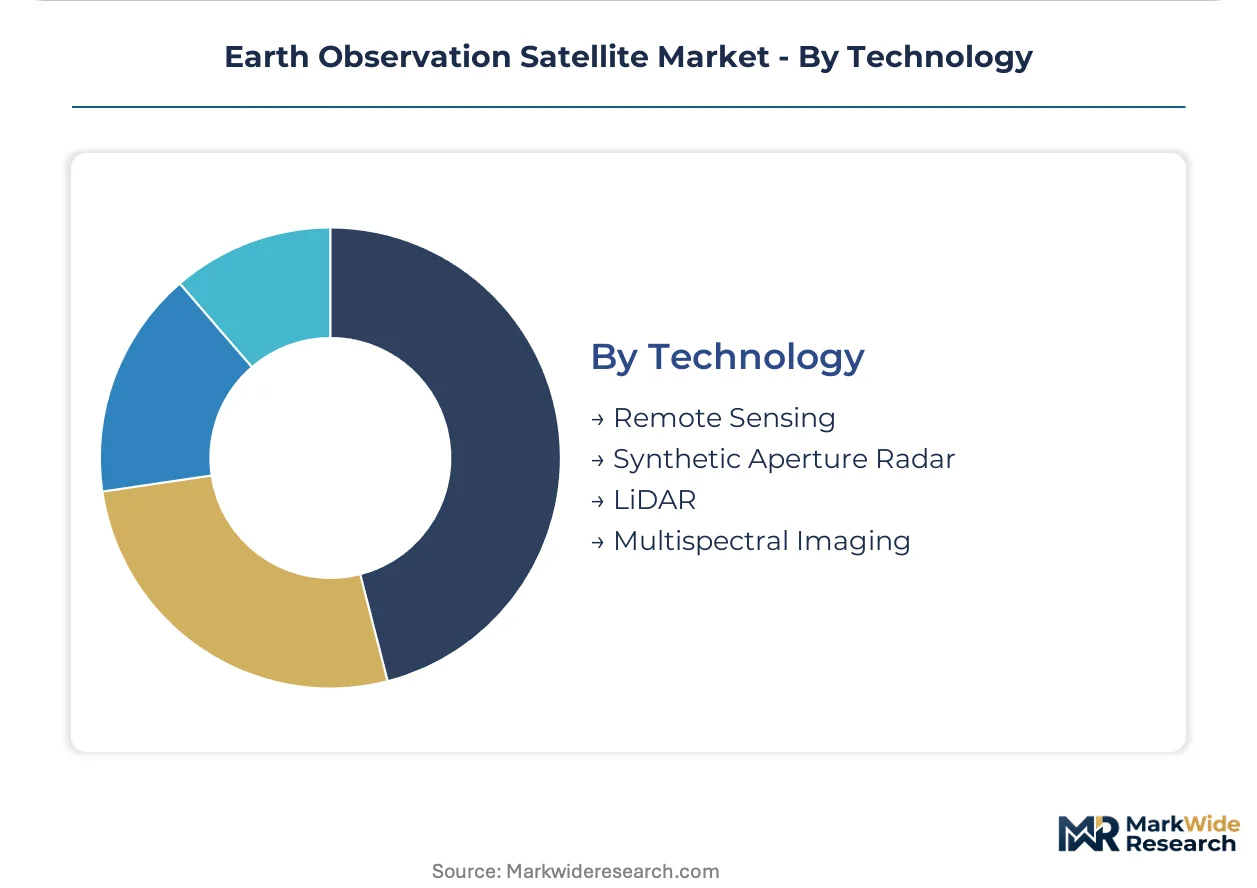
| Segmentation | Product Type: Imaging Satellites, Communication Satellites, Research Satellites, Navigation Satellites End User: Aerospace, Environmental Agencies, Government, Agriculture Deployment: Low Earth Orbit, Geostationary Orbit, Medium Earth Orbit, Sun-Synchronous Orbit Technology: Remote Sensing, Synthetic Aperture Radar, LiDAR, Multispectral Imaging |
| Companies Covered | Airbus Defence and Space, Maxar Technologies Inc., Planet Labs PBC, Lockheed Martin Corporation, L3Harris Technologies Inc., Northrop Grumman Corporation, ICEYE, BlackSky Technology Inc., Capella Space Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earth Observation Satellite Market Emerging Trajectories
Standardized satellite bus platforms and rideshare launch aggregation are compressing capital barriers for Earth observation entrants, enabling specialized sensor developers to field orbital assets without vertical integration into spacecraft manufacturing.
Software-defined radio payloads are collapsing the traditional hardware-locked architecture of Earth observation satellites. Operators reconfigure sensor parameters and communication protocols post-launch, extending mission utility without physical retrofit. Defense agencies and maritime surveillance providers adopt these flexible architectures fastest, demanding rapid frequency reallocation across contested spectrum environments. This capability compresses replacement cycles for legacy fixed-function satellites while fragmenting procurement across modular subsystem vendors.
EU AI Act transparency requirements for high-risk automated decision systems are reshaping geospatial analytics contracting. Satellite-derived intelligence products deployed for border surveillance and critical infrastructure classification must now document training data provenance and algorithmic uncertainty bounds. European institutional buyers delay procurement cycles to validate compliance, while non-EU operators capture near-term contracts from buyers seeking regulatory arbitrage. This friction accelerates segmentation between explainable-AI-native platforms and black-box legacy providers.
Subscription-based data access models displace traditional per-image licensing across agricultural and insurance verticals. Buyers demand API-integrated streaming feeds rather than archive downloads, forcing operators to restructure pricing around consumption tiers and integration support. This shift concentrates contract value with platforms offering direct enterprise system connectivity, marginalizing brokers and value-added resellers. North American precision agriculture cooperatives lead this transition, consolidating procurement through consortium agreements that demand guaranteed uptime service-level agreements.
Earth Observation Satellite Market Segmentation
Segmentation in the Earth observation satellite market reveals how sensor modality, orbital mechanics, and customer procurement patterns fragment revenue streams across specialized hardware configurations and mission profiles.
Product Type:
Mature optical platforms dominate current fleet deployments while emerging synthetic aperture radar architectures capture defense and all-weather maritime surveillance contracts.
- Imaging Satellites:Electro-optical and multispectral sensor platforms collect sub-meter to kilometer-scale spatial resolution data across visible, near-infrared, and shortwave infrared bands. Environmental agencies in the United States and the European Union anchor procurement for agricultural yield forecasting and disaster response monitoring, though cloud cover constraints limit temporal reliability in tropical zones.
- Communication Satellites:Data relay and command-link spacecraft enable real-time downlink from distributed sensor constellations to ground stations. Defense ministries prioritize these assets for tactical intelligence dissemination, driving demand for high-bandwidth Ka-band and optical laser cross-links that bypass radio frequency congestion.
- Research Satellites:Scientific mission platforms carry experimental payloads for atmospheric chemistry and climate modeling.
- Navigation Satellites:Precise positioning infrastructure supports georeferencing accuracy for commercial imagery products.
Imaging satellites handle the majority of throughput; synthetic aperture radar-enabled communication relay platforms are expanding most quickly on share.
End User:
Procurement authority concentrates in sovereign institutional buyers while commercial agriculture and insurance verticals emerge as consumption growth vectors.
- Government:National security agencies and civilian ministries fund sovereign constellation development for signals intelligence and infrastructure monitoring. China's Ministry of Industry and Information Technology directs state-owned enterprise deployment of Gaofen optical and Haiyang radar satellites, compressing revisit intervals that Western operators must match through commercial partnerships.
- Environmental Agencies:Regulatory bodies and intergovernmental organizations commission satellite-derived data for carbon accounting compliance and methane leak detection. The European Union Space Programme Agency's Copernicus free-data mandate subsidizes downstream application development across precision agriculture and reforestation verification verticals.
- Aerospace:Satellite manufacturers and launch providers consume engineering validation data.
- Agriculture:Cooperatives and agritech platforms subscribe to API-integrated vegetation index feeds for irrigation optimization.
Government contracts anchor revenue stability; environmental agency procurement is climbing the fastest as Green Deal compliance mandates harden.
Deployment:
Altitude selection trades sensor resolution against coverage swath and atmospheric drag, with ride-share economics reshaping orbital architecture preferences.
- Low Earth Orbit:Altitudes below 2,000 kilometers enable sub-meter optical resolution and reduced signal latency for real-time applications. Standardized CubeSat and smallsat bus platforms from suppliers in Germany and Japan compress unit economics, though FCC debris mitigation protocols require propellant reserves that shorten operational lifespans.
- Sun-Synchronous Orbit:Polar inclination at 98 degrees delivers consistent solar illumination angles for change detection algorithms. Agricultural insurers and commodity traders in North America anchor demand for these orbits that enable standardized vegetation index time series.
- Geostationary Orbit:Fixed positioning at 35,786 kilometers supports continuous regional weather monitoring.
- Medium Earth Orbit:Intermediate altitudes serve navigation augmentation and specialized communications relay.
Low Earth Orbit deployments handle the majority of new launch manifests; Sun-Synchronous Orbit demand is accelerating fastest among precision agriculture buyers.
Technology:
Sensor modality selection determines atmospheric penetration capability, spectral discrimination depth, and data processing architecture requirements.
- Synthetic Aperture Radar:Active microwave sensors transmit and receive radio waves to construct high-resolution imagery independent of solar illumination or cloud cover. Defense ministries in the United States and maritime surveillance operators across the Pacific Rim prioritize SAR for chokepoint monitoring and ground movement tracking, with all-weather reliability commanding premium pricing over optical alternatives.
- Remote Sensing:Passive electro-optical systems capture reflected solar radiation across panchromatic and multispectral bands. Commercial imagery markets in the European Union and North America standardize on these mature technologies, though ITAR-aligned export controls on sub-meter resolution fragment cross-border licensing.
- Multispectral Imaging:Narrowband spectral filters enable vegetation health and mineral identification applications.
- LiDAR:Laser ranging systems generate three-dimensional terrain models for forestry and infrastructure engineering.
Remote sensing platforms handle the majority of current data throughput; synthetic aperture radar is gaining share fastest as defense procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Defense ministries in the United States prioritize all-weather synthetic aperture radar capabilities, while European environmental agencies anchor procurement around Copernicus-subsidized optical data streams. China's state-directed constellation deployment compresses revisit intervals through sovereign launch cadence.
United States
The Department of Defense and National Reconnaissance Office fund classified and unclassified imaging satellite procurement through multi-year budget allocations. The FAA governs commercial launch licensing while NOAA regulates remote sensing spacecraft under the Land Remote Sensing Policy Act. Colorado's Front Range corridor hosts concentrated satellite manufacturing and ground station operations, with operators leveraging ride-share manifests from Cape Canaveral and Vandenberg.
China
The Ministry of Industry and Information Technology directs state-owned enterprise deployment of Gaofen optical and Haiyang radar satellites for territorial monitoring and maritime surveillance. MIIT and the National Space Administration jointly supervise domestic constellation licensing with explicit priority for sovereign data security. Beijing and Shanghai anchor integrated satellite design-to-launch ecosystems, with Xichang and Taiyuan launch centers supporting polar and inclined orbit deployments.
Germany
The Federal Office of Bundeswehr Equipment, Information Technology and In-Service Support procures SAR data for military reconnaissance and crisis response missions. ITAR-aligned export controls from allied jurisdictions constrain sub-meter imagery licensing, while national regulators enforce dual-use technology restrictions. Munich and Bremen concentrate satellite bus manufacturing and sensor integration capabilities, with OHB System AG and Airbus Defence and Space operations anchoring the industrial cluster.
India
ISRO's commercial arm Antrix offers polar orbit launch services at cost structures below Western alternatives, attracting Southeast Asian and European constellation operators seeking deployment diversification. The Space Activities Bill under parliamentary review will formalize private sector participation in satellite manufacturing and data services. Bengaluru's aerospace corridor hosts ISRO headquarters and emerging private launch vehicle developers, with Sriharikota's Satish Dhawan Space Centre handling the majority of domestic orbital insertions.
Japan
METI coordinates commercial space utilization policy while JAXA operates the Advanced Land Observing Satellite series for disaster management and environmental monitoring. The country's national space regulator enforces debris mitigation protocols aligned with international guidelines. Tokyo and Tsukuba concentrate Earth observation data processing and application development, with Mitsubishi Electric Corporation manufacturing optical and radar sensor platforms for domestic and export markets.
Earth Observation Satellite Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. Sovereign-backed aerospace conglomerates and defense contractors anchor high-resolution, high-reliability procurement channels for classified and critical infrastructure applications. Emerging commercial operators compete on temporal revisit density and API-integrated data delivery. Strategic archetypes include: vertically integrated prime contractors with captive launch access; pure-play satellite imagery platforms with software-defined payload architectures; and specialized synthetic aperture radar operators with all-weather data products. Competitive dynamics center on constellation refresh rates and direct government relationship depth.
Among defense-anchored primes, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify the vertically integrated archetype with established National Reconnaissance Office contracting relationships. On the commercial imagery vector, Planet Labs PBC and Maxar Technologies Inc. occupy positions spanning government and private sector demand pools. These named entities represent structural positioning rather than definitive market share claims, with actual competitive outcomes depending on launch cost trajectories and sovereign data localization mandates.
| Leading Market Players |
|---|
| Airbus Defence and Space |
| Maxar Technologies Inc. |
| Planet Labs PBC |
| Lockheed Martin Corporation |
| L3Harris Technologies Inc. |
| Northrop Grumman Corporation |
| ICEYE |
| BlackSky Technology Inc. |
| Capella Space Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in German and Japanese star tracker manufacturing is compressing component lead times and eroding supplier pricing power, while downstream satellite operators exploit buyer concentration to negotiate volume discounts on sensor payloads.
Pricing Analysis
Long-term offtake contracts anchor revenue stability for prime contractors serving the Department of Defense and National Reconnaissance Office, while spot procurement dominates commercial agriculture and insurance verticals seeking API-integrated data streams. Three-tier pricing structure across premium defense-grade SAR, standard commercial optical, and economy CubeSat imagery segments reflects certification level and revisit guarantee differentiation. Cost compression in the economy tier is intensifying because standardized bus platforms and rideshare launch aggregation collapse capital barriers for new entrants. Environmental agencies exhibit highest price sensitivity due to Copernicus free-data subsidy exposure, while defense ministries demonstrate lowest sensitivity given mission-critical all-weather requirements.
Supply Chain Analysis
Contract manufacturing concentration in Germany, Japan, and the United States holds capacity for high-precision reaction wheels, star trackers, and sensor integration. Raw material dependencies draw from gallium arsenide substrates, synthetic aperture radar transmit-receive modules, and radiation-hardened electronics. Single-source vulnerability in German star tracker supply exposes non-integrated operators to extended lead time risk. Distribution runs through direct government contracting channels for defense procurement and API-integrated subscription platforms for commercial verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable rocket economics constitute a high-growth disruption collapsing launch costs below historical floors, with the Federal Aviation Administration's streamlined commercial licensing creating regulatory tailwinds for constellation deployment acceleration.
For Market Incumbents: Build switching-cost moats through proprietary ground station networks and direct government security clearance relationships. Deepen backward integration into sensor payload manufacturing to reduce German and Japanese supplier dependency. Counter emerging SAR specialists by accelerating software-defined radio deployment for rapid frequency reallocation capability.
For New Entrants and Emerging Players: Pursue carbon credit verification mandates under European Union Green Deal compliance as the most penetrable near-term revenue pool. Target precision agriculture cooperatives in North America with API-integrated vegetation index subscriptions. Establish go-to-market positioning through guaranteed uptime service-level agreements that differentiate from archive-download incumbents.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because sovereign data security mandates and climate monitoring requirements create structurally guaranteed demand. Acquisition targets should emphasize software-defined payload architectures and explainable-AI-native analytics platforms compliant with EU AI Act transparency requirements. Monitor Federal Communications Commission debris mitigation rulemaking as the critical inflection signal for constellation density constraints and maneuvering cost impacts.
| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Aperture Radar Payload Expansion | Defense ministries prioritize all-weather maritime chokepoint monitoring regardless of cloud cover constraints. |
| Software-Defined Radio Architecture Deployment | Post-launch sensor reconfiguration extends mission utility without physical satellite retrofit requirements. |
| Hyperspectral-SAR Fusion Platform Development | Combined sensors enable mineral identification through vegetation canopy for agricultural insurance applications. |
| Polar Orbit Launch Partnership Diversification | ISRO's Antrix offers cost structures below Western alternatives for Southeast Asian constellation operators. |
| EU AI Act Compliance Certification Investment | Explainable-AI-native platforms capture contracts from buyers avoiding regulatory arbitrage delays. |
Methodological Framework
A spread of perspectives from satellite constellation operators, defense procurement officers, sensor payload engineers, and launch service providers converged on the working assumptions shaping this analysis. Primary interviews with Earth observation executives and ground station operations directors combined with secondary validation from Federal Aviation Administration launch licensing databases, National Oceanic and Atmospheric Administration remote sensing registrations, European Union Space Programme Agency Copernicus data policy documents, and Securities and Exchange Commission filings from publicly traded operators. Bottom-up unit economics modeling and top-down sovereign budget allocation triangulation anchored market sizing across sensor modality and orbital deployment segments.
Demand-supply-balance framing integrated constellation refresh rates, launch manifest availability, and defense procurement cycle timing across the projection horizon. Segmentation dimensions modeled include sensor technology, orbital altitude, end-user procurement authority, and sovereign data localization requirements. CAGRs derived from historical deployment trajectories and announced constellation expansion plans, with specific inputs from reusable rocket cost compression curves and European Green Deal compliance mandate timelines.
Sensitivities concentrate around Federal Communications Commission debris mitigation protocol revisions, European Union AI Act enforcement intensity, and China Ministry of Industry and Information Technology export restriction escalations. Quarterly review of launch slot availability at Cape Canaveral and Vandenberg Space Force Base, plus sovereign data security legislation progression in target markets, is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Germany Satellite Imagery Services Market
Satellite
Satellite Parts and Components Market
Satellite
Global Commercial Satellite Imagery Market
Satellite
Communication Satellite Launch Services Market
Satellite
United Arab Emirates Satellite-Based Earth Observation Market
Satellite
UK Satellite-Based Earth Observation Market
Satellite
Global Broadband Satellite Services Market
Satellite
United States Satellite Communications Market
Satellite
Nigeria Satellite-Based Earth Observation Market
Satellite
North America Satellite Launch Vehicle Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
Commercial Satellite Launch Service Market
Satellite
US Remote Sensing Technology Market
Satellite
Italy Satellite Communication Market
Satellite
Global Maritime Satellite Communication Market
Satellite
UAE Satellite Communication Market