
 Broadband Satellite System Market | 2026-2036
Broadband Satellite System Market Size, Share, and Industry Trends Forecast 2026-2036
Broadband Satellite System Market Outlook
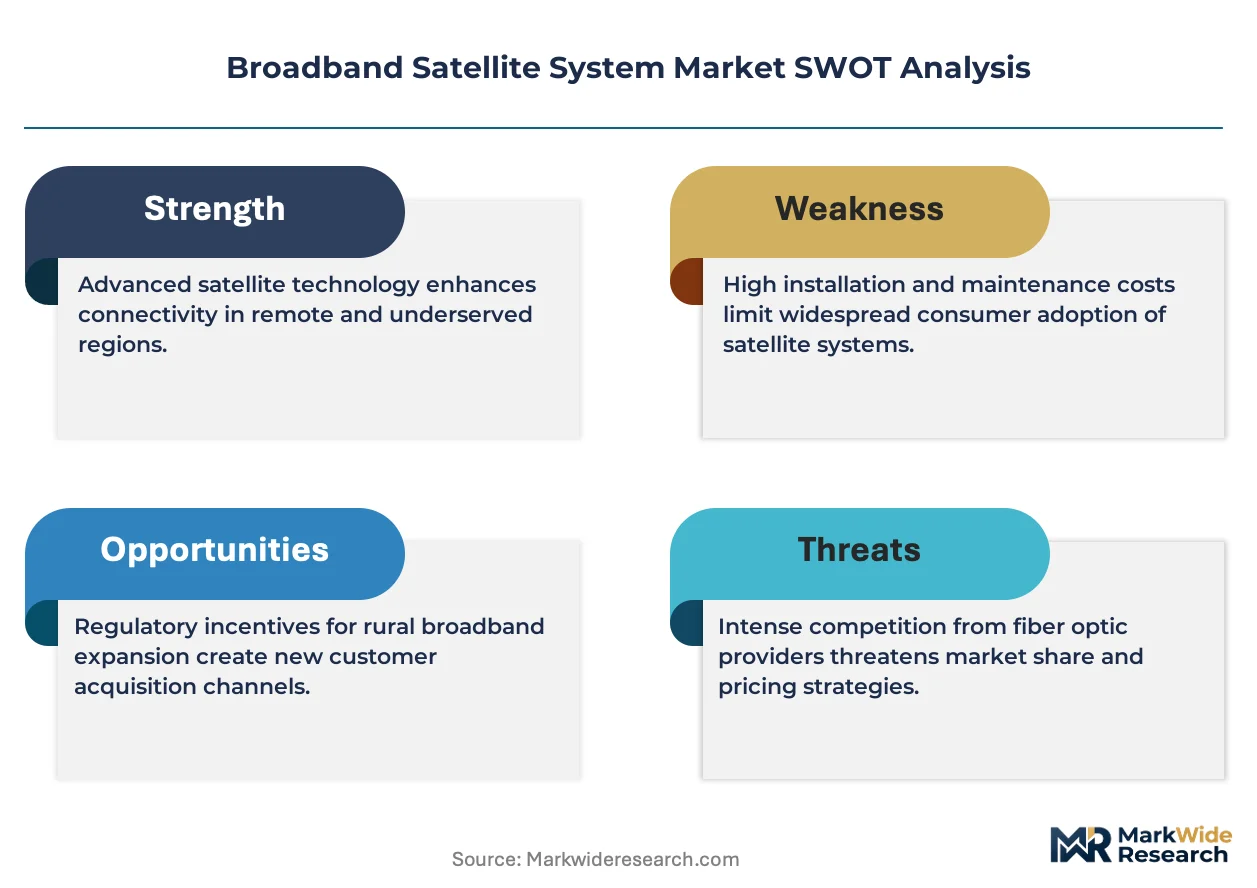
Project finance tied to constellation deployment is narrowing the competitive field to capital-rich operators. SpaceX leverages its vertically integrated launch infrastructure to sustain rapid satellite replenishment. Viasat anchors its position through high-throughput geostationary capacity serving enterprise and government clients. Hughes Network Systems competes via established ground equipment manufacturing and managed service platforms.
Broadband satellite systems deliver high-speed data transmission through constellations of orbiting transponders operating across Ku, Ka, and V-band frequencies, with latency profiles determined by orbital altitude. These systems bridge connectivity gaps where terrestrial fiber and cellular infrastructure prove uneconomical, serving maritime vessels, aircraft, remote industrial sites, and underserved residential zones. Low Earth Orbit technology leads deployment velocity due to its sub-50 millisecond latency advantage over geostationary alternatives. Enterprise Solutions commands premium pricing through service-level agreements and customized bandwidth allocation. Military Communications represents a concentrated margin pool driven by sovereign resilience requirements and encrypted waveform specifications.
The FCC governs spectrum allocation and orbital debris mitigation standards for US operators, while the ITU coordinates international frequency registration to prevent cross-border interference. The EU's Space Traffic Management initiative and proposed constellation licensing framework will reshape market access for non-European operators seeking European coverage. Stakeholders must monitor spectrum auction outcomes and debris compliance deadlines as gatekeepers for constellation authorization.
Market Dynamics
Low Earth Orbit constellation density is compressing latency benchmarks and forcing geostationary operators to reposition capacity toward high-margin enterprise verticals or risk price erosion in consumer broadband.
Growth Catalysts
- FCC streamlined licensing:The FCC's accelerated approval pathways for non-geostationary orbit systems compress deployment timelines from years to months for qualified operators.
- Maritime fleet digitization:Container shipping lines and offshore energy operators mandate real-time navigation, predictive maintenance, and crew connectivity at sea.
- Ka-band spectrum expansion:Higher frequency allocations enable multi-gigabit throughput that supports 4K video streaming and cloud workloads in remote locations.
Market Restraints
- Launch capacity bottlenecks:Limited heavy-lift vehicle availability constrains constellation refresh rates and orbital plane population schedules.
- Space debris compliance:FCC orbital debris mitigation rules mandate active de-orbit plans and collision avoidance systems that add engineering overhead.
- Terrestrial fiber substitution:Government-subsidized rural fiber rollouts in the United States and parts of Europe erode addressable markets for satellite residential broadband.
Strategic Opportunities
- Defense sovereign resilience:Military Communications procurement prioritizes encrypted, anti-jam waveforms and dedicated military satellite capacity immune to commercial congestion.
- In-flight connectivity expansion:Airlines retrofit narrow-body fleets with electronically steered antennas to monetize passenger broadband and operational data links.
- ITU coordination harmonization:Improved international frequency registration processes reduce cross-border interference disputes and accelerate multi-territory service launches.
Industry Challenges
- RF engineer scarcity:Specialized expertise in phased array antenna design and satellite modem firmware commands premium compensation and extends hiring cycles.
- Ground segment capex intensity:Gateway earth stations, user terminals, and network operations centers require sustained capital deployment before revenue materializes.
- Legacy system interoperability:Enterprise clients demand seamless handoff between satellite and terrestrial networks, complicating protocol standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Broadband Satellite System Market |
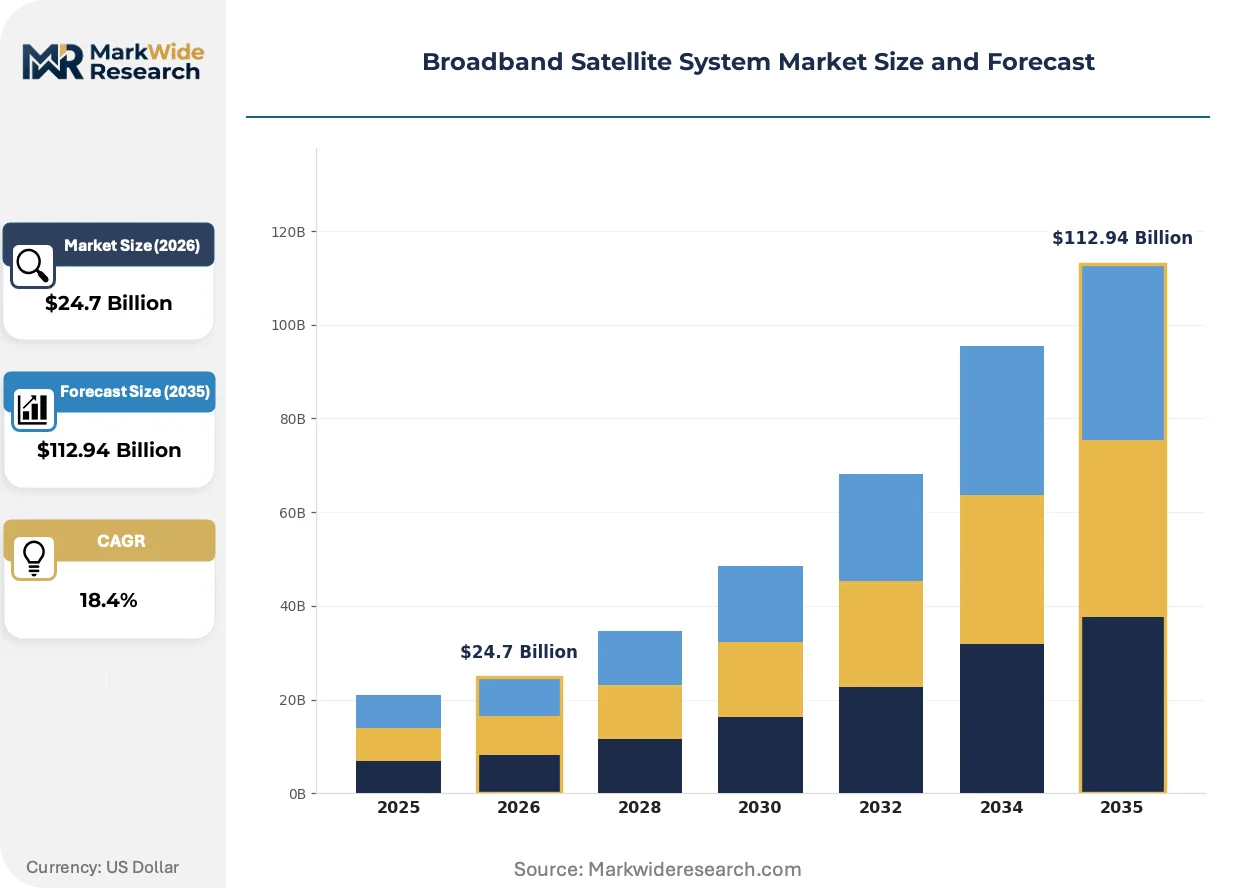
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $112.94 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consumer Internet, Enterprise Solutions, Military Communications, IoT Connectivity Technology: Geostationary, Low Earth Orbit, Medium Earth Orbit, Hybrid Systems Application: Residential, Maritime, Aviation, Emergency Services End User: Aerospace, Telecommunications, Military, Agriculture |
| Companies Covered | SpaceX (Starlink), Viasat, Hughes Network Systems, EchoStar Corporation, SES, Eutelsat Communications, Amazon (Project Kuiper), Telesat, OneWeb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Broadband Satellite System Market Strategic Shifts
Software-defined payload architectures and optical inter-satellite links are redefining throughput economics, while regulatory pressure on spectrum efficiency and debris mitigation accelerates hardware refresh cycles across operator fleets.
Electronically steered flat-panel antennas are digitizing terminal economics by eliminating mechanical gimbals and reducing unit costs for mobility applications. Maritime and aviation integrators are adopting these systems for phased fleet upgrades. The technology is digitizing procurement patterns by enabling volume orders that match automotive-scale manufacturing rather than bespoke aerospace sourcing.
The EU Space Traffic Management initiative is imposing collision avoidance and end-of-life disposal mandates on constellation operators seeking European coverage. This regulatory architecture elevates compliance costs for non-European entrants while creating certification advantages for operators with pre-positioned debris mitigation capabilities. Commercial broadband providers with existing STM-aligned operations are capturing preferential market access in EU member states.
Enterprise buyers are consolidating vendor relationships and demanding managed service contracts with guaranteed latency and uptime rather than raw bandwidth leases. Systems integrators and maritime fleet operators are displacing direct satellite operator contracts with layered service agreements. This concentration is most pronounced in United States defense contracting, where prime contractors bundle satellite capacity into broader communications infrastructure awards.
Broadband Satellite System Market Segmentation
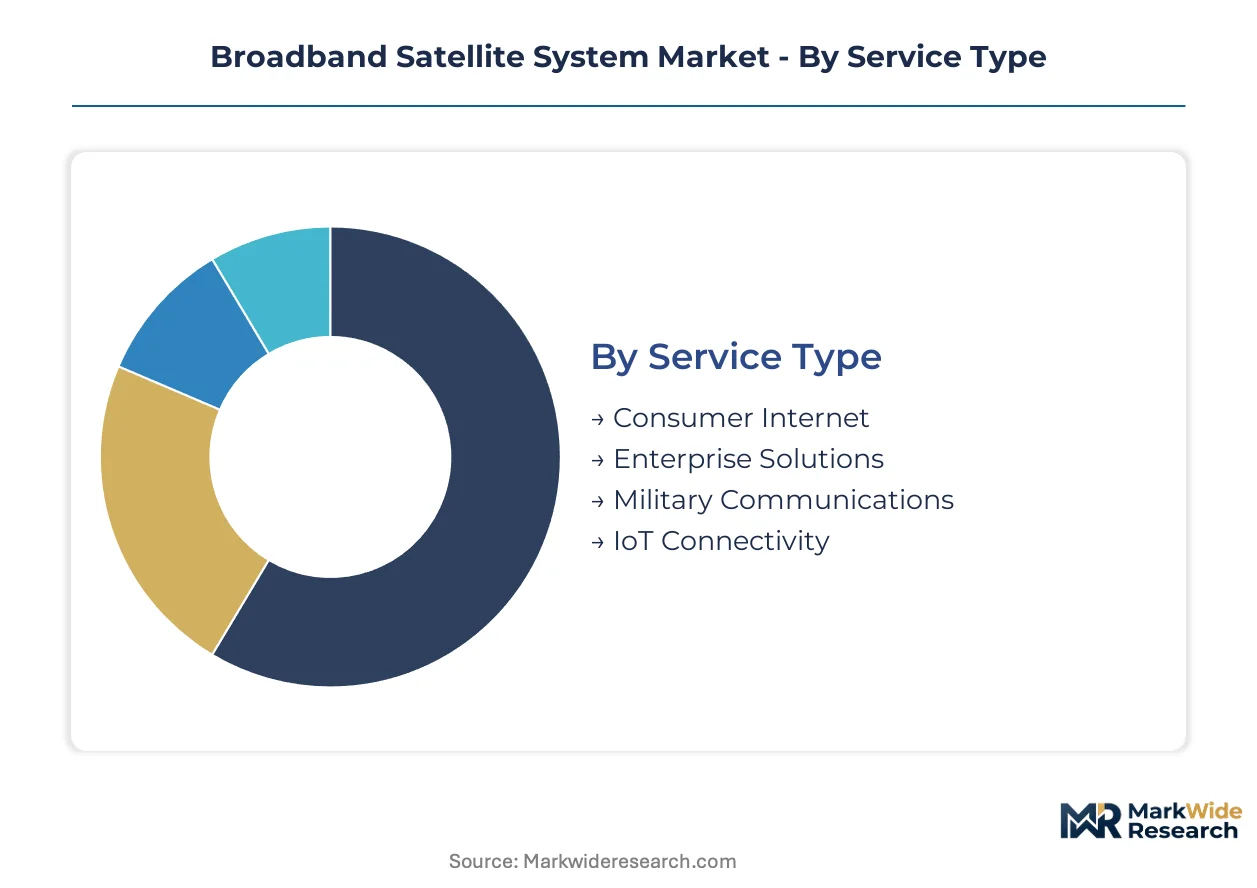
Broadband satellite systems serve radically different performance requirements across consumer streaming, maritime navigation, and encrypted defense networks. Segmentation reveals how orbital altitude, service architecture, and end-user security specifications determine pricing power and capital intensity for operators.
Service Type:
Use cases span from mass-market residential broadband to hardened military waveforms with diverging margin structures and contract terms.
- Consumer Internet:Mass-market residential broadband delivered via Ku and Ka-band spot beams targets underserved rural households and remote communities. Demand concentrates in the United States where FCC subsidies and digital equity mandates accelerate subscriber acquisition in rural broadband gaps.
- Enterprise Solutions:Customized bandwidth allocation with service-level agreements serves maritime fleets, energy extraction sites, and financial trading networks requiring guaranteed uptime. Energy majors in the Gulf of Mexico and North Sea anchor procurement volumes through multi-year managed service contracts with latency specifications below 100 milliseconds.
- Military Communications:Encrypted anti-jam waveforms on dedicated military satellite capacity support sovereign resilience requirements and tactical battlefield networks.
- IoT Connectivity:Narrowband machine-to-machine links enable predictive maintenance, asset tracking, and environmental monitoring across distributed industrial infrastructure.
Established volume favors Consumer Internet; emerging adoption favors Enterprise Solutions.
Technology:
Orbital altitude determines latency benchmarks, coverage economics, and constellation replacement schedules.
- Geostationary:Fixed orbital position at 35,786 kilometers enables persistent regional coverage with three-satellite global reach and mature ground infrastructure. Broadcasters and government clients in equatorial regions sustain demand despite 500+ millisecond latency limitations.
- Low Earth Orbit:Constellations orbiting below 2,000 kilometers deliver sub-50 millisecond latency through dense satellite meshes with inter-satellite optical links. Maritime shipping operators and low-latency financial traders in the United States and European port cities drive fleet expansion requirements.
- Medium Earth Orbit:Intermediate altitude constellations balance coverage footprint against latency performance for regional broadband services.
- Hybrid Systems:Integrated architectures combining multiple orbital regimes optimize cost and performance across diverse application requirements.
Geostationary systems retain installed base advantages; Low Earth Orbit configurations are climbing the fastest on deployment velocity.
Application:
Vertical-specific connectivity requirements shape terminal specifications, regulatory compliance, and service pricing tiers.
- Residential:Fixed broadband substitution targets households beyond terrestrial fiber economics with self-install terminals and volume pricing structures. Rural counties across the United States midwest and mountain west sustain subscriber growth where USDA ReConnect programs lag deployment timelines.
- Maritime:Stabilized antenna systems deliver continuous connectivity across vessel motion profiles for navigation, cargo monitoring, and crew welfare applications. Container lines headquartered in Denmark and Singapore mandate fleet-wide retrofits as competitive standards for seafarer retention.
- Aviation:Airborne terminals with electronic beam steering enable passenger broadband and cockpit operational data links during flight phases.
- Emergency Services:Rapidly deployable satellite terminals restore communications infrastructure following natural disasters and network outages.
Residential applications dominate subscriber counts; Maritime generates premium pricing per terminal.
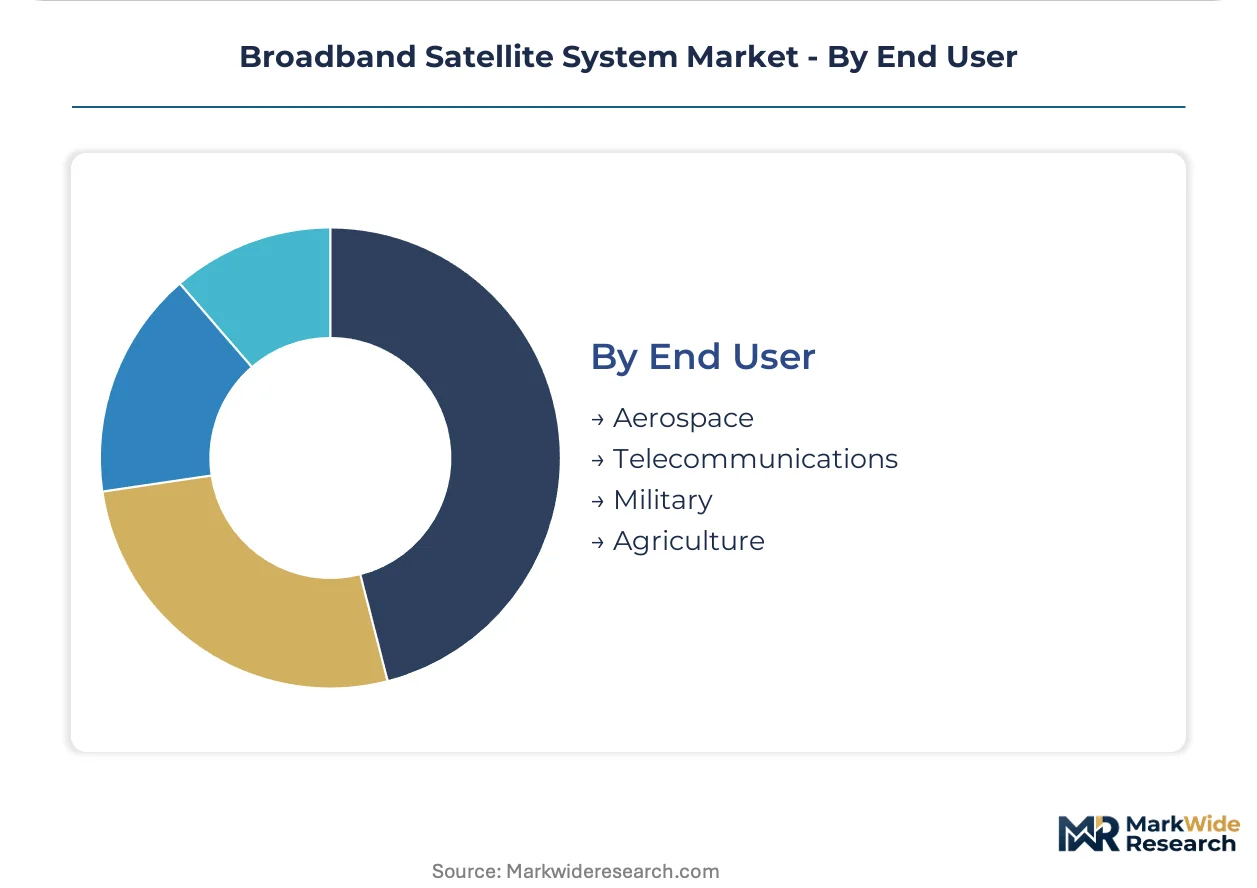
End User:
Procurement sophistication and security certification requirements segment the customer base across commercial and sovereign buyers.
- Aerospace:Satellite manufacturers and launch service providers consume capacity for telemetry, tracking, and command functions during mission operations.
- Telecommunications:Mobile network operators lease satellite backhaul for remote cell towers and emergency network restoration capabilities.
- Military:Defense agencies and intelligence services procure dedicated capacity with anti-jam protections and nuclear-hardened command infrastructure.
- Agriculture:Precision farming operations deploy connected sensors and autonomous machinery across extensive land holdings with limited cellular coverage.
Telecommunications delivers scale volume; Military commands margin premiums through security specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC licensing reforms and defense procurement contracts are concentrating satellite operator investment in the United States, while the EU Space Traffic Management initiative and maritime digitization mandates in Northern Europe reshape competitive access across Atlantic markets.
United States
Rural broadband subsidy programs and Pentagon communications contracts drive constellation deployment velocity. The FCC's streamlined non-geostationary orbit approval pathways compress licensing timelines for qualified applicants. Seattle-area launch infrastructure and California-based satellite manufacturing clusters anchor domestic supply chain concentration.
Germany
Industrial automation networks and North Sea offshore energy operations demand low-latency maritime connectivity. The EU Space Traffic Management initiative imposes collision avoidance and end-of-life disposal mandates on operators seeking European coverage. Hamburg and Bremerhaven port authorities mandate fleet-wide satellite retrofits for container lines calling at German terminals.
United Kingdom
Financial trading networks and defense intelligence procurement prioritize sub-50 millisecond latency specifications. The UK Space Agency coordinates national frequency registration with ITU protocols to prevent cross-border interference. London and Edinburgh host satellite operator headquarters serving European enterprise and government clients.
France
Overseas territory connectivity requirements and military sovereign resilience programs sustain geostationary capacity demand. The national spectrum regulator enforces debris mitigation compliance deadlines as a condition for orbital authorization. Toulouse aerospace clusters concentrate satellite manufacturing and ground segment engineering expertise.
Japan
Remote island broadband gaps and maritime shipping lane digitization drive Ka-band terminal adoption. METI coordinates national space traffic management standards aligned with international debris mitigation frameworks. Tokyo and Yokohama harbor districts anchor maritime integrator consolidation for Asia-Pacific fleet deployments.
Broadband Satellite System Market Competitive Environment
Channel-controlling players compete with product-specialist players across vertically integrated launch infrastructure, high-throughput geostationary capacity, and managed service platform tiers. The field narrows to capital-rich operators capable of sustaining multi-billion dollar constellation refresh cycles. Three archetypes dominate: launch-integrated constellation deployers, geostationary capacity incumbents, and ground equipment manufacturers with service layer extensions. Competitive moves concentrate on vertical integration into launch infrastructure and strategic partnerships for maritime and aviation distribution.
Among vertically integrated operators, SpaceX and Amazon exemplify the launch-captive archetype through control over satellite production and orbital deployment cadence. Viasat occupies a position within the geostationary tier, anchoring enterprise and government demand through high-throughput capacity over fixed orbital positions. These three represent distinct strategic postures—rapid constellation scaling, incumbent capacity monetization, and emerging challenger deployment—without prescribing specific market share or operational outcomes.
| Leading Market Players |
|---|
| SpaceX (Starlink) |
| Viasat |
| Hughes Network Systems |
| EchoStar Corporation |
| SES |
| Eutelsat Communications |
| Amazon (Project Kuiper) |
| Telesat |
| OneWeb |
| Others |
Value Chain & Pricing Dynamics
Launch capacity undercapacity in the United States is compressing constellation deployment schedules and elevating pricing power for vertically integrated operators with captive heavy-lift access. This utilization squeeze feeds back into supplier consolidation as capital-constrained players defer replenishment cycles or exit orbital plane population entirely.
Pricing Analysis
Orbital altitude tier creates the primary spread between sub-50 millisecond Low Earth Orbit premiums and discounted geostationary residential broadband. Subscription-based recurring revenue dominates, with Enterprise Solutions commanding service-level agreement premiums while Consumer Internet faces compression from subsidized terrestrial fiber alternatives. Maritime and defense buyers exhibit lowest price sensitivity due to mission-critical latency specifications and sovereign resilience mandates; residential rural subscribers face highest churn risk when USDA ReConnect programs accelerate terrestrial deployment.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk profiles for phased array antenna components and satellite modem chipsets. Manufacturing concentrates in California, Washington, and Toulouse for satellite bus assembly, with critical rare earth element dependencies drawing from Chinese and Australian extraction operations. Single-source vulnerability in heavy-lift launch services anchors risk concentration, while distribution runs through gateway earth station operators and maritime integrators serving fleet-wide retrofit contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability standards between Low Earth Orbit constellations and legacy geostationary networks are creating platform-economics inflection, with enterprise buyers consolidating vendor relationships around seamless handoff capabilities.
For Market Incumbents: Insulate enterprise margin pools by accelerating managed service contract penetration with guaranteed latency specifications. Deepen backward integration into optical inter-satellite link manufacturing to reduce dependency on single-source photonic component suppliers. Position against emerging launch-captive challengers through pre-positioned debris mitigation certification aligned with EU Space Traffic Management mandates. For New Entrants and Emerging Players: Build out maritime fleet digitization verticals where container shipping lines mandate crew welfare connectivity as competitive retention standards. Target North Sea and Gulf of Mexico energy extraction sites with hybrid orbital solutions combining Low Earth Orbit latency with geostationary persistence. Pursue channel partnerships with established maritime integrators rather than direct operator competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ground segment manufacturing as flat-panel antenna volumes scale toward automotive-tier production economics. Long-term viability favors operators with pre-committed launch manifests and spectrum coordination precedence. Acquisition targets should demonstrate ITU filing priority dates and active de-orbit plan compliance; monitor FCC streamlined licensing approval velocity as inflection signal for competitive field narrowing.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Inter-Satellite Link Deployment | Multi-gigabit throughput enables cloud workload migration for maritime and energy extraction clients. |
| Managed Service Contract Consolidation | Systems integrators displace direct operator relationships through layered service agreements bundling satellite and terrestrial capacity. |
| EU Space Traffic Management Certification | Pre-positioned debris mitigation capabilities create preferential market access for European coverage authorization. |
| Flat-Panel Antenna Manufacturing Scale-Up | Automotive-tier production economics reduce terminal costs for aviation and maritime mobility applications. |
| Defense Sovereign Resilience Procurement | Encrypted anti-jam waveforms on dedicated military capacity command premium pricing through security specifications. |
Study Parameters
Desk research of FCC licensing databases, ITU frequency registration filings, and satellite operator technical specifications preceded structured interviews with constellation program managers, maritime fleet operations directors, defense procurement officers, and ground segment engineering leads. Primary intelligence combined with secondary validation through SEC filings, customs records for satellite component trade flows, and EIA energy extraction site connectivity surveys. Bottom-up subscriber and terminal shipment estimates triangulated against top-down constellation capacity announcements across the analysis window.
Fixed assumptions held launch cost trajectories and spectrum allocation timelines within observed regulatory patterns while varying constellation deployment velocity and maritime fleet retrofit adoption curves. Segmentation modeling spanned orbital altitude tier, service architecture type, end-use vertical, and geographic regulatory cluster. CAGRs derived from fitted adoption curves calibrated to historical satellite broadband penetration patterns and cross-referenced against defense procurement budget authorization trends.
The forecast holds incumbent behavior within observed patterns; aggressive constellation scaling by capital-rich challengers or accelerated terrestrial fiber substitution would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Global Commercial Satellite Imagery Market
Satellite
India Satellite-Based Earth Observation Market
Satellite
Satellite GPS Receivers Market
Satellite
Satellite Communication Equipment Market
Satellite
China Satellite Communication Market
Satellite
Airborne UHF-Band SATCOM Market
Satellite
Satellite Internet Market
Satellite
Europe Military Satellite Market
Satellite
Europe Satellite Manufacturing Market
Satellite
Spain Satellite-Based Earth Observation Market
Satellite
4K Satellite Broadcasting Market
Satellite
Germany Satellite Communications Market
Satellite
All-Electric Satellites Market
Satellite
Satellite Gateway Market
Satellite
ASEAN Satellite Imagery Services Market
Satellite
Argentina Satellite Imagery Services Market