
 United States Chemical Logistics Market | 2026-2036
United States Chemical Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Chemical Logistics Market Insights
Buyer concentration among specialty chemical producers is broadening as mid-sized manufacturers in Texas and Ohio diversify their logistics partnerships beyond captive fleets. C.H. Robinson leverages its digital freight platform to match volatile chemical shipping schedules with qualified carrier networks. Kenan Advantage Group sustains dominant tank truck capacity across the Gulf Coast and Midwest corridors. Odyssey Logistics differentiates through integrated bulk liquid and intermodal solutions serving pharmaceutical and agricultural chemical clients.
United States chemical logistics encompasses the specialized movement, storage, and handling of hazardous and non-hazardous chemical products, requiring temperature-controlled vessels, corrosion-resistant containers, and DOT-certified drivers with HAZMAT endorsements. Its primary purpose is maintaining product integrity and regulatory compliance across multi-modal supply chains from refinery or plant gate to end-use manufacturing facilities. Transportation services command the largest value pool due to fuel surcharges, driver scarcity, and specialized equipment requirements, while warehousing segments face margin pressure from EPA secondary containment mandates. Freight forwarding is gaining share as chemical exporters navigate complex customs and dangerous goods documentation for cross-border trade.
FDA, EPA, and DOT regulations govern chemical logistics through overlapping jurisdictions covering food-contact chemical purity, environmental release prevention, and hazardous materials transport safety. DOT PHMSA rules on rail tank car specifications and EPA Risk Management Plan requirements for bulk storage facilities directly shape capital allocation toward compliant infrastructure. Stakeholders must monitor proposed FERC pipeline safety amendments and state-level California Air Resources Board trucking emissions standards that could reroute cross-country chemical flows.
Market Dynamics
EPA PHMSA rail tank car specifications and secondary containment mandates are forcing Gulf Coast chemical producers to reconfigure their logistics networks around compliant infrastructure investments.
Growth Catalysts
- Specialty chemical demand in Texas and Louisiana:Petrochemical corridor expansions are generating sustained volume for temperature-controlled bulk liquid transport and specialized warehousing.
- DOT HAZMAT endorsement requirements:Regulatory certification barriers limit carrier entry, protecting qualified logistics providers with established safety protocols and trained driver pools.
- Intermodal infrastructure at Houston and New Orleans ports:Deepwater access and pipeline connectivity enable efficient transfer between tanker, rail, and truck modes for agricultural and pharmaceutical chemical flows.
Market Restraints
- Driver scarcity and wage inflation:DOT-certified HAZMAT drivers command premium compensation, compressing margins on standard chemical freight lanes.
- Equipment specialization costs:Corrosion-resistant tank trailers and temperature-controlled vessels require capital outlays that deter small carrier expansion.
- EPA Risk Management Plan compliance:Bulk storage facility upgrades for secondary containment and release prevention absorb logistics provider cash flow.
Strategic Opportunities
- Ohio River Valley chemical manufacturing:Mid-sized specialty producers in Ohio and Kentucky are diversifying beyond captive fleets, opening third-party logistics partnerships.
- Digital freight matching platforms:Real-time carrier qualification and scheduling optimization reduce empty miles for volatile chemical shipping patterns.
- California Air Resources Board trucking standards:Anticipated emissions regulations create first-mover advantage for fleets investing in compliant equipment ahead of mandate enforcement.
Industry Challenges
- HAZMAT driver training pipeline:The certification timeline for DOT endorsements and specialized handling protocols extends recruitment cycles during peak demand periods.
- Legacy warehouse management system integration:EPA-mandated inventory tracking and release monitoring require costly upgrades to older storage facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Chemical Logistics Market |
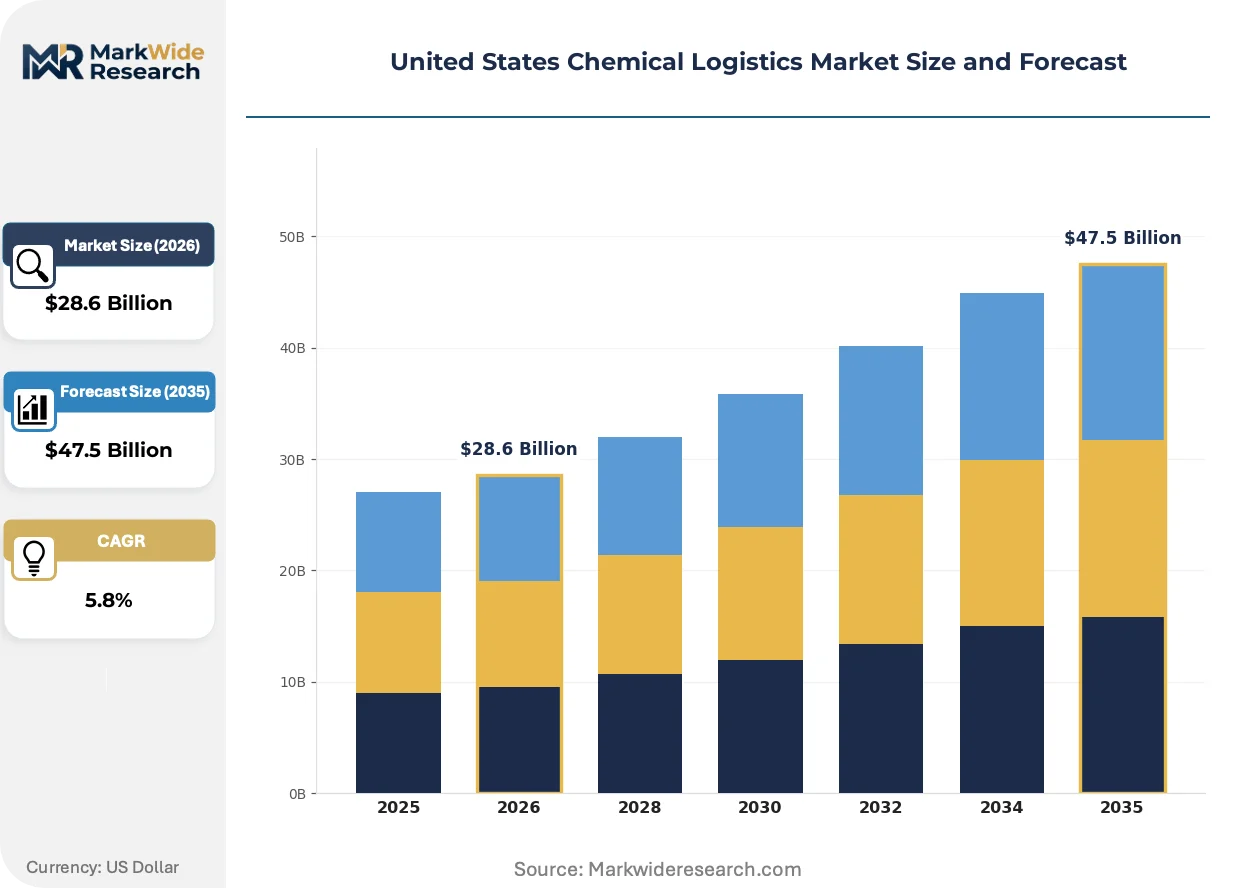
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Solvents, Polymers, Resins, Industrial Chemicals Service Type: Transportation, Warehousing, Packaging, Freight Forwarding End User: Pharmaceuticals, Food & Beverage, Cosmetics, Agriculture Application: Manufacturing, Research & Development, Quality Control, Distribution |
| Companies Covered | Agility Logistics, Kenan Advantage Group, C.H. Robinson, Universal Logistics Holdings, Odyssey Logistics, BDP International, DHL, Evans Distribution Systems, Quantix Supply Chain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Chemical Logistics Market Trends and Innovations
Digital platforms and sensor technologies are compressing planning cycles and enabling real-time compliance verification across multi-modal chemical movements.
Telematics and IoT sensor networks is unifying visibility across tank truck, rail, and vessel assets. Specialty chemical manufacturers in agricultural and pharmaceutical segments are adopting these systems fastest. The technology is unifying previously siloed carrier networks into integrated compliance and tracking ecosystems that reduce detention penalties.
EPA secondary containment mandates for bulk storage facilities are accelerating capital deployment toward double-walled tanks and automated leak detection. Logistics providers face stepped-up inspection frequencies and documentation requirements. Agricultural chemical distributors in the Gulf Coast corridor are consolidating warehousing footprints to amortize compliance investments across higher throughput volumes.
Shippers are consolidating carrier relationships around integrated service bundles that combine transport, storage, and customs documentation. The spot market for chemical freight is losing share to contracted capacity arrangements with qualified HAZMAT providers. Pharmaceutical chemical importers at East Coast ports are driving this shift most aggressively due to FDA documentation complexity.
United States Chemical Logistics Market Segmentation
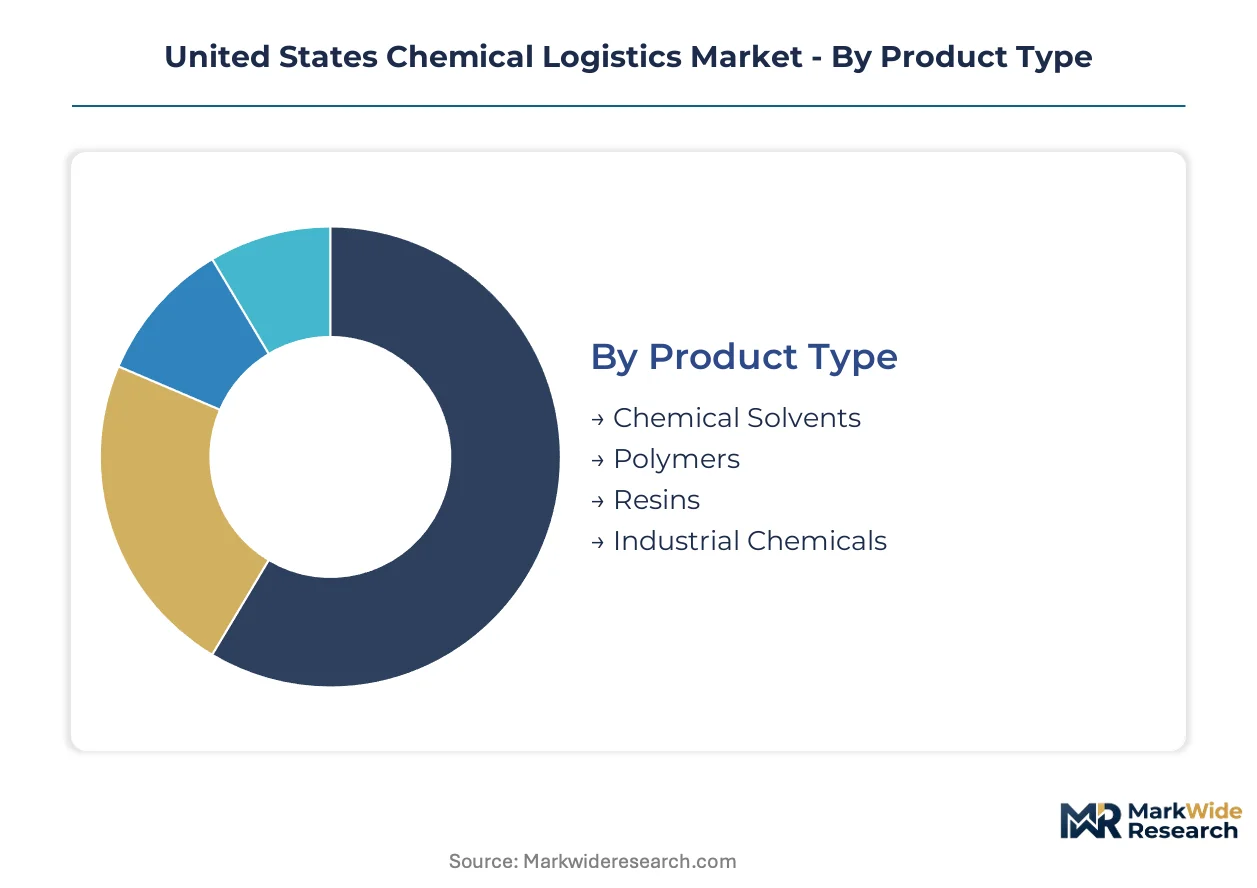
Segmentation in chemical logistics reveals how specialized infrastructure requirements and regulatory complexity fragment service provision across distinct product hazards, customer compliance needs, and operational modalities. Understanding these divisions clarifies where capital deployment concentrates and where margin differentiation emerges.
Product Type:
Supply concentration for hazardous and non-hazardous chemicals diverges sharply across the Gulf Coast petrochemical corridor and Midwest manufacturing belts.
- Chemical Solvents:Flammable liquid classifications require DOT-certified tank trucks with vapor recovery systems and grounded loading protocols. Demand clusters in Texas and Louisiana refineries serving pharmaceutical and coating manufacturers facing EPA air quality compliance deadlines.
- Polymers:Temperature-sensitive pellet and powder forms necessitate pneumatic conveying equipment and moisture-controlled silo storage. Ohio River Valley resin producers are expanding third-party logistics partnerships as captive fleet costs escalate.
- Resins:Viscous liquid and solid thermoset varieties demand heated tank trailers and specialized pumping infrastructure for high-viscosity discharge.
- Industrial Chemicals:Sulfuric acid, caustic soda, and chlorine derivatives require corrosion-resistant containers and secondary containment across all handling nodes.
Chemical solvents absorb the bulk of installed capacity; polymers are expanding most quickly.
Service Type:
Cost tier differentiation separates capital-intensive asset ownership from variable-cost brokerage and compliance services.
- Transportation:Tank truck, rail, and intermodal movements command premium pricing due to HAZMAT driver scarcity and specialized equipment requirements. Temperature-controlled bulk liquid transport sees sustained volume from Gulf Coast petrochemical expansions.
- Warehousing:EPA Risk Management Plan mandates for secondary containment and automated leak detection are absorbing logistics provider cash flow. Agricultural chemical distributors in Texas and Louisiana are consolidating footprints to amortize compliance investments.
- Packaging:UN-certified drums, intermediate bulk containers, and corrosion-resistant totes require DOT specification testing and serialization for hazardous materials tracking.
- Freight Forwarding:Customs documentation and dangerous goods certification for cross-border chemical trade are gaining share as exporters navigate complex multi-jurisdictional regulations.
Transportation claims the largest revenue pool; freight forwarding is climbing the fastest.
End User:
Application-driven compliance intensity varies dramatically across FDA-regulated, EPA-regulated, and agricultural chemical segments.
- Pharmaceuticals:FDA current Good Manufacturing Practice requirements govern temperature integrity, chain-of-custody documentation, and contamination prevention from API through finished dosage form distribution.
- Food & Beverage:Food-contact chemical purity standards under FDA and USDA jurisdictions require dedicated handling equipment and allergen segregation protocols.
- Cosmetics:Fragrance and preservative chemical logistics face moderate hazard classification with emphasis on batch traceability and shelf-life management.
- Agriculture:Fertilizer and pesticide movements concentrate seasonally, demanding surge capacity and EPA-compliant storage with groundwater protection measures.
Pharmaceuticals command premium service pricing; agriculture is gaining share fastest.
Application:
Volume concentration in manufacturing logistics contrasts with high-margin specialized services for quality control and R&D support.
- Manufacturing:High-volume feedstock delivery to chemical processors and downstream manufacturers sustains contracted tank truck and railcar networks across the Gulf Coast and Ohio River corridors.
- Research & Development:Small-batch, high-variety chemical movements for pilot-scale synthesis require flexible carrier qualification and rapid scheduling adaptation.
- Quality Control:Sampling logistics and analytical reference material distribution demand chain-of-custody documentation and temperature-validated transport.
- Distribution:Finished chemical product allocation to regional warehouses and direct customer delivery balances inventory carrying costs against service level requirements.
Manufacturing absorbs dominant volume share; research and development is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for chemical logistics concentrates in the Gulf Coast petrochemical corridor, where refinery expansions and specialty chemical manufacturing sustain high-volume throughput requirements.
Texas
Petrochemical corridor expansions near Houston and Beaumont generate sustained volume for temperature-controlled bulk liquid transport. EPA Risk Management Plan requirements for secondary containment shape capital allocation toward compliant warehousing infrastructure. The Port of Houston anchors intermodal chemical flows connecting tanker, rail, and truck networks serving agricultural and pharmaceutical clients.
Louisiana
Deepwater port access at New Orleans supports efficient transfer between vessel and land-based modes for fertilizer and industrial chemical movements. DOT PHMSA rail tank car specifications force infrastructure reconfiguration around compliant loading and storage facilities. Baton Rouge and Lake Charles industrial clusters absorb logistics provider investments in double-walled tanks and automated leak detection systems.
Ohio
Mid-sized specialty chemical producers in the Ohio River Valley diversify beyond captive fleets, opening third-party logistics partnerships. State-level environmental regulations align with federal EPA mandates for groundwater protection around bulk storage facilities. Cincinnati and Columbus manufacturing belts concentrate polymer and resin logistics demand requiring heated tank trailers and pneumatic conveying equipment.
California
Anticipated California Air Resources Board trucking emissions standards create first-mover advantage for fleets investing in compliant equipment ahead of mandate enforcement. FDA food-contact chemical purity requirements govern dedicated handling protocols for food and beverage sector logistics. Los Angeles and Long Beach port complexes handle pharmaceutical chemical imports requiring complex customs and dangerous goods documentation.
Kentucky
Agricultural chemical distribution concentrates seasonally, demanding surge capacity and EPA-compliant storage with groundwater protection measures. DOT HAZMAT endorsement requirements limit carrier entry, protecting qualified logistics providers with established safety protocols. Louisville and northern Kentucky industrial zones connect Ohio River chemical manufacturing to rail and interstate highway corridors.
United States Chemical Logistics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital freight matching and specialized HAZMAT certification services. The vendor base organizes around asset-heavy tank truck operators, technology-enabled freight brokers, and integrated intermodal specialists. Three archetypes dominate: Gulf Coast corridor incumbents with captive fleet scale, digital platforms optimizing volatile chemical scheduling, and pharmaceutical-focused compliance specialists. Competitive intensity centers on M&A consolidation of regional carriers and strategic partnerships linking warehousing with transport assets.
Among integrated service providers, C.H. Robinson exemplifies the digital freight platform archetype, while Kenan Advantage Group occupies a position within asset-heavy tank truck capacity. Odyssey Logistics represents the specialized intermodal tier serving bulk liquid and pharmaceutical chemical segments. These three anchors illustrate how competitive positioning fragments across technology-enabled brokerage, physical infrastructure ownership, and vertical compliance expertise.
| Leading Market Players |
|---|
| Agility Logistics |
| Kenan Advantage Group |
| C.H. Robinson |
| Universal Logistics Holdings |
| Odyssey Logistics |
| BDP International |
| DHL |
| Evans Distribution Systems |
| Quantix Supply Chain |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up tank truck operators have consolidated Gulf Coast corridor capacity, tightening pricing discipline among HAZMAT-qualified carriers while forcing captive fleet conversions toward outsourced third-party logistics partnerships.
Pricing Analysis
High-volume contract lanes absorb margin compression from driver wage inflation, while specialized pharmaceutical and agricultural chemical segments sustain premium pricing through FDA and EPA certification requirements. Price differentiation hinges on HAZMAT endorsement density and temperature-controlled equipment availability. Cost compression in standard industrial chemical transport is intensifying because qualified carrier scarcity limits competitive entry. Mid-sized specialty chemical producers in Ohio and Kentucky exhibit highest price sensitivity, whereas pharmaceutical importers at East Coast ports prioritize compliance reliability over rate negotiation.
Supply Chain Analysis
DOT HAZMAT certification and EPA Risk Management Plan compliance gate carrier participation, concentrating qualified capacity among established Gulf Coast and Midwest operators. Supply concentrates in Texas, Louisiana, and Ohio, with raw material flows drawing from regional refinery complexes, polymer production facilities, and agricultural chemical formulation plants. Single-source vulnerability runs through the certified driver pipeline, where training timelines extend recruitment cycles during seasonal demand surges. Distribution runs through intermodal hubs at Houston and New Orleans ports, connecting tanker, rail, and truck networks for agricultural and pharmaceutical chemical flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
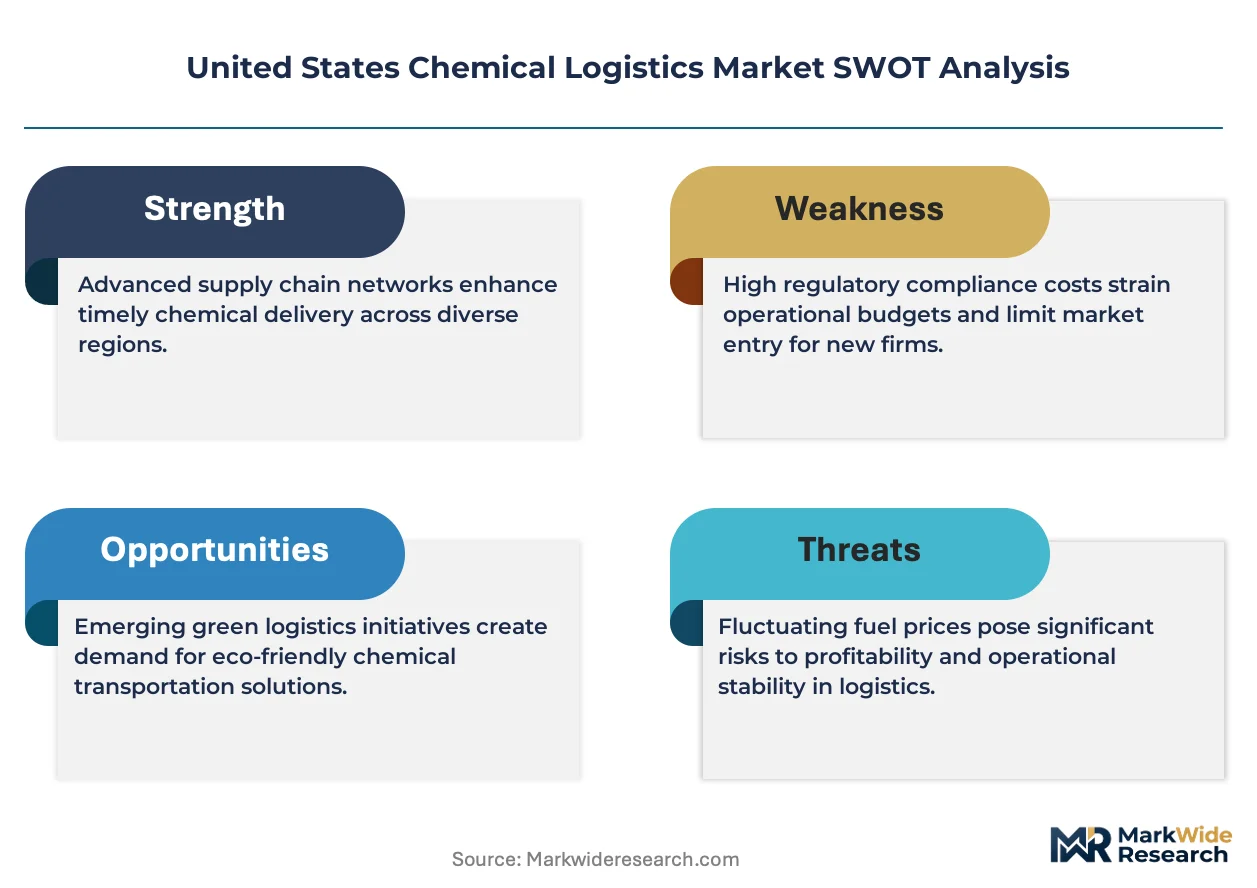
Chemical logistics functions as a consolidation play where EPA secondary containment mandates and driver certification barriers force sub-scale warehousing operators toward acquisition or exit.
For Market Incumbents: Cement Gulf Coast corridor dominance through backward integration into double-walled tank storage assets ahead of stepped-up EPA inspection frequencies. Acquire regional carriers in the Ohio River Valley to capture mid-sized specialty chemical producers diversifying beyond captive fleets, leveraging existing HAZMAT training infrastructure to compress integration timelines.
For New Entrants and Emerging Players: Digital freight matching platforms offer the lowest barrier route into volatile chemical scheduling optimization, bypassing capital-intensive equipment ownership. Target agricultural chemical distributors in Kentucky and Louisiana seeking surge capacity solutions, positioning around real-time carrier qualification and automated compliance documentation as the core go-to-market angle.
For Investors and Strategic Acquirers: Anticipated California Air Resources Board enforcement actions are the leading indicator that emissions-compliant fleet investments will separate viable platforms from stranded assets. Frame long-term viability around carriers with established pharmaceutical chemical expertise and intermodal infrastructure at deepwater ports. Watch for DOT PHMSA rail tank car specification amendments as the signal triggering accelerated infrastructure replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Double-walled tank installations at Baton Rouge and Lake Charles facilities address EPA secondary containment mandates. |
| Backward Integration | Captive warehousing assets reduce exposure to third-party storage compliance failures during peak seasonal demand. |
| Digital Platform Integration | Real-time carrier qualification compresses empty miles for volatile specialty chemical shipping schedules. |
| Long-term Supply Agreement | Contracted capacity arrangements with qualified HAZMAT providers displace spot market exposure for pharmaceutical clients. |
| Joint Venture | Port authority partnerships at Houston and New Orleans secure priority intermodal transfer capacity for bulk liquid flows. |
Research Methodology
Independent corroboration across logistics procurement directors, DOT-certified fleet operators, EPA compliance officers, and specialty chemical plant managers underwrites the qualitative findings. Primary interviews with transportation directors at agricultural chemical distributors and pharmaceutical import operations combined with secondary validation from SEC 10-K filings, American Chemistry Council trade data, and FERC pipeline safety disclosures. Bottom-up carrier capacity assessments and top-down petrochemical production volume estimates triangulate market sizing.
Rate-of-change decomposition across transportation, warehousing, and freight forwarding segments isolates volume drivers from pricing effects throughout the forecast period. Segmentation dimensions modeled include product hazard classification, service modality, end-use regulatory intensity, and regional production hub concentration. CAGRs derive from historical throughput trends adjusted for infrastructure constraint assumptions and regulatory implementation timelines. Forecast inputs incorporate DOT HAZMAT endorsement pipeline data and EPA Risk Management Plan compliance cost curves.
The model holds under stable regulatory enforcement intensity; deviation in EPA inspection frequency acceleration or DOT driver certification backlogs would shift capacity utilization assumptions. Forecasts reflect documented assumptions regarding petrochemical corridor expansion timelines and intermodal infrastructure completion schedules. A model refresh is warranted upon material change in California Air Resources Board mandate enforcement dates or FERC pipeline safety amendment finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Germany Freight Forwarding Market
Logistics and Shipping
Sweden Courier, Express, and Parcel Market
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
Air Freight Software Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
Warehousing and Distribution Logistics Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
Control Towers Market
Logistics and Shipping
Spain Pharmaceutical Logistics Market
Logistics and Shipping
Tanker Shipping Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
Europe Chemical Logistics Market