
 Indonesia Cold Chain Logistics Market | 2026-2036
Indonesia Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Cold Chain Logistics Market Insights
A shift from fragmented in-house fleet ownership toward outsourced third-party cold-chain specialists is realigning procurement patterns across Indonesian food and pharmaceutical supply chains. Samudera Logistics leverages its integrated port-to-warehouse network to dominate maritime temperature-controlled corridors. PT YCH Indonesia anchors pharmaceutical distribution through FDA-equivalent compliant warehousing in Greater Jakarta. DHL Supply Chain Indonesia extends multinational operating protocols into Indonesia's emerging tier-two cities.
Cold chain logistics encompasses the temperature-controlled storage and distribution infrastructure maintaining product integrity from origin to consumption, typically operating between minus 25 degrees Celsius and plus 8 degrees Celsius depending on cargo class, with insulated vehicles, refrigerated warehouses, and real-time environmental monitoring forming the operational backbone. The primary purpose centers on preventing spoilage, preserving nutritional value, and ensuring pharmaceutical efficacy across extended tropical supply routes. Seafood and dairy product types command premium infrastructure investment due to stringent temperature bands and short shelf windows. Road transport delivery mode absorbs the majority of domestic volume given Indonesia's archipelagic geography and last-mile fragmentation. IoT monitoring technology is gaining fastest traction as shippers seek granular traceability against BPOM food safety mandates.
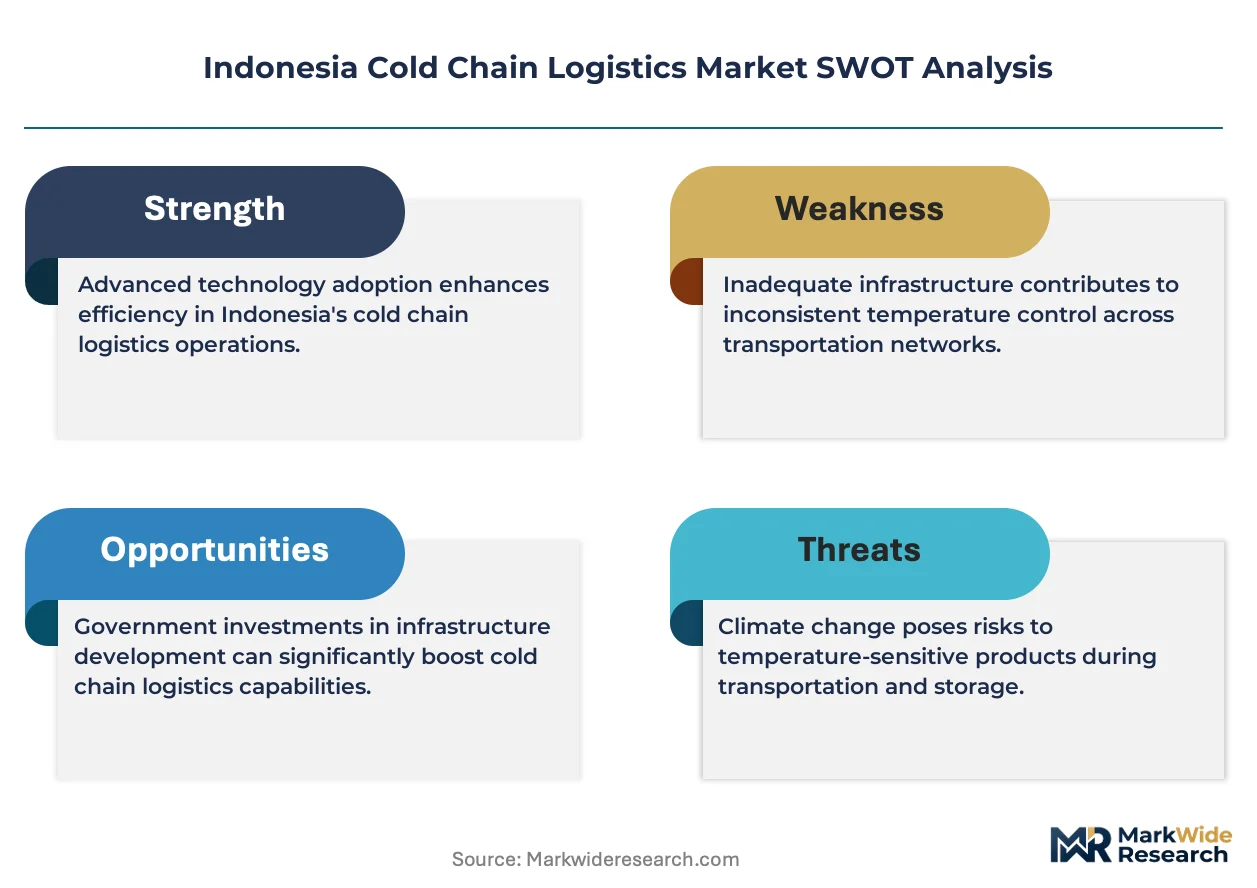
Indonesia's national food and drug regulator BPOM enforces cold-chain standards for imported pharmaceuticals and processed foods, while the Ministry of Agriculture mandates traceability protocols for livestock and fishery products moving across provincial borders. These frameworks compel logistics providers to upgrade refrigeration certification and documentation systems. Stakeholders must monitor evolving halal certification requirements for cold-chain segregation and anticipate infrastructure gaps between Java's saturated corridor and outer island expansion zones.
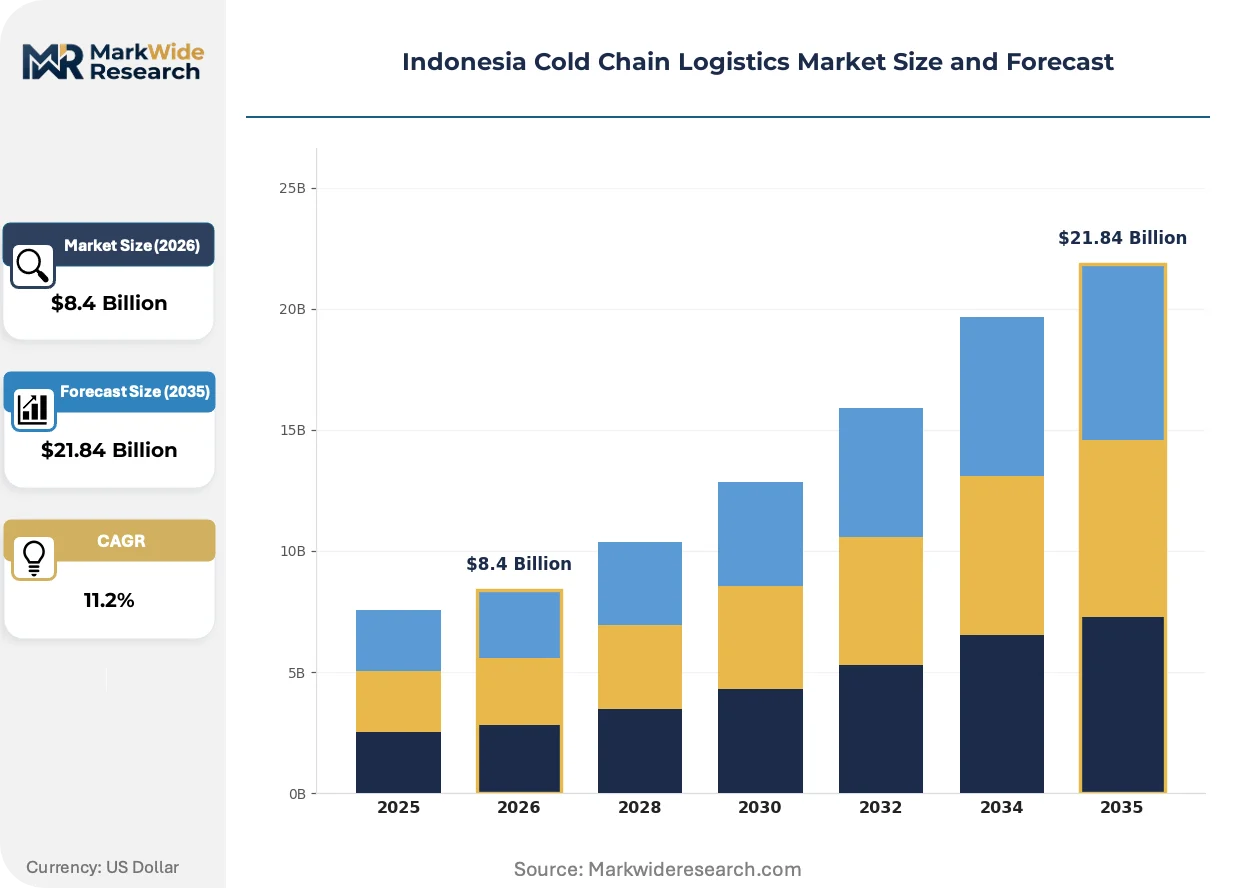
Market Dynamics
Indonesia's cold chain sector is compressing around BPOM's escalating enforcement of pharmaceutical temperature documentation, forcing logistics providers to consolidate fragmented fleet ownership into certified third-party networks.
Growth Catalysts
- BPOM Cold-Chain Mandates:The national food and drug regulator now requires end-to-end temperature logging for imported vaccines and biologics, compelling pharmaceutical distributors to upgrade warehouse certification.
- Seafood Export Quality Demands:Japan's METI import standards for frozen tuna and shrimp are driving investment in minus 25 degree Celsius blast freezing capacity at Surabaya and Makassar port zones.
- IoT Sensor Deployment:Real-time environmental monitoring systems are replacing manual temperature logs, enabling shippers to demonstrate compliance during provincial border inspections.
Market Restraints
- Diesel Price Volatility:Refrigerated transport fleets consume 40% more fuel than dry cargo equivalents, exposing operators to Pertamina's administered pricing adjustments.
- Java-Centric Infrastructure:Outer island cold storage capacity remains concentrated in Sulawesi and Sumatra hubs, leaving Maluku and Papua dependent on Jakarta transshipment.
- Halal Segregation Requirements:MUI certification mandates separate handling protocols for pork-adjacent products, complicating multi-user warehouse economics.
Strategic Opportunities
- Eastern Indonesia Expansion:Papua and West Papua present near-greenfield demand as mining camps and government health programs require reliable vaccine distribution.
- Pharmaceutical 2-8°C Last-Mile:Biologics and insulin delivery to tier-two cities outside Java's corridor remains underserved by compliant transport options.
- Solar-Powered Cold Storage:Hybrid photovoltaic refrigeration units are reducing diesel dependency for off-grid fishery collection points in Nusa Tenggara.
Industry Challenges
- Certified Technician Scarcity:BPOM-recognized cold-chain auditors and refrigeration engineers remain concentrated in Greater Jakarta, constraining outer island facility accreditation.
- Multi-Temperature Fleet Complexity:Operators struggle to maintain simultaneous minus 25, minus 18, and plus 2 to 8 degree Celsius zones within single vehicle configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Cold Chain Logistics Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $21.84 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Seafood, Dairy End User: Retailers, Distributors, Food Manufacturers, Wholesalers Technology: Thermal Control, Refrigeration Systems, IoT Monitoring, GPS Tracking Delivery Mode: Road Transport, Air Freight, Sea Freight, Rail Transport |
| Companies Covered | Samudera Logistics, PT YCH Indonesia, Kiat Ananda Group, PT Mitsubishi Logistics Indonesia, Yusen Logistics, Enseval Putera Megatrading Tbk, DHL Supply Chain Indonesia, Pangan Lestari, MGM Bosco Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Cold Chain Logistics Market Trends and Innovations
Digital traceability and renewable-powered refrigeration are restructuring how Indonesian cold chain operators justify capital deployment and secure pharmaceutical contracts.
IoT-enabled temperature loggers with blockchain-anchored data integrity are integrating pharmaceutical shipment records into BPOM's electronic submission portal. Major vaccine distributors in Greater Jakarta are retrofitting existing reefers with cellular-connected sensors within 18-month windows. This integration is compressing insurance premium spreads between certified and uncertified fleet operators.
Indonesia's Ministry of Agriculture is rolling out mandatory QR-code traceability for livestock and fishery products crossing provincial borders. The regulation forces cold storage facilities to deploy serialized inventory management systems or face shipment detention at inspection posts. Dairy processors in East Java are responding fastest, embedding compliance costs into supplier payment terms.
Consolidated procurement of temperature-controlled transport is displacing fragmented in-house fleet ownership among food manufacturers. Large instant noodle and dairy producers in Java are outsourcing entire distribution networks to third-party cold chain specialists with BPOM certification. This restructuring is most visible in the Jakarta-Surabaya corridor where asset-light manufacturers now represent 60% of contracted refrigerated trucking volume.
Indonesia Cold Chain Logistics Market Segmentation
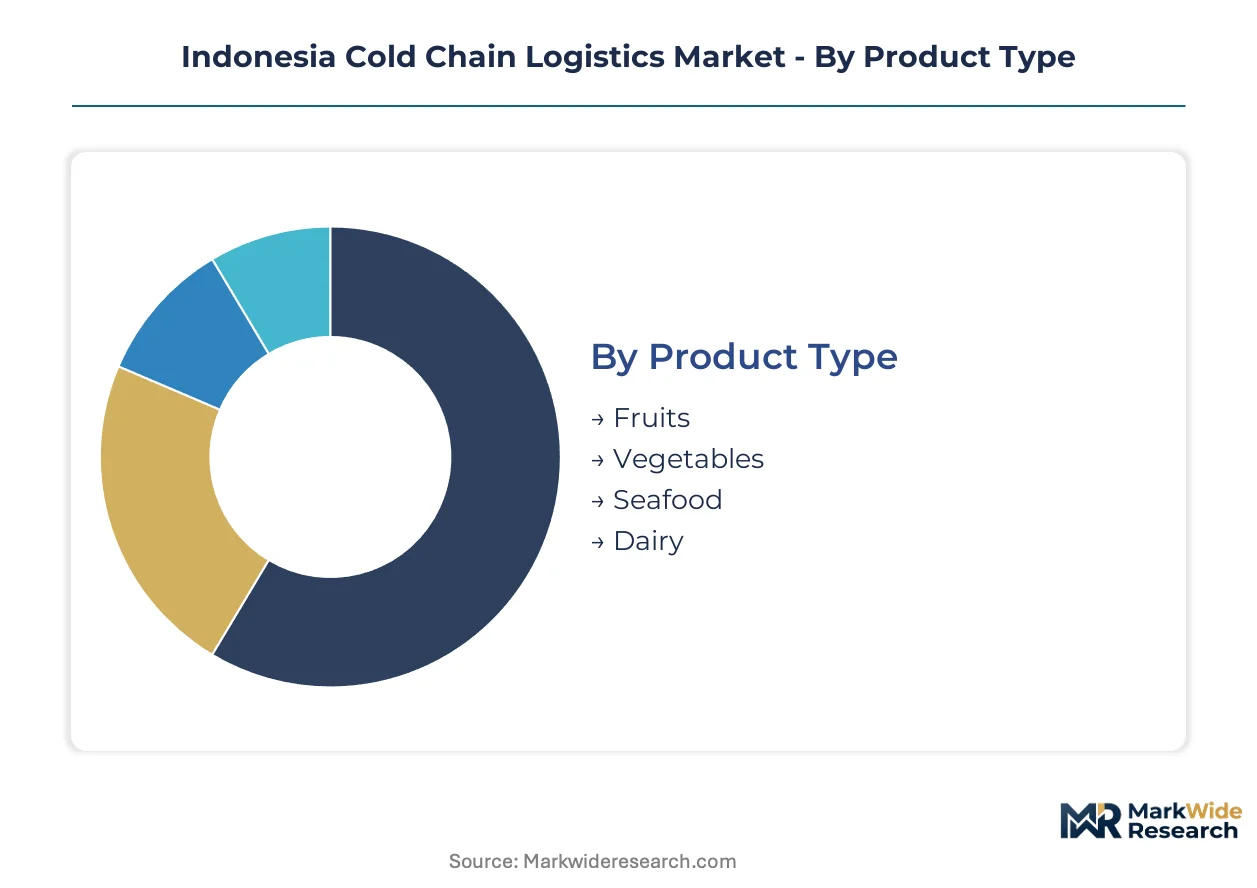
Cold chain logistics in Indonesia fragments across cargo temperature requirements, customer procurement sophistication, and transport infrastructure availability. Understanding these axes reveals where capital deployment concentrates and where compliance gaps persist.
Product Type:
Temperature bands and shelf stability differentiate infrastructure investment intensity across cargo categories.
- Seafood:Blast freezing to minus 25 degrees Celsius preserves tuna and shrimp for Japan METI export compliance. Surabaya and Makassar port zones concentrate investment due to proximity to fishing grounds and international shipping lanes.
- Dairy:Pasteurized milk and yogurt demand continuous plus 2 to 8 degree Celsius chains from East Java processing plants through Jakarta-Surabaya retail corridors. Short shelf windows force daily delivery cadences that strain fleet utilization.
- Fruits:Mangosteen and durian exports to China require controlled atmosphere containers with ethylene scrubbing.
- Vegetables:Leafy greens from Bandung highlands to Jakarta supermarkets tolerate broader plus 4 to 12 degree bands.
Seafood leads on scale; dairy leads on momentum.
End User:
Procurement consolidation patterns separate asset-heavy operators from outsourced logistics adopters.
- Food Manufacturers:Instant noodle and dairy processors in Java are divesting captive fleets fastest. These manufacturers now contract BPOM-certified third-party operators for 60 percent of refrigerated trucking volume in the Jakarta-Surabaya corridor.
- Retailers:Modern trade chains including Indomaret and Alfamart operate centralized distribution centers with multi-temperature zones. Their private standards exceed BPOM minimums for fresh produce display-case compliance.
- Distributors:Pharmaceutical specialists maintain FDA-equivalent warehousing for vaccine importation.
- Wholesalers:Traditional market suppliers rely on fragmented owner-operator trucks with minimal temperature logging.
Food manufacturers dominate contracted volume; retailers set specification benchmarks.
Technology:
Digital traceability and mechanical refrigeration specifications determine contract eligibility for pharmaceutical and export cargo.
- IoT Monitoring:Cellular-connected temperature loggers with blockchain-anchored data integrity integrate directly into BPOM electronic submission portals. Vaccine distributors in Greater Jakarta are retrofitting reefers with these sensors within 18-month compliance windows.
- Refrigeration Systems:Transport refrigeration units using R404A and R448A refrigerants dominate road fleets. Phase-down schedules under the Kigali Amendment are forcing operators to evaluate CO2 transcritical systems for new warehouse construction.
- GPS Tracking:Real-time location monitoring enables estimated-time-of-arrival coordination for just-in-time pharmaceutical deliveries.
- Thermal Control:Insulated containers with phase-change materials protect payloads during power interruptions.
Refrigeration systems anchor installed base; IoT monitoring climbs the fastest.
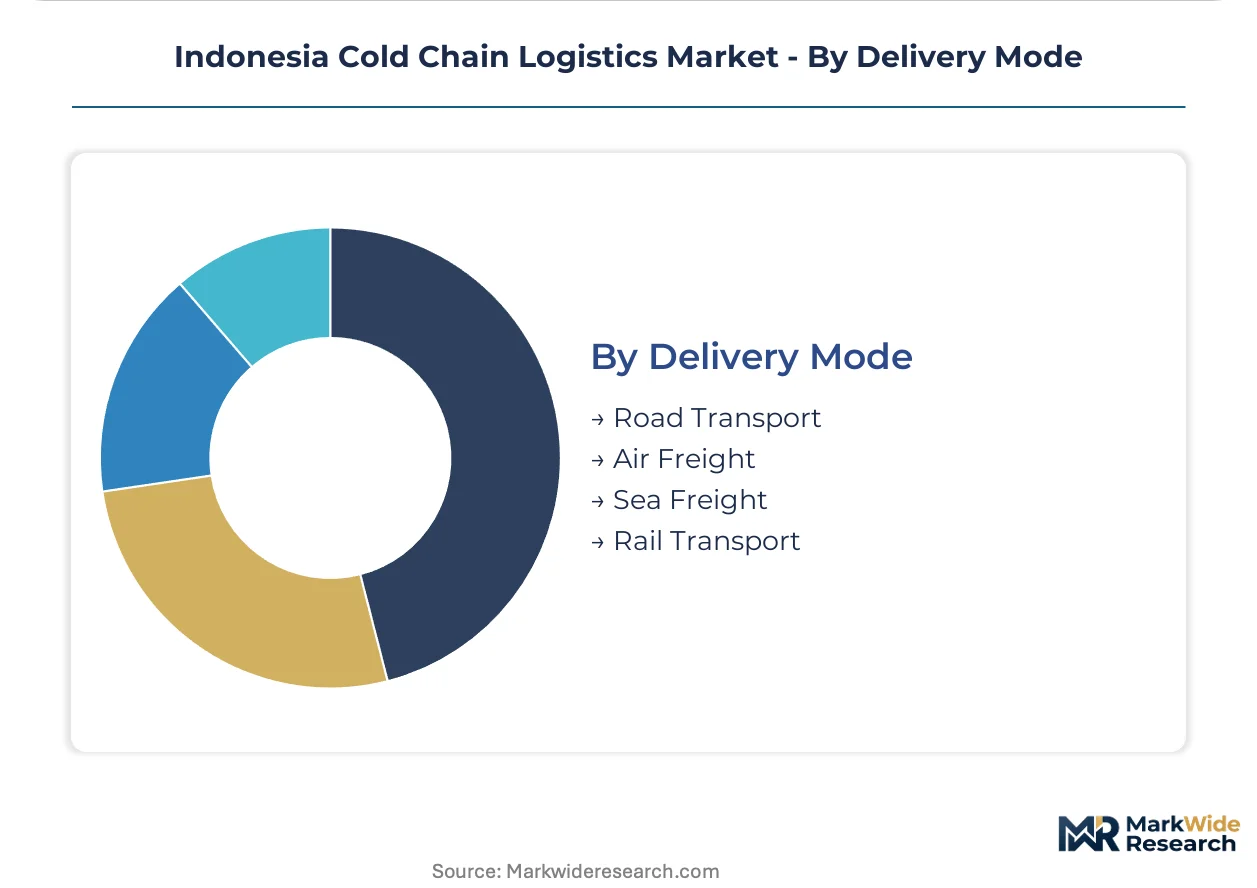
Delivery Mode:
Archipelagic geography and last-mile fragmentation dictate modal specialization across domestic and international lanes.
- Road Transport:Refrigerated trucks handle the majority of domestic volume despite Java's highway congestion. Multi-drop routes from Jakarta to Surabaya serve dairy and pharmaceutical distribution with scheduled departures every four hours.
- Sea Freight:Reefer containers connect outer islands to Java transshipment hubs. Sulawesi and Maluku fishery exports depend on reliable vessel scheduling for minus 25 degree Celsius maintenance.
- Air Freight:Express carriers transport high-value biologics and temperature-sensitive vaccines to tier-two cities lacking compliant road infrastructure.
- Rail Transport:Limited refrigerated wagon availability restricts mode share to bulk commodity movements on Java's northern line.
Road transport commands volume dominance; sea freight captures outer island expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is concentrating cold-chain investment in Java's urban corridor, where BPOM certification costs and technical talent availability create compliance economies unavailable in outer island provinces. Producers migrate distribution networks toward Greater Jakarta and Surabaya to minimize temperature-documentation penalties and secure pharmaceutical contracts.
Greater Jakarta
Pharmaceutical importation and vaccine distribution dominate demand as BPOM mandates end-to-end temperature logging for biologics. The national food and drug regulator requires warehouse certification upgrades that only Greater Jakarta facilities can staff with qualified auditors. Cikarang and Bekasi industrial zones attract third-party logistics providers consolidating fragmented fleet ownership.
East Java Corridor
Seafood blast-freezing capacity concentrates in Surabaya and Gresik to meet Japan METI export standards for frozen tuna and shrimp. The Ministry of Agriculture enforces QR-code traceability for fishery products crossing provincial borders. Malang and Pasuruan dairy processing plants maintain continuous plus 2 to 8 degree Celsius chains through daily delivery cadences to modern trade retailers.
South Sulawesi
Makassar anchors tuna export infrastructure with minus 25 degree Celsius port-side freezing capacity serving Japanese and Korean buyers. BPOM's escalating enforcement of pharmaceutical documentation has yet to penetrate this fishery-dominated economy. Pare-Pare and Bone regencies operate as collection points dependent on Jakarta transshipment for temperature-sensitive cargo.
North Sumatra
Medan's palm oil derivatives and processed food manufacturing generate secondary cold-chain demand for chocolate and dairy ingredients. Halal segregation requirements from the Indonesian Ulema Council complicate multi-user warehouse economics in this Muslim-majority region. Belawan port maintains limited reefer container connectivity to Singapore and Port Klang.
Papua and West Papua
Mining camp catering and government health programs create near-greenfield demand for reliable vaccine distribution. Solar-powered cold storage pilots in Jayapura and Sorong reduce diesel dependency for off-grid fishery collection points. Infrastructure gaps force dependence on air freight for temperature-sensitive biologics, with road networks largely non-compliant for pharmaceutical last-mile delivery.
Indonesia Cold Chain Logistics Market Competitive Landscape
Established logistics providers occupy the standard tier; emerging entrants pursue solar-powered off-grid refrigeration and tier-two city pharmaceutical distribution. The market compresses around BPOM certification requirements that favor operators with integrated port-to-warehouse networks and FDA-equivalent compliant warehousing. Three archetypes dominate: maritime-integrated specialists with container control, pharmaceutical-certified warehouse operators, and multinational protocol extenders. Competitive moves center on fleet retrofitting for IoT temperature monitoring and consolidation of fragmented owner-operator trucking into certified third-party networks.
Within the maritime-integrated tier, Samudera Logistics leverages its port-to-warehouse network to anchor temperature-controlled corridors. PT YCH Indonesia occupies a position among pharmaceutical-certified warehouse operators with Greater Jakarta facilities. DHL Supply Chain Indonesia represents multinational protocol extension into Indonesia's emerging tier-two cities. These three exemplify how certification depth and geographic coverage determine contract eligibility for pharmaceutical and export seafood cargo.
| Leading Market Players |
|---|
| Samudera Logistics |
| PT YCH Indonesia |
| Kiat Ananda Group |
| PT Mitsubishi Logistics Indonesia |
| Yusen Logistics |
| Enseval Putera Megatrading Tbk |
| DHL Supply Chain Indonesia |
| Pangan Lestari |
| MGM Bosco Logistics |
| Others |
Pricing and Supply Chain Analysis
BPOM certification tiers bifurcate Indonesia's cold chain market into premium pharmaceutical-grade operators and commodity food logistics providers, with this divergence manifesting in both rate structures and fleet investment patterns. Pharmaceutical distributors absorb 40-60% cost premiums for FDA-equivalent warehousing, while seafood exporters concentrate procurement on Surabaya-Makassar corridors where blast-freezing infrastructure justifies higher per-kilogram handling fees.
Pricing Analysis
Distributor margins compress most severely in Java's saturated Jakarta-Surabaya corridor where 60% of refrigerated trucking volume now flows through third-party contracts. Pricing stratifies across BPOM-certified pharmaceutical chains, export-grade seafood freezing, and domestic dairy distribution, with diesel price volatility under Pertamina's administered adjustments squeezing fleet operators most acutely. Food manufacturers exhibit highest price sensitivity, driving consolidation toward asset-light outsourcing models, while vaccine importers accept premium rates for uninterrupted 2-8°C compliance documentation.
Supply Chain Analysis
Direct-to-pharmaceutical channels handle hyperscale vaccine distribution through Greater Jakarta's certified warehouse clusters, while fragmented owner-operator trucking dominates last-mile food delivery. Supply concentration anchors in Java's industrial corridor with Cikarang-Bekasi zones feeding national distribution, drawing from diesel-dependent transport refrigeration units and imported R404A refrigerant stocks. Single-source vulnerability pervades outer island operations where Maluku and Papua depend on Jakarta transshipment for temperature-sensitive cargo, with distribution running through multi-modal port-to-warehouse networks controlled by integrated maritime specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's cold chain market compounds steadily as BPOM enforcement hardens compliance barriers and pharmaceutical importation expands across the archipelago.
For Market Incumbents: Deploy IoT retrofitting programs to capture pharmaceutical contract renewals before BPOM's 18-month compliance windows expire. Samudera Logistics and PT YCH Indonesia should consolidate fragmented owner-operator fleets into certified networks, defending against solar-powered cold storage entrants in Nusa Tenggara and Papua. Certification depth in Greater Jakarta remains the priority lever for margin defense.
For New Entrants and Emerging Players: Capture tier-two city pharmaceutical last-mile gaps outside Java's saturated corridor where compliant transport options remain scarce. Eastern Indonesia presents the most penetrable geography, with mining camp catering and government vaccine programs creating near-greenfield demand. A go-to-market angle anchored on solar-hybrid refrigeration units for off-grid fishery collection points bypasses incumbent diesel dependency.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented owner-operator trucking lacks BPOM certification and electronic temperature logging capability. Long-term viability favors operators with integrated port-to-warehouse networks spanning maritime and land-based cold chains. The signal to watch is M&A activity among pharmaceutical-certified warehouse operators in Greater Jakarta as compliance costs squeeze sub-scale competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Sensor Fleet Retrofitting | Cellular-connected temperature loggers integrate directly into BPOM electronic submission portals for pharmaceutical compliance. |
| Solar-Powered Cold Storage Deployment | Hybrid photovoltaic units reduce diesel dependency for off-grid fishery collection points in Nusa Tenggara and Papua. |
| Multi-Temperature Zone Fleet Expansion | Simultaneous minus 25, minus 18, and plus 2-8°C configurations address seafood, frozen food, and pharmaceutical cargo diversity. |
| Outer Island Distribution Partnership | Air freight alliances with express carriers bypass non-compliant road networks for biologics delivery to tier-two cities. |
| Halal Segregation Infrastructure Investment | MUI-compliant separate handling protocols unlock multi-user warehouse economics in Muslim-majority North Sumatra and Sulawesi. |
Research Methodology
Bottom-up pharmaceutical and food manufacturer demand modeling reconciled against top-down refrigerated fleet capacity tracking forms the analytical core. Primary interviews with cold chain operations directors, BPOM compliance officers, pharmaceutical distribution managers, and seafood export procurement leads combined with secondary validation from Indonesia's Ministry of Agriculture traceability databases, BPOM regulatory filings, and customs reefer container movement records. Triangulation across these sources anchors volume estimates.
Input-output matrices model cold storage capacity utilization against cargo temperature requirements across the projection horizon. Segmentation dimensions include product type temperature bands, end-user procurement sophistication, delivery mode infrastructure availability, and regional regulatory enforcement intensity. CAGRs derive from pharmaceutical import growth trajectories and seafood export quality mandate compliance timelines, with diesel price elasticity and IoT adoption curves as industry-specific forecast inputs.
Regulatory enforcement intensity shifts, refrigerant phase-down schedules under the Kigali Amendment, and halal certification requirement evolution are the dominant revision risks. Forecasts reflect base-case assumptions about BPOM mandate penetration rates and outer island infrastructure investment flows. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
Brazil Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
Germany Third-Party Logistics (3PL) Market
Logistics and Shipping
Europe Courier, Express and Parcel (CEP) Market
Logistics and Shipping
United States Courier, Express and Parcel (CEP) Market
Logistics and Shipping
UK Logistics Market
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
Tanker Cargo Ship Market
Logistics and Shipping
Project Logistics Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
Cargo Shipping Market
Logistics and Shipping
Sustainable Logistics Market
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
Sweden Freight and Logistics Market