
 Germany Freight and Logistics Market | 2026-2036
Germany Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Freight and Logistics Market Foresight
German port infrastructure and inland waterway capacity is shifting toward intermodal integration. DHL Group leverages its domestic network density to dominate parcel and express segments. Kuehne+Nagel anchors its European sea-air hub operations through Hamburg and Frankfurt gateways. Rhenus Group specializes in contract logistics for automotive and industrial suppliers across Baden-Württemberg and Bavaria.
Germany freight and logistics encompasses the physical movement, storage, and information management of goods across road, rail, air, and waterway networks, with container handling capacity exceeding 14 million TEU annually at Hamburg and Bremerhaven combined. Its primary purpose is synchronizing supply chains for export-oriented manufacturing, chemical production, and retail distribution. Road freight still carries the largest volume share but faces structural margin pressure from driver shortages and fuel cost volatility, while rail freight and intermodal services capture expanding share on corridor routes to Italy, Poland, and the Benelux. Warehouse automation and freight management software within technology adoption are attracting capital fastest, driven by labor scarcity and shipper demands for real-time visibility.
KBA enforces commercial vehicle emissions standards and driving time regulations that directly shape fleet renewal cycles and route planning economics. The EU Green Deal and Germany's national dual carbon goals mandate freight decarbonization timelines that push operators toward electric trucks, alternative fuels, and rail modal shift. Stakeholders must monitor how EU AI Act provisions on automated transport systems and CSRD supply chain disclosure requirements will reshape compliance costs and technology procurement priorities.
Market Dynamics
The EU Green Deal and Germany's dual carbon goals are compressing fleet renewal cycles while accelerating modal shift investments across Rhine corridor infrastructure. This regulatory pressure layer intersects with acute commercial driver shortages to reshape operator economics.
Growth Catalysts
- Rail modal shift mandates:The EU Green Deal's freight decarbonization timelines push cargo onto electrified rail corridors connecting the Rhine-Ruhr industrial cluster to Italian and Polish markets.
- Automotive just-in-time intensity:Baden-Württemberg and Bavaria manufacturing plants demand synchronized inbound parts logistics with sub-hour delivery windows.
- Warehouse automation capital deployment:Labor scarcity in logistics hubs drives investment in automated storage and retrieval systems for e-commerce fulfillment.
Market Restraints
- Diesel cost volatility:Road freight operators face margin compression from fuel price swings that KBA emissions standards cannot offset through fleet efficiency alone.
- Driver labor pool contraction:Germany's commercial driver shortage creates structural capacity constraints on long-haul routes regardless of equipment availability.
- Intermodal terminal bottlenecks:Limited rail-yard throughput at Hamburg and Bremerhaven restricts container transfer velocity during peak shipping seasons.
Strategic Opportunities
- CSRD supply chain disclosure:The EU's Corporate Sustainability Reporting Directive creates service revenue streams for logistics providers offering emissions tracking and Scope 3 data management.
- Alternative fuel infrastructure:Hydrogen and battery-electric truck corridors along the A1 and A7 autobahns offer first-mover positioning for fleet operators.
- AI Act automated transport:Regulatory frameworks for autonomous trucking pilot zones open testing grounds for platooning and yard automation technologies.
Industry Challenges
- Telematics integration complexity:Fleet operators struggle to harmonize legacy dispatch systems with real-time visibility platforms demanded by automotive and chemical shippers.
- Certification timeline compression:EU AI Act compliance for automated logistics systems requires documentation protocols that stretch engineering resources.
- Interoperable data standards:Rail and road operators lack unified cargo status protocols, forcing manual reconciliation across modal handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Freight and Logistics Market |
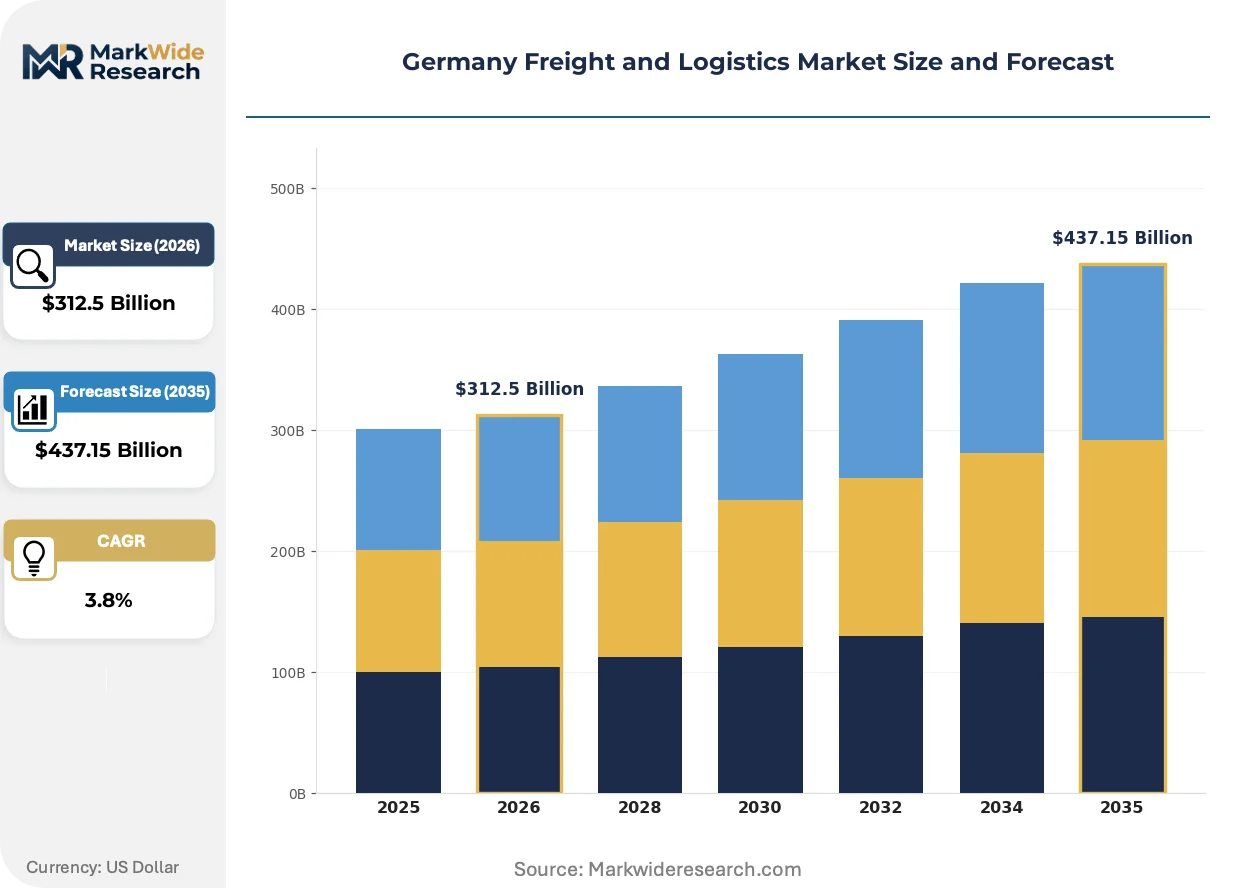
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $437.15 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Supply Chain Management, Last Mile Delivery, Customs Brokerage Transport Mode: Road Freight, Rail Freight, Air Cargo, Sea Freight, Intermodal, Courier Services Customer Type: Manufacturers, Retail Chains, Wholesale Distributors, E-commerce Platforms, Industrial Suppliers, Food Producers Technology Adoption: Telematics, GPS Tracking, Warehouse Automation, Freight Management Software, Blockchain, Robotics |
| Companies Covered | Kuehne+Nagel, Hapag-Lloyd, DHL Group, HHLA, BLG Logistics Group, DSV (including DB Schenker), Rhenus Group, KION Group, DACHSER, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Freight and Logistics Market Shifts & Advancements
Digital freight platforms and predictive analytics are compressing planning cycles while reshaping how shppers procure capacity across modal alternatives.
Freight management software is consolidating control tower visibility across multimodal networks. Chemical and automotive shippers in North Rhine-Westphalia are deploying these platforms to orchestrate rail-truck transfers. This technology compression is consolidating procurement power with large shippers who can mandate data interoperability from contracted carriers.
The EU AI Act establishes liability frameworks for automated transport systems that directly affect logistics technology roadmaps. German operators must document algorithmic decision-making for yard automation and route optimization tools. The automotive supplier segment is responding fastest, embedding compliance documentation into tender requirements for 3PL partners.
Shippers are unbundling long-term contract commitments in favor of spot-market capacity with dynamic pricing. This procurement fragmentation disadvantages smaller fleet operators lacking real-time rate visibility tools. The Rhine-Ruhr corridor shows the clearest manifestation, where chemical producers now source 40% of truck capacity through digital freight exchanges rather than annual tenders.
Germany Freight and Logistics Market Segmentation
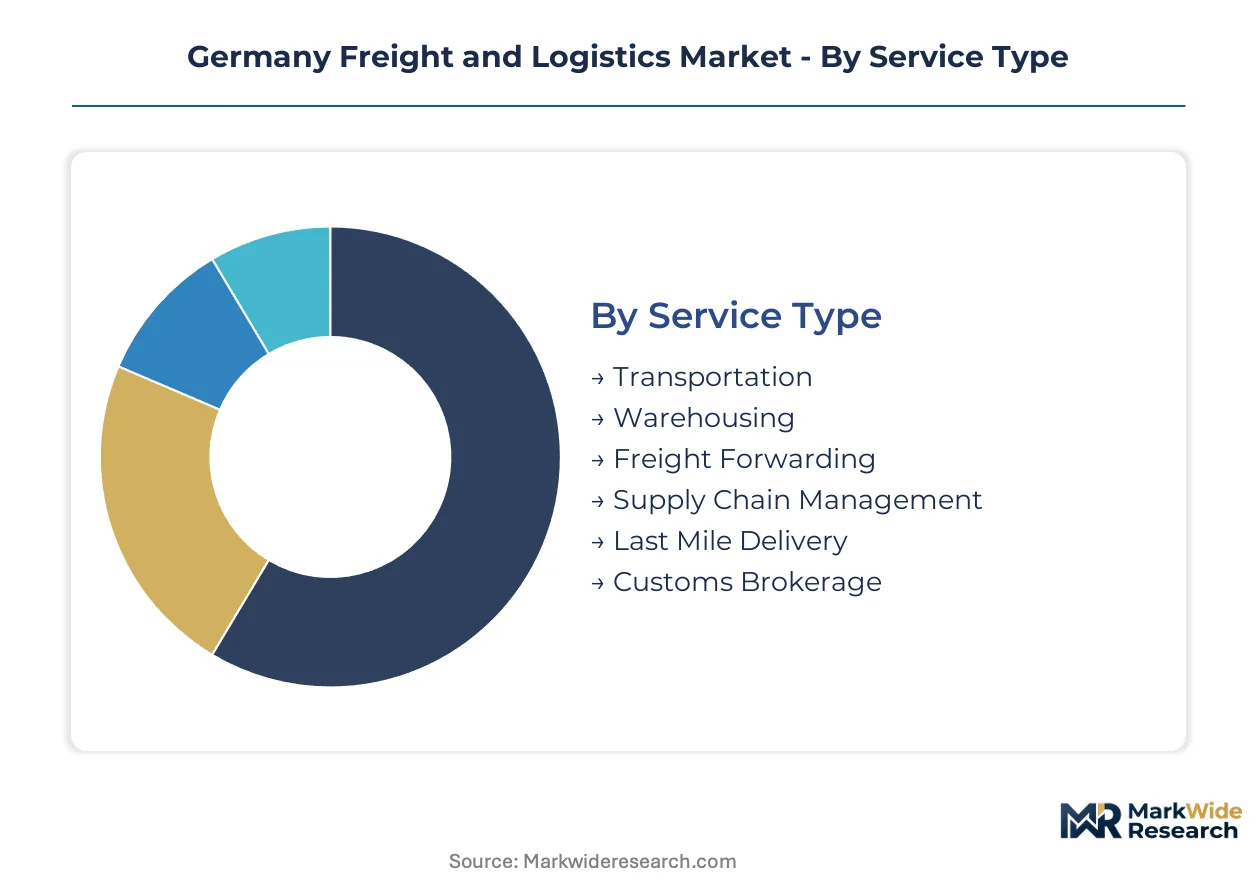
German freight and logistics segmentation reveals how shippers prioritize service reliability, modal flexibility, and technology integration when selecting providers. Each dimension captures distinct procurement logic across automotive, chemical, and retail supply chains.
Service Type:
Shippers select service tiers based on inventory velocity requirements and control preferences, with cost-to-serve varying dramatically across asset-light versus asset-heavy models.
- Transportation:Asset-based trucking and dedicated fleet operations dominate contract logistics for Baden-Württemberg automotive plants. KBA driving-time regulations compress route planning economics while driver shortages force premium labor rates on long-haul corridors to Poland and Italy.
- Warehousing:Automated storage and retrieval systems in Rhine-Ruhr distribution centers handle e-commerce fulfillment peaks. Labor scarcity in North Rhine-Westphalia logistics hubs accelerates capital deployment in robotic picking and sortation infrastructure.
- Freight Forwarding:Non-asset intermediaries orchestrate multimodal bookings through Hamburg and Bremerhaven gateways.
- Supply Chain Management:Control tower services integrate visibility across tiered supplier networks for industrial manufacturers.
- Last Mile Delivery:Parcel networks face margin pressure from urban delivery density requirements and emissions zone restrictions.
- Customs Brokerage:Post-Brexit documentation complexity and EU import controls sustain demand for specialized declarants at border terminals.
Transportation leads on scale; warehousing leads on momentum.
Transport Mode:
Modal selection in Germany tracks corridor-specific infrastructure maturity, emissions compliance costs, and cargo time-sensitivity across manufacturing supply chains.
- Road Freight:Diesel and battery-electric truck fleets carry the largest volume share despite structural margin pressure. Driver labor pool contraction and fuel cost volatility constrain capacity expansion on Rhine-Ruhr to Bavaria corridors.
- Rail Freight:Electrified corridor services capture expanding share on Italy and Benelux routes through modal shift mandates. EU Green Deal timelines accelerate investment in terminal infrastructure at Hamburg and Bremerhaven.
- Air Cargo:Frankfurt Gateway anchors European sea-air hub operations for time-critical automotive and pharmaceutical shipments.
- Sea Freight:Container handling at Hamburg and Bremerhaven exceeds 14 million TEU annually combined.
- Intermodal:Rail-truck transfers concentrate at Rhine corridor terminals serving chemical producers.
- Courier Services:Express parcel networks leverage domestic density for next-day delivery commitments.
Road freight dominates absolute volume; rail freight shows the steepest expansion trajectory.
Customer Type:
End-use procurement patterns diverge sharply between synchronized manufacturing supply chains and volatile retail fulfillment demands.
- Manufacturers:Automotive and chemical producers in Baden-Württemberg and North Rhine-Westphalia mandate sub-hour delivery windows for just-in-time production lines. Contract logistics providers embed dedicated operations within plant perimeters to synchronize inbound parts flow.
- E-commerce Platforms:Digital retailers drive warehouse automation investment through seasonal demand spikes and same-day delivery promises. Fulfillment center location strategy prioritizes population density within 50-kilometer radii of major urban centers.
- Retail Chains:Omnichannel distribution requires flexible capacity allocation between store replenishment and direct-to-consumer fulfillment.
- Wholesale Distributors:Bulk commodity handling favors palletized road freight with established lane density.
- Industrial Suppliers:Tiered automotive component vendors demand synchronized sequencing services.
- Food Producers:Temperature-controlled logistics compliance shapes cold chain infrastructure requirements.
Manufacturers anchor contract logistics revenue; e-commerce platforms drive automation capital deployment.
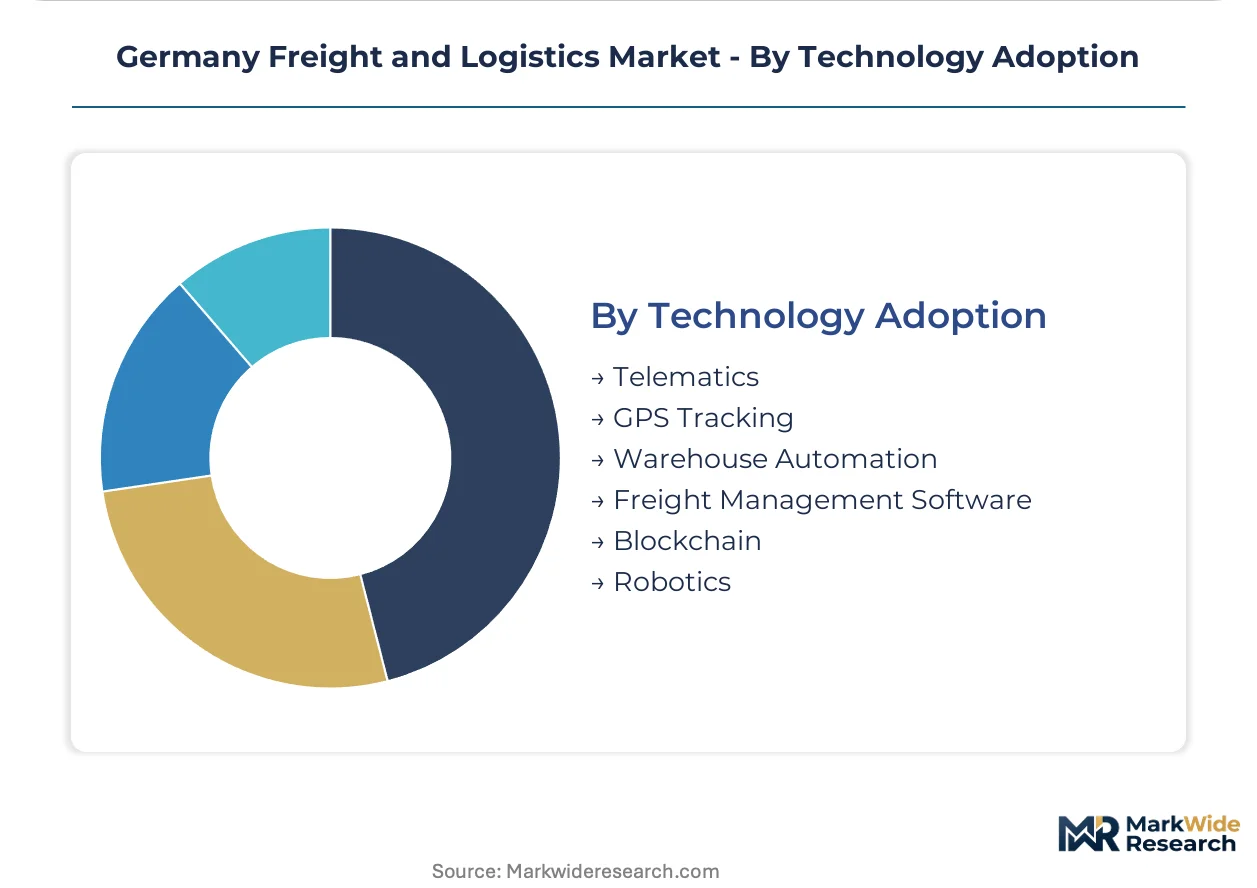
Technology Adoption:
Technology procurement priorities reflect labor substitution economics and shipper mandates for real-time cargo visibility across multimodal networks.
- Warehouse Automation:Automated storage and retrieval systems and robotic picking address labor scarcity in Rhine-Ruhr fulfillment hubs. E-commerce volume concentration justifies capital intensity for throughput acceleration.
- Freight Management Software:Control tower platforms consolidate visibility across road, rail, and sea bookings for chemical and automotive shippers. Procurement fragmentation toward spot-market sourcing increases demand for dynamic rate optimization tools.
- Telematics:Fleet tracking systems support KBA driving-time compliance and fuel consumption monitoring.
- GPS Tracking:Real-time location data satisfies shipper visibility requirements for high-value cargo.
- Blockchain:Distributed ledger pilots target documentation efficiency in multimodal handoffs.
- Robotics:Yard automation and sortation systems reduce manual handling at intermodal terminals.
Warehouse automation leads on current investment scale; freight management software gains share fastest among technology categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between German federal states creates divergent logistics cost structures. KBA enforcement intensity and state-level emissions zone designations push fleet operators toward compliant sub-regions while penalizing high-carbon corridors.
North Rhine-Westphalia
Chemical producers in the Rhine-Ruhr cluster demand synchronized multimodal transfers between road and barge networks. The EU Green Deal accelerates terminal automation at Duisburg intermodal facilities. Dortmund and Cologne logistics hubs attract automation capital to offset labor scarcity in fulfillment operations.
Baden-Württemberg
Automotive just-in-time supply chains compress delivery windows to sub-hour precision for Stuttgart-area assembly plants. KBA driving-time regulations force fleet operators into relay configurations on Italy-bound corridors. Mannheim and Karlsruhe serve as consolidation points for supplier sequencing services.
Bavaria
Munich manufacturing plants anchor high-velocity inbound parts logistics for premium automotive production. The EU AI Act creates compliance documentation requirements for automated yard systems at Nuremberg distribution centers. Ingolstadt chemical parks drive demand for temperature-controlled tanker capacity.
Hamburg
Port-centric logistics concentrates container handling and sea-air transshipment through the Elbe corridor. EU CSRD disclosure mandates push terminal operators toward emissions tracking infrastructure. Billwerder and Altenwerder rail yards handle modal shift volume to Italian and Polish markets.
Lower Saxony
Volkswagen Group operations in Wolfsburg generate dedicated contract logistics demand for inbound component flows. The EU Green Deal rail investment targets electrified corridors through Hanover to Benelux ports. Braunschweig and Salzgitter industrial zones sustain bulk chemical and steel logistics requirements.
Germany Freight and Logistics Market Competitive Landscape
Domestic operators anchor asset-heavy contract logistics; international specialists hold non-asset forwarding tiers. The market structures around three strategic layers: integrated parcel networks, multimodal forwarders, and automotive-dedicated contract providers. Competitive dynamics favor M&A consolidation among mid-scale road operators and technology partnerships linking warehouse automation vendors to fleet telematics platforms.
Within the integrated logistics tier, DHL Group and Kuehne+Nagel occupy positions spanning domestic parcel density and European sea-air gateway control. Rhenus Group exemplifies the automotive-specialist archetype embedded within Baden-Württemberg manufacturing corridors. These three anchors represent distinct competitive vectors: network scale, modal orchestration, and vertical industry integration.
| Leading Market Players |
|---|
| Kuehne+Nagel |
| Hapag-Lloyd |
| DHL Group |
| HHLA |
| BLG Logistics Group |
| DSV (including DB Schenker) |
| Rhenus Group |
| KION Group |
| DACHSER |
| Others |
Supply & Pricing Matrix
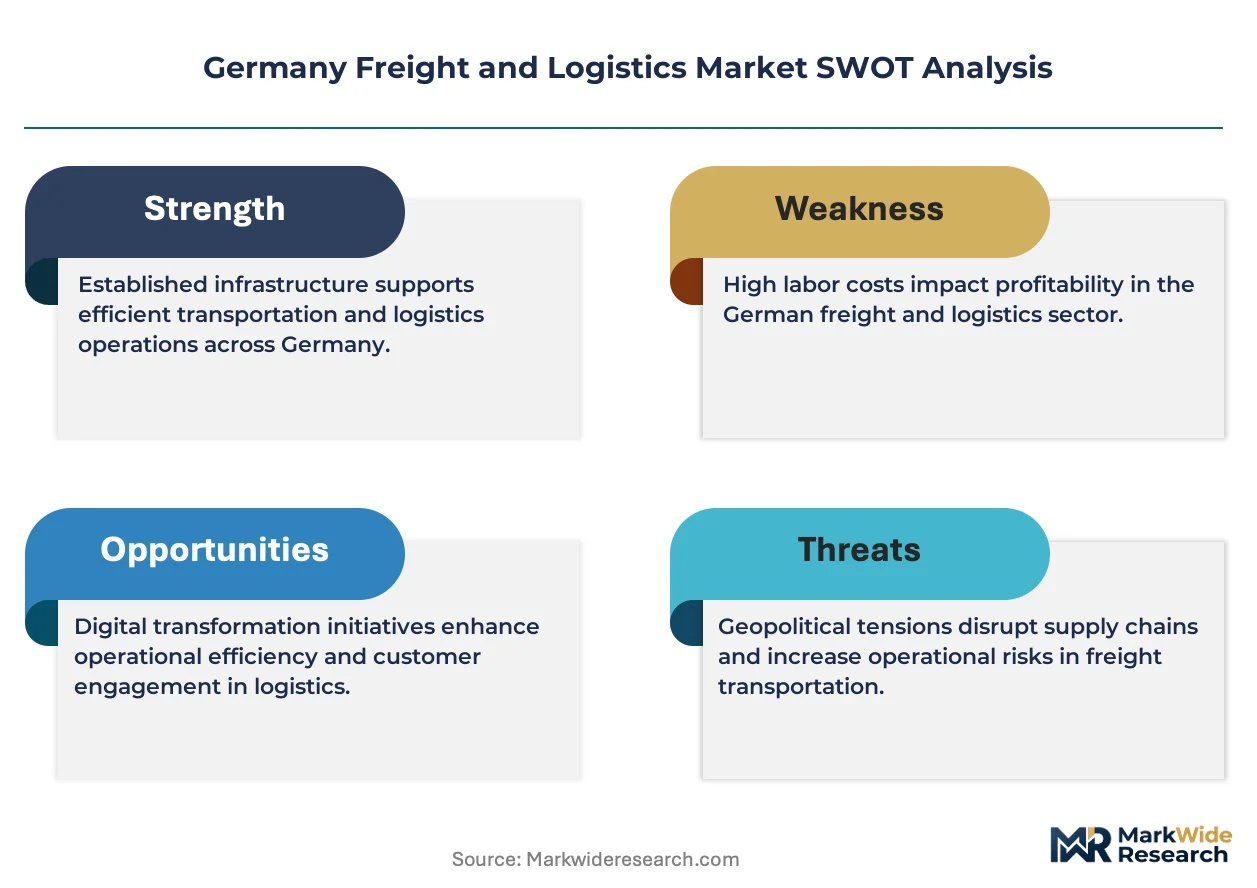
Captive fleet integration by automotive manufacturers anchors supply positioning and pricing power across Baden-Württemberg corridors. This vertical control over dedicated transport assets compresses third-party margins while insulating OEMs from spot-market volatility.
Pricing Analysis
Distributor margin layers in contract logistics separate premium just-in-time sequencing from standard palletized freight. Three-tier pricing structure across premium, standard, and economy levels tracks KBA compliance certification, cargo time-sensitivity, and dedicated fleet allocation. Cost compression in standard road freight intensifies because diesel volatility and driver scarcity squeeze operator economics. Chemical producers in North Rhine-Westphalia exhibit highest price sensitivity due to bulk commodity positioning, while automotive OEMs prioritize reliability over rate negotiation.
Supply Chain Analysis
Workforce availability constraints in German manufacturing geographies tether supply capacity to immigration policy and training pipeline outputs. Production equipment and rolling stock fabrication draw from Germany, Poland, and Czech Republic manufacturing bases. Diesel fuel, battery-electric drivetrains, and intermodal terminal infrastructure constitute critical input dependencies. Single-source vulnerability concentrates in specialized chassis production for automotive sequencing. Distribution runs through Rhine corridor terminals connecting Hamburg and Bremerhaven gateways to inland industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential through warehouse automation substitution of scarce logistics labor and premium-tier service differentiation for automotive just-in-time requirements.
For Market Incumbents: To counter digital freight platform disintermediation, DHL Group and Rhenus Group should deepen captive fleet integration in Stuttgart-area automotive corridors and embed CSRD-compliant emissions tracking as a mandatory tender requirement. KBA regulatory expertise becomes a defendable moat against asset-light competitors lacking compliance infrastructure. For New Entrants and Emerging Players: Capture white-space in hydrogen truck corridor infrastructure along A1 and A7 autobahns where first-mover fueling networks lock in fleet operator relationships. Alternative fuel logistics services represent the most penetrable segment given EU Green Deal enforcement timelines and incumbent capital allocation lag. Position through pilot partnerships with chemical producers seeking Scope 3 disclosure compliance. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale road operators with dense Rhine-Ruhr lane coverage because driver scarcity accelerates consolidation pressure and technology integration costs favor scaled platforms. Target acquisition archetypes include specialized automotive sequencing providers and terminal automation technology vendors. Watch KBA enforcement intensity on emissions standards as the inflection signal for fleet renewal cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Intermodal Terminal Automation | EU Green Deal rail investment at Duisburg and Hamburg accelerates container transfer velocity. |
| Alternative Fuel Fleet Conversion | Battery-electric and hydrogen truck deployment along A1 corridor addresses KBA emissions mandates. |
| CSRD Data Service Integration | Emissions tracking platforms capture chemical shipper demand for supply chain disclosure compliance. |
| Automotive Sequencing Expansion | Just-in-time parts logistics embedding within Stuttgart plant perimeters locks in contract revenue. |
| Digital Freight Platform Partnership | Real-time capacity marketplaces consolidate procurement power with large Rhine-Ruhr chemical producers. |
Research Methodology
Bottom-up automotive and chemical shipper modeling reconciled against top-down fleet capacity and terminal throughput tracking forms the analytical core of this study. Primary interviews with logistics procurement managers, fleet operations directors, intermodal terminal planners, and KBA compliance officers combined with secondary validation from Bundesamt für Güterverkehr transport statistics, EU transport infrastructure investment disclosures, and operator financial filings. Triangulation across these sources ensures segment-level accuracy.
Input-output matrices map freight volume flows across service type, transport mode, customer category, and technology adoption tier throughout the forecast period. CAGRs derive from corridor-specific capacity expansion timelines, regulatory enforcement schedules, and shipper procurement pattern shifts. Forecast inputs include KBA commercial vehicle registration data, EU Green Deal infrastructure allocation announcements, and warehouse automation deployment trajectories in Rhine-Ruhr fulfillment hubs.
Fuel cost volatility, driver labor pool contraction, and EU AI Act compliance timeline delays are the dominant revision risks to modeled outputs. Forecasts reflect assumptions on modal shift adoption rates and terminal automation deployment schedules. Material deviation in named triggers warrants pause and re-evaluation of segment growth trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
Retail Logistics Market
Logistics and Shipping
Asia Pacific Automotive Logistics Market
Logistics and Shipping
Carrier-Agnostic Parcel and Freight Visibility Aggregation Market
Logistics and Shipping
Fine Art Logistics Market
Logistics and Shipping
Outbound Logistics Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
Italy Cold Chain Logistics Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
Saudi Arabia Last Mile Delivery Market
Logistics and Shipping
Halal Logistics Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
Kazakhstan Freight and Logistics Market
Logistics and Shipping
South Africa Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Egypt Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Illinois Freight and Logistics Market