
 Timber Logistics Market | 2026-2036
Timber Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Timber Logistics Market Analysis
The gap between certified sustainable timber flows and standard-grade commodity shipments is repositioning how carriers allocate refrigerated and dry van capacity across Northern Europe. Deutsche Bahn AG leverages its integrated rail-terminal network to dominate long-haul movements from Scandinavian forests to Central European mills. DSV A/S sustains competitive advantage through specialized flatbed and open-deck fleets calibrated for oversized log dimensions. C.H. Robinson Worldwide anchors its position via digital freight matching platforms that reduce empty backhauls on return legs from Baltic ports.
Timber logistics encompasses the planning, execution, and control of physical movement and storage for wood products from forest extraction through intermediate processing to end-user delivery, typically requiring moisture-controlled transport with load securing rated for densities between 400 and 900 kg per cubic meter depending on species and seasoning state. Rail freight for sawn timber commands the highest volume share on corridors exceeding 800 kilometers where unit train economics outperform road alternatives, while sea freight for logs and chips is expanding fastest on trans-Pacific and trans-Atlantic routes driven by Asian pulp mill demand. Warehousing services generate concentrated margin pools where climate-controlled storage and phytosanitary certification handling create service differentiation that standard freight forwarding cannot replicate.
The EU Deforestation Regulation and ECHA timber trade standards mandate chain-of-custody documentation that shapes market access for non-certified suppliers, while Germany's KBA enforces vehicle weight and dimension rules that constrain truck configurations for heavy log hauls. The US EPA and OSHA frameworks govern emissions compliance and loading safety protocols that affect equipment replacement cycles across North American fleets. Stakeholders must monitor how evolving due diligence requirements will redistribute volume toward providers with verified traceability systems rather than lowest-unit-rate bidding.
Market Dynamics
The EU Deforestation Regulation is compressing certification timelines across Northern European supply chains, forcing carriers and terminal operators to deploy traceability infrastructure before enforcement deadlines harden market access rules.
Growth Catalysts
- Nordic-Baltic Port Expansion:Breakbulk terminal capacity at Riga, Klaipeda, and Kotka is absorbing redirected volumes from congested North Sea hubs, creating new rail-sea intermodal economics for Russian-border alternative routing.
- EU Deforestation Regulation:Mandatory chain-of-custody documentation is concentrating procurement toward certified suppliers, rewarding logistics providers with pre-positioned audit trails and phytosanitary handling capabilities.
- Engineered Wood Products:German construction firms are extending sourcing radii for cross-laminated timber and glulam, stretching haul distances beyond 800 kilometers where unit train configurations outperform road alternatives.
Market Restraints
- Vehicle Dimension Constraints:Germany's KBA enforces strict weight and length limits on heavy log hauls, capping payload efficiency and forcing fleet specialization that raises capital intensity per cubic meter moved.
- Certification Cost Burden:Small-scale Baltic forest owners face disproportionate compliance costs for FSC and PEFC chain-of-custody audits, shrinking the supplier base and concentrating volume among integrated majors.
- Fuel Price Volatility:Diesel cost swings directly erode road freight margins on low-density chip and bark movements where weight-based pricing cannot absorb energy shocks.
Strategic Opportunities
- Climate-Controlled Warehousing:Moisture-managed storage with automated humidity sensing commands premium spreads in Poland and the Czech Republic where sawmills lack on-site seasoning capacity.
- Rail Electrification Corridors:Deutsche Bahn's terminal network offers captive positioning for battery-electric locomotive conversion, aligning with EU Green Deal freight decarbonization incentives.
- Digital Freight Matching:Platforms reducing empty backhauls from Baltic ports to Central European mills capture margin pools that traditional forwarders leave unmonetized on return legs.
Industry Challenges
- Phytosanitary Certification Delays:Heat treatment documentation for ISPM-15 compliance creates bottlenecks at Polish-Ukrainian border crossings, extending dwell times and disrupting just-in-time mill schedules.
- Legacy Fleet Retrofit Costs:Refrigerated and flatbed assets require telematics installation and sensor calibration to meet emerging traceability mandates, straining mid-size operator balance sheets.
- Specialized Driver Scarcity:Securement certification for oversized log dimensions and hazardous cargo endorsements limits the qualified labor pool across Scandinavian haul markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Timber Logistics Market |
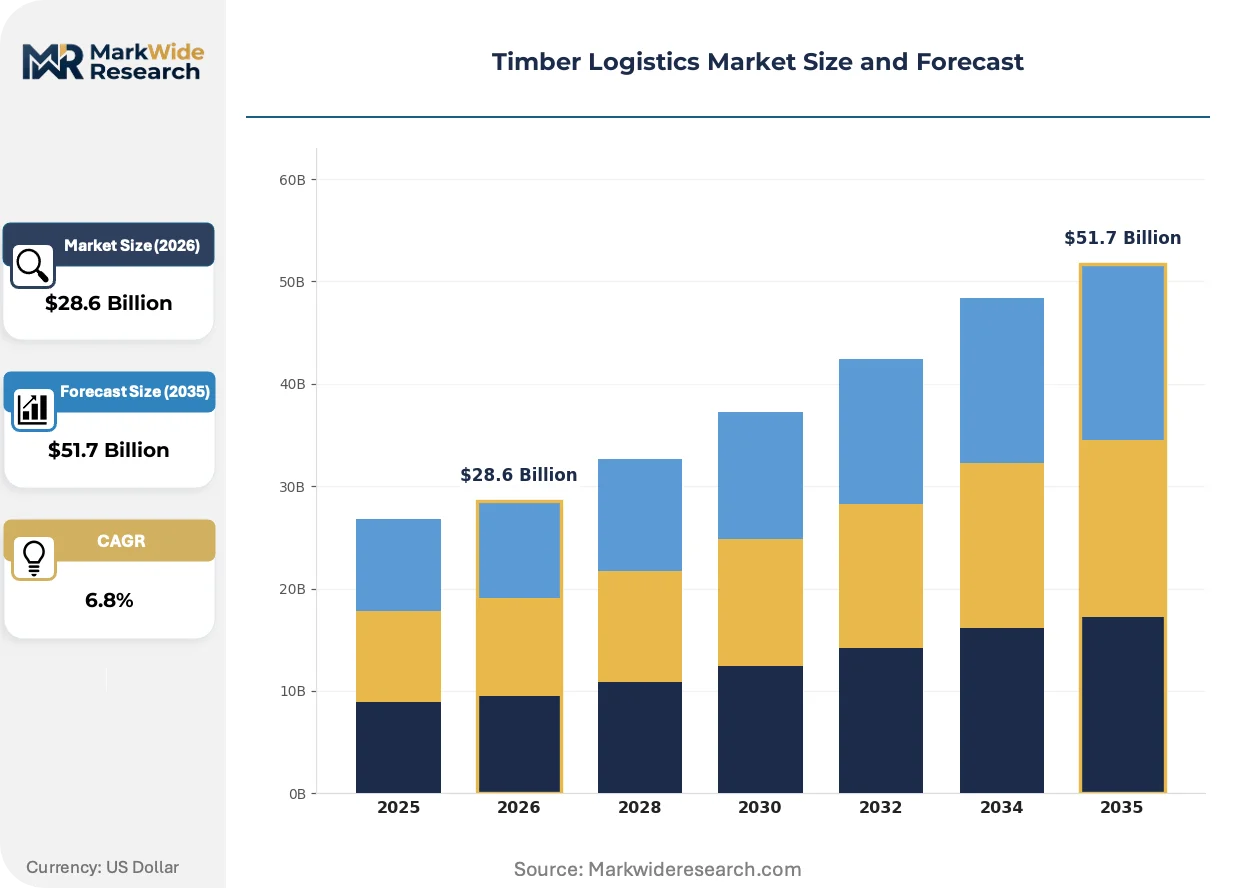
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transportation Mode: Rail, Road, Sea, Air Log Type: Sawn Timber, Plywood, Chips, Logs Service Type: Warehousing, Freight Forwarding, Distribution, Inventory Management End User: Construction Companies, Furniture Manufacturers, Paper Mills, Exporters |
| Companies Covered | XPO Logistics, Rhenus Logistics, DHL Supply Chain, C.H. Robinson Worldwide, Deutsche Bahn AG, Kuehne + Nagel, CEVA Logistics, DSV A/S, DB Schenker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Timber Logistics Market Emerging Trajectories
Digital traceability infrastructure is displacing paper-based chain-of-custody systems, while electrified rail corridors and automated load-securing technologies reshape capital allocation across modal networks.
Blockchain-enabled timber provenance tracking is overtaking traditional audit-based certification methods in high-value species shipments. Scandinavian exporters and German mill buyers are piloting distributed ledger systems to compress verification cycles from weeks to hours. The technology is overtaking documentary compliance as the default market-access filter for tropical hardwood substitutes entering EU customs zones.
The EU Deforestation Regulation's due diligence requirements are mandating satellite-based deforestation monitoring linked to shipment documentation. Operators must integrate geospatial verification into logistics management systems or face exclusion from supermarket and construction retail supply chains. Baltic port authorities are responding by embedding certification checkpoints within terminal operating software.
Construction procurement teams are consolidating vendor lists around integrated logistics-timber suppliers capable of guaranteed moisture-content delivery. Single-source contracting is displacing fragmented spot-market purchasing for engineered wood products in German residential and commercial building. This concentration is most visible in Bavaria and Baden-Württemberg where prefabrication factories demand schedule-certain material flows.
Timber Logistics Market Segmentation
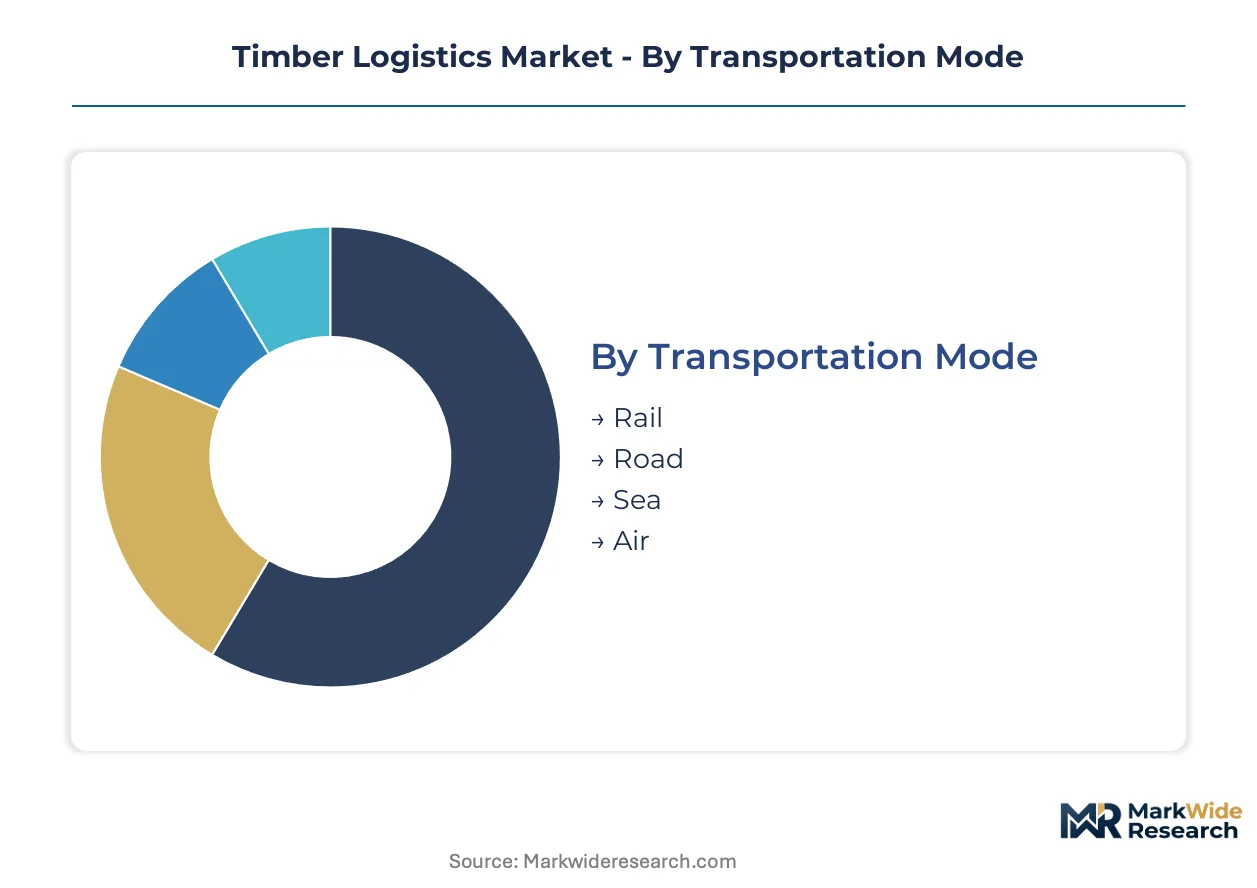
Modal specialization and certification burdens fragment carrier capabilities across timber logistics. Service differentiation hinges on matching moisture-controlled handling requirements to specific product densities and end-use quality standards.
Transportation Mode:
FSC and PEFC chain-of-custody documentation requirements vary sharply by modal infrastructure, with rail and sea offering integrated audit trails that road freight struggles to replicate.
- Rail:Unit train configurations dominate corridors exceeding 800 kilometers from Scandinavian forests to Central European mills. Deutsche Bahn's electrified network captures volume from German construction firms extending sourcing radii for engineered wood products.
- Road:Flatbed and specialized open-deck fleets handle oversized log dimensions under strict KBA weight and length enforcement. German haulers face payload efficiency caps that raise capital intensity per cubic meter moved on heavy log routes.
- Sea:Breakbulk terminal capacity at Riga, Klaipeda, and Kotka absorbs redirected volumes from congested North Sea hubs.
- Air:Premium species and high-value hardwood samples move under temperature-controlled charter arrangements for urgent mill qualification testing.
Leading the category by volume: Rail. Expanding most quickly: Sea freight on Nordic-Baltic routes.
Log Type:
Density differentials between 400 and 900 kg per cubic meter dictate load securing specifications and vehicle selection across the fleet.
- Sawn Timber:Moisture-content guarantees drive procurement consolidation among German prefabrication factories in Bavaria and Baden-Württemberg. Climate-controlled rail cars and warehousing command premium spreads where on-site seasoning capacity is absent.
- Plywood:ISPM-15 heat treatment documentation creates bottlenecks at Polish-Ukrainian border crossings. Cross-laminated timber demand from German residential construction stretches haul distances beyond unit train economic thresholds.
- Chips:Low-density bulk movements suffer direct margin erosion from diesel price volatility under weight-based pricing structures.
- Logs:Phytosanitary certification delays disrupt just-in-time schedules for Scandinavian pulp mill supply chains.
Steepest expansion trajectory: Plywood. Highest revenue concentration: Sawn timber.
Service Type:
Margin pools concentrate where automated humidity sensing and phytosanitary handling create differentiation that standard forwarding cannot replicate.
- Warehousing:Climate-controlled storage with satellite-linked inventory tracking supports EU Deforestation Regulation compliance. Polish and Czech Republic facilities capture demand from sawmills lacking on-site seasoning infrastructure.
- Freight Forwarding:Digital platforms reducing empty backhauls from Baltic ports capture unmonetized return-leg margins that traditional operators leave exposed.
- Distribution:Schedule-certain material flows dominate German construction procurement consolidation around integrated logistics-timber suppliers.
- Inventory Management:Real-time moisture monitoring and automated replenishment triggers serve prefabrication factories with narrow tolerance requirements.
Widest margin capture: Warehousing. Fastest platform adoption: Freight forwarding digitization.
End User:
Due diligence requirements from the EU Deforestation Regulation redistribute volume toward providers with verified traceability systems rather than lowest-unit-rate bidding.
- Construction Companies:Single-source contracting displaces fragmented spot-market purchasing for cross-laminated timber and glulam. German firms anchor demand concentration through extended sourcing radii and guaranteed moisture-content delivery requirements.
- Furniture Manufacturers:Blockchain-enabled provenance tracking compresses verification cycles for tropical hardwood substitutes entering EU customs zones.
- Paper Mills:Asian pulp mill demand drives fastest expansion on trans-Pacific and trans-Atlantic sea routes.
- Exporters:Scandinavian shippers pilot distributed ledger systems to overtake traditional audit-based certification methods for high-value species.
Dominant demand source: Construction companies. Fastest compliance investment: Furniture manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Kotka anchors Nordic timber flows, processing breakbulk volumes redirected from congested North Sea alternatives. German construction procurement radiates outward from Bavarian prefabrication clusters, stretching haul distances beyond unit train thresholds.
Germany
German construction firms extend sourcing radii for cross-laminated timber and glulam beyond 800 kilometers. The KBA enforces strict vehicle weight and dimension limits on heavy log hauls, capping payload efficiency. Bavarian and Baden-Württemberg prefabrication factories demand schedule-certain material flows with guaranteed moisture-content delivery.
Sweden
Scandinavian forest extraction feeds Central European mill demand through electrified rail corridors. Swedish pulp mills drive phytosanitary certification requirements that disrupt just-in-time schedules at Polish-Ukrainian border crossings. The Stockholm-Mälaren logistics cluster concentrates climate-controlled warehousing capacity for engineered wood products.
Poland
Polish sawmills absorb Nordic timber flows lacking on-site seasoning infrastructure, creating concentrated margin pools for climate-controlled storage. ISPM-15 heat treatment documentation creates bottlenecks at Ukrainian border crossings. The Silesian industrial corridor hosts expanding breakbulk terminal capacity for redirected Baltic volumes.
Latvia
Riga's breakbulk terminal expansion absorbs redirected volumes from congested North Sea hubs, creating new rail-sea intermodal economics. Small-scale Baltic forest owners face disproportionate FSC and PEFC chain-of-custody audit costs, shrinking the supplier base. The Riga Freeport zone embeds certification checkpoints within terminal operating software.
Finland
Finnish exporters pilot blockchain-enabled provenance tracking to compress verification cycles for high-value species shipments. Kotka port capacity expansion supports Russian-border alternative routing for breakbulk timber. The Helsinki-Turku corridor anchors digital freight matching platforms reducing empty backhauls from Baltic ports.
Timber Logistics Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification infrastructure and moisture-controlled handling capabilities. The market structures around integrated rail-terminal operators, specialized flatbed fleet holders, and digital freight matching platforms. Three archetypes dominate: state-affiliated rail incumbents with captive terminal networks, asset-heavy road specialists with calibrated oversized load fleets, and technology-enabled brokers compressing backhaul inefficiencies. Competitive moves concentrate on rail electrification corridor positioning and phytosanitary certification capability pre-positioning.
Among integrated rail-terminal operators, Deutsche Bahn AG exemplifies the state-affiliated archetype with captive electrified network positioning. DSV A/S and C.H. Robinson Worldwide occupy distinct tier positions—DSV representing asset-heavy specialization in oversized dimensions, C.H. Robinson anchoring digital brokerage efficiency. These three entities collectively illustrate how certification-ready infrastructure separates premium-margin capture from commodity-rate competition in EU Deforestation Regulation compliance environments.
| Leading Market Players |
|---|
| XPO Logistics |
| Rhenus Logistics |
| DHL Supply Chain |
| C.H. Robinson Worldwide |
| Deutsche Bahn AG |
| Kuehne + Nagel |
| CEVA Logistics |
| DSV A/S |
| DB Schenker |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed rail incumbents and private-equity-rolled-up road specialists anchor supply-side ownership patterns that directly discipline pricing behavior across Nordic-Baltic corridors. Deutsche Bahn's captive terminal network and DSV's calibrated flatbed fleets extract premium spreads where certification-ready infrastructure separates rate-setters from price-takers under EU Deforestation Regulation compliance timelines.
Pricing Analysis
Value-based pricing anchored to moisture-content guarantees and chain-of-custody verification commands spreads above commodity spot rates for engineered wood products. Three-tier pricing structure across certified-premium, standard-grade, and economy-bulk tiers reflects FSC/PEFC audit burden differentials and haul distance thresholds. Cost compression in economy chip movements intensifies because diesel volatility erodes weight-based margins. Small-scale Baltic forest owners exhibit highest price sensitivity due to disproportionate certification audit costs, while German prefabrication factories in Bavaria and Baden-Württemberg accept premium pricing for schedule-certain delivery.
Supply Chain Analysis
Forest extraction capacity rests on Swedish and Finnish ownership concentration, with Polish sawmills and Latvian port terminals serving as intermediate processing nodes. Roundwood, sawn timber, and engineered wood products feed from Scandinavian forest basins through electrified rail corridors and breakbulk sea terminals. Single-source vulnerability concentrates in Riga and Kotka port capacity for Russian-border alternative routing. Distribution runs through integrated rail-terminal operators, specialized flatbed fleets, and digital freight matching platforms serving Central European mill demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over certified timber sources and downstream capture of climate-controlled warehousing capacity determines margin durability. Players are pursuing captive supply of FSC/PEFC-audited forest concessions to lock in procurement access ahead of EU Deforestation Regulation enforcement deadlines.
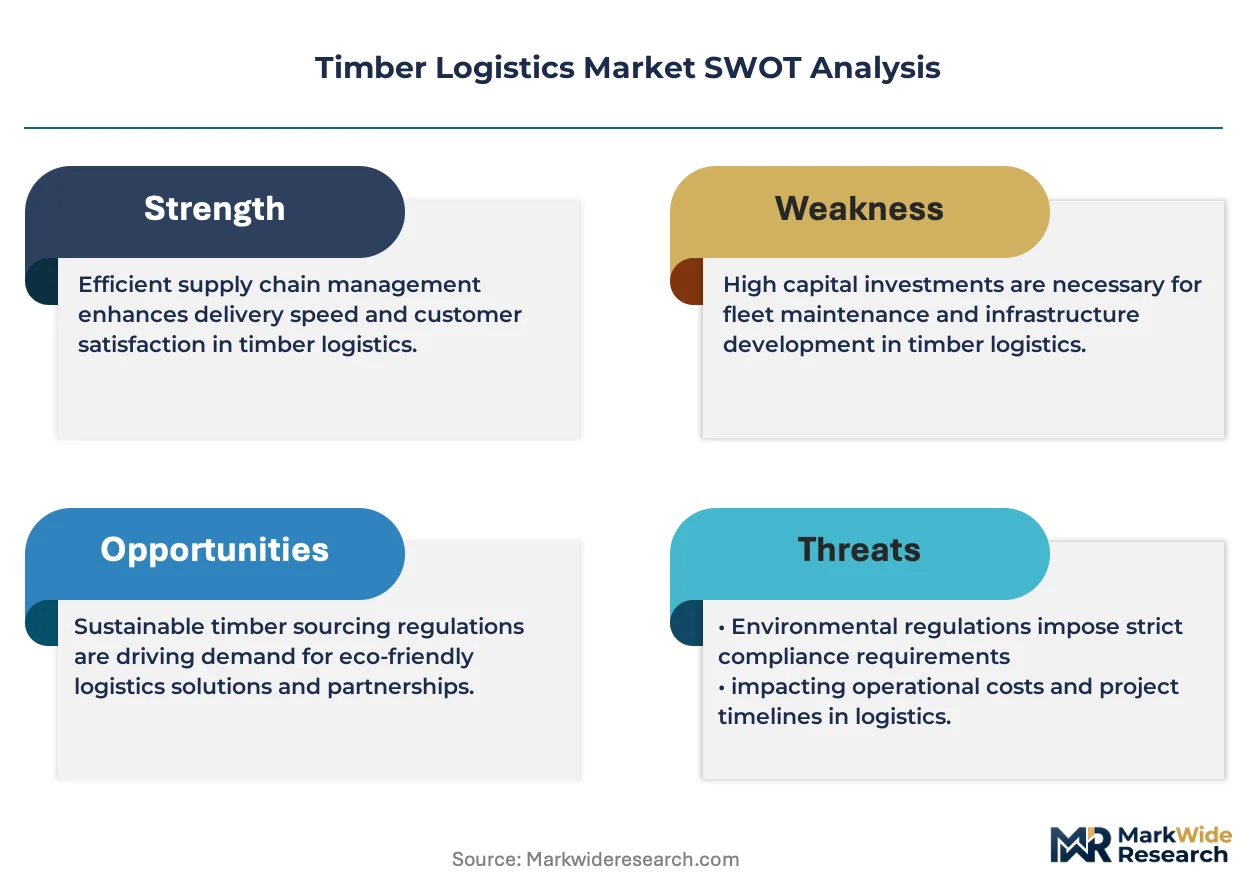
For Market Incumbents: Cement terminal operating software integration with satellite-linked inventory tracking to preempt certification checkpoint embedding at Kotka and Riga ports. Acquire distressed Baltic warehousing assets to consolidate climate-controlled storage capacity serving sawmills lacking on-site seasoning infrastructure. Deutsche Bahn's electrified network positioning and DSV's specialized fleet calibration illustrate how infrastructure pre-positioning defends against digital freight matching disruption.
For New Entrants and Emerging Players: Digital freight brokers should partner with Polish and Czech Republic sawmills seeking automated humidity sensing and phytosanitary handling capabilities. White-space concentration sits in moisture-managed storage for German prefabrication factories demanding narrow tolerance delivery. Target breakbulk terminal software integration at Klaipeda and Kotka as the most penetrable infrastructure gap, leveraging blockchain-enabled provenance tracking as differentiated go-to-market positioning.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size road operators with telematics-ready flatbed fleets in Poland and Latvia facing legacy retrofit cost burdens. Long-term viability hinges on certification infrastructure ownership rather than spot-rate commodity positioning. Acquisition targets should display integrated chain-of-custody audit trails and phytosanitary handling licenses. The signal to watch is EU Deforestation Regulation enforcement hardening that excludes non-certified suppliers from supermarket and construction retail supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Operating Software Integration | Embedding certification checkpoints at Kotka and Riga ports supports EU Deforestation Regulation compliance automation. |
| Climate-Controlled Warehousing Acquisition | Polish and Czech Republic facilities capture margin pools from sawmills lacking on-site seasoning capacity. |
| Rail Electrification Corridor Positioning | Deutsche Bahn's battery-electric locomotive conversion aligns with EU Green Deal freight decarbonization incentives. |
| Blockchain Provenance Tracking Deployment | Scandinavian exporters compress verification cycles from weeks to hours for high-value species shipments. |
| Digital Freight Matching Platform Scale-Up | Reducing empty backhauls from Baltic ports captures unmonetized return-leg margins traditional forwarders leave exposed. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this timber logistics analysis. Primary interviews with rail terminal operators, flatbed fleet managers, sawmill procurement directors, and phytosanitary certification officers combined with secondary validation from EU Timber Regulation submissions, Baltic port authority statistics, and German KBA vehicle registration databases. Bottom-up volume modeling across transportation modes and log types triangulated against top-down construction sector demand projections.
Segment-level granularity modeled transportation mode, log type, service tier, and end-user industry at country-specific resolution across the projection horizon. CAGRs derived from corridor-specific volume trends, fleet capacity utilization rates, and terminal throughput expansion schedules. Forecast inputs incorporated EU Deforestation Regulation compliance timeline assumptions, electrified rail corridor conversion capex disclosures, and breakbulk terminal capacity addition announcements at Riga, Klaipeda, and Kotka.
Caveats apply where EU Deforestation Regulation enforcement delays, phytosanitary certification bottlenecks at Polish-Ukrainian crossings, or diesel price volatility spikes could materially shift the outlook. Forecasts reflect documented assumptions about certification infrastructure deployment rates and port capacity expansion timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Dry Van Container Market
Logistics and Shipping
California Freight and Logistics Market
Logistics and Shipping
Global Sea Air Logistics Market
Logistics and Shipping
Georgia Freight and Logistics Market
Logistics and Shipping
Colombia Cold Chain Logistics Market
Logistics and Shipping
Digital Freight Matching Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
South Korea International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
Italy Cold Chain Logistics Market
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
Singapore Chemical Logistics Market
Logistics and Shipping
United States Cold Chain Logistics Market
Logistics and Shipping
Smart Container Market
Logistics and Shipping
Logistics Outsourcing Market