
 Texas Freight and Logistics Market | 2026-2036
Texas Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Texas Freight and Logistics Market Analytics
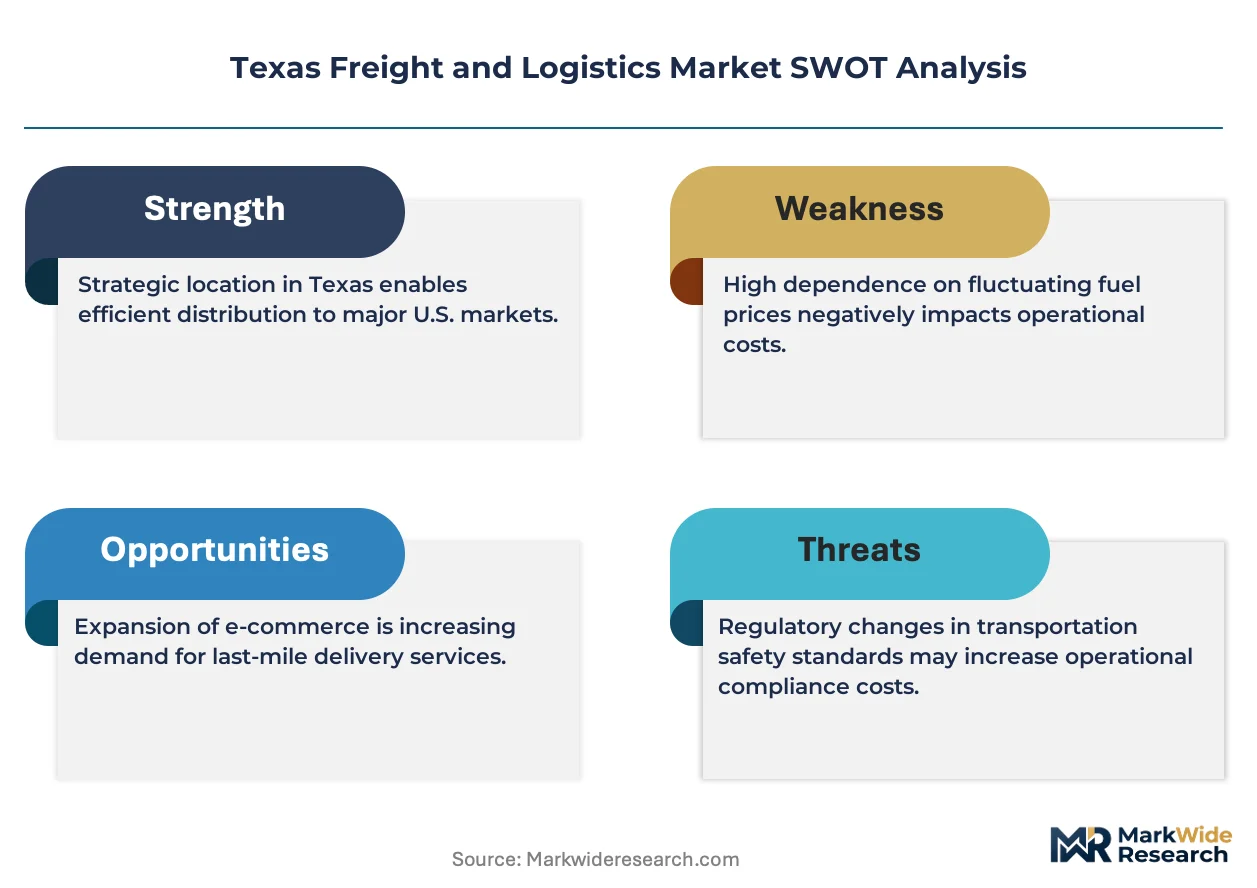
The gap between premium expedited services and commodity truckload pricing is expanding across Texas freight corridors. Schneider leverages its dedicated fleet model to sustain higher-margin contracted lanes, while J.B. Hunt Transport Services anchors intermodal volume through rail partnerships at Dallas and Houston terminals. FedEx Corporation dominates time-definite parcel networks, positioning its ground infrastructure to capture e-commerce density in Austin and San Antonio.
Texas freight and logistics encompasses the physical movement, storage, and coordination of goods across road, rail, air, and intermodal systems, typically operating through Class 8 tractors with 80,000-pound gross vehicle weight limits and temperature-controlled trailers for perishables. The primary purpose is synchronizing supply chains between Gulf Coast ports, inland distribution centers, and cross-border manufacturing nodes. Transportation services command the largest revenue pool, though warehousing is concentrating margin growth near the Port of Houston's petrochemical complex. RFID technology adoption is accelerating fastest among retail end users seeking real-time inventory visibility, while fleet management systems remain the most mature technology segment with near-universal GPS penetration.
The Federal Motor Carrier Safety Administration enforces hours-of-service rules that directly constrain driver availability and inflate spot market rates during peak agricultural harvests. The Texas Department of Transportation coordinates overweight corridor permits that shape heavy-haul routing for oilfield equipment. The Environmental Protection Agency's Phase 3 greenhouse gas standards for heavy-duty vehicles will force fleet operators to evaluate alternative powertrains ahead of compliance deadlines. Stakeholders must weigh electrification infrastructure investments against the state's prolonged freight distances and dispersed rural delivery points.
Market Dynamics
Electronic logging device mandates from the Federal Motor Carrier Safety Administration are compressing driver utilization rates and amplifying spot market volatility during peak agricultural seasons across Texas freight corridors.
Growth Catalysts
- E-commerce Fulfillment Density:Dallas-Fort Worth metroplex distribution centers are pulling refrigerated trailer demand upward as cold-chain grocery delivery expands.
- Cross-Border Manufacturing Integration:Laredo-Nuevo Laredo freight corridors are absorbing maquiladora output from Mexican industrial parks.
- FMCSA Compliance Technology:Fleet telematics adoption is accelerating as hours-of-service enforcement tightens driver scheduling flexibility.
Market Restraints
- Diesel Price Volatility:Fuel represents 25-30% of operating costs for Class 8 fleets, with price spikes transmitted directly to shippers through fuel surcharge mechanisms.
- Driver Pool Contraction:Commercial driver's license issuance rates lag retirement outflows, constraining capacity expansion regardless of equipment availability.
- EPA Phase 3 Standards:Greenhouse gas regulations for heavy-duty vehicles are forcing premature powertrain evaluation against Texas's extended haul distances.
Strategic Opportunities
- Rio Grande Valley Agricultural Logistics:Perishable produce corridors remain underserved by temperature-controlled intermodal infrastructure.
- Port of Houston Petrochemical Warehousing:Hazardous materials storage capacity is concentrating margin capture near Gulf Coast processing clusters.
- Alternative Powertrain Infrastructure:Electric charging corridors along I-35 and I-10 could anchor fleet electrification pilots ahead of compliance deadlines.
Industry Challenges
- Telematics Integration Complexity:Legacy dispatch systems require costly retrofitting to synchronize with FMCSA-mandated electronic logging platforms.
- Specialized Equipment Lead Times:Refrigerated trailer manufacturing backlogs are extending procurement cycles for perishable shippers beyond seasonal windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Texas Freight and Logistics Market |
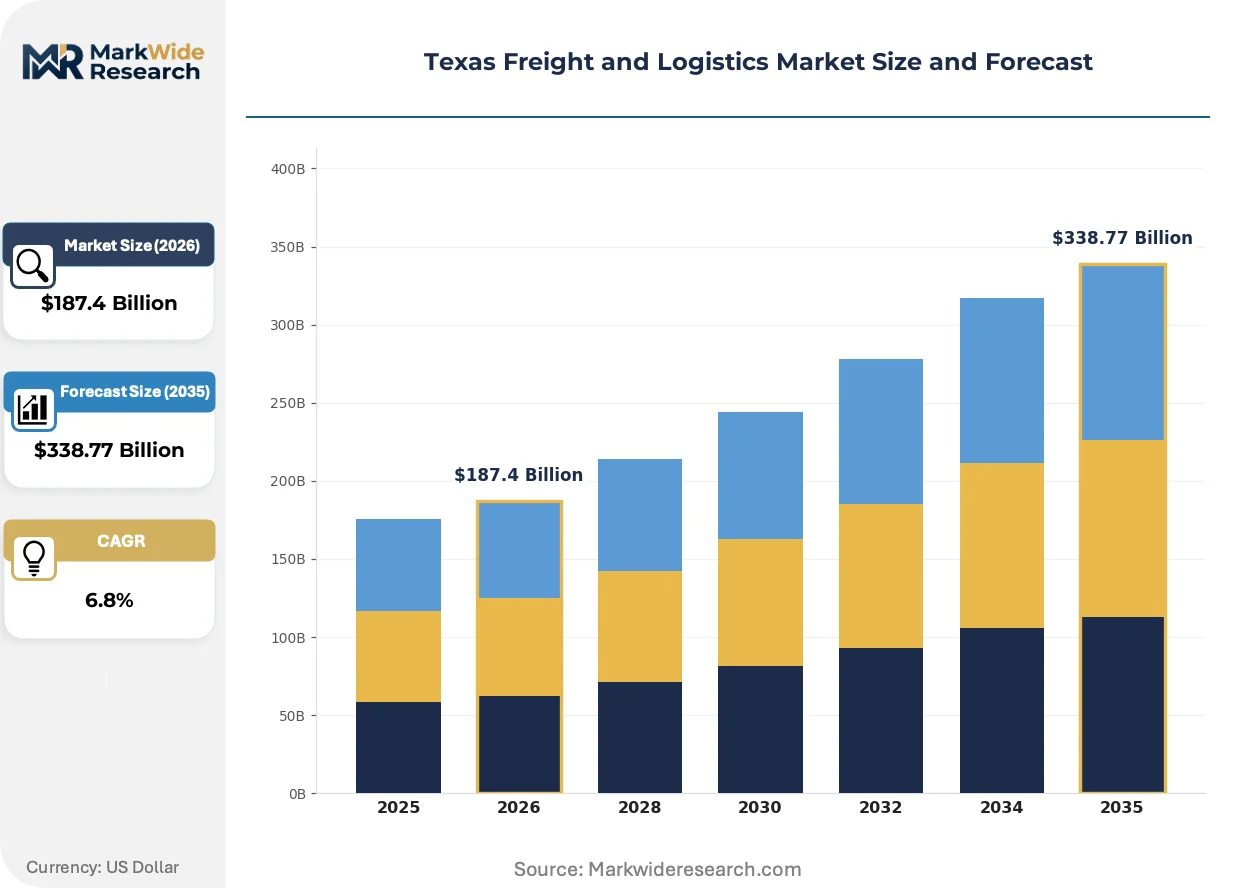
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Freight Forwarding End User: Manufacturers, Retailers, E-commerce, Agriculture Technology: RFID, GPS Tracking, Fleet Management, Automation Vehicle Type: Trucks, Trailers, Railcars, Air Freight |
| Companies Covered | Schneider, CH Robinson Worldwide, FedEx Corporation, J.B. Hunt Transport Services, XPO Logistics, UPS Inc., Penske Logistics, Ryder System, Total Quality Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Texas Freight and Logistics Market Evolving Landscape
Digital freight matching platforms are compressing broker margins while RFID inventory tracking is penetrating retail distribution networks. Fleet operators are recalibrating asset deployment around real-time demand signals rather than contracted lane commitments.
Battery-electric Class 8 tractors are electrifying terminal-to-terminal drayage operations at Houston and Dallas intermodal yards. Regional grocers are piloting short-haul electric fleets for urban last-mile delivery. The technology is electrifying fleet composition strategies despite range limitations on Texas's extended rural corridors.
The Environmental Protection Agency's Phase 3 greenhouse gas standards are mandating powertrain efficiency improvements for heavy-duty vehicles. Fleet operators must evaluate compressed natural gas and battery-electric alternatives against diesel baseline economics. Refrigerated carriers face disproportionate compliance pressure due to auxiliary power unit emissions profiles.
Shippers are consolidating freight procurement through digital brokerage platforms that disintermediate traditional 3PL relationships. Mid-sized manufacturers are bypassing contracted lane agreements in favor of spot market flexibility. This pattern concentrates among Austin and San Antonio e-commerce fulfillment networks seeking dynamic capacity matching.
Texas Freight and Logistics Market Segmentation
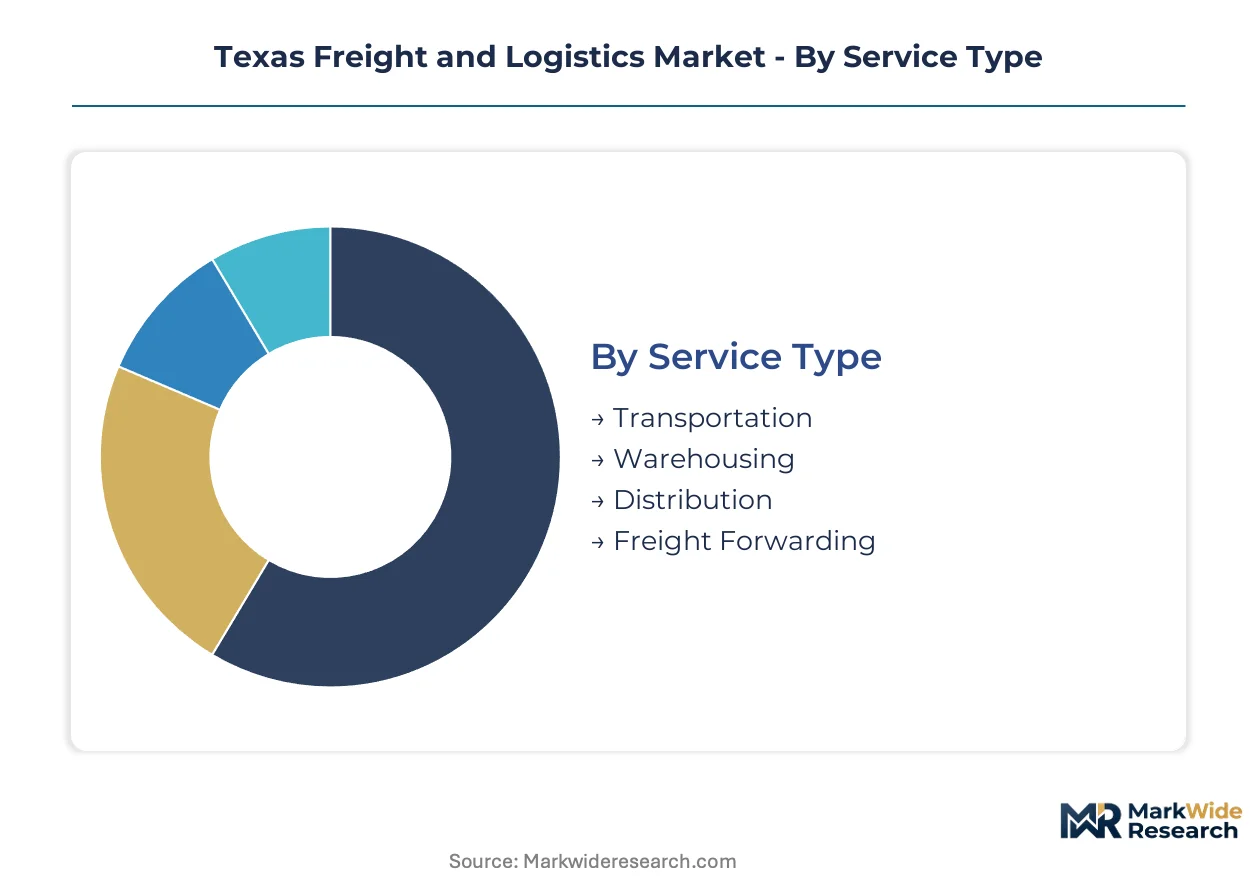
Service configuration in Texas freight and logistics determines capital intensity and margin capture. Segment boundaries reflect how shippers bundle physical movement with storage and coordination services.
Service Type:
Standalone transportation services operate independently from embedded warehousing and distribution functions.
- Transportation:Road-based freight movement using Class 8 tractors and specialized trailers dominates revenue pools. Demand concentrates along I-35 and I-10 corridors connecting Dallas-Fort Worth distribution hubs to Gulf Coast ports, with cross-border lanes to Laredo absorbing maquiladora output.
- Warehousing:Temperature-controlled and hazardous materials storage facilities anchor margin growth near Port of Houston petrochemical clusters. Cold-chain capacity is tightening around Dallas-Fort Worth e-commerce fulfillment centers as grocery delivery expands.
- Distribution:Last-mile consolidation and cross-docking operations synchronize inventory flow between regional fulfillment nodes.
- Freight Forwarding:Customs brokerage and cross-border documentation services facilitate Laredo-Nuevo Laredo trade corridors.
Volume placements concentrate in Transportation; the faster expansion belongs to Warehousing.
End User:
Customer scale and order frequency shape service tier selection across the Texas freight network.
- Manufacturers:Industrial shippers demand contracted lane commitments and dedicated fleet capacity for predictable production schedules. Automotive and electronics producers near Austin and San Antonio anchor high-frequency freight corridors.
- E-commerce:Digital retailers require dynamic capacity matching and time-definite delivery windows. Dallas-Fort Worth metroplex distribution density is pulling refrigerated trailer demand upward for cold-chain grocery fulfillment.
- Retailers:Big-box and specialty stores rely on consolidated procurement through regional distribution centers.
- Agriculture:Perishable produce shippers in the Rio Grande Valley face compressed seasonal windows and temperature-controlled equipment scarcity.
Manufacturers command the largest contract volumes; E-commerce is climbing the fastest on fulfillment density.
Technology:
Technology deployment spans standalone visibility tools and integrated fleet management platforms.
- Fleet Management:GPS tracking, route optimization, and driver scheduling systems have achieved near-universal penetration among Texas-based carriers. FMCSA electronic logging device mandates are compressing utilization rates and amplifying spot market volatility.
- RFID:Radio-frequency identification enables real-time inventory visibility across retail distribution networks. Adoption is accelerating fastest among grocery and consumer goods end users seeking warehouse-to-shelf traceability.
- GPS Tracking:Asset location monitoring supports theft prevention and customer notification systems.
- Automation:Warehouse robotics and autonomous yard trucks are piloting at Houston and Dallas intermodal terminals.
Fleet Management captures the deepest installed base; RFID is gaining share fastest on retail compliance requirements.
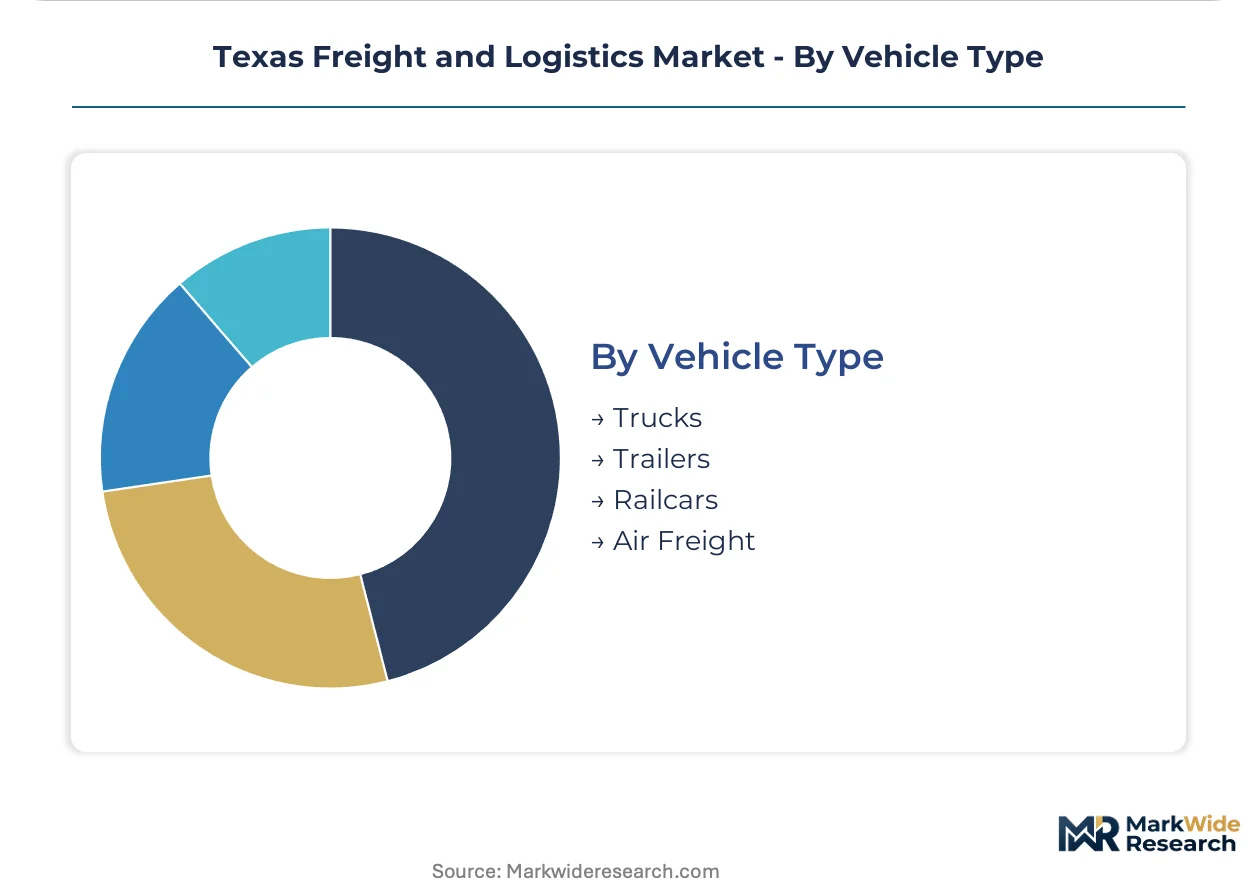
Vehicle Type:
Asset class selection reflects haul distance, cargo characteristics, and infrastructure availability.
- Trucks:Class 8 tractors with 80,000-pound gross vehicle weight limits form the backbone of Texas freight movement. Diesel powertrains dominate though EPA Phase 3 standards are forcing premature evaluation of compressed natural gas and battery-electric alternatives.
- Trailers:Dry van, refrigerated, and flatbed configurations match cargo requirements. Refrigerated trailer manufacturing backlogs are extending procurement cycles for perishable shippers beyond seasonal windows.
- Railcars:Intermodal containers and bulk commodity cars anchor long-haul economics on Dallas and Houston terminal corridors.
- Air Freight:Time-definite express shipments concentrate at Dallas-Fort Worth International and Houston George Bush Intercontinental airports.
Trucks dominate total fleet deployment; battery-electric variants within this category are expanding most quickly on drayage pilot programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors freight demand across Texas, with distribution centers concentrating refrigerated trailer deployment for e-commerce fulfillment networks.
Houston-Gulf Coast
Port of Houston petrochemical throughput drives hazardous materials warehousing expansion. EPA Phase 3 greenhouse gas standards force fleet operators to evaluate alternative powertrains against extended haul distances. The Houston Ship Channel corridor concentrates temperature-controlled storage capacity near Gulf Coast processing clusters.
San Antonio-Austin Corridor
Automotive and electronics manufacturers anchor high-frequency freight lanes between Austin semiconductor fabs and San Antonio assembly plants. FMCSA electronic logging device mandates compress driver utilization rates during peak production cycles. The I-35 corridor between these metros absorbs dedicated fleet capacity for just-in-time delivery schedules.
Laredo Border Region
Maquiladora output from Nuevo Laredo industrial parks generates concentrated cross-border truckload demand. US Customs and Border Protection documentation requirements shape freight forwarding service tiers. The Laredo-Colombia Solidarity International Bridge corridor represents the densest northbound freight flow from Mexican manufacturing hubs.
Rio Grande Valley
Perishable produce shippers face compressed seasonal windows and temperature-controlled equipment scarcity during harvest peaks. Texas Department of Transportation overweight corridor permits shape heavy-haul routing for agricultural machinery. McAllen and Brownsville distribution nodes remain underserved by intermodal cold-chain infrastructure.
Midland-Odessa Permian Basin
Oilfield equipment movements require specialized heavy-haul permits across dispersed rural delivery points. FMCSA hours-of-service rules constrain driver availability during drilling activity surges. The Permian Basin energy corridor generates irregular demand spikes for flatbed and oversized load capacity.
Texas Freight and Logistics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service tier differentiation, with dedicated fleet operators capturing contracted lane premiums while spot market brokers compress margins through digital matching platforms. The vendor base stratifies between asset-heavy integrated carriers and asset-light logistics intermediaries. Three archetypes dominate: integrated trucking-intermodal hybrids, pure-play freight brokers, and specialized temperature-controlled operators. Capacity expansion through refrigerated trailer procurement and strategic partnerships with rail terminals constitute the dominant competitive moves.
Within the integrated carrier tier, Schneider and J.B. Hunt Transport Services exemplify asset-heavy positioning through dedicated fleet and intermodal rail partnerships. FedEx Corporation anchors time-definite parcel networks, representing premium service tier capture in urban last-mile density. These three players occupy distinct competitive positions without overlapping core service configurations.
| Leading Market Players |
|---|
| Schneider |
| CH Robinson Worldwide |
| FedEx Corporation |
| J.B. Hunt Transport Services |
| XPO Logistics |
| UPS Inc. |
| Penske Logistics |
| Ryder System |
| Total Quality Logistics |
| Others |
Value Network & Pricing Analysis
Commercial driver's license holders concentrated across the Dallas-Fort Worth metroplex and Houston-Gulf Coast corridor command wage premiums that widen spreads between dedicated fleet contracted rates and spot market broker pricing. Labor-cost differentials between unionized LTL terminals and non-union truckload operators translate directly into three-tier pricing stratification across expedited, standard, and economy service levels.
Pricing Analysis
Value-based pricing anchored to on-time performance guarantees and cargo integrity outcomes dominates premium service tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates based on equipment age, driver experience certification, and fuel surcharge pass-through mechanisms. Cost compression in the spot broker tier is intensifying because digital freight matching platforms disintermediate traditional 3PL relationships. E-commerce shippers exhibit highest price sensitivity due to thin fulfillment margins, while petrochemical manufacturers demonstrate lowest sensitivity given hazardous materials compliance requirements.
Supply Chain Analysis
Freight cost escalation along cross-border corridors shapes sourcing decisions for manufacturers with maquiladora integration. Equipment manufacturing concentrates in Mexico, China, and the United States; diesel fuel supply rests on Gulf Coast refinery output and global crude differentials. Single-source vulnerability pervades refrigerated trailer procurement due to concentrated domestic manufacturing capacity. Distribution runs through Dallas-Fort Worth consolidation hubs before final-mile deployment to Austin, San Antonio, and Rio Grande Valley endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EPA Phase 3 compliance costs and telematics integration complexity force sub-scale operators toward exit or acquisition.
For Market Incumbents: Deepen dedicated fleet penetration along I-35 and I-10 corridors to lock in contracted lane premiums before digital brokers capture share. Acquire refrigerated trailer assets ahead of seasonal demand peaks to exploit manufacturing backlogs. Electronic logging device mandate enforcement represents the primary regulatory threat compressing utilization rates. For New Entrants and Emerging Players: Digital freight brokerage platforms offer the most viable entry vector for asset-light operators seeking to bypass legacy dispatch system investments. Target Rio Grande Valley perishable corridors where temperature-controlled intermodal infrastructure remains underserved. Lead with dynamic capacity matching tools that synchronize with FMCSA hours-of-service constraints. For Investors and Strategic Acquirers: Re-rating potential sits with specialized temperature-controlled operators given cold-chain grocery delivery expansion and refrigerated equipment scarcity. Long-term viability favors asset-heavy models with rail terminal partnerships and captive driver development programs. Watch for inflection in electric charging corridor deployment along I-35 as signal for alternative powertrain transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerated Fleet Expansion | Captures margin concentration near Dallas-Fort Worth e-commerce fulfillment centers. |
| Rail Terminal Partnership | Anchors intermodal economics for J.B. Hunt and Schneider against diesel volatility. |
| Digital Brokerage Platform Launch | Disintermediates traditional 3PL relationships through real-time capacity matching. |
| Electric Drayage Pilot Program | Positions operators ahead of EPA Phase 3 compliance deadlines at Houston terminals. |
| Cross-Border Customs Integration | Streamlines Laredo-Nuevo Laredo freight forwarding through documentation automation. |
Research Methodology
FMCSA regulatory filings, Texas Department of Transportation corridor permit databases, and EPA heavy-duty vehicle standards documentation formed the secondary backbone for this analysis. Primary interviews with fleet operations directors, refrigerated carrier dispatch managers, and cross-border customs brokers validated demand assumptions. Shipper procurement leads at Dallas-Fort Worth distribution centers and Houston petrochemical processors provided contract lane pricing color. Bottom-up and top-down triangulation reconciled equipment count estimates with freight volume flows.
Bottom-up modeling anchored projections while top-down macroeconomic validation tested sensitivity to diesel price and driver wage trajectories across the analysis window. Segmentation dimensions included service type, end-user industry, technology deployment, and vehicle powertrain configuration. CAGRs derived from historical freight volume growth rates adjusted for e-commerce penetration and cross-border manufacturing integration. Forecast inputs incorporated FMCSA enforcement intensity assumptions and refrigerated trailer manufacturing capacity constraints.
The model holds under stable regulatory enforcement and diesel price bands; deviation in EPA Phase 3 implementation timing or driver shortage severity would shift trajectory. Forecasts reflect documented assumptions about e-commerce fulfillment density and maquiladora output growth. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Japan Freight and Logistics Market
Logistics and Shipping
Philippines Freight and Logistics Market
Logistics and Shipping
China Automotive Logistics Market
Logistics and Shipping
Italy Apparel Logistics Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
Terminal Tractors Market
Logistics and Shipping
Carrier-Agnostic Parcel and Freight Visibility Aggregation Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
GCC Event Logistics Market
Logistics and Shipping
Singapore Chemical Logistics Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
Sri Lanka Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market
Logistics and Shipping
Asia-Pacific Container Drayage Market