
 Steel Pipes and Tubes Market | 2026-2036
Steel Pipes and Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Pipes and Tubes Market Intelligence
REACH compliance is expanding the cost-of-entry calculus for European steel pipe exporters, forcing mills to certify full material traceability and restricted substance thresholds. ArcelorMittal leverages its integrated flat-rolled supply chain to control substrate costs for welded pipe production. Nippon Steel Corporation anchors high-margin seamless OCTG output through proprietary hot-rolling expertise. Tenaris competes on API threading technology and global threading facility placement.
Steel pipes and tubes are hollow cylindrical sections manufactured from carbon steel, stainless steel, or alloy grades through seamless extrusion or welded rolling processes, typically specified by outer diameter, wall thickness, and yield strength ratings for pressure containment. Their primary purpose is to transport fluids, gases, and structural loads across energy, construction, and mechanical systems. Seamless pipe commands premium positioning in high-pressure oil and gas environments where defect tolerance approaches zero, while welded pipe dominates infrastructure and construction volume through cost-efficient coil-to-pipe manufacturing. Stainless steel grades are capturing margin pools in chemical processing and desalination applications where chloride corrosion resistance determines replacement cycles.
The US EPA enforces leak detection and repair mandates that accelerate replacement of aging pipeline networks with certified higher-grade materials. India's BIS imposes mandatory quality control orders on carbon steel tubes for structural and plumbing uses, reshaping import eligibility for non-certified suppliers. China's GB standards and dual carbon goals are pressuring domestic mills to decarbonize electric-arc furnace operations. Stakeholders must monitor how carbon border adjustments and evolving pressure-equipment directives redefine competitive access across major demand centers.
Market Dynamics
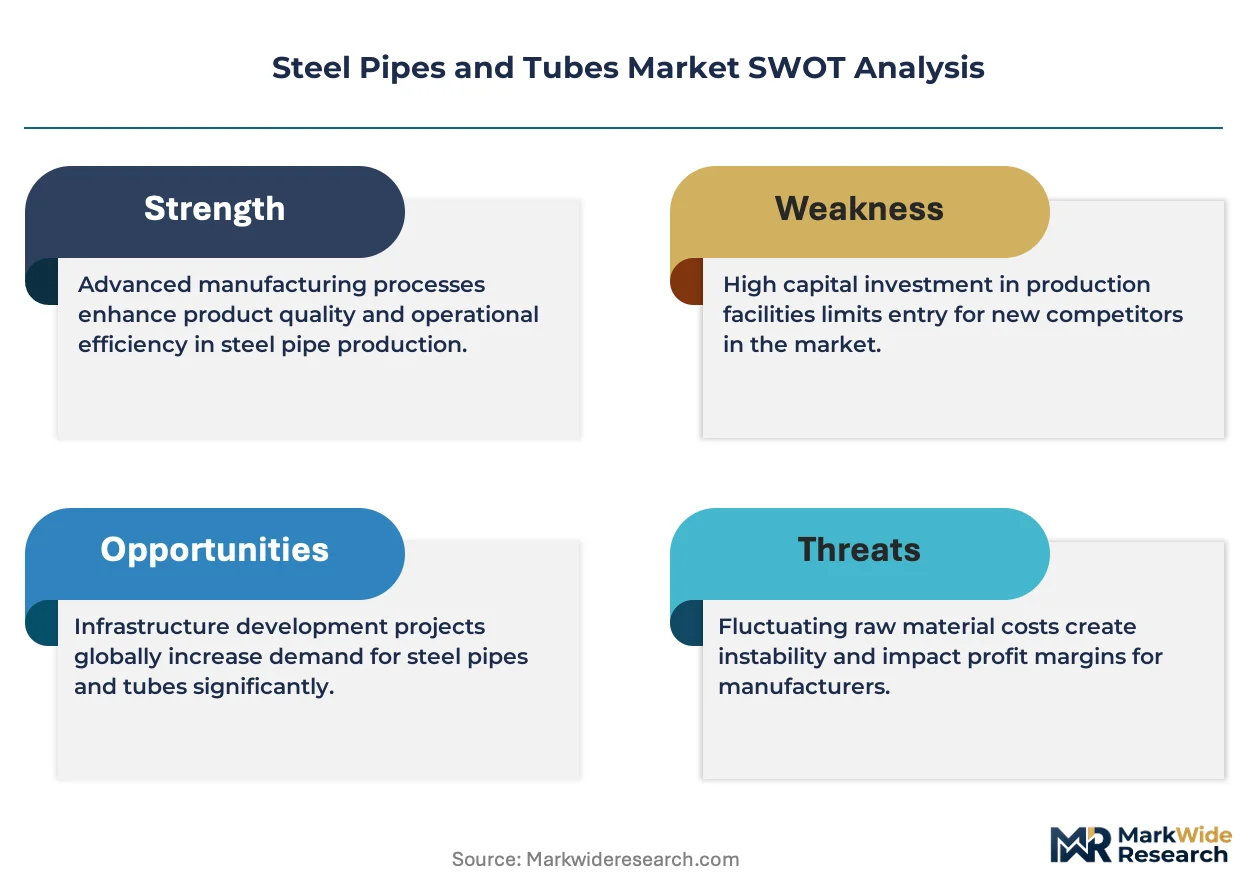
API 5L and ASME standards are tightening wall-thickness tolerances and hydrostatic test requirements, forcing mills to retool quality systems and scrap rates upward while sour-service alloy premiums widen.
Growth Catalysts
- India's pipeline infrastructure buildout:The government's refinery expansion and cross-country crude and gas networks are accelerating orders for large-diameter welded pipe. State-owned energy majors dominate tender volumes.
- REACH compliance expansion:European material traceability mandates are filtering out uncertified exporters and consolidating procurement toward integrated mills with captive metallurgical labs.
- Seamless OCTG hot-rolling advances:Proprietary piercing and elongation processes are extending defect-free lengths for high-pressure sour wells, capturing premium positioning in offshore environments.
Market Restraints
- Scrap and iron ore cost volatility:Electric-arc furnace operators face margin compression when ferrous scrap spreads widen against hot-rolled coil benchmarks.
- Supply concentration in China:Domestic GB-standard mills control over half of global welded pipe capacity, creating price-discovery asymmetry for importers.
- Composite pressure piping substitution:Reinforced thermoplastic lines are displacing carbon steel in corrosive gathering systems and water injection networks.
Strategic Opportunities
- Hydrogen transmission infrastructure:Germany's F-Gas Regulation phase-down and hydrogen backbone plans are creating demand for hydrogen-certified large-diameter pipe with specialized coating systems.
- Desalination stainless expansion:Super-duplex and 6Mo grades are capturing replacement cycles in Middle Eastern thermal desalination plants where chloride attack determines asset life.
- Digital thread integration:Blockchain-based mill test certificate verification is automating customs clearance and reducing documentary fraud in cross-border OCTG trade.
Industry Challenges
- Welding procedure qualification bottlenecks:API 1104 and ASME Section IX certification timelines stretch 12-18 months for exotic alloy positions, delaying project mobilization.
- Legacy ERP integration with traceability platforms:Mid-tier mills struggle to retrofit material genealogy systems onto decades-old production planning software without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Pipes and Tubes Market |
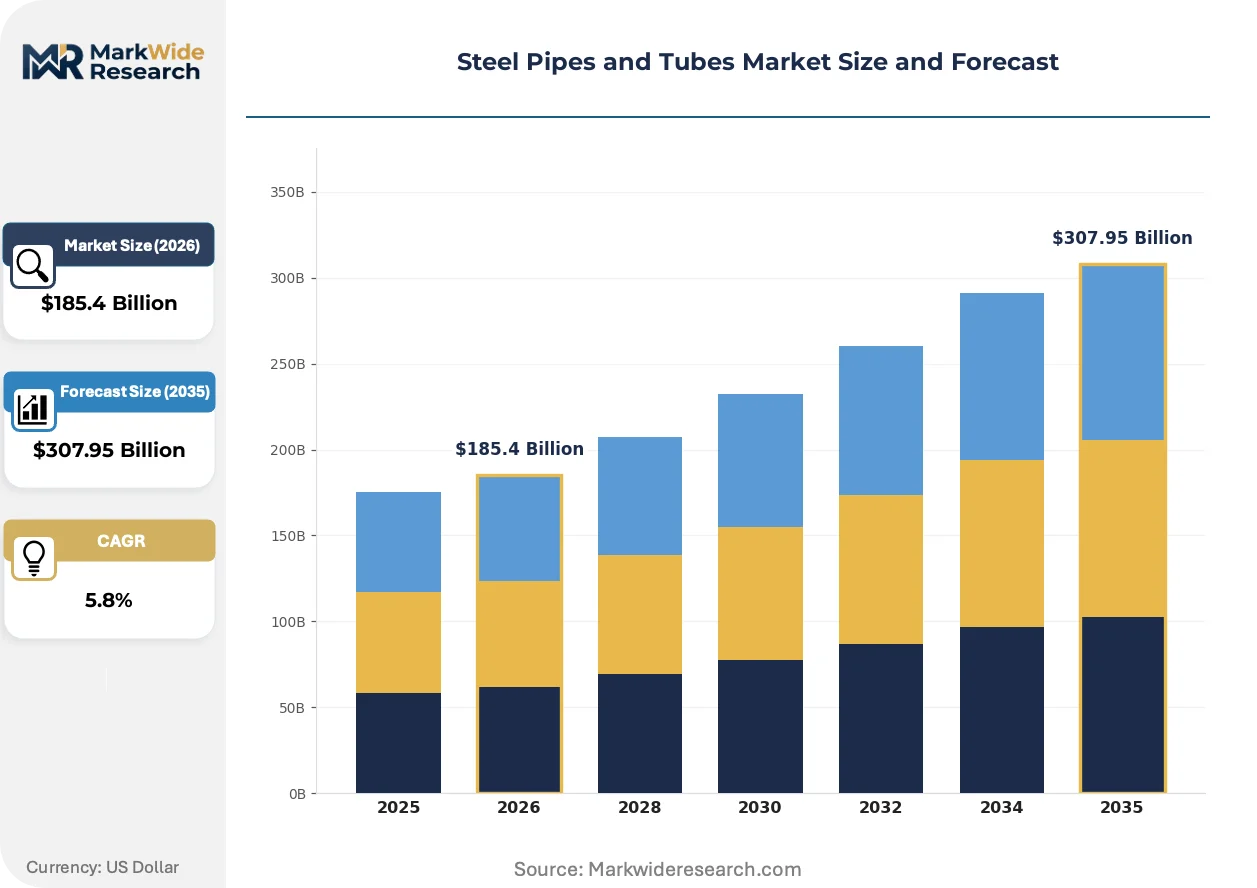
| Market Size in 2026 | $185.4 Billion |
| Market Size in 2035 | $307.95 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless, Welded, ERW, API Application: Construction, Automotive, Oil & Gas, Infrastructure End User: Manufacturers, Distributors, Contractors, Utilities Material Grade: Low Carbon, High Carbon, Stainless Steel, Alloy |
| Companies Covered | ArcelorMittal, Nippon Steel Corporation, United States Steel Corporation, Tata Steel, JFE Steel Corporation, Tenaris, Vallourec, EVRAZ plc, Steel Authority of India Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Pipes and Tubes Market Strategic Shifts & Innovations
Automation of inline inspection and predictive maintenance is compressing defect escape rates and extending asset life, while regulatory carbon accounting and buyer procurement centralization reshape competitive access.
Ultrasonic phased-array testing coupled with machine vision is automating weld seam inspection at speeds exceeding 3 meters per second. Offshore pipeline contractors in the North Sea and Gulf of Mexico are mandating these systems for sour-service line pipe acceptance. The technology is automating the elimination of manual radiographic interpretation delays and reducing third-party inspection headcount.
The US EPA's methane leak detection and repair mandates are accelerating replacement of pre-1990 vintage gathering lines with certified higher-grade materials. Operators must demonstrate material traceability and pressure-test documentation for entire replaced segments. Onshore shale basins in Texas and North Dakota face the steepest compliance timelines and scrap-disposal volumes.
Consolidated procurement through integrated energy majors is displacing fragmented distributor purchasing for standard carbon grades. National oil companies in India and Brazil now issue multi-year framework agreements with volume commitments and fixed pricing bands. This concentration is most visible in large-diameter line pipe where tender sizes exceed single-mill annual capacity, forcing consortium bidding.
Steel Pipes and Tubes Market Segmentation
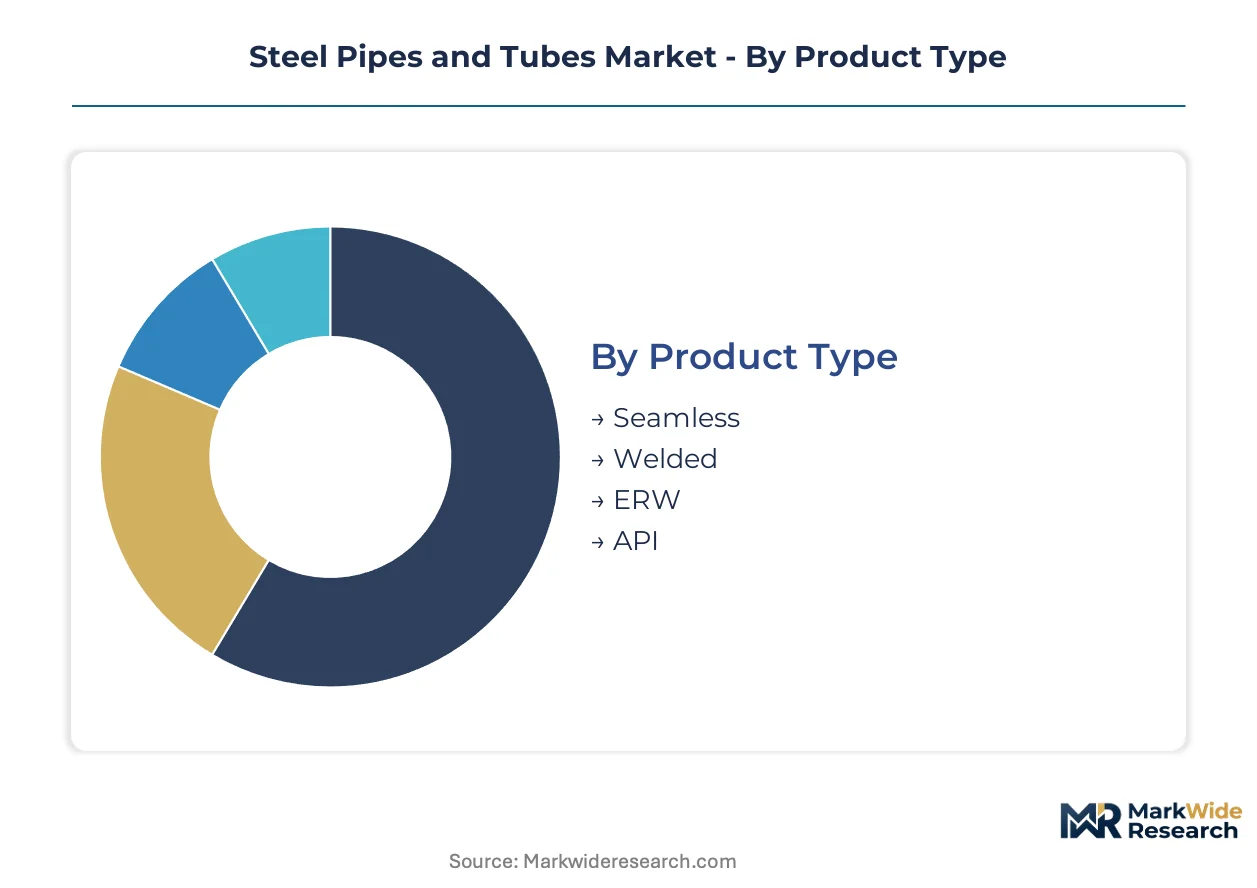
Segmentation in steel pipes and tubes separates high-specification pressure containment products from commodity structural grades. Buyers differentiate on defect tolerance, corrosion resistance, and certification requirements rather than price alone.
Product Type:
Buyers in this category separate on pressure rating tolerance and defect sensitivity rather than unit cost.
- Seamless:Manufactured through hot rotary piercing and elongation without longitudinal welds, achieving uniform grain structure through wall thickness. Demand concentrates in offshore oil and gas developments where sour-service hydrogen sulfide exposure requires zero-defect integrity. API 5CT certification and proprietary hot-rolling expertise determine supplier selection.
- Welded:Formed from hot-rolled coil through electric resistance or submerged arc processes, with seam integrity verified by ultrasonic testing. Infrastructure buildouts in India and Middle Eastern desalination plants drive volume procurement of large-diameter line pipe. Cost efficiency versus seamless alternatives dominates tender evaluation.
- ERW:Electric resistance welding joins skelp edges under pressure and current, producing dimensional precision for mechanical tubing applications.
- API:Threaded and coupled configurations meeting American Petroleum Institute specifications for downhole casing and tubing strings.
Volume sits with Welded; growth tilts toward Seamless.
Application:
Application segmentation tracks load-bearing requirements against fluid containment specifications.
- Oil & Gas:Gathering lines, transmission pipelines, and downhole tubulars face sour-service corrosion and high-pressure cycling. North Sea and Gulf of Mexico operators mandate phased-array ultrasonic inspection for line pipe acceptance.
- Construction:Structural hollow sections for building frames and piling applications prioritize yield strength consistency and dimensional tolerance over pressure ratings.
- Automotive:Chassis components and exhaust systems require tight diameter tolerances and surface finish quality for robotic assembly integration.
- Infrastructure:Water transmission, sewage systems, and bridge construction deploy cement-lined or coated carbon grades for durability in buried environments.
Construction commands current volume; Oil & Gas captures the steepest expansion trajectory.
End User:
End user categories reflect procurement sophistication and inventory carrying capacity.
- Utilities:State-owned energy majors and water authorities issue multi-year framework agreements with volume commitments and fixed pricing bands.
- Contractors:Project-specific purchasing for construction and pipeline installation depends on just-in-time delivery and certification documentation.
- Manufacturers:OEMs of automotive components and industrial equipment specify custom lengths and surface treatments for downstream fabrication.
- Distributors:Stocking intermediaries consolidate fragmented demand from maintenance, repair, and small-project customers.
Utilities anchor procurement scale; Manufacturers drive specification complexity.
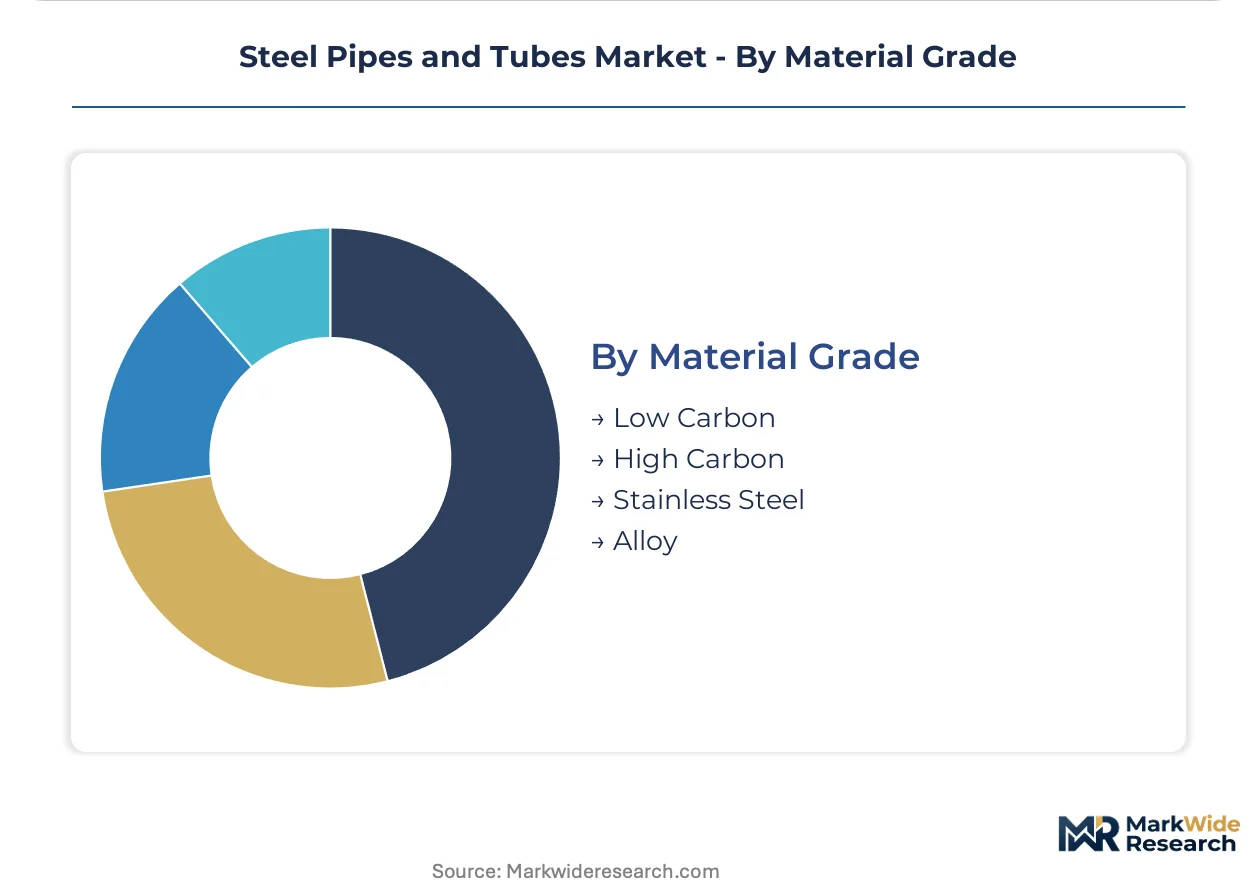
Material Grade:
Material selection balances corrosion environment severity against capital cost constraints.
- Stainless Steel:Austenitic and duplex grades resist chloride attack in desalination plants and chemical processing. Middle Eastern thermal desalination replacement cycles favor super-duplex and 6Mo super-austenitic compositions for extended asset life.
- Alloy:Chromium-molybdenum and nickel-based grades withstand high-temperature hydrogen service in refinery and petrochemical reactors.
- Low Carbon:Mild steel grades for structural and plumbing applications face mandatory BIS quality control orders in India, filtering import eligibility.
- High Carbon:Elevated carbon content provides hardness for mechanical tubing and pressure vessel applications requiring heat treatment response.
Low Carbon dominates shipment tonnage; Stainless Steel gains share fastest on replacement cycle extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Petroleum, Chemicals and Petrochemicals Investment Regions and Saudi Arabia's Jubail Industrial City concentrate steel pipe demand through refinery-pipeline clusters and tax-advantaged manufacturing zones.
United States
Shale operators in the Permian Basin and Bakken formation are replacing pre-1990 vintage gathering lines under EPA methane leak detection mandates. The EPA enforces material traceability and pressure-test documentation for entire replaced segments. Houston-Galveston anchors OCTG threading and coating facility concentration for Gulf of Mexico offshore projects.
India
State-owned energy majors are issuing multi-year framework agreements for large-diameter line pipe as cross-country crude and gas networks expand. The BIS imposes mandatory quality control orders on carbon steel tubes for structural and plumbing uses, filtering import eligibility. Gujarat's Dahej PCPIR and Maharashtra's Ratnagiri cluster concentrate welded pipe fabrication capacity near refinery sites.
China
Domestic GB-standard mills control over half of global welded pipe capacity, creating price-discovery asymmetry for importers. The MIIT and MEE are pressuring mills to decarbonize electric-arc furnace operations under dual carbon goals. Tangshan and Tianjin anchor the northern concentration of coil-to-pipe manufacturing infrastructure.
Germany
Hydrogen backbone plans under the EU Green Deal and F-Gas Regulation phase-down are creating demand for hydrogen-certified large-diameter pipe with specialized coating systems. REACH compliance mandates full material traceability and restricted substance thresholds for European exporters. Duisburg-Ruhr and Bremen harbor zones concentrate steel service center and pipe coating operations.
Saudi Arabia
Thermal desalination plant replacement cycles favor super-duplex and 6Mo stainless grades for extended asset life against chloride attack. The SFDA and national procurement frameworks emphasize certified sour-service alloy specifications for oilfield tubulars. Jubail Industrial City hosts integrated seamless pipe production and downstream coating facilities serving Eastern Province oilfields.
Steel Pipes and Tubes Market Key Industry Players
European integrated mills anchor one tier through captive metallurgical labs and REACH-certified traceability systems; Asian coil-based specialists hold volume positioning through electric-arc furnace cost structures. The vendor base separates into three strategic archetypes: flat-rolled integrated players controlling substrate costs, seamless OCTG specialists with proprietary hot-rolling expertise, and welded pipe fabricators competing on coil procurement and seam inspection automation. Dominant competitive moves include backward integration into scrap and DRI supply, and capacity placement near demand clusters through greenfield threading facilities.
Among European-integrated producers, ArcelorMittal represents the flat-rolled supply chain archetype, while Vallourec occupies a position within the seamless premium tier. Nippon Steel Corporation exemplifies the hot-rolling expertise model for defect-sensitive sour-service applications. These three anchors illustrate how geographic origin and manufacturing structure determine competitive positioning without requiring specific product or technology claims.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nippon Steel Corporation |
| United States Steel Corporation |
| Tata Steel |
| JFE Steel Corporation |
| Tenaris |
| Vallourec |
| EVRAZ plc |
| Steel Authority of India Limited |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between API 5L sour-service seamless pipe and commodity welded structural grades manifests in divergent pricing power and supply chain configurations. Premium seamless OCTG commands extended lead times and dedicated metallurgical lab capacity, while commodity welded product flows through coil-proximate electric-arc furnace mills with minimal traceability overhead.
Pricing Analysis
Short lead-time premiums for API-certified sour-service seamless pipe widen against spot inventory discounts for standard carbon grades. Three-tier pricing structure across premium seamless OCTG, mid-grade line pipe, and economy structural tubing reflects certification burden and defect-tolerance thresholds. Cost compression in welded commodity segments intensifies as Chinese GB-standard mills expand electric-arc furnace capacity. Distributor buyers exhibit highest price sensitivity for standard mechanical tubing, while national oil companies accept premium positioning for hydrogen-certified large-diameter pipe.
Supply Chain Analysis
Scrap metal returns and coil edge trim refurbishment feed circular material flows back into electric-arc furnace charge mixes. Manufacturing gravity centers on China, India, and the United States for welded pipe, with seamless concentration in Japan, Germany, and Saudi Arabia. Ferrous scrap, hot-rolled coil, and nickel alloy inputs anchor cost structures. Single-source vulnerability concentrates in Chinese coil supply for Asian welded pipe fabricators. Distribution runs through integrated energy major procurement desks and regional steel service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive position in this market is consolidating around backward integration into scrap, DRI, and captive threading capacity as the decisive upstream lever.
For Market Incumbents: Deploy captive metallurgical laboratory certification to defend API 5CT positioning against emerging seamless specialists in India and the Middle East. Reinforce threading facility placement near Gulf of Mexico and North Sea demand clusters to compress logistics costs. Composite pressure piping substitution in corrosive gathering systems represents the most acute substitution threat requiring coating technology R&D response. For New Entrants and Emerging Players: Blockchain-enabled mill test certificate verification offers a digital-channel route to bypass documentary fraud barriers in cross-border OCTG trade. White-space opportunity concentrates in hydrogen-certified large-diameter pipe for German backbone infrastructure and super-duplex desalination replacement cycles in Saudi Arabia. Target utility framework agreement participation through consortia bidding structures that aggregate volume across multiple mills. For Investors and Strategic Acquirers: Re-rating potential sits with seamless OCTG specialists possessing proprietary hot-rolling expertise given sour-service alloy premium expansion in offshore environments. Long-term viability favors integrated flat-rolled players controlling substrate costs rather than coil-dependent welded fabricators exposed to scrap volatility. Monitor EPA methane leak detection mandate enforcement intensity as replacement cycle inflection signal for US gathering line demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap and DRI Supply | Captive ferrous feedstock insulates ArcelorMittal and EVRAZ from spot scrap spread volatility. |
| Hydrogen Certification Investment | Specialized coating systems for German F-Gas Regulation compliance open premium large-diameter positioning. |
| Greenfield Threading Facility Placement | Proximity to Saudi Jubail and US Gulf Coast clusters reduces logistics costs for Tenaris and Vallourec. |
| Blockchain Traceability Platform Deployment | Automated mill test certificate verification accelerates Indian customs clearance under BIS quality orders. |
| Super-Duplex Capacity Expansion | 6Mo and duplex stainless positioning captures Middle Eastern thermal desalination replacement cycles. |
Research Approach
Document review covered API specification bulletins, ASME Section IX welding procedure databases, and BIS quality control orders, complemented by interviews with plant managers at integrated flat-rolled mills, procurement leads at national oil companies, OCTG distribution channel partners, and technical R&D directors at seamless specialists. Secondary validation drew from customs trade data, SEC 10-K filings, and EPA enforcement disclosure databases. Bottom-up shipment tallies and top-down steel consumption models were triangulated.
Historical capacity utilization patterns were cross-referenced against industry panel input on tender pipeline visibility. The analytical framework modeled product type, application, end user, and material grade dimensions across the projection horizon. CAGRs were derived from segmented volume trajectories and alloy-grade price elasticity assumptions. Hydrogen infrastructure buildout timelines and desalination replacement cycles provided industry-specific forecast anchors.
The model holds under sustained regulatory enforcement of API 5L and ASME standards; deviation in EPA mandate delay or BIS quality order relaxation would shift replacement cycle timing. Practitioners should monitor FERC certificate approvals for hydrogen pipeline projects and Indian PCPIR tender issuance for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Gas Fittings and Components Market
Pipes and Tubes
Global Lance Tubes Market
Pipes and Tubes
Portugal PVC Pipes Market
Pipes and Tubes
Drum Funnel Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
China Industrial Hoses Market
Pipes and Tubes
Water and Wastewater Pipe Market
Pipes and Tubes
Global Municipal Pipes Market
Pipes and Tubes
North America PVC Pipes Market
Pipes and Tubes
India PVC Pipes Market
Pipes and Tubes
PVDF Pipes Market
Pipes and Tubes
Industrial Tubes Market
Pipes and Tubes
Europe Line Pipe Market
Pipes and Tubes
HDPE Corrugated Pipe Market
Pipes and Tubes
Global Flexible Pipes Market
Pipes and Tubes
Global Polyolefin Pipes Market