
 OCTG Pipe Market | 2026-2036
OCTG Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
OCTG Pipe Market Insights
Shale operators are redrawing procurement priorities across the OCTG value chain. National Oilwell Varco leverages its integrated rig-to-retail distribution network to capture recurring replacement demand. Tenaris anchors its competitive stance through captive Dalmine seamless capacity and threading services co-located with producing basins. Vallourec differentiates via premium VAM connection technology tailored for high-pressure, high-temperature well architectures.
Oil country tubular goods encompass seamless and welded steel pipe products manufactured to API 5CT specifications, with wall thicknesses engineered to withstand collapse, burst, and tensile loads encountered during drilling, completion, and production operations. Casing pipes represent the largest product category by tonnage, while tubing pipes command superior margins due to threaded-and-coupled finishing requirements and alloy-grade premiums. Seamless tubulars dominate critical sour-service and deepwater applications where weld-seam integrity risks exclude electric-resistance-welded alternatives; alloy steel grades, particularly chromium-molybdenum formulations, are displacing carbon steel in high-chloride formations.
API standards, NACE sour-service protocols, and EPA methane emissions regulations collectively shape material selection, threading protocols, and supplier qualification timelines across North American basins. The EPA's New Source Performance Standards for oil and gas facilities indirectly elevate OCTG reliability requirements by penalizing unplanned wellbore interventions. Stakeholders must monitor evolving API 5CT edition cycles and regional emissions enforcement intensity to align inventory positioning with specification-driven replacement waves.
Market Dynamics
Pad drilling intensity in the Permian Basin is compressing replacement cycles and forcing suppliers to co-locate threading capacity near producing clusters, reshaping inventory positioning across the OCTG value chain.
Growth Catalysts
- EPA methane regulations:Penalties for unplanned wellbore interventions elevate reliability requirements for casing and tubing grades, accelerating replacement of legacy carbon steel in high-pressure formations.
- Extended-reach horizontal wells:Shale operators in Texas and New Mexico are expanding procurement of premium connections engineered for torque-intensive drilling geometries.
- NACE MR0175 sour-service standards:Tightening material qualification requirements for hydrogen sulfide exposure are displacing standard API grades in Appalachian and Bakken basins.
Market Restraints
- Scrap steel volatility:Electric-arc furnace operators face margin compression when shredded auto scrap prices spike, squeezing seamless pipe producers without captive raw material supply.
- API 5CT specification lag:Edition cycles averaging 5-7 years fail to keep pace with downhole pressure-temperature extremes encountered in 15,000-foot laterals.
- Electric-resistance-welded pipe substitution ceiling:Weld-seam integrity risks exclude ERW alternatives from deepwater and sour-service applications, limiting cost-down options for buyers.
Strategic Opportunities
- Argentina Vaca Muerta shale:Underdeveloped logistics infrastructure and import-dependent supply chains create first-mover advantage for threading service providers establishing local finishing capacity.
- Carbon capture injection wells:CO2 sequestration projects require corrosion-resistant chromium-molybdenum grades with collapse ratings exceeding conventional oilfield specifications.
- Digital thread inspection:Machine-vision systems for connection defect detection enable premium pricing for certified-zero-defect lots versus standard visual-inspection product.
Industry Challenges
- Heat-treatment technician scarcity:Specialized knowledge of quench-and-temper protocols for high-collapse grades is concentrating among retiring workforce cohorts in legacy producing regions.
- API monogram audit timelines:Supplier qualification stretches 12-18 months for new entrants, freezing out mid-cap mills during specification-driven replacement waves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OCTG Pipe Market |
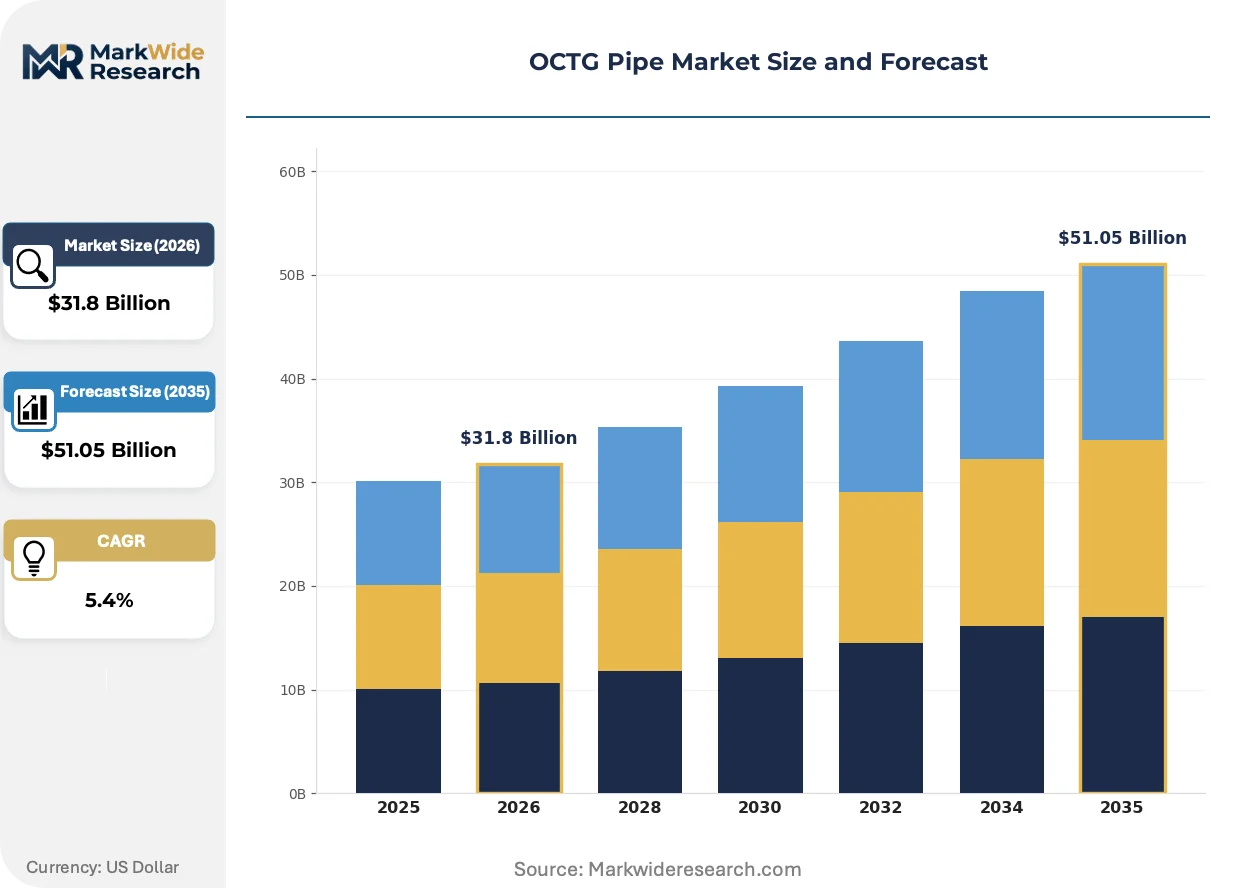
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $51.05 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless Tubulars, Welded Pipes, Casing Pipes, Tubing Pipes, Drill Pipes Material Grade: Carbon Steel, Alloy Steel, Stainless Steel, Nickel Alloy, Titanium Alloy End Use Industry: Upstream Exploration, Midstream Transportation, Downstream Refining, Petrochemical Plants Deployment Type: Onshore Wells, Subsea Installations, Directional Drilling, Hydraulic Fracturing |
| Companies Covered | National Oilwell Varco, Shandong Molong Petroleum Machinery, Tenaris, JFE Steel Corporation, ArcelorMittal, Vallourec, Tianjin Pipe Corporation, Evraz, TMK Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OCTG Pipe Market Trends and Innovations
Downhole digitalization and metallurgical precision are compressing acceptable tolerance bands for connection performance, forcing threading technology to evolve faster than legacy equipment refresh cycles permit.
Ultrasonic phased-array inspection systems are fragmenting quality assurance protocols across the OCTG supply base. Major shale operators in the Permian and Eagle Ford are mandating 100% volumetric testing for premium connections, rejecting statistical sampling methods. This technology is fragmenting supplier tiers into inspection-capable and inspection-dependent categories, with threading houses investing $2-4 million per automated line to retain qualified supplier status.
EPA New Source Performance Standards for oil and gas facilities are tightening fugitive emissions monitoring requirements. Wellhead integrity specifications now incorporate pressure-test documentation traceable to individual pipe joints, extending record-keeping obligations back to steel mill heat numbers. Sour-service grades in the Appalachian Basin face the most stringent documentation burdens, with operators rejecting shipments lacking digital thread records.
Integrated supply contracts are compressing procurement cycles for drilling contractors. Rather than spot-buying casing strings, Permian operators are committing to 12-24 month offtake agreements with threading services bundled into per-foot pricing. This model concentrates purchasing authority with basin-level supply chain managers, marginalizing traditional distributor relationships in West Texas and southeastern New Mexico.
OCTG Pipe Market Segmentation
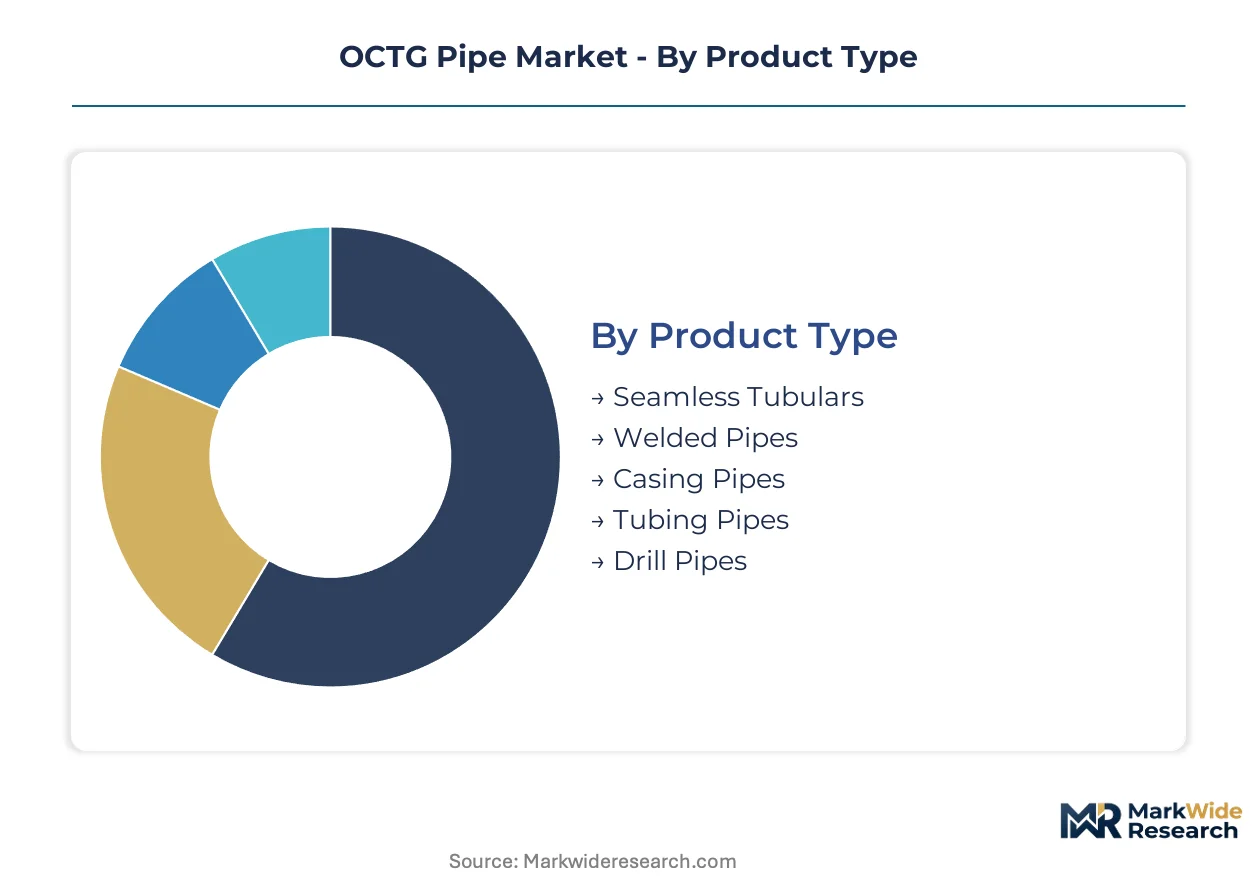
OCTG pipe segmentation reflects divergent technical requirements across well architectures and reservoir conditions. Procurement patterns fragment sharply between standard API grades and premium alloy formulations, with material selection increasingly driven by sour-service exposure and lateral length extremes.
Product Type:
Welded pipe substitution pressure intensifies most acutely in shallow onshore applications, yet seamless alternatives defend irreplaceable positions in critical service environments.
- Seamless Tubulars:Manufactured via rotary piercing and hot-rolling processes without longitudinal weld seams, these products withstand collapse pressures exceeding 10,000 psi in deep Permian laterals. Demand concentrates in 15,000-foot extended-reach wells where weld integrity risks exclude ERW alternatives.
- Casing Pipes:Larger-diameter strings cemented into wellbores provide structural integrity against formation collapse and pressure containment. Pad drilling intensity in West Texas compresses replacement cycles, forcing suppliers to co-locate threading capacity near Midland-Odessa clusters.
- Welded Pipes:Electric-resistance-welded alternatives serve low-pressure gathering lines and shallow vertical wells where cost sensitivity outweighs performance premiums.
- Tubing Pipes:Smaller-diameter production strings require threaded-and-coupled finishing that commands margin premiums over plain-end casing.
- Drill Pipes:Heavy-wall tool joints transmit torque and axial loads during directional drilling operations in the Delaware Basin.
Casing pipes anchor the volume base while seamless tubulars gain share at the steepest rate.
Material Grade:
Cost tier stratification separates commodity carbon grades from metallurgically complex alloys commanding 3-4x per-ton premiums.
- Carbon Steel:Standard API 5CT grades J55, K55, and N80 dominate vertical well programs in conventional reservoirs where corrosion exposure remains minimal.
- Alloy Steel:Chromium-molybdenum formulations including P110 and Q125 grades deliver high-collapse ratings for HPHT formations in the Eagle Ford shale. NACE MR0175 qualification requirements displace carbon alternatives in Appalachian sour-gas fields.
- Stainless Steel:13% chromium grades resist CO2 corrosion in enhanced oil recovery injection wells.
- Nickel Alloy:Inconel and Monel formulations withstand chloride stress cracking in subsea tiebacks.
- Titanium Alloy:Ultra-lightweight strings reduce hookload constraints in extended-reach drilling from offshore platforms.
Carbon steel retains the dominant shipment volume while alloy grades expand most quickly.
End Use Industry:
Customer type segmentation concentrates purchasing authority with drilling contractors versus integrated operators.
- Upstream Exploration:Exploration and production companies drive specification-setting for premium connections and sour-service grades in unconventional basins.
- Midstream Transportation:Pipeline operators specify longitudinally welded line pipe for gathering systems, creating demand overlap with OCTG distributors.
- Downstream Refining:Refinery construction consumes heavy-wall pressure piping with distinct metallurgical requirements from oilfield tubulars.
- Petrochemical Plants:Steam cracker and polyethylene units require specialized alloy piping for high-temperature process streams.
Upstream exploration commands the specification authority while midstream transportation offers the most stable offtake contracting.
Deployment Type:
Geography-driven segmentation fragments inventory positioning between Permian cluster proximity and Gulf Coast port access.
- Onshore Wells:Land-based drilling in Texas, New Mexico, and North Dakota consumes 80% of North American OCTG tonnage through pad development programs.
- Hydraulic Fracturing:Frac iron and wellhead connections require high-pressure-rated tubulars engineered for cyclic loading during stimulation operations.
- Directional Drilling:Steerable bottomhole assemblies demand premium connections with torque capacity exceeding standard API buttress threads.
- Subsea Installations:Deepwater developments in the Gulf of Mexico specify thick-wall seamless strings with sour-service qualification for high-pressure reservoirs.
Onshore wells generate the dominant shipment volume while hydraulic fracturing applications command the highest per-foot technology premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese mills supply the bulk of welded OCTG tonnage to Southeast Asian buyers, while seamless premium grades flow from Western European and Japanese producers toward North American shale basins and Middle Eastern sour-service fields.
United States
Permian Basin pad drilling consumes high-collapse casing grades for 15,000-foot laterals, while EPA methane regulations tighten wellhead integrity documentation. Midland-Odessa threading clusters co-locate with rig activity to compress replacement cycle lead times.
China
Domestic shale development in Sichuan-Chongqing and Tarim Basin drives alloy-grade demand for high-pressure formations. MIIT industrial standards and GB specifications govern domestic qualification, while Tianjin Pipe Corporation anchors seamless capacity in the Bohai Rim industrial corridor.
Saudi Arabia
Aramco's unconventional gas program in Jafurah Basin specifications displace standard grades with NACE-qualified alternatives. The country's national oil company procurement protocols emphasize long-term offtake contracting with threading services bundled into per-foot pricing.
Germany
REACH chemical compliance and EU Green Deal carbon-border adjustments shape alloy steel sourcing for European distributors. Ruhr Valley heat-treatment facilities concentrate quench-and-temper capacity for high-collapse grades serving North Sea developments.
Argentina
Vaca Muerta shale expansion lags behind infrastructure development, creating import-dependent supply chains for premium connections. Neuquén Basin drilling contractors face logistics constraints that favor first-mover threading providers establishing local finishing yards.
OCTG Pipe Market Competitive Landscape
Player mix skews toward integrated steel-to-services conglomerates with captive seamless capacity and basin-proximate threading networks. Structural concentration favors entities controlling Dalmine-class rotary piercing mills and licensed premium connection technologies. Two archetypes dominate: European-Japanese metallurgical specialists with sour-service pedigree, and Chinese-Russian scale producers optimizing electric-arc furnace economics. Competitive moves center on backward integration into scrap-to-pipe supply chains and strategic co-location of finishing capacity near Permian and Vaca Muerta drilling clusters.
Among Western integrated producers, Tenaris S.A. and Vallourec S.A. occupy positions defined by captive seamless mill ownership and proprietary connection licensing. Tenaris exemplifies the basin-proximate threading archetype through co-located service yards, while Vallourec represents the premium-technology tier with VAM-qualified architectures. Chinese scale production concentrates with Tianjin Pipe Corporation, which anchors the cost-optimized seamless segment serving domestic and export markets.
| Leading Market Players |
|---|
| National Oilwell Varco |
| Shandong Molong Petroleum Machinery |
| Tenaris |
| JFE Steel Corporation |
| ArcelorMittal |
| Vallourec |
| Tianjin Pipe Corporation |
| Evraz |
| TMK Group |
| Others |
Pricing and Supply Chain Analysis
Rotary piercing mill utilization rates above 85 percent at Dalmine-class facilities concentrate seamless pipe supply among a handful of integrated producers, compressing price floors for standard API grades while sustaining premiums for NACE-qualified alloy strings. This scale concentration forces electric-arc furnace operators without captive billet supply to absorb scrap volatility, eroding margin buffers that might otherwise fund threading service investments.
Pricing Analysis
Current-generation premium connection technology commands 40-50 percent per-foot premiums over prior-generation API buttress threads, while next-generation digital-inspection-certified lots extract additional pricing power from zero-defect guarantees. Three-tier pricing structure across premium, standard, and economy levels stratifies by NACE qualification status and volumetric inspection coverage, with carbon steel J55 grades facing the steepest price compression due to electric-resistance-welded substitution pressure. Buyers in shallow vertical well programs exhibit highest price sensitivity, whereas Permian extended-reach operators prioritize torque capacity over per-foot cost.
Supply Chain Analysis
Inbound logistics costs from Tianjin Port to Neuquén Basin drilling clusters run 15-20 percent above Gulf Coast delivery benchmarks due to Panama Canal congestion and container availability constraints on the Asia-South America trade lane. Supply concentrates in China, Italy, and Japan for seamless capacity, while raw material dependencies span Brazilian iron ore, Australian metallurgical coal, and ferrochrome from South Africa. Single-source vulnerability around Dalmine rotary piercing technology creates chokepoint risk. Distribution runs through basin-proximate threading yards co-located with Midland-Odessa and Delaware Basin activity clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OCTG procurement is shifting from spot transactions toward bundled threading-service contracts, with recurring inspection and connection re-cutting revenue expanding faster than mill-delivered pipe tonnage. This service-attach dynamic elevates threading capacity location and digital inspection certification as valuation drivers.
For Market Incumbents: Compound defensive positioning through backward integration into scrap-to-billet supply chains and captive heat-treatment capacity for high-collapse Q125 grades. Threat from Chinese electric-arc furnace scale producers intensifies in standard welded segments. Priority lever rests on API monogram audit pre-qualification to freeze out mid-cap entrants during specification replacement waves.
For New Entrants and Emerging Players: Anchor in Argentina Vaca Muerta's import-dependent supply chains, where underdeveloped local threading infrastructure creates white-space for premium connection finishing yards. Neuquén Basin drilling contractors face logistics constraints that favor first-mover threading providers establishing regional service capacity. Go-to-market angle emphasizes NACE MR0175 pre-certification bundled with per-foot pricing contracts.
For Investors and Strategic Acquirers: Basin-proximate threading specialists with licensed premium connection technology represent the most defensible acquisition archetype for long-term viability across the 5-10 year projection horizon. Signal to watch: EPA methane enforcement intensity tightening wellhead integrity documentation requirements, extending record-keeping obligations back to mill heat numbers and favoring integrated pipe-to-services platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Supply | Captive shredded auto scrap sourcing insulates electric-arc furnace margins from commodity volatility. |
| Basin-Proximate Threading Expansion | Co-located service yards near Midland-Odessa compress replacement cycle lead times for Permian operators. |
| NACE MR0175 Pre-Certification Investment | Sour-service qualification displaces standard API grades in Appalachian and Bakken hydrogen sulfide exposure. |
| Digital Thread Inspection Deployment | Machine-vision systems enable premium pricing for certified-zero-defect connection lots. |
| Long-Term Offtake Contracting | 12-24 month bundled threading agreements concentrate purchasing authority with basin-level supply chain managers. |
Research Methodology
Cross-validation between trade association shipment data and customs import records anchors the qualitative findings on regional demand concentration. Primary interviews with drilling contractors, procurement managers at shale operators, threading service technicians, and API audit inspectors combined with secondary validation from API specification documents, NACE technical standards, EPA regulatory filings, and steel mill production disclosures. Bottom-up rig-count modeling and top-down steel consumption triangulation establish volume estimates.
Sensitivity analysis across price-scrap spreads, specification adoption curves, and basin activity levels frames the projection envelope. Segmentation dimensions modeled include product type, material grade, end-use industry, and deployment type across the analysis window. CAGRs derive from regression against historical rig-count elasticities and steel intensity per lateral foot, with forecast inputs incorporating EPA methane regulation enforcement trajectories and NACE edition update timelines.
Material uncertainties — API 5CT specification lag relative to downhole pressure-temperature extremes, scrap steel price volatility, and geopolitical disruption to alloy raw material flows — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Glass Reinforced Epoxy (GRE) Pipes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
GCC Polyethylene (PE) Pipes Market
Pipes and Tubes
PVC Pipes and Fittings Market
Pipes and Tubes
Stainless Steel Tank Container Market
Pipes and Tubes
Clad Pipe Market
Pipes and Tubes
Piping System and Piping Spools Market
Pipes and Tubes
Drum Funnel Market
Pipes and Tubes
Seamless Pipe Market
Pipes and Tubes
Multiflex Tubes Market
Pipes and Tubes
FRP Pipe Market
Pipes and Tubes
Gathering Pipeline Market
Pipes and Tubes
Europe Pipe Market
Pipes and Tubes
GRP Pipe Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market
Pipes and Tubes
Reinforced Thermoplastic Pipes Market