
 Global CPVC Pipes and Fittings Market | 2026-2036
Global CPVC Pipes and Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Global CPVC Pipes and Fittings Market Foresight
India's western industrial corridor is reconfiguring regional supply dynamics for chlorinated polyvinyl chloride infrastructure. Ashirvad Pipes leverages integrated resin-to-pipe manufacturing across Gujarat and Karnataka to control input costs. Astral Pipes sustains brand dominance through extensive plumbing contractor training programs. Finolex Industries anchors its position with deep distribution into tier-two and tier-three Indian cities.
Chlorinated polyvinyl chloride pipes and fittings are thermoplastic conduit systems produced by post-chlorination of PVC resin to achieve chlorine content of 63-69%, yielding temperature resistance up to 93°C for pressurized hot water distribution. The material's corrosion immunity and low thermal conductivity serve municipal water delivery, chemical transport, and building plumbing networks. Pipes command the dominant revenue share due to linear footage volume in building construction, while fire sprinkler systems represent the fastest-expanding application segment driven by mandatory NFPA 13 retrofits in commercial complexes. Residential buildings generate the largest end-user demand pool, though industrial plants yield superior margin profiles through specification-grade custom fabrication.
India's BIS mandates CPVC plumbing compliance under IS 15778, while the US NSF/ANSI 61 governs potable water contact safety and the EU REACH framework restricts phthalate plasticizer chemistries. These regulatory layers shape formulation chemistry, testing protocols, and export market access for compounders and extruders. Stakeholders must monitor evolving state-level plumbing codes in India and the US for specification shifts that could advantage or disqualify incumbent product lines.
Market Dynamics
Resin supply concentration among chlor-alkali producers is reconfiguring input cost structures for CPVC compounders worldwide, forcing extruders to secure long-term chlorine supply contracts or absorb volatile feedstock swings.
Growth Catalysts
- NFPA 13 Retrofit Mandates:US commercial building codes now require fire suppression system upgrades in structures over 75 feet, accelerating specification-grade CPVC sprinkler installations across multi-story properties.
- India BIS IS 15778 Enforcement:Mandatory certification for chlorinated polyvinyl chloride plumbing products is eliminating substandard imports and consolidating demand around compliant domestic manufacturers.
- Hot Water Distribution Expansion:Residential developers in Maharashtra and Gujarat are specifying CPVC over copper for pressurized hot water loops, driven by corrosion immunity and installation speed advantages.
Market Restraints
- Chlorine Feedstock Volatility:European chlor-alkali plant curtailments have tightened elemental chlorine availability, compressing margins for compounders without captive chlorination capacity.
- Cross-Linked Polyethylene Substitution:PEX tubing manufacturers are capturing share in North American residential plumbing through flexible installation and lower fitting counts.
- REACH Phthalate Restrictions:ECHA scrutiny of plasticizer chemistries is forcing reformulation investments for EU-bound CPVC products, extending certification timelines.
Strategic Opportunities
- Industrial Chemical Transport:Corrosion-resistant CPVC piping for acid handling in Brazilian mining operations remains underpenetrated relative to fiberglass and rubber-lined steel.
- Smart Infrastructure Convergence:Integration of pressure-monitoring sensors with CPVC distribution networks enables predictive maintenance contracts for municipal water utilities.
- Saudi SFDA Medical-Grade Certification:Hospital potable water system upgrades are creating specification pathways for NSF/ANSI 61-compliant CPVC in healthcare construction.
Industry Challenges
- Certification Timeline Compression:Multi-jurisdictional testing for BIS, NSF, and REACH compliance is extending product launch cycles by 14-18 months for new formulations.
- Specialized Extrusion Talent Scarcity:Compounders face recruitment gaps for process engineers capable of managing chlorine content uniformity across high-speed production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global CPVC Pipes and Fittings Market |
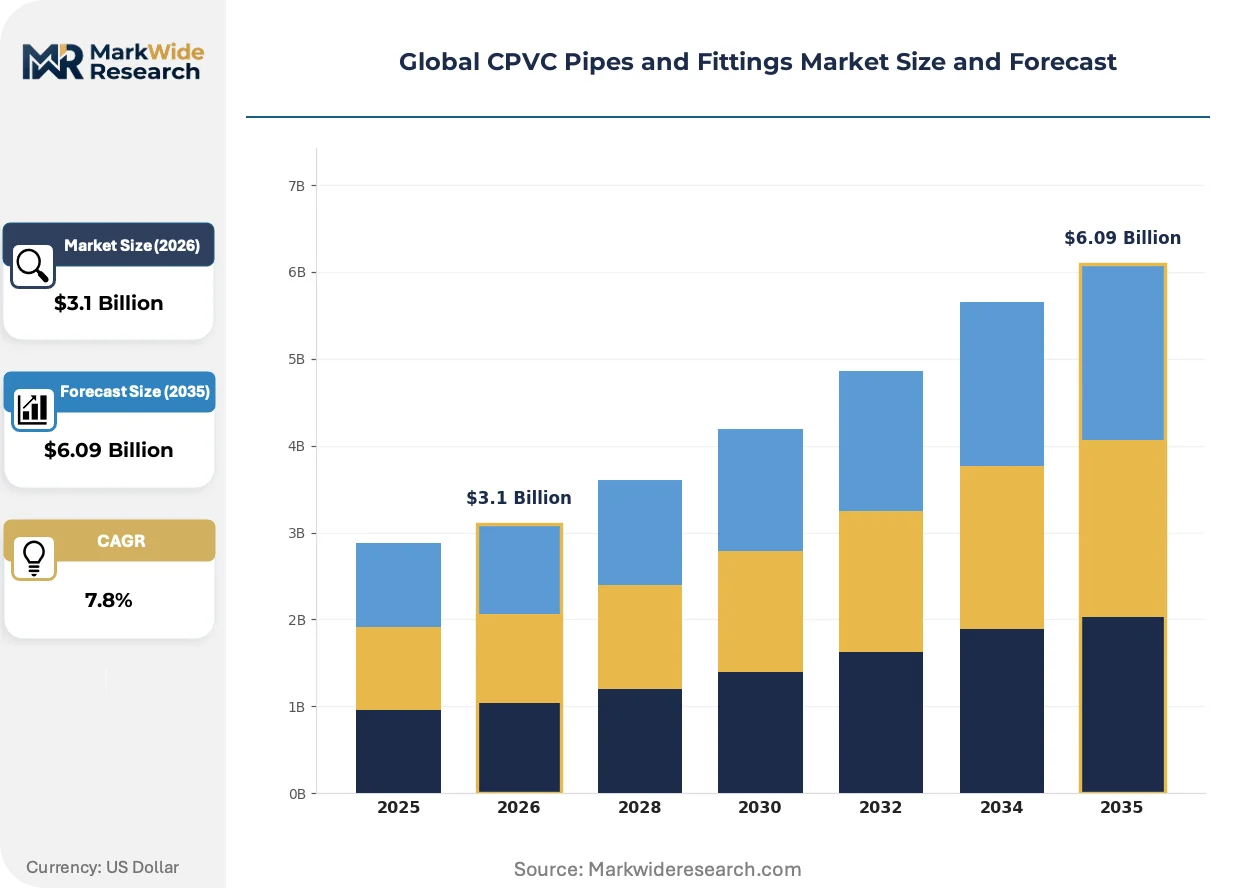
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.09 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pipes, Elbows, Tees, Couplings, Adapters, Nipples Application: Water Supply Systems, Fire Sprinkler Systems, Chemical Processing, HVAC, Wastewater Management, Agriculture Irrigation End User: Residential Buildings, Commercial Complexes, Institutional Facilities, Industrial Plants, Public Infrastructure Installation Type: New Construction, Renovation Projects, Retrofitting, Municipal Installations, OEM Equipment Fitting |
| Companies Covered | Ashirvad Pipes, Astral Pipes, Georg Fischer Harvel, NIBCO, IPEX, Charlotte Pipe, Finolex Industries, Supreme Industries, Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global CPVC Pipes and Fittings Market Shifts & Advancements
Digital manufacturing integration and regulatory chemistry shifts are compressing product development cycles while fragmenting specification authority across regional standards bodies.
Embedded IoT pressure sensors within CPVC distribution networks is digitizing asset management for municipal water utilities. US cities including Phoenix and Austin are piloting smart leak detection systems that transmit flow anomalies to centralized control centers. This convergence is compressing maintenance response times from days to hours while generating recurring data-service revenue streams for infrastructure contractors.
ECHA's evolving REACH restrictions on phthalate plasticizers are forcing compounders toward bio-based or trimellitate alternatives. European extruders must reformulate legacy recipes to maintain potable water contact approvals under tightening migration limits. German KBA-aligned testing protocols are becoming the de facto benchmark for EU-bound products, extending validation periods but creating first-mover advantages for compliant suppliers.
Plumbing contractor certification programs are displacing traditional distributor-led specification in India's western corridor. Astral Pipes and regional competitors now train thousands of installers annually, embedding brand preference through hands-on competence validation. This channel transformation is most visible in Gujarat's tier-two cities where contractor recommendations override architect specifications in mid-market residential projects.
Global CPVC Pipes and Fittings Market Segmentation
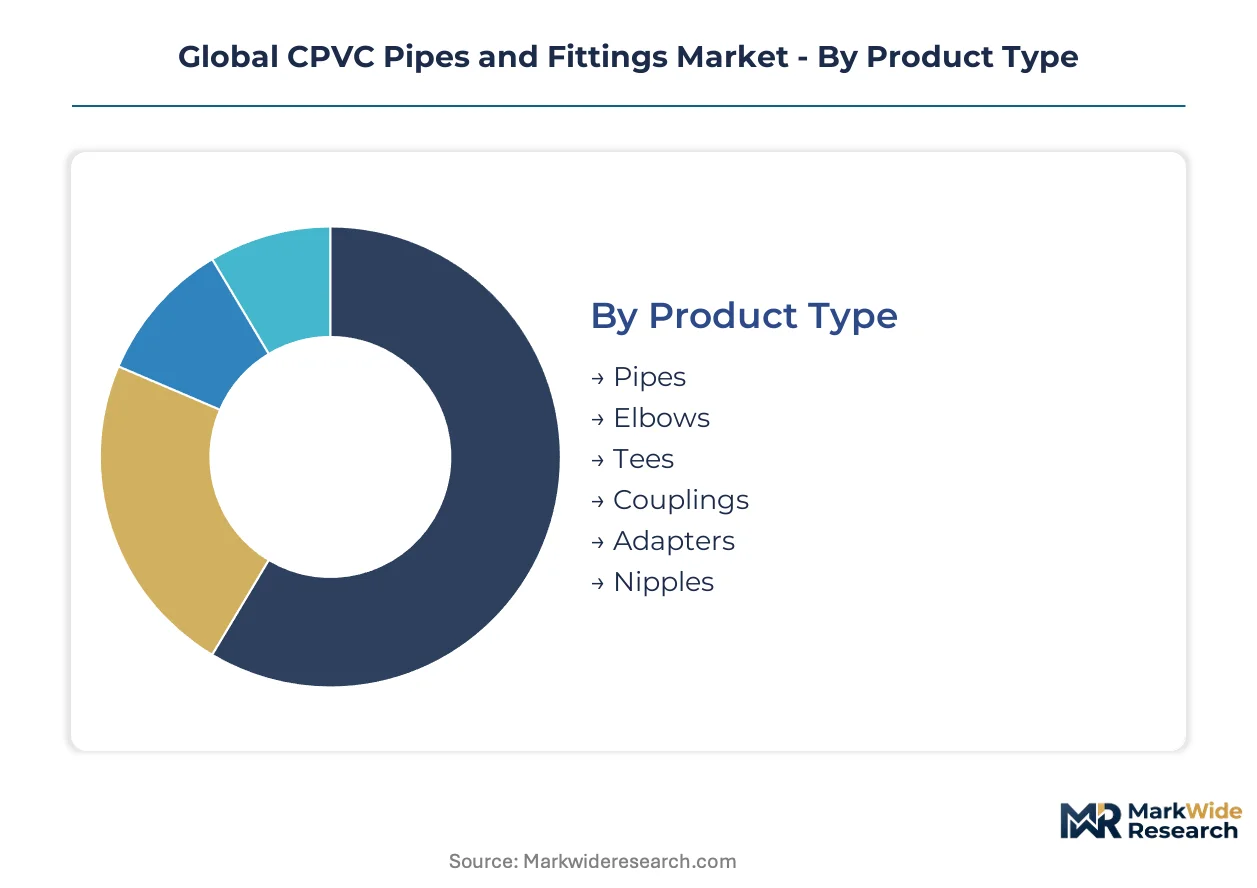
CPVC market segmentation reflects divergent technical requirements across pressure ratings, chemical exposure levels, and installation methodologies. Specification-grade distinctions between potable water and industrial chemical transport create distinct margin architectures for compounders and extruders.
Product Type:
Mature commodity segments dominate volume, while engineered fittings command premium positioning through specification complexity.
- Pipes:Linear extrusions in Schedule 40 and 80 wall thicknesses constitute the foundational revenue base, with SDR-11 dimensions specified for residential hot water distribution across Maharashtra and Gujarat housing developments. Chlorine content uniformity of 63-69% ensures temperature resistance to 93°C under sustained pressure.
- Elbows:90-degree and 45-degree pressure-molded fittings enable directional changes in confined mechanical spaces without flow restriction. Demand concentrates in multi-story commercial retrofits where NFPA 13 sprinkler routing requires compact geometry.
- Tees:Branch connection fittings facilitate distribution network expansion in municipal water grids.
- Couplings:Straight-line splicing components repair damaged sections without system shutdown.
- Adapters:Transition fittings bridge CPVC to copper, PEX, or galvanized steel legacy infrastructure.
- Nipples:Short threaded extensions connect valves and fixtures in tight mechanical assemblies.
Pipes handle the majority of throughput; elbows are expanding most quickly on specification-grade fire protection demand.
Application:
Application segmentation tracks regulatory mandate intensity, with code-driven retrofits outpacing discretionary new construction.
- Water Supply Systems:Pressurized potable and hot water distribution networks leverage CPVC's corrosion immunity against aggressive municipal chemistry. BIS IS 15778 certification requirements in India are consolidating demand around compliant domestic manufacturers while eliminating substandard imports.
- Fire Sprinkler Systems:Concealed and exposed light-hazard installations in commercial structures over 75 feet now mandate CPVC under NFPA 13 retrofit codes. US multi-story properties are accelerating specification-grade installations as jurisdictions enforce compliance deadlines.
- Chemical Processing:Acid handling in Brazilian mining and fertilizer operations remains underpenetrated relative to fiberglass alternatives.
- HVAC:Chilled water and condensate drainage applications exploit low thermal conductivity.
- Wastewater Management:Corrosive effluent transport in industrial pretreatment systems.
- Agriculture Irrigation:Chemical-resistant drip and sprinkler distribution in high-salinity soil regions.
Water supply systems anchor volume commitment; fire sprinkler systems show the steepest expansion trajectory on regulatory mandate density.
End User:
End-user segmentation separates specification authority between architect-driven institutional projects and contractor-influenced residential work.
- Residential Buildings:Single-family and multi-family plumbing contractors specify CPVC over copper for installation speed and material cost advantages. India's western corridor training programs embed brand preference through hands-on competence validation in tier-two cities.
- Commercial Complexes:Office, retail, and hospitality developers balance first-cost against lifecycle maintenance exposure on fire suppression and HVAC distribution.
- Institutional Facilities:Hospital and school construction in Saudi Arabia requires SFDA medical-grade certification for potable water contact.
- Industrial Plants:Specification-grade custom fabrication for chemical transport yields superior margin profiles through technical consultation requirements.
- Public Infrastructure:Municipal water utilities pilot smart pressure-monitoring integration in Phoenix and Austin networks.
Residential buildings generate the largest demand pool; industrial plants capture the highest margin realization.
Installation Type:
Installation segmentation distinguishes greenfield specification from replacement economics and regulatory-driven retrofit urgency.
- New Construction:Ground-up building projects enable optimized CPVC routing without legacy infrastructure constraints. Developer specifications in Gujarat and Maharashtra housing stock expansion favor integrated plumbing and fire protection packages.
- Renovation Projects:Partial system upgrades in occupied buildings demand flexible installation windows and minimal disruption protocols.
- Retrofitting:Mandated fire sprinkler additions to existing commercial structures over 75 feet create compressed timeline demand spikes.
- Municipal Installations:City-owned water distribution networks require extended warranty terms and predictive maintenance integration.
- OEM Equipment Fitting:Factory-integrated CPVC components in water treatment skids and chemical processing units.
New construction absorbs the dominant share of linear footage; retrofitting is climbing the fastest on code enforcement timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chlor-alkali capacity clusters in the US Gulf Coast and China's coastal provinces are reconfiguring resin economics for extruders worldwide. Indian compounders leverage captive chlorination to offset feedstock volatility. European producers navigate ECHA reformulation mandates while Gulf states deploy CPVC in healthcare infrastructure.
United States
NFPA 13 retrofit deadlines for commercial structures over 75 feet are accelerating specification-grade fire sprinkler installations. The EPA oversees potable water contact safety through NSF/ANSI 61 alignment. Phoenix and Austin municipal utilities pilot smart pressure-monitoring integration in distribution networks.
India
Maharashtra and Gujarat housing stock expansion is driving residential hot water distribution specification. BIS mandates IS 15778 certification for chlorinated polyvinyl chloride plumbing products, eliminating substandard imports. Tier-two cities in Gujarat's western corridor embed brand preference through contractor training programs.
Germany
ECHA's evolving REACH restrictions on phthalate plasticizers are forcing compounders toward bio-based alternatives. KBA-aligned testing protocols are becoming the de facto benchmark for EU-bound products. Industrial chemical transport applications in the Ruhr region remain underpenetrated relative to fiberglass alternatives.
Saudi Arabia
Hospital potable water system upgrades are creating specification pathways for NSF/ANSI 61-compliant products in healthcare construction. The SFDA governs medical-grade certification requirements. Riyadh and Jeddah construction clusters are embedding CPVC in institutional facility builds.
Brazil
Acid handling in mining operations represents underpenetrated demand relative to rubber-lined steel alternatives. ANVISA oversees industrial chemical transport safety protocols. The Minas Gerais mining belt is specifying corrosion-resistant piping for fertilizer and mineral processing operations.
Global CPVC Pipes and Fittings Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on resin and formulation. The vendor base separates into three tiers: multinational chlor-alkali producers with captive compound capacity, regional extruders serving single-country building codes, and specialized fabricators for industrial chemical transport. Dominant competitive moves include backward integration into chlorine supply and certification-driven portfolio pruning for multi-jurisdictional compliance.
Among Indian fabricators, Ashirvad Pipes and Astral Pipes exemplify the integrated-resin-to-pipe archetype, while Finolex Industries represents the deep-distribution model penetrating tier-two and tier-three cities. These three occupy positions within India's western industrial corridor, where BIS enforcement is consolidating demand around compliant domestic manufacturers.
| Leading Market Players |
|---|
| Ashirvad Pipes |
| Astral Pipes |
| Georg Fischer Harvel |
| NIBCO |
| IPEX |
| Charlotte Pipe |
| Finolex Industries |
| Supreme Industries |
| Lubrizol Corporation |
| Others |
Supply & Pricing Matrix
Hazira Port freight corridors connecting Gujarat to Maharashtra carry chlorine feedstock and finished CPVC inventory at rates that fluctuate with fuel surcharges and vessel availability, compressing margins for compounders without captive chlorination while enabling price premiums for BIS-certified domestic manufacturers over import-dependent competitors.
Pricing Analysis
BIS IS 15778 dictates the pricing tier structure across India's CPVC plumbing market, separating NSF/ANSI 61-compliant premium grades from standard domestic formulations and uncertified economy imports. Price differentiation rests on certification level and brand-embedded contractor training programs rather than commodity resin costs alone. Pricing pressure stems from European chlor-alkali curtailments tightening elemental chlorine availability. Residential developers in tier-two cities show highest price sensitivity, while industrial chemical transport buyers prioritize corrosion performance over unit cost.
Supply Chain Analysis
Tariff exposure between India and China dominates supply chain risk calculus for compounders sourcing specialty plasticizers and extrusion equipment. Manufacturing concentrates in India, the United States, and Germany, with resin production anchored in chlor-alkali corridors along the US Gulf Coast and Gujarat's industrial belt. Raw material dependencies include PVC resin, elemental chlorine, and phthalate or trimellitate plasticizers. Distribution runs through plumbing contractor networks in India's western corridor and distributor-led specification in North American commercial construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CPVC market sits at an inflection where NFPA 13 retrofit mandates and BIS enforcement are compressing specification windows, rewarding players who synchronize certification timelines with capacity expansion.
For Market Incumbents: Build regulatory certification moats by securing parallel BIS, NSF/ANSI 61, and REACH approvals before competitors complete multi-jurisdictional testing cycles. Anchor chlorine supply through long-term offtake agreements with Gulf Coast or Gujarat chlor-alkali producers to neutralize feedstock volatility. Deepen contractor training penetration in Maharashtra and Gujarat tier-two cities where installer recommendations override architect specifications. For New Entrants and Emerging Players: Establish a beachhead in Brazilian mining chemical transport where fiberglass and rubber-lined steel still dominate acid handling applications. Target Saudi healthcare construction requiring SFDA medical-grade certification for hospital potable water systems, a specification pathway with limited incumbent saturation. Lead with IoT-integrated pressure monitoring bundled into predictive maintenance contracts for municipal utilities piloting smart infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational chemical conglomerates pruning non-core chlorinated polymer divisions to focus on specialty materials. Long-term viability favors compounders with captive chlorination capacity and multi-certification portfolios spanning potable water, fire protection, and industrial chemical transport. Monitor ECHA plasticizer restriction evolution as the signal indicating which formulation investments will capture sustainable EU market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorine Supply | Captive chlorination capacity insulates margins from European feedstock volatility and secures BIS compliance timelines. |
| Multi-Jurisdictional Certification Investment | Parallel BIS, NSF, and REACH approvals compress product launch cycles by 14-18 months versus sequential testing. |
| Contractor Training Program Expansion | Astral Pipes validates installer competence in Gujarat tier-two cities, embedding brand preference ahead of distributor influence. |
| Smart Infrastructure Convergence | Phoenix and Austin pilot pressure-monitoring sensors, generating recurring data-service revenue for infrastructure contractors. |
| Industrial Chemical Transport Specialization | Brazilian mining operations in Minas Gerais specify corrosion-resistant piping for acid handling, outpacing fiberglass substitution rates. |
Research Methodology
A spread of perspectives from CPVC compounders, plumbing contractors in Maharashtra and Gujarat, municipal water utility engineers, and chlor-alkali procurement managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against BIS certification databases, NSF/ANSI 61 listings, ECHA REACH substance restrictions, and customs trade flows for chlorinated polyvinyl chloride resin. Bottom-up triangulation across product-grade volume estimates and top-down reconciliation against end-use construction activity anchored the market sizing.
Demand-supply balance dynamics shaped the analytical framework across the analysis window, with segmentation modeling across product type, application, end user, and installation methodology dimensions. CAGRs derived from weighted regression against housing stock expansion in India, NFPA 13 enforcement timelines in US commercial construction, and ECHA plasticizer migration limit evolution. Forecast inputs incorporated chlorine feedstock contract pricing volatility and tier-two city contractor penetration rates.
Sensitivities concentrate around European chlor-alkali plant operating rates, BIS enforcement intensity in Indian states beyond Maharashtra and Gujarat, and PEX tubing substitution acceleration in North American residential plumbing. Forecasts reflect documented assumptions subject to revision from regulatory timeline shifts or feedstock supply disruptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Seamless Pipe Market
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
Industrial Blast Hoses Market
Pipes and Tubes
Saw Pipes Market
Pipes and Tubes
Europe Line Pipe Market
Pipes and Tubes
Saudi Arabia PVC Pipes Market
Pipes and Tubes
Pipe Market
Pipes and Tubes
Water and Wastewater Pipe Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
Plastic Pipe Jointing and Welding Market
Pipes and Tubes
Global Tracer Wires Market
Pipes and Tubes
Global Municipal Pipes Market
Pipes and Tubes
Steel Roll-On Tube Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
HDPE Pipes Market