
 Saudi Arabia Commercial Real Estate Market | 2026-2036
Saudi Arabia Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Commercial Real Estate Market Analytics
Cross-laminated timber and modular steel framing is shifting structural economics for mid-rise commercial builds across the Kingdom. Red Sea Global leverages captive fabrication yards to control project timelines on coastal developments. Kingdom Holding Company anchors its portfolio through mixed-use superblocks in Riyadh. Jabal Omar Development Company specializes in hospitality-adjacent retail precincts near religious sites.
Saudi Arabia commercial real estate encompasses income-producing properties—office spaces, retail stores, warehouses, and industrial parks—built to specifications ranging from reinforced concrete frame systems with minimum 4.5-meter clear heights to climate-controlled logistics shells exceeding 15,000 square meters, serving tenant operations from corporate headquarters to last-mile distribution. Office spaces dominate transactional velocity in Riyadh and Jeddah as multinational entrants seek Grade-A stock with smart building certification. Warehouses represent the fastest-expanding property type as bonded logistics demand surges alongside Special Economic Zone activation. Real Estate Investment Trusts channel institutional capital into stabilized income streams, while pre-construction phases attract development-stage private equity seeking land-bank appreciation.
SFDA building code harmonization with Gulf Standards Organization frameworks elevates fire safety and accessibility mandates for new commercial stock. MOHAP municipal permitting in Dubai-adjacent economic zones creates competitive pressure on Saudi approval timelines. Stakeholders must monitor how Riyadh's new transit-oriented development overlays redistribute foot traffic and rent gradients across legacy and emerging submarkets.
Market Dynamics
Saudi Vision 2030 zoning reforms are compressing approval timelines and unlocking greenfield land banks for mixed-use development, while logistics operators anchor absorption as e-commerce fulfillment networks expand across the Kingdom.
Growth Catalysts
- Special Economic Zone activation:Bonded logistics demand surges as customs-free processing zones attract third-party fulfillment operators seeking tariff-advantaged import-export positioning.
- SFDA building code harmonization:Gulf Standards Organization fire safety and accessibility mandates elevate specifications for new commercial stock, accelerating replacement cycles in aging submarkets.
- Modular steel framing adoption:Cross-laminated timber and prefabricated structural systems compress construction schedules for mid-rise office and retail builds in Riyadh's secondary districts.
Market Restraints
- Skilled construction labor scarcity:Projected workforce gaps in MEP installation and smart building commissioning extend handover timelines for Grade-A office deliveries.
- Imported materials cost volatility:Steel and aluminum price fluctuations from East Asian supply bases compress developer margins on fixed-price contracts.
- Legacy infrastructure retrofit burden:Existing commercial stock in Jeddah's older districts requires extensive mechanical and facade upgrades to meet current energy efficiency benchmarks.
Strategic Opportunities
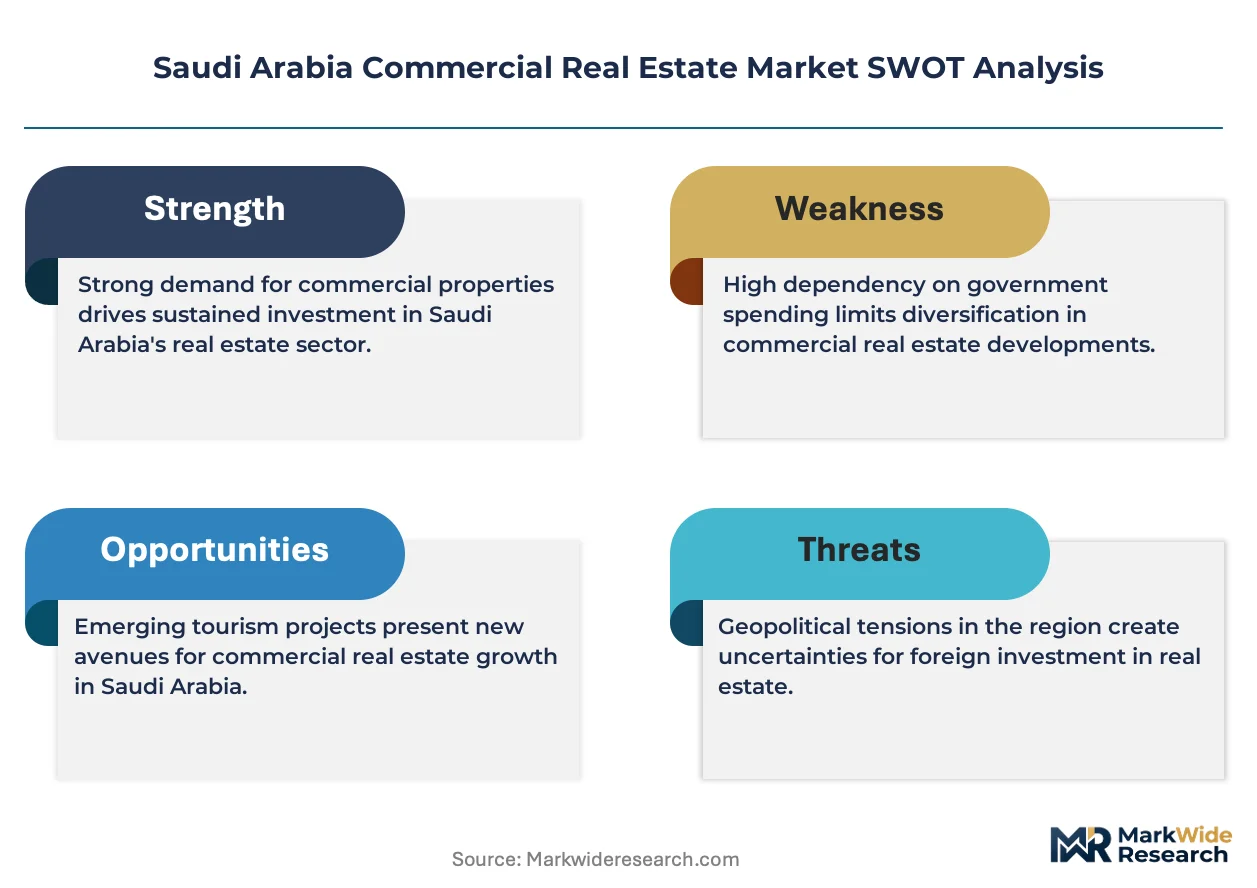
- Transit-oriented development overlays:Riyadh Metro corridor stations are redistributing foot traffic and creating infill retail and flex-office opportunities in previously secondary submarkets.
- Red Sea coastal tourism integration:Hospitality-adjacent commercial precincts near religious and leisure destinations capture pilgrimage and leisure crossover demand.
- Real Estate Investment Trust channel expansion:Regulatory frameworks for REITs channel institutional capital into stabilized income streams, deepening liquidity for income-producing assets.
Industry Challenges
- Smart building certification complexity:Multi-vendor IoT integration and cybersecurity compliance extend commissioning timelines for Grade-A office deliveries.
- Municipal permitting coordination:Inter-agency approval workflows between local municipalities and sector-specific regulators create execution uncertainty for phased developments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Commercial Real Estate Market |
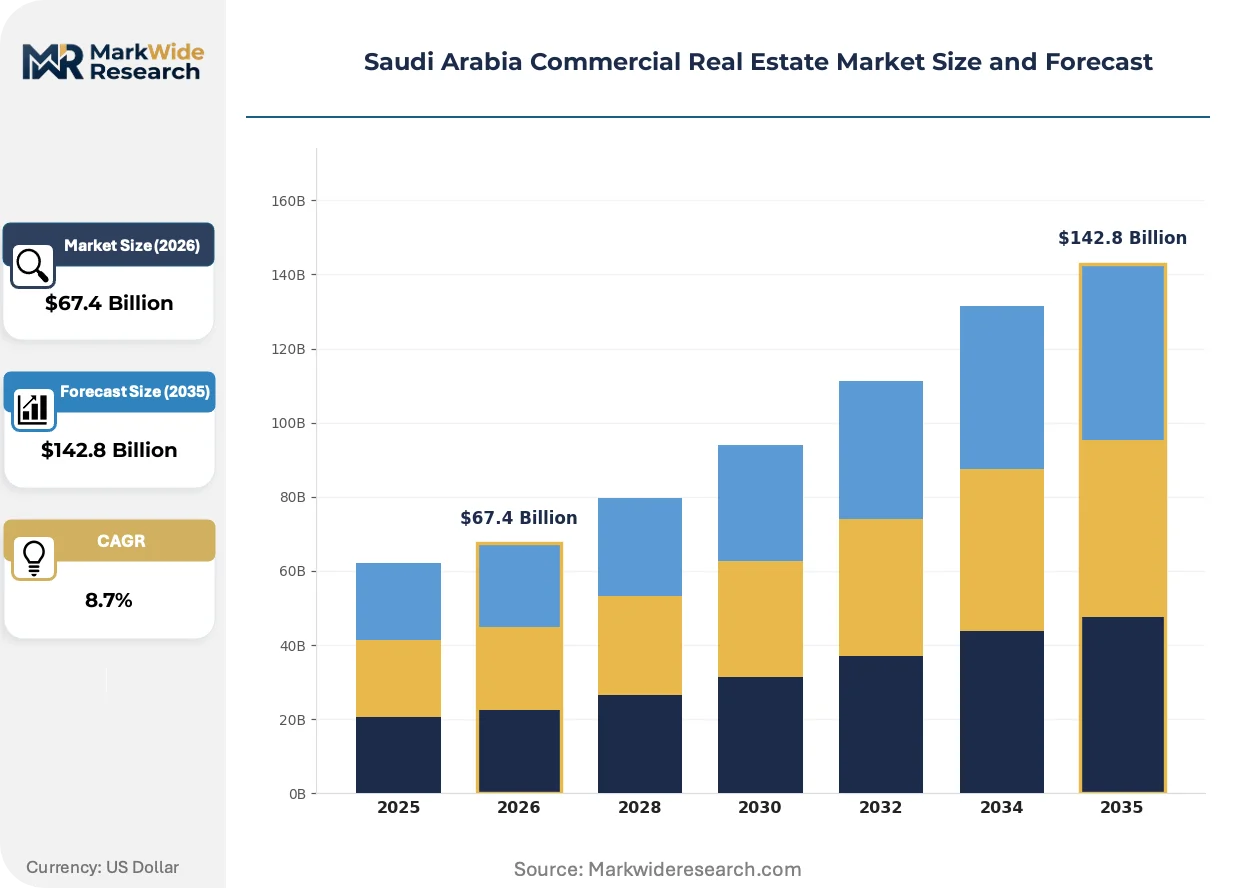
| Market Size in 2026 | $67.4 Billion |
| Market Size in 2035 | $142.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office Spaces, Retail Stores, Warehouses, Industrial Parks Investment Type: Foreign Direct Investment, Joint Ventures, Real Estate Investment Trusts, Private Equity End User: Corporations, Business Startups, Government Agencies, Non-Profit Organizations Development Stage: Pre-Construction, Under Construction, Completed, Renovated |
| Companies Covered | Arriyadh Development Co., Kingdom Holding Company, Jabal Omar Development Company, Red Sea Global, RAFAL Real Estate, Dar Al Arkan Real Estate Development Company, Emaar The Economic City, Al Saedan Real Estate Co., Al Akaria (Saudi Real Estate Company), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Commercial Real Estate Market Evolving Landscape
Structural economics for commercial builds across the Kingdom are compressing as prefabrication and digital construction methods displace conventional on-site assembly, while regulatory harmonization accelerates specification convergence.
Cross-laminated timber and modular steel framing is rewriting structural economics for mid-rise commercial builds across the Kingdom. Logistics operators and institutional developers are specifying factory-fabricated structural packages to compress weather-dependent construction exposure. This technology is compressing traditional cast-in-place concrete timelines by 30-40% for office and retail typologies under 12 stories.
SFDA building code harmonization with Gulf Standards Organization frameworks is elevating fire safety and accessibility mandates for new commercial stock. Developers must now integrate enhanced sprinkler density and egress width requirements into schematic design phases. Warehouse and logistics shell specifications face the steepest compliance cost adjustments as bonded storage facilities adopt pharmaceutical-grade safety standards.
Last-mile fulfillment operators are consolidating distribution footprints around Riyadh's ring road interchanges and Jeddah's port-adjanced industrial zones. Traditional bulk warehouse leasing is fragmentating into smaller, climate-controlled units with cross-dock capabilities. This pattern is most visible in the Kingdom's Central Region where e-commerce penetration drives specification divergence between legacy bulk storage and automated fulfillment facilities.
Saudi Arabia Commercial Real Estate Market Segmentation
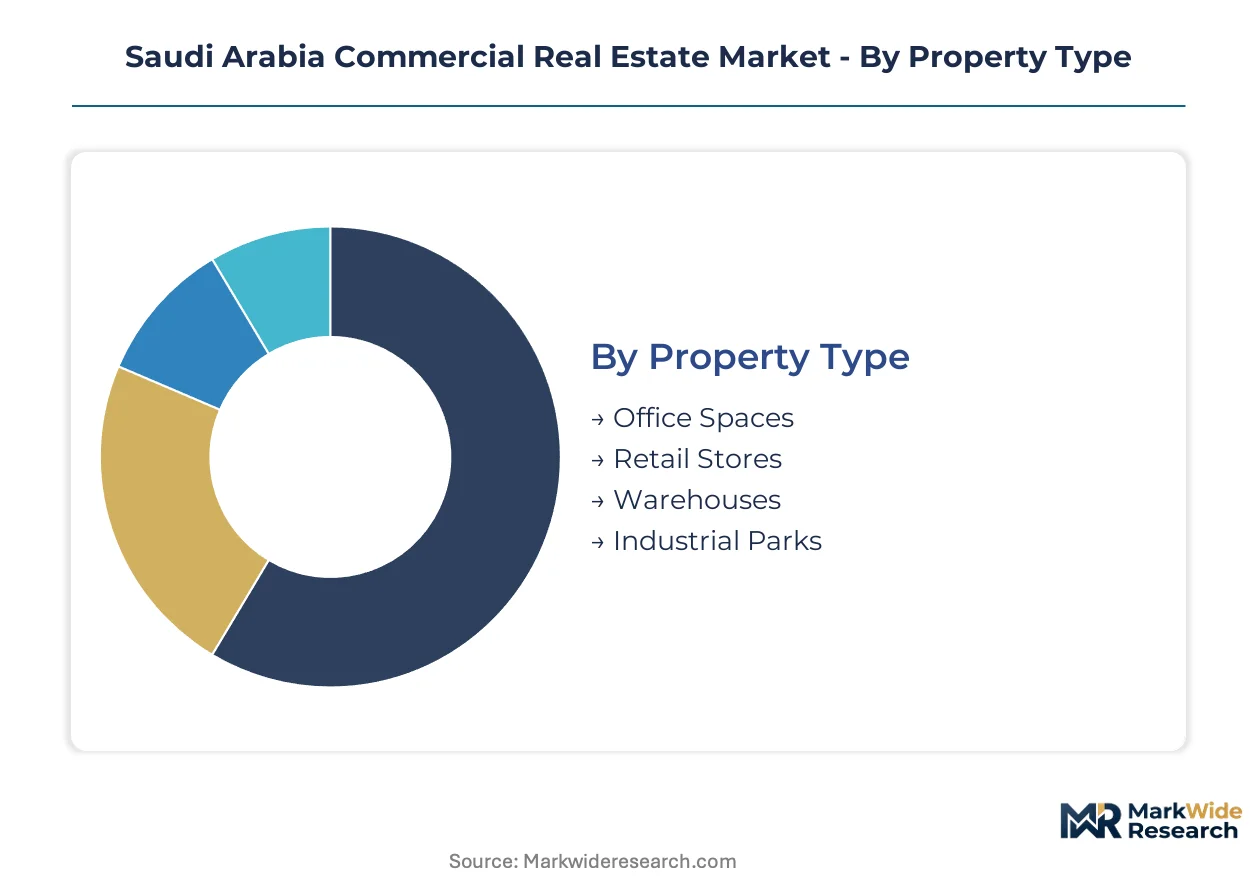
Segmentation reveals how capital allocation patterns diverge across property types and investment vehicles in the Kingdom. Distinct risk-return profiles separate stabilized income seekers from development-stage speculators. Understanding these fault lines clarifies where SFDA building codes and Vision 2030 zoning reforms exert differential pressure.
Property Type:
Buyer decisions here pivot on lease duration certainty versus capital appreciation velocity.
- Office Spaces:Grade-A stock with smart building certification commands premium rents in Riyadh's central business district as multinational entrants consolidate headquarters operations. Jeddah's secondary submarkets absorb mid-tier supply as SFDA harmonization elevates retrofit costs for aging stock.
- Warehouses:Climate-controlled logistics shells exceeding 15,000 square meters anchor bonded storage demand near Special Economic Zone perimeters. Automated fulfillment specifications diverge from legacy bulk storage as e-commerce operators consolidate around Riyadh ring road interchanges.
- Retail Stores:Hospitality-adjacent precincts near religious sites capture pilgrimage crossover traffic.
- Industrial Parks:Heavy manufacturing footprints cluster in port-adjacent zones with customs-free processing advantages.
Volume sits with Office Spaces; growth tilts toward Warehouses.
Investment Type:
Capital source determines holding period expectations and regulatory exposure thresholds.
- Real Estate Investment Trusts:Regulatory frameworks channel institutional capital into stabilized income streams with mandated distribution requirements. REIT structures deepen liquidity for income-producing assets while constraining development-stage risk-taking.
- Private Equity:Pre-construction phases attract land-bank appreciation strategies with 5-7 year fund lifecycles. Development-stage returns depend on municipal permitting velocity and construction cost containment.
- Foreign Direct Investment:Sovereign wealth and multinational balance sheets deploy patient capital into mixed-use superblocks.
- Joint Ventures:Local sponsorship requirements shape partnership structures for greenfield land access.
Transaction flow concentrates through Real Estate Investment Trusts; risk-adjusted returns favor Private Equity.
End User:
Tenant credit quality and lease covenant strength drive valuation multiples across submarkets.
- Corporations:Multinational headquarters operations specify smart building certification and redundant MEP systems as non-negotiables. Riyadh's central business district concentrates premium absorption as sectoral diversification broadens tenant mix beyond oil services.
- Business Startups:Flex-office and co-working operators fragment traditional leasing structures with short-term license agreements. Secondary district infill opportunities emerge as transit-oriented development overlays redistribute foot traffic.
- Government Agencies:Long-term lease commitments anchor public-private partnership structures.
- Non-Profit Organizations:Mission-driven facilities cluster near educational and healthcare precincts.
Occupancy stability flows from Corporations; expansion velocity tracks Business Startups.
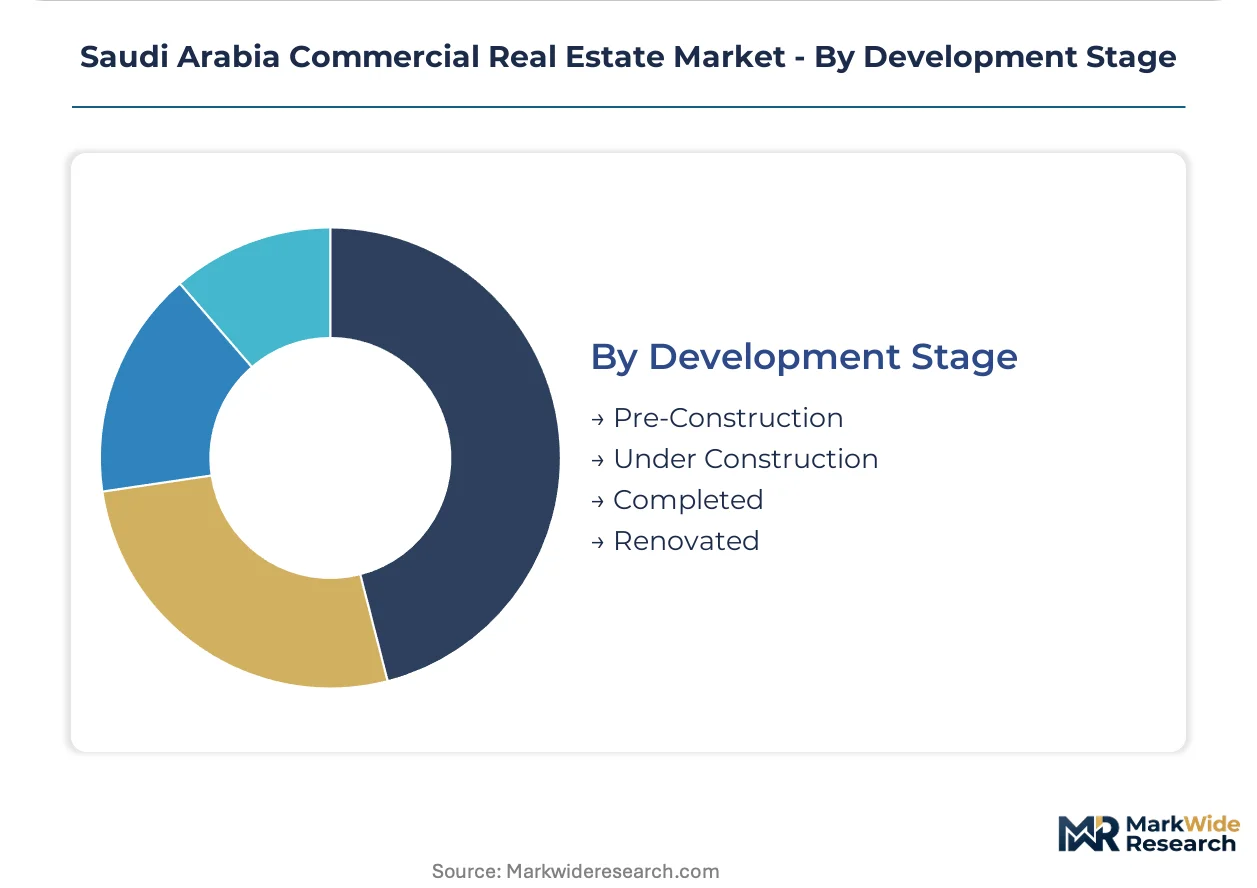
Development Stage:
Construction risk exposure and yield compression timelines segment investor profiles.
- Completed:Stabilized assets with in-place cash flows trade on cap rate compression as REIT acquisition demand deepens. Income certainty attracts institutional mandates with liability-matching requirements.
- Pre-Construction:Land-bank appreciation strategies hinge on zoning reform velocity and infrastructure timing certainty. Vision 2030 unlocking of greenfield permissions creates speculative entry points.
- Under Construction:Fixed-price contract structures transfer steel and aluminum volatility risk to contractors.
- Renovated:Legacy stock in Jeddah's older districts requires extensive mechanical upgrades to meet current energy efficiency benchmarks.
Pricing transparency anchors Completed assets; return asymmetry concentrates in Pre-Construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in Saudi Arabia's commercial real estate sector gravitates toward Riyadh's central business district and the Western Region's logistics corridors. SFDA building code harmonization and Vision 2030 zoning reforms are redistributing development activity across four distinct sub-markets.
Riyadh
Multinational headquarters operations and government agency relocations are absorbing Grade-A office stock with smart building certification. The Riyadh Metro corridor stations are redistributing foot traffic and creating infill retail opportunities in secondary districts. King Abdullah Financial District anchors premium transactional velocity as sectoral diversification broadens tenant mix beyond oil services.
Eastern Province
Port-adjacent industrial zones with customs-free processing advantages are attracting heavy manufacturing footprints and bonded logistics operators. SFDA harmonization with Gulf Standards Organization frameworks elevates fire safety mandates for warehouse specifications near Special Economic Zone perimeters. Dammam's industrial corridor concentrates climate-controlled logistics shells exceeding 15,000 square meters.
Western Region
Hospitality-adjacent retail precincts near religious sites capture pilgrimage crossover traffic alongside leisure destination development. Jeddah's secondary submarkets absorb mid-tier office supply as retrofit costs escalate for aging stock. King Abdullah Economic City exemplifies mixed-use superblock strategies integrating commercial, residential, and logistics functions.
NEOM Northwest
Coastal tourism integration and captive fabrication yards are compressing project timelines for experimental commercial typologies. Red Sea Global leverages controlled development zones to test modular steel framing and cross-laminated timber at scale. The linear city concept is redrawing conventional submarket boundaries for office and retail absorption patterns.
Saudi Arabia Commercial Real Estate Market Competitive Landscape
Portfolio diversification dominates the current landscape as developers rebalance exposure across property types and development stages. The competitive structure concentrates around sovereign-linked entities, family conglomerates, and specialized hospitality developers. Three strategic archetypes define positioning: mixed-use superblock integrators, religious tourism adjacency specialists, and coastal mega-project operators. M&A activity and land-bank consolidation represent the dominant competitive moves as Vision 2030 unlocking accelerates greenfield access.
Within the mixed-use superblock tier, Kingdom Holding Company and Emaar The Economic City exemplify scale-driven positioning across Riyadh and King Abdullah Economic City respectively. Among religious tourism adjacency specialists, Jabal Omar Development Company occupies a distinctive position near Makkah's holy sites. Red Sea Global represents the coastal mega-project archetype through its controlled development of the northwestern coastline. Dar Al Arkan Real Estate Development Company and Al Akaria anchor mid-market residential-commercial integration across secondary cities.
| Leading Market Players |
|---|
| Arriyadh Development Co. |
| Kingdom Holding Company |
| Jabal Omar Development Company |
| Red Sea Global |
| RAFAL Real Estate |
| Dar Al Arkan Real Estate Development Company |
| Emaar The Economic City |
| Al Saedan Real Estate Co. |
| Al Akaria (Saudi Real Estate Company) |
| Others |
Value Network & Pricing Analysis
Steel and aluminum input costs from East Asian supply bases cascade through fixed-price contract structures into compressed developer margins across Riyadh's Grade-A office pipeline. Procurement teams now specify modular steel framing packages to offset volatility exposure while maintaining construction velocity.
Pricing Analysis
Volume concentrates in mid-tier warehouse shells near Special Economic Zone perimeters, while margins accrue to smart building-certified Grade-A office stock in Riyadh's central business district. Price differentiation hinges on SFDA fire safety certification tier and MEP redundancy specifications. Cost compression in secondary district retail developments is intensifying because imported materials volatility transfers risk to contractors on fixed-price structures. Logistics operators demonstrate lowest price sensitivity due to bonded storage tariff advantages, while flex-office startup tenants negotiate aggressively on short-term license agreements.
Supply Chain Analysis
Dual-sourcing mandates from institutional developers now require qualified suppliers in China, South Korea, and the UAE for structural steel and MEP components to mitigate single-source vulnerability. Factory-fabricated cross-laminated timber and modular framing systems draw from European and Southeast Asian fabrication yards. Logistics chokepoints at Jeddah Islamic Port and King Abdulaziz Port in Dammam concentrate delivery risk for just-in-time construction schedules. Distribution runs through captive fabrication yards at Red Sea Global coastal developments and third-party logistics hubs near Riyadh ring road interchanges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled MEP installation and smart building commissioning capacity constraints prop pricing power for contractors with qualified labor pools. SFDA harmonization elevates compliance costs that selective developers can absorb through premium positioning.
For Market Incumbents: Hedge against materials volatility through backward integration into captive steel fabrication partnerships in the Eastern Province. Consolidate land-bank positions near Riyadh Metro corridor stations before transit-oriented development overlays mature. Lock in municipal pre-approvals to compress inter-agency coordination timelines that threaten phased development execution.
For New Entrants and Emerging Players: Enter via climate-controlled logistics shell development in Jeddah's port-adjacent industrial zones where bonded storage demand outpaces supply. Target secondary district infill retail in Riyadh where foot traffic redistribution creates absorption gaps. Pursue joint venture structures with local sponsors for greenfield land access under Vision 2030 unlocking.
For Investors and Strategic Acquirers: Distressed-cycle entries favor renovated legacy stock in Jeddah's older districts where energy efficiency retrofit requirements strand undercapitalized owners. Long-term viability centers on assets with in-place cash flows from multinational corporate tenants. Watch SFDA enforcement velocity as the inflection signal for accelerated replacement cycles in aging submarkets.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fabrication Scale-Up | Red Sea Global's captive yards compress construction timelines for coastal commercial typologies. |
| Transit-Oriented Development Overlay | Riyadh Metro corridor stations redistribute foot traffic and create infill retail absorption opportunities. |
| SFDA Certification Investment | Gulf Standards Organization harmonization elevates fire safety mandates that accelerate aging stock replacement. |
| Special Economic Zone Positioning | Bonded logistics demand near customs-free processing zones attracts tariff-advantaged fulfillment operators. |
| REIT Channel Expansion | Regulatory frameworks deepen liquidity for stabilized income streams with mandated distribution requirements. |
Research Methodology
Independent corroboration across development executives at sovereign-linked entities, municipal planning officers in Riyadh and Jeddah, logistics operator procurement leads, and REIT portfolio managers underwrites the qualitative findings. Secondary validation draws from SFDA regulatory filings, Vision 2030 policy documents, municipal permitting databases, and customs zone activation records. Bottom-up project pipeline tracking triangulates against top-down investment flow estimates from institutional capital deployment patterns.
Comparable-period anchoring to historical absorption velocities across Riyadh's central business district, Jeddah's secondary submarkets, and Eastern Province industrial corridors structured the projection horizon. Segmentation modeling spanned property type, investment vehicle, end-user credit tier, and development stage maturity. CAGRs derive from rolling average investment commitments against deliverable square footage timelines. Forecast inputs incorporated e-commerce penetration trajectories and Special Economic Zone activation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged municipal permitting delays or acute steel price spikes. Assumptions reflect Vision 2030 zoning reform implementation velocity and bonded logistics demand continuity. Deviation in Riyadh Metro corridor station opening schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
UK Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Market
Commercial Real Estate
Indonesia Commercial Real Estate Market
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
Asia Pacific Co-Working Office Spaces Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
North America Coworking Spaces Market
Commercial Real Estate
Canada Commercial Real Estate Market
Commercial Real Estate
Canada Co-Working Office Spaces Market
Commercial Real Estate
Israel Commercial Real Estate Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Spain Commercial Real Estate Market
Commercial Real Estate
United Arab Emirates Co-Working Space Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
Egypt Commercial Real Estate Market