
 United Arab Emirates Co-Working Space Market | 2026-2036
United Arab Emirates Co-Working Space Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Co-Working Space Market Analytics
Freelancer and remote worker influx from South Asia and Europe is redrawing tenant composition across UAE co-working assets. IWG sustains the widest geographic footprint through its Regus and Spaces banners, anchoring premium locations in Dubai International Financial Centre and Abu Dhabi Global Market. Astrolabs specializes in startup acceleration infrastructure, positioning its JLT and Riyadh-adjacent hubs as venture-pipeline gateways rather than pure lease plays.
Co-working space denotes commercially operated real estate delivering flexible desk access, shared amenities, and on-demand office infrastructure without traditional long-term lease obligations. Operators typically provision high-speed connectivity, meeting room bookings, and hospitality services through membership-based contracts spanning daily to annual terms. Private office configurations within the Type segment command premium rates from enterprise clients seeking brand-differentiated satellite locations without capital deployment. Hot desking under Service Type attracts the highest volume turnover among freelancers and remote workers, though full-service packages generate superior per-seat economics through bundled concierge and IT support.
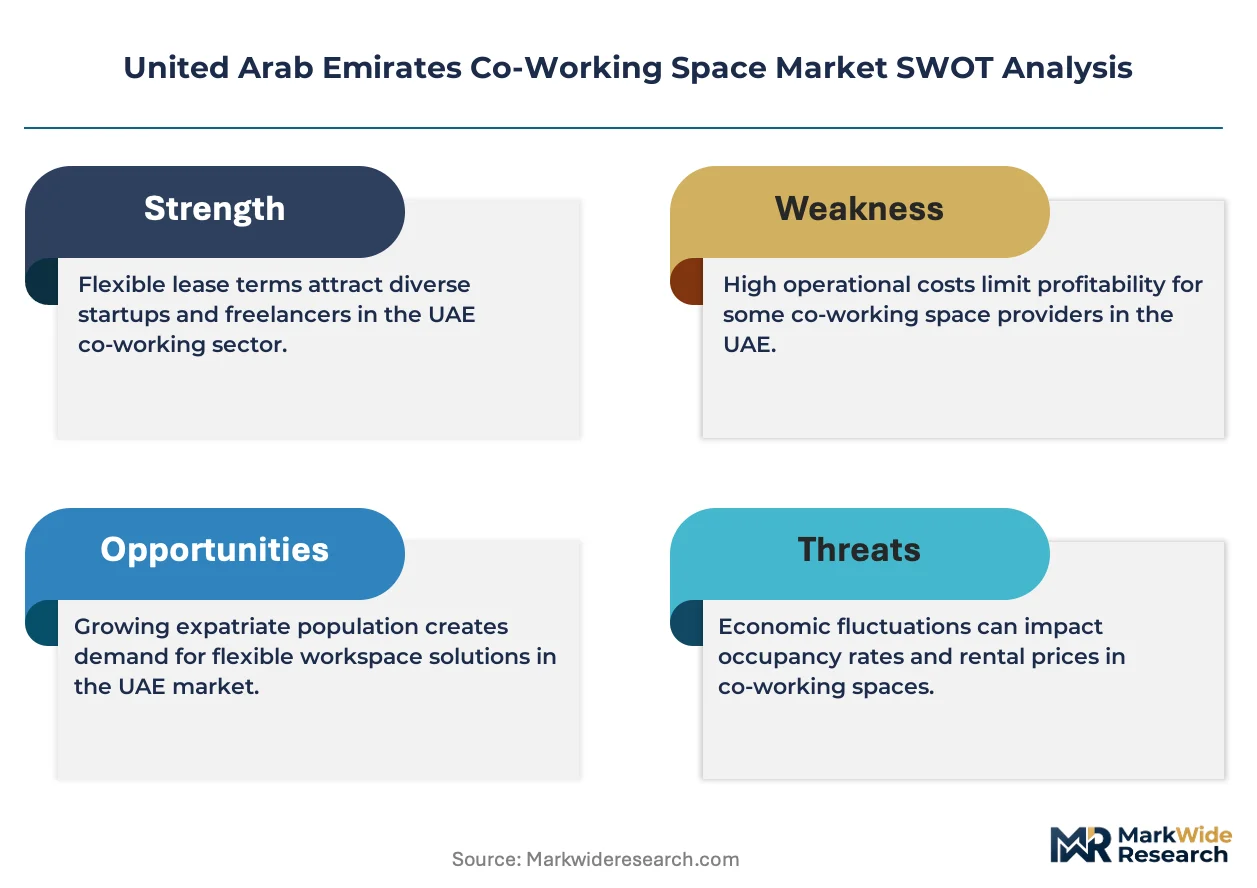
MOHAP workplace wellness guidelines and Dubai Municipality building codes jointly enforce air quality, density, and accessibility standards that filter subscale operators from licensed competition. TRAI-equivalent telecommunications oversight through the UAE Telecommunications and Digital Government Regulatory Authority mandates redundant connectivity uptime, elevating capital requirements for new market entrants. Stakeholders must weigh free zone licensing advantages against mainland lease economics as Dubai South and Abu Dhabi KIZAD expand competing innovation district footprints.
Market Dynamics
MOHAP wellness mandates and Dubai Municipality building codes are compressing operator margins while filtering subscale competition from licensed co-working assets across the emirates.
Growth Catalysts
- Smart-building IoT integration:Sensor networks optimizing energy consumption and space utilization are drawing enterprise satellite office demand toward certified intelligent buildings in Dubai's technology corridor.
- Free zone licensing advantages:Dubai South and Abu Dhabi KIZAD innovation districts offer streamlined business setup frameworks that reduce operational friction for foreign-operated co-working ventures.
- South Asian freelancer influx:Remote worker migration from India and Pakistan is expanding hot-desking volume turnover in Dubai International Financial Centre and Jumeirah Lakes Towers clusters.
Market Restraints
- Telecommunications redundancy costs:UAE Telecommunications and Digital Government Regulatory Authority uptime mandates impose elevated capital requirements for connectivity infrastructure that strain subscale operator economics.
- Prime real estate concentration:Limited Grade A office supply in Dubai's financial core concentrates lease pricing power with a handful of institutional landlords, compressing operator net operating income.
- Traditional long-term lease substitution:Some enterprise tenants retain preference for conventional office tenures in Abu Dhabi Global Market, limiting flexible workspace penetration among conservative institutional clients.
Strategic Opportunities
- Ras Al Khaimah and Fujairah expansion:Underpenetrated northern emirates present first-mover positioning for operators willing to anchor emerging free zone developments ahead of competitor saturation.
- Wellness certification premium tiering:MOHAP-compliant air quality and biophilic design standards enable rate differentiation from unlicensed informal operators in mainland Dubai.
- Enterprise white-label deployment:Real estate investment trusts and corporate occupiers seek turnkey flexible workspace management partnerships rather than direct operational investment.
Industry Challenges
- Facilities management talent scarcity:Qualified technicians capable of maintaining integrated building management systems and hospitality-grade service delivery command premium compensation in Dubai's tight labor pool.
- Multi-jurisdictional compliance complexity:Operators spanning Dubai mainland, DIFC, and Abu Dhabi Global Market must navigate divergent free zone authority requirements without centralized regulatory harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Co-Working Space Market |
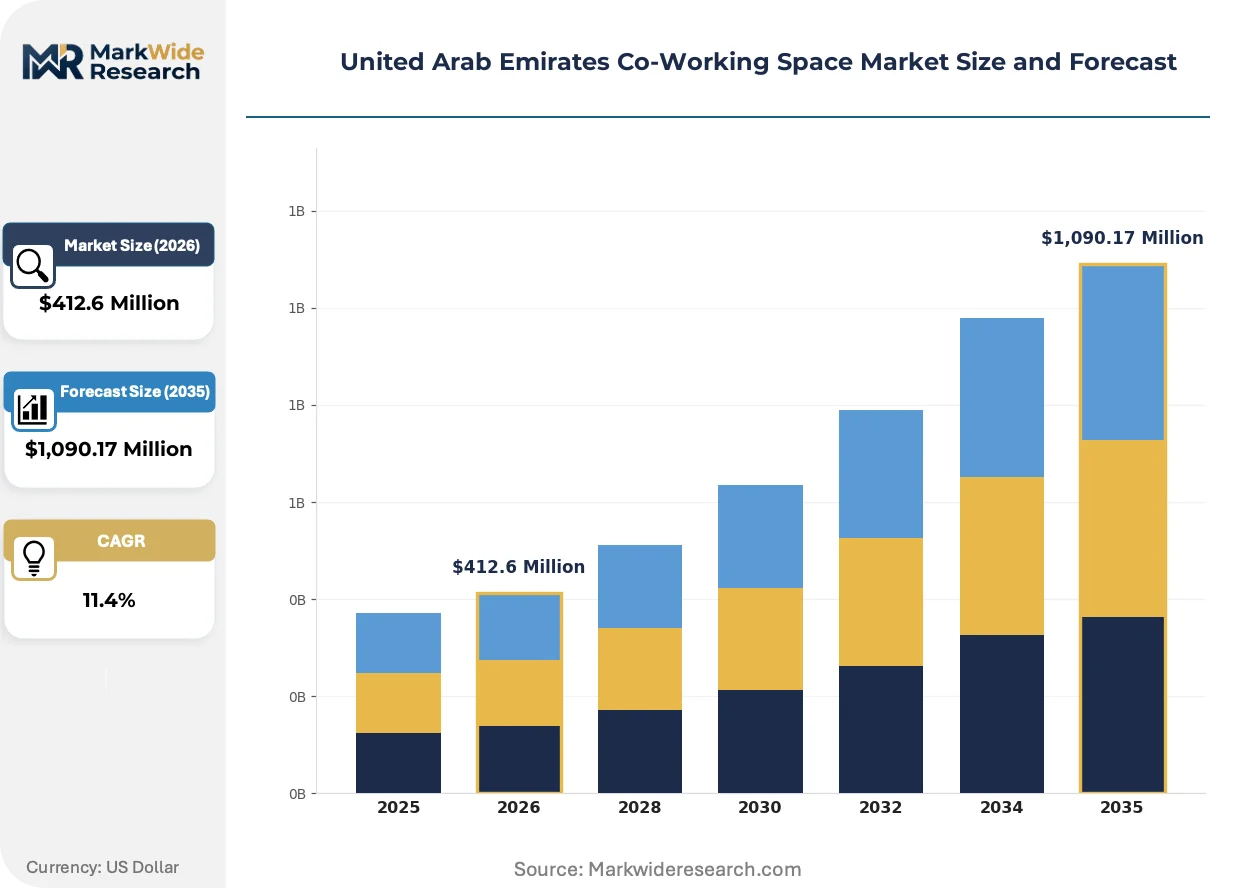
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,090.17 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Flex Space, Shared Office, Dedicated Desk, Private Office Service Type: Hot Desking, Virtual Office, Meeting Rooms, Full Service End User: Freelancers, Startups, Enterprises, Remote Workers Pricing Model: Pay-As-You-Go, Monthly Membership, Day Pass, Annual Subscription |
| Companies Covered | IWG (Regus, Spaces), WeWork, The Executive Centre, Servcorp, Astrolabs, Hub71, Impact Hub, Letswork, Cloud Spaces, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Co-Working Space Market Evolving Landscape
Technology convergence and regulatory compression are reconfiguring how co-working assets compete on experience differentiation rather than square-meter economics alone.
Building management system software is decomposing the traditional landlord-operator boundary by embedding predictive maintenance and dynamic space reconfiguration directly into lease infrastructure. Enterprise occupiers now expect API-accessible desk booking and environmental controls as standard provisioning. This capability compression is forcing independent operators to license third-party platforms or cede operational control to technology-enabled property managers.
MOHAP workplace wellness guidelines and Dubai Municipality density codes are mandating real-time air quality monitoring and maximum occupancy algorithms across licensed facilities. Operators must retrofit existing assets with sensor networks and automated ventilation response systems to maintain operating permits. Premium locations in Dubai International Financial Centre are responding fastest, embedding wellness certification into marketing collateral to justify rate premiums over mainland competitors.
Enterprise procurement teams are unbundling long-term workspace commitments into project-based satellite deployments with 30-day cancellation flexibility. Financial services and technology verticals in Abu Dhabi Global Market are displacing annual memberships with quarterly enterprise service agreements that bundle concierge support and dedicated IT infrastructure. This contractual fragmentation is most visible among multinational professional services firms rotating teams between London, Singapore, and Dubai hubs.
United Arab Emirates Co-Working Space Market Segmentation
Segmentation in the UAE co-working market reveals how tenant composition and contract structures are fragmenting under pressure from regulatory mandates and shifting workplace norms. Operators must align physical space configurations with pricing flexibility to capture divergent demand across Dubai's financial corridor and emerging northern emirate free zones.
Type:
Private Office configurations face the strongest substitution threat from enterprise satellite deployments in Abu Dhabi Global Market, where conventional lease retention competes directly with flexible alternatives.
- Flex Space:Open-plan environments with modular furniture systems enable rapid reconfiguration for event programming and pop-up corporate activations. Demand concentrates among marketing agencies and consulting firms rotating project teams through Dubai International Financial Centre hubs.
- Shared Office:Partitioned workstations within communal floorplates deliver cost efficiency for small professional services firms. Abu Dhabi KIZAD innovation district tenants favor this format for its balance of privacy and networking access.
- Dedicated Desk:Assigned seating with personal storage attracts hybrid workers seeking consistency without private room premiums. Dubai South free zone operators report strongest uptake among South Asian remote worker cohorts.
- Private Office:Enclosed suites with branded signage and dedicated infrastructure serve multinational satellite offices. MOHAP wellness compliance and redundant connectivity mandates elevate capital requirements, filtering subscale competitors from this tier.
Flex Space anchors the volume base while Private Office gains share at the steepest rate as enterprise procurement teams unbundle long-term commitments.
Service Type:
Cost tier differentiation separates commodity desk access from premium hospitality bundles, with margin compression most severe in undifferentiated hot-desking offerings.
- Hot Desking:Unassigned daily access with basic amenities generates highest turnover volume among transient users. Jumeirah Lakes Towers clusters see peak utilization from Indian and Pakistani freelancer influx during European winter months.
- Virtual Office:Mailing address and call handling without physical presence serves offshore company formations. Dubai Multi Commodities Centre free zone licensing frameworks drive concentration in this segment.
- Meeting Rooms:Hourly bookable conference facilities with AV infrastructure support client presentations and board meetings. Enterprise procurement teams in Abu Dhabi Global Market increasingly specify this as standalone service rather than bundled amenity.
- Full Service:Concierge support, IT helpdesk, and hospitality-grade F&B provisioning command premium rates. Dubai International Financial Centre locations justify rate multiples through MOHAP-compliant wellness certification and smart-building sensor integration.
Hot Desking delivers the transaction volume foundation whereas Full Service expands most quickly as operators seek per-seat economics improvement.
End User:
Customer type maturity varies sharply, with enterprise procurement sophistication forcing contractual innovation that startup and freelancer segments rarely demand.
- Freelancers:Individual remote workers prioritizing network reliability and transport accessibility over amenity depth. Dubai Metro proximity determines site selection more than brand recognition for this cohort.
- Startups:Venture-backed teams requiring scalable headcount flexibility and investor-facing address prestige. Astrolabs and similar acceleration-linked operators capture this demand through pipeline relationships rather than pure real estate plays.
- Enterprises:Multinational professional services and financial institutions deploying project-based satellite teams. Quarterly service agreements with 30-day cancellation clauses are displacing annual memberships in Abu Dhabi Global Market.
- Remote Workers:Employer-detached individuals seeking community infrastructure and visa facilitation. Ras Al Khaimah and Fujairah free zones target this segment with lower cost positioning than Dubai mainland alternatives.
Freelancers constitute the broadest user base while Enterprises drive the sharpest contract structure innovation.
Pricing Model:
Volume concentration in subscription formats is accelerating as operators seek revenue predictability to offset telecommunications redundancy capital burdens.
- Pay-As-You-Go:Per-hour or per-day billing without commitment serves sporadic users and trial conversions. Conversion rates to recurring formats remain lowest in this tier due to price sensitivity.
- Monthly Membership:Recurring desk access with standard amenity inclusion generates predictable revenue streams. Dubai South and Abu Dhabi KIZAD operators report this as their dominant contract format.
- Day Pass:Single-day bundled access marketed to tourists and intermittent business visitors. Hospitality sector crossover promotions in Dubai Marina cluster sustain this segment.
- Annual Subscription:Prepaid long-term access with rate discounts and priority booking rights. Enterprise procurement teams in financial services verticals increasingly negotiate customized annual frameworks rather than standard published rates.
Monthly Membership anchors operator revenue stability while Annual Subscription climbs fastest as procurement teams seek budget predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MOHAP workplace wellness mandates and Dubai Municipality building codes anchor regulatory oversight across the emirates, filtering subscale operators while concentrating licensed competition in premium corridors.
Dubai
Startup density and enterprise satellite office deployment drive demand concentration in Dubai International Financial Centre and Jumeirah Lakes Towers. Smart-building IoT integration requirements under Dubai Municipality codes elevate capital barriers for new entrants. Technology corridor assets command rate premiums through sensor-network energy optimization and wellness certification.
Abu Dhabi
Abu Dhabi Global Market attracts multinational professional services firms seeking project-based satellite deployments with quarterly cancellation flexibility. KIZAD innovation district offers streamlined free zone licensing that reduces operational friction for foreign-operated ventures. Conservative institutional clients here retain partial preference for conventional office tenures, capping flexible workspace penetration.
Sharjah
Cost-sensitive remote worker cohorts from South Asia gravitate toward Sharjah's lower positioning versus Dubai mainland alternatives. The emirate's media free zone licensing frameworks support virtual office formations for offshore company structures. Industrial zone adjacency creates hybrid demand from logistics and trading firms seeking flexible administrative space.
Northern Emirates
Ras Al Khaimah and Fujairah present first-mover positioning for operators willing to anchor emerging free zone developments ahead of competitor saturation. Visa facilitation programs target employer-detached remote workers seeking community infrastructure at reduced cost. Infrastructure gaps in telecommunications redundancy impose elevated capital requirements that filter subscale entrants.
United Arab Emirates Co-Working Space Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the UAE co-working market. IWG sustains the widest geographic footprint through multi-banner operations, while venture-linked accelerators occupy distinct pipeline-positioning roles. Three archetypes dominate: global network operators with premium address portfolios, startup-ecosystem integrators trading equity access for tenancy, and technology-enabled flex-space platforms optimizing per-seat economics. Competitive moves concentrate on wellness certification differentiation and enterprise white-label management partnerships.
Among global network operators, IWG anchors premium locations through its Regus and Spaces banners in Dubai International Financial Centre and Abu Dhabi Global Market. Astrolabs exemplifies the startup-ecosystem archetype, positioning JLT and Riyadh-adjacent hubs as venture-pipeline gateways rather than pure lease plays. WeWork occupies the technology-enabled tier, though its regional footprint has contracted against more capital-efficient local competitors.
| Leading Market Players |
|---|
| IWG (Regus, Spaces) |
| WeWork |
| The Executive Centre |
| Servcorp |
| Astrolabs |
| Hub71 |
| Impact Hub |
| Letswork |
| Cloud Spaces |
| Others |
Value Network & Pricing Analysis
Quarterly enterprise service agreements with 30-day cancellation clauses now dominate procurement patterns across Dubai International Financial Centre and Abu Dhabi Global Market, locking in supply access for multinational tenants while ceding rate visibility to operators bearing telecommunications redundancy capital burdens.
Pricing Analysis
Project-based satellite deployments anchor the dominant pricing structure, with enterprise procurement teams unbundling annual commitments into cancellable quarterly frameworks. Price differentiation rests on MOHAP wellness certification tier and smart-building IoT integration grade, with DIFC locations commanding premiums over mainland competitors. Cost compression intensifies in hot-desking tiers as South Asian freelancer influx expands volume turnover at depressed per-seat rates. Freelancers exhibit highest price sensitivity, while financial services enterprises prioritize flexibility over rate optimization.
Supply Chain Analysis
Port congestion at Jebel Ali and container availability fluctuations on Asia-Gulf trade lanes elevate inbound logistics costs for sensor networks and building management system hardware. Supply concentrates in China, South Korea, and Germany for IoT components, redundant connectivity infrastructure, and modular furniture systems. Raw material dependencies span steel framing, fiber-optic cabling, and air quality monitoring sensors. Single-source vulnerability in telecommunications equipment creates procurement risk. Distribution runs through Dubai-based facilities management contractors serving free zone developments across the emirates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as building management system software embeds predictive maintenance into lease infrastructure, forcing operators to choose between third-party platform licensing and operational control surrender.
For Market Incumbents: Consolidate wellness certification differentiation through accelerated MOHAP compliance investments ahead of regulatory tightening. Lock in enterprise white-label management partnerships with real estate investment trusts to defend against technology-enabled property manager encroachment. Deepen backward integration into facilities management talent pools to offset technician scarcity in Dubai's tight labor market.
For New Entrants and Emerging Players: MOHAP fast-track certification offers the most penetrable wedge into premium tiers currently dominated by IWG and Astrolabs. Target Ras Al Khaimah and Fujairah free zones ahead of competitor saturation, anchoring visa facilitation programs for employer-detached remote workers. Deploy community infrastructure partnerships with northern emirate development authorities as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward venture-linked accelerators trading pipeline access for tenancy rather than pure lease-play operators facing margin compression. Long-term viability favors technology-enabled flex-space platforms with API-accessible infrastructure and enterprise procurement integration. Watch quarterly enterprise service agreement penetration rates as the inflection signal distinguishing sustainable operators from commodity desk providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Wellness Certification Fast-Track | MOHAP-compliant air quality standards enable rate premiums over unlicensed mainland competitors. |
| Enterprise White-Label Partnership | Turnkey flexible workspace management contracts with REITs reduce direct operational capital deployment. |
| Smart-Building IoT Integration | Sensor-network energy optimization satisfies Dubai Municipality codes while attracting satellite office demand. |
| Free Zone Licensing Streamlining | Dubai South and KIZAD innovation district frameworks reduce operational friction for foreign-operated ventures. |
| Facilities Management Talent Acquisition | Qualified building management system technicians command premium compensation in Dubai's constrained labor pool. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with co-working space managers, enterprise procurement leads, free zone authority representatives, and facilities management contractors. Secondary validation drew from UAE Telecommunications and Digital Government Regulatory Authority filings, Dubai Municipality building code documentation, MOHAP workplace wellness guidelines, and free zone licensing framework disclosures. Bottom-up tenant composition analysis and top-down real estate absorption estimates were triangulated to anchor market sizing.
Across the analysis window, the forecasting framework modeled demand trajectories by space type, service tier, end-user segment, and pricing model, with additional dimensioning by free zone jurisdiction. CAGRs were derived from fitted growth curves calibrated to historical absorption patterns and projected supply pipeline completions. Key inputs included startup density indices, enterprise satellite deployment intentions, and telecommunications infrastructure investment disclosures.
Underlying assumptions cover regulatory enforcement continuity, free zone licensing competitiveness, and remote worker migration patterns, with deviation risk concentrated in telecommunications redundancy mandate timing and Grade A office supply availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Canada Hospitality Real Estate Market
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
Egypt Commercial Real Estate Market
Commercial Real Estate
South Africa Commercial Real Estate Market
Commercial Real Estate
Latin America Commercial Real Estate Market
Commercial Real Estate
Canada Co-Working Office Spaces Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Qatar Commercial Real Estate Market
Commercial Real Estate
Global Shared Office Spaces Market
Commercial Real Estate
Saudi Arabia Commercial Real Estate Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
UAE Commercial Real Estate Market
Commercial Real Estate
Malaysia Commercial Real Estate Market
Commercial Real Estate
UK Commercial Real Estate Market