
 Ceramic Fabrication Services Market | 2026-2036
Ceramic Fabrication Services Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Fabrication Services Market Analysis
REACH is decoupling low-investment fabricators from European aerospace and medical supply chains. Morgan Advanced Materials leverages its vertical integration across oxide and non-oxide grades to sustain qualification advantages. Saint-Gobain Ceramic Materials anchors its position through captive raw material sourcing and furnace infrastructure. CoorsTek, Inc. competes on precision CNC machining tolerances for semiconductor chamber components.
Ceramic fabrication services encompass the shaping, sintering, and precision finishing of inorganic, non-metallic materials—typically alumina, zirconia, silicon carbide, or silicon nitride—into dimensionally stable components that withstand temperatures exceeding 1,200°C, corrosive media, and electrical stress. CNC machining of oxide ceramics still occupies the largest revenue pool due to established aerospace and industrial buyer relationships, while 3D printing of non-oxide ceramics represents the fastest-expanding segment as layer-wise consolidation enables geometries impossible through subtractive methods. Injection molding dominates medical device applications where batch consistency and surface finish specifications override unit cost sensitivity.
EMA's Medical Device Regulation and EPA emissions standards for kiln operations are reshaping facility capital requirements and site selection across the European fabrication base. FDA device master file expectations and ISO 13485 quality system mandates govern medical-grade ceramic sourcing decisions in the United States. Fabricators must monitor evolving dual carbon goals from China's MEE and the EU Green Deal's embedded carbon reporting rules, as these frameworks will determine which kiln technologies and energy contracts preserve market access.
Market Dynamics
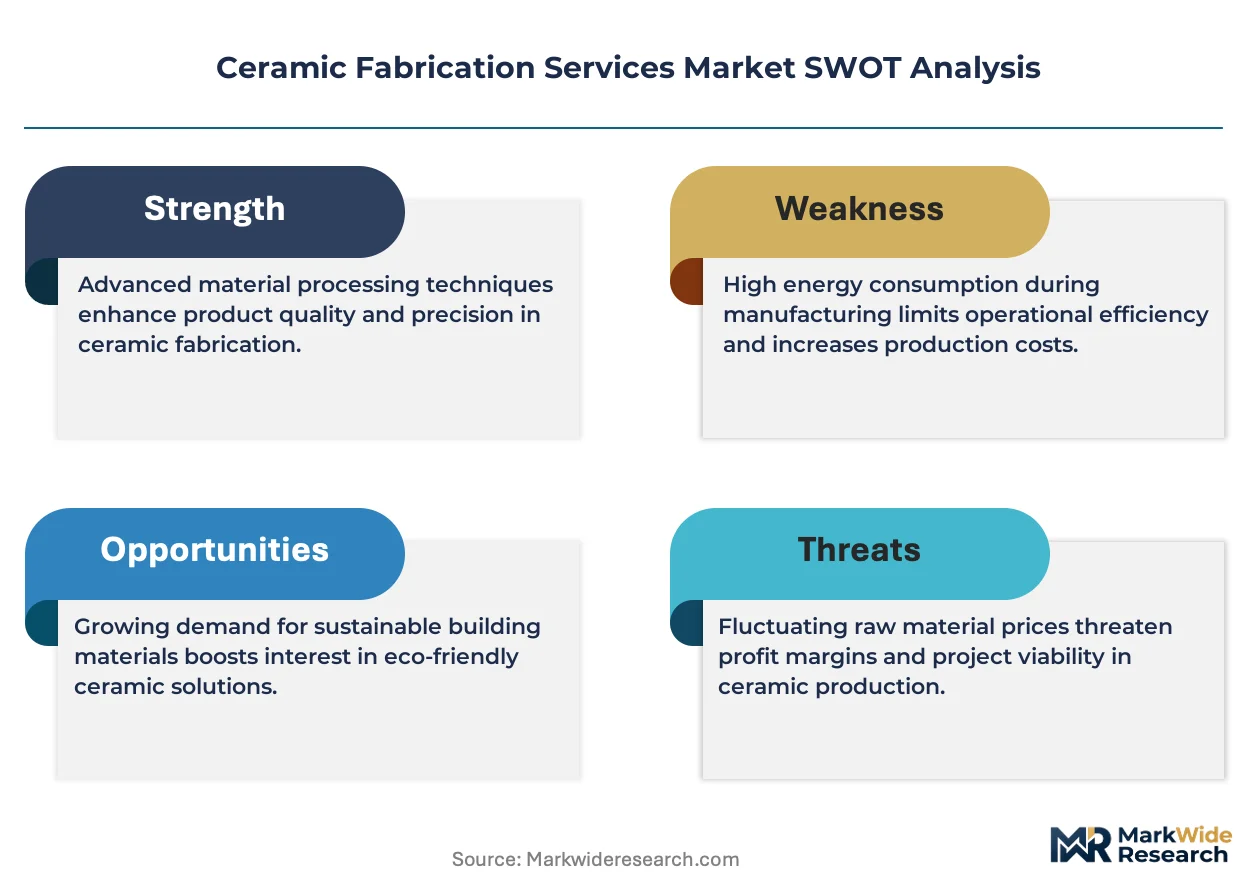
REACH compliance deadlines are compressing qualification timelines for European fabricators, forcing rapid kiln technology upgrades and raw material traceability investments that smaller operators cannot absorb.
Growth Catalysts
- Aerospace CMC Adoption:Turbine blade manufacturers are expanding ceramic matrix composite contracts to fabricators with NADCAP heat treatment accreditation. This pulls precision machining capacity toward aviation-certified production lines.
- EMA MDR Medical Device Pathway:The European Medical Device Regulation's 2021 implementation created a certification backlog that now favors established ceramic implant fabricators with notified body relationships.
- Germany's Industrial Ceramics Corridor:Fabrication demand concentrates around Cologne and Düsseldorf, where proximity to RWTH Aachen's materials research cluster accelerates technology transfer into production-scale sintering.
Market Restraints
- Yttria-Stabilized Zirconia Price Volatility:Rare earth supply concentration in Chinese processing facilities exposes fabricators to input cost swings that contract pricing cannot fully hedge.
- High-Purity Alumina Supply Concentration:Three Australian and Brazilian mining groups control spherical alumina feedstock for semiconductor-grade components, creating single-source vulnerability.
- Non-Oxide Ceramic Machinability Limits:Silicon carbide and silicon nitride's extreme hardness restricts achievable surface finishes without diamond-tool grinding, elongating cycle times versus oxide alternatives.
Strategic Opportunities
- India's PLI Scheme for Medical Devices:Production-linked incentives for domestic implant manufacturing create first-mover advantages for fabricators establishing ISO 13485-certified facilities near Chennai or Hyderabad.
- EU Green Deal Embedded Carbon Reporting:Fabricators with renewable-powered tunnel kilns can capture premium positioning as Scope 3 disclosure mandates penetrate aerospace supply chains.
- Additive Manufacturing Convergence:Binder jetting of silicon carbide combined with reaction sintering enables closed-loop cooling channels that subtractive methods cannot produce, opening defense thermal management contracts.
Industry Challenges
- Pyrometry and Atmosphere Control Expertise:The specialized knowledge required for multi-zone kiln profiling and controlled atmosphere sintering exceeds available trained technician supply in most fabrication hubs.
- FDA Device Master File Timelines:Ceramic implant fabricators face 18-24 month qualification cycles for new material grades, compressing RROI windows before patent cliffs erode pricing power.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Fabrication Services Market |
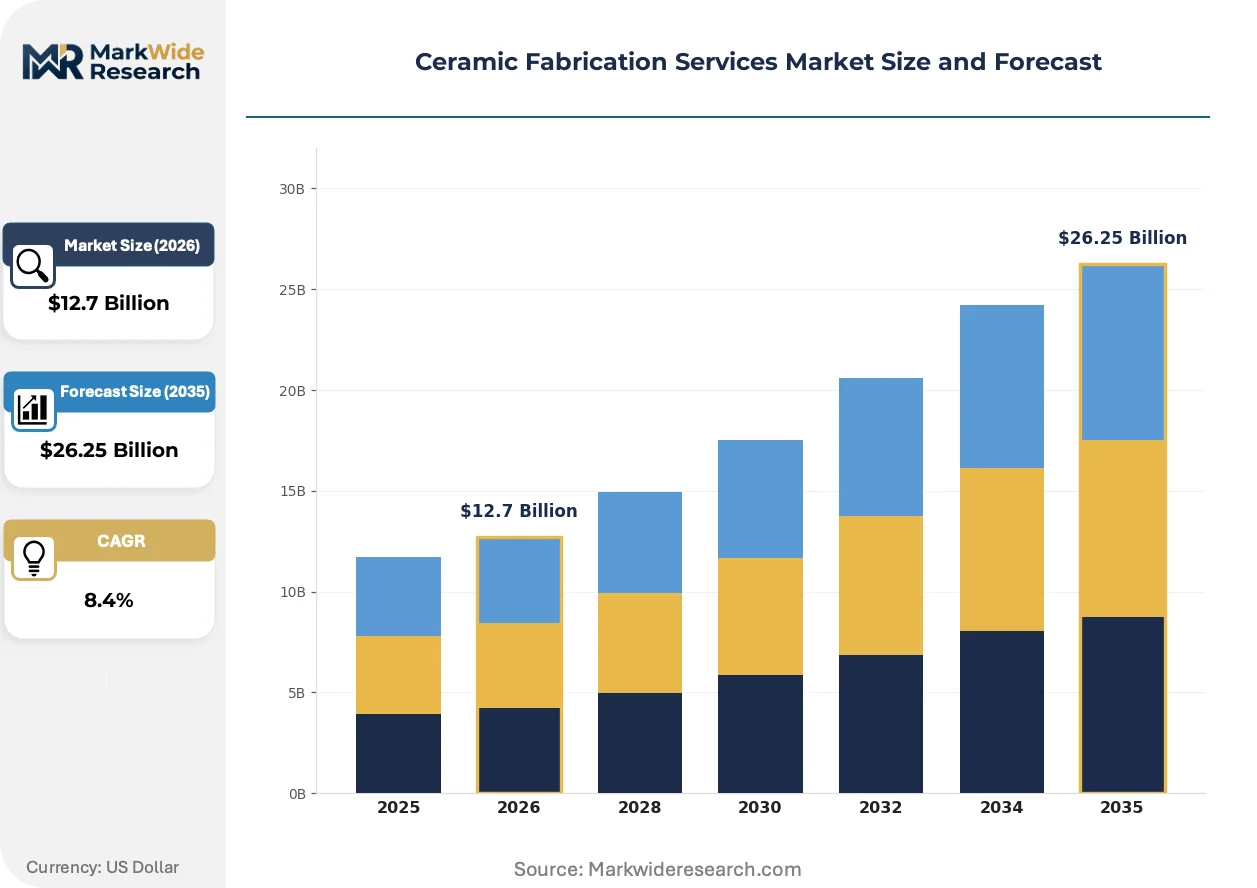
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $26.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: 3D Printing, CNC Machining, Injection Molding, Casting Material Type: Oxide Ceramics, Non-Oxide Ceramics, Composite Materials, Refractories End User: Aerospace, Electronics, Automotive, Medical Devices Application: Structural Components, Insulators, Wear Parts, Heat Shields |
| Companies Covered | Morgan Advanced Materials, Saint-Gobain Ceramic Materials, CoorsTek, Inc., Rauschert Group, NGK Insulators, Kyocera Corporation, 3M Advanced Materials, Advanced Ceramics Manufacturing, CeramTec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Fabrication Services Market Emerging Trajectories
Digital thread integration across sintering, machining, and inspection workflows is compressing first-article qualification cycles while enabling lot-level traceability that regulators now mandate.
Hybrid manufacturing—combining binder jetting with isostatic pressing and CNC finishing—is unifying geometric freedom with structural density requirements. Aerospace heat shield manufacturers are adopting this workflow for complex leading-edge components. The approach collapses traditional stage-gate handoffs between forming and finishing operations into continuous digital workflows.
REACH Annex XVII restrictions on refractory ceramic fibers are forcing furnace insulation retrofits across European fabrication facilities. The regulation's 2023 enforcement wave triggered capital allocation toward synthetic mullite and polycrystalline fiber alternatives. German fabricators near the Cologne-Düsseldorf corridor report 15-20% facility downtime during kiln relining compliance sprints.
Semiconductor OEMs are consolidating supplier panels around fabricators with integrated metrology and particle contamination controls. This behavioral shift displaces arm's-length component sourcing with embedded engineering partnerships. The pattern is most visible in Arizona and Hsinchu, where fab expansion timelines demand concurrent ceramic chamber component development rather than catalog procurement.
Ceramic Fabrication Services Market Segmentation
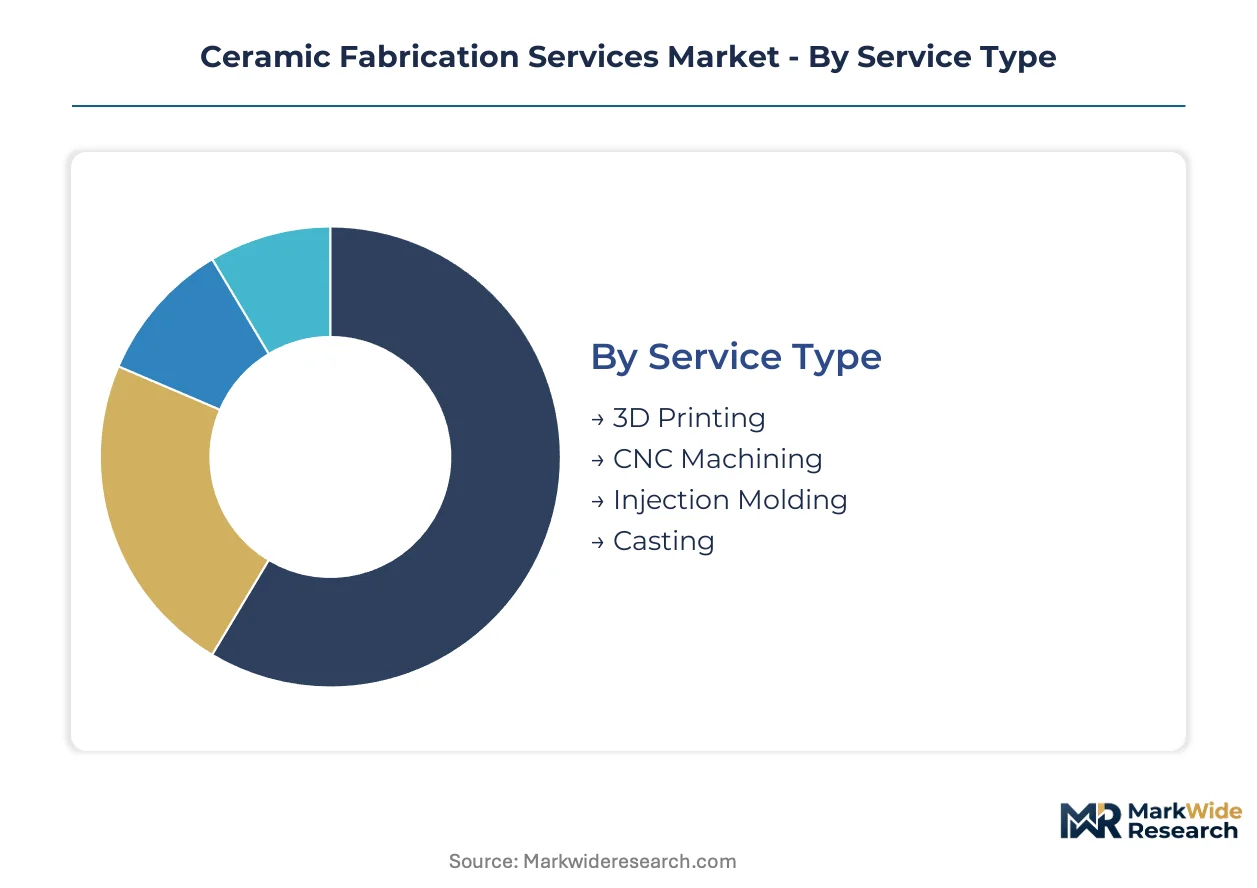
Service modality determines capital intensity and margin structure across ceramic fabrication. Material chemistry governs thermal performance ceilings and regulatory qualification pathways. End-use verticals impose divergent certification standards that fragment vendor capabilities.
Service Type:
Technology selection hinges on geometric complexity tolerance versus surface finish requirements.
- CNC Machining:Subtractive processing of sintered blanks achieves sub-micron tolerances on alumina and zirconia workpieces. Aerospace turbine seal manufacturers in Germany's Cologne-Düsseldorf corridor anchor demand for five-axis precision grinding capacity.
- 3D Printing:Binder jetting and stereolithography of silicon carbide slurries enable conformal cooling geometries impossible through conventional forming. Defense thermal management programs are pulling capacity toward reaction-sintering post-processing infrastructure.
- Injection Molding:Ceramic powder feedstock injection suits high-volume medical implant production where batch consistency overrides unit economics.
- Casting:Slip casting and gelcasting of refractory shapes serves industrial furnace component demand with lower tooling amortization pressure.
CNC Machining leads on scale; 3D Printing leads on momentum.
Material Type:
Cost tier alignment separates qualified aerospace supply chain participants from commodity refractory vendors.
- Oxide Ceramics:Alumina and zirconia formulations dominate semiconductor chamber component fabrication due to established EPA emissions compliance pathways for kiln operations. Arizona fab expansion timelines concentrate procurement around vendors with integrated particle contamination controls.
- Non-Oxide Ceramics:Silicon carbide and silicon nitride withstand temperatures exceeding 1,400°C in turbine blade applications. REACH Annex XVII restrictions on refractory ceramic fibers are forcing European fabricators toward synthetic mullite insulation retrofits that preserve non-oxide processing capability.
- Composite Materials:Ceramic matrix composites combine oxide matrices with silicon carbide fiber reinforcement for aerospace heat shields.
- Refractories:Magnesia and dolomite-based shapes serve steel and cement kiln lining replacement cycles.
Oxide Ceramics leads on scale; Non-Oxide Ceramics leads on momentum.
End User:
Customer type dictates quality system mandates and contract duration structures.
- Aerospace:NADCAP heat treatment accreditation gates participation in ceramic matrix composite turbine blade contracts. Fabricators with existing aerospace metallurgy certifications leverage audit overlap to compress qualification timelines.
- Medical Devices:FDA device master file expectations and ISO 13485 quality system mandates govern implant-grade ceramic sourcing. EMA MDR implementation created certification backlog favoring established notified body relationships.
- Electronics:Semiconductor OEMs consolidate supplier panels around fabricators with embedded metrology partnerships.
- Automotive:Sensor housing and spark plug insulator demand scales with electric vehicle inverter packaging requirements.
Aerospace leads on scale; Medical Devices leads on momentum.
Application:
Functional performance requirements determine material specification and finishing intensity.
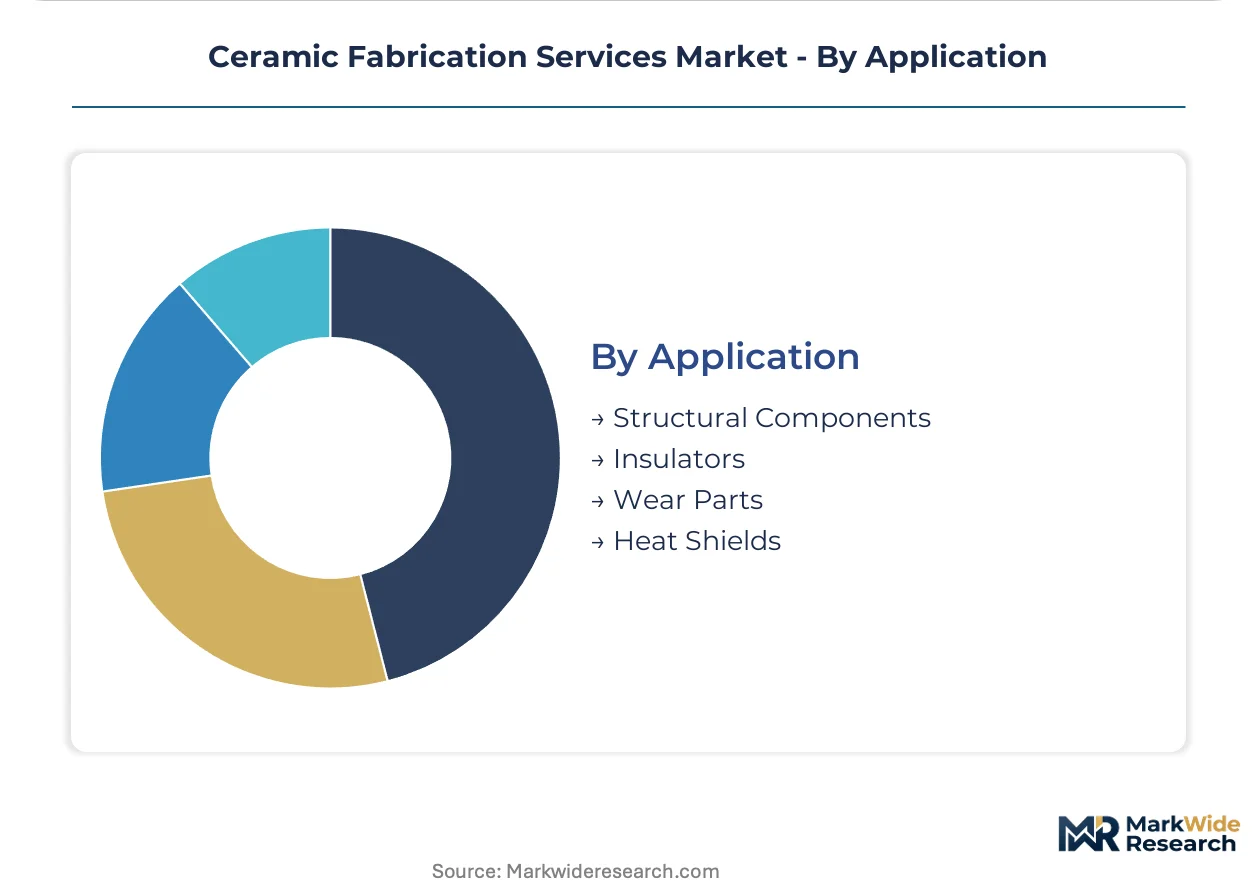
- Structural Components:Load-bearing ceramic brackets and fasteners for aerospace assemblies require isostatic pressing followed by diamond-tool grinding to achieve fatigue-resistant surface integrity.
- Heat Shields:Leading-edge thermal protection systems for re-entry vehicles and hypersonic platforms demand hybrid manufacturing combining binder jetting with reaction sintering.
- Insulators:High-voltage ceramic bushings and substrate cores for power electronics rely on alumina purity grades with controlled dielectric loss characteristics.
- Wear Parts:Zirconia and silicon nitride seals, bearings, and cutting tool inserts prioritize hardness and fracture toughness over thermal shock resistance.
Structural Components leads on scale; Heat Shields leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pyrometry technicians and kiln atmosphere control specialists concentrate in Germany's industrial ceramics corridor, anchoring European fabrication capability. RWTH Aachen's materials science program feeds engineering talent directly into Cologne-Düsseldorf production facilities. This workforce density shapes regional competitive positioning.
United States
Semiconductor OEM expansion in Arizona and Oregon pulls precision ceramic fabrication capacity toward integrated metrology partnerships. EPA emissions standards for tunnel kiln operations govern facility permitting timelines. Greater Phoenix concentrates chamber component development concurrent with fab construction schedules.
Germany
Aerospace turbine seal manufacturers anchor demand for five-axis CNC grinding of oxide ceramics in the Cologne-Düsseldorf corridor. REACH Annex XVII restrictions on refractory ceramic fibers forced 15-20% facility downtime during 2023 compliance retrofits. RWTH Aachen's research cluster accelerates technology transfer into production-scale sintering.
Japan
Electronics substrate fabricators in the Nagoya-Chubu region supply silicon carbide components for power inverter packaging. METI's industrial decarbonization roadmap shapes kiln energy contract negotiations. Kyushu's advanced materials parks host non-oxide ceramic reaction-sintering infrastructure.
China
Rare earth processing concentration in Jiangxi and Inner Mongolia exposes fabricators to yttria-stabilized zirconia price volatility. MEE dual carbon goals and embedded carbon reporting rules determine which kiln technologies preserve aerospace supply chain access. Yangtze River Delta clusters concentrate semiconductor-grade alumina finishing capacity.
India
Medical device implant fabricators near Chennai and Hyderabad pursue CDSCO alignment with ISO 13485 quality system mandates. PLI scheme production-linked incentives for domestic manufacturing create first-mover advantages for certified facility establishment. Telangana's medical device parks offer expedited regulatory pathway support.
Ceramic Fabrication Services Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across qualification-intensive segments. Market structure tilts toward consolidation in aerospace and medical verticals where NADCAP and FDA device master file requirements erect entry barriers. Three archetypes dominate: vertically integrated material-to-component suppliers, precision machining specialists with captive metrology, and additive manufacturing pure-plays with reaction-sintering partnerships. Capacity expansion and strategic technology licensing represent the dominant competitive moves as fabricators race to secure renewable-powered kiln infrastructure ahead of EU Green Deal disclosure mandates.
Among UK-based diversified materials groups, Morgan Advanced Materials occupies a position exemplifying vertical integration across oxide and non-oxide grades. Saint-Gobain Ceramic Materials anchors the European tier through captive raw material sourcing and furnace infrastructure. CoorsTek, Inc. represents the precision-machining archetype competing on CNC tolerance achievement for semiconductor chamber components.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| Saint-Gobain Ceramic Materials |
| CoorsTek, Inc. |
| Rauschert Group |
| NGK Insulators |
| Kyocera Corporation |
| 3M Advanced Materials |
| Advanced Ceramics Manufacturing |
| CeramTec GmbH |
| Others |
Supply Flow & Price Mechanics
Yttria-stabilized zirconia feedstock from Jiangxi and Inner Mongolia processing facilities flows through three distinct pricing tiers before reaching aerospace turbine seal manufacturers in Germany's Cologne-Düsseldorf corridor. Rare earth supply concentration grants Chinese processors outsized leverage over European fabricators locked into long-term qualification cycles with Airbus and Rolls-Royce procurement teams.
Pricing Analysis
Bundled precision-machining-plus-certification packages command premium positioning against unbundled component-only supply, particularly for NADCAP-accredited heat treatment workflows. Three-tier pricing structure across NADCAP-certified premium, ISO-standard mid-market, and uncertified economy levels separates aerospace-qualified fabricators from commodity refractory vendors. Cost compression in the mid-tier is intensifying because REACH Annex XVII compliance retrofits have stranded smaller European operators with unabsorbed capital burdens. Medical device OEMs exhibit lowest price sensitivity due to FDA device master file switching costs, while industrial furnace component buyers drive aggressive spot-market negotiation.
Supply Chain Analysis
High-purity spherical alumina feedstock draws from Australian and Brazilian mining group concentration, with semiconductor-grade finishing capacity clustering in Arizona and the Yangtze River Delta. Silicon carbide powder supply rests on Chinese and Japanese specialty ceramic producers, while synthetic mullite insulation alternatives for REACH-compliant kilns source predominantly from German and American refractory manufacturers. Single-source vulnerability in yttria-stabilized zirconia exposes fabricators to input cost volatility that contract pricing cannot fully hedge. Distribution runs through direct OEM engineering partnerships for aerospace and medical verticals, with arm's-length catalog procurement persisting in industrial refractory replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EMA MDR implementation and REACH Annex XVII enforcement have created structural demand for qualified fabrication capacity that outstrips supply.
For Market Incumbents: Deepen captive raw material sourcing into high-purity alumina and yttria-stabilized zirconia to defend margin position against Chinese rare earth price volatility. Expand renewable-powered tunnel kiln infrastructure ahead of EU Green Deal embedded carbon disclosure mandates penetrating aerospace supply chains. Fortify NADCAP and ISO 13485 certification portfolios against emerging additive manufacturing pure-plays seeking reaction-sintering partnerships. For New Entrants and Emerging Players: Enter via India's PLI scheme for medical devices, establishing ISO 13485-certified facilities near Chennai or Hyderabad before CDSCO alignment hardens qualification barriers. Target defense thermal management programs seeking binder-jetted silicon carbide with conformal cooling geometries impossible through subtractive methods. Pursue embedded engineering partnerships with semiconductor OEMs in Greater Phoenix rather than arm's-length component catalog positioning. For Investors and Strategic Acquirers: Roll-up economics work for precision CNC machining specialists with captive metrology because semiconductor OEM consolidation around integrated supplier panels fragments acquisition targets into sub-scale regional players. Five-to-ten year viability hinges on renewable kiln infrastructure positioning ahead of Scope 3 disclosure mandates. Watch for EU Green Deal enforcement waves triggering distressed asset availability among REACH-noncompliant European fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Kiln Infrastructure Investment | EU Green Deal embedded carbon reporting rules will disqualify fossil-fuel-dependent fabricators from Airbus and Safran supply chains. |
| Reaction Sintering Partnership | Binder jetting of silicon carbide combined with post-processing enables defense thermal management contracts closed to subtractive competitors. |
| NADCAP Heat Treatment Accreditation | Aerospace turbine blade manufacturers mandate this certification for ceramic matrix composite fabrication contracts. |
| ISO 13485 Facility Certification | EMA MDR backlog favors established notified body relationships for hip and dental implant ceramic sourcing. |
| Captive Raw Material Sourcing | Vertically integrated alumina and zirconia supply hedges against Australian and Brazilian mining group price volatility. |
Methodological Framework
Coverage spans Germany's industrial ceramics corridor, the United States semiconductor fabrication belt, and India's emerging medical device parks, with primary inputs from each. Fabrication plant managers, aerospace procurement officers at Tier 1 turbine manufacturers, biomedical engineers at orthopedic OEMs, and kiln technology specialists provided operational data. Secondary validation drew from EMA MDR submission databases, EPA emissions compliance filings, REACH Annex XVII enforcement notices, and customs trade records for yttria and alumina feedstock. Bottom-up capacity estimates triangulated against top-down end-use demand projections.
Rate-of-change decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include service modality, material chemistry, end-use vertical, and geographic regulatory cluster. CAGRs derived from fitted growth curves incorporating aerospace CMC adoption curves, semiconductor fab construction timelines, and medical device regulatory backlog clearance rates. Forecast inputs incorporated kiln technology upgrade cycles, rare earth supply concentration risk, and renewable energy contract availability.
Inputs from plant managers and procurement officers were available through the study window; gaps in private contract pricing between fabricators and aerospace OEMs introduce uncertainty bands around margin projections. Forecasts reflect assumptions about REACH enforcement consistency, PLI scheme continuity, and NADCAP accreditation timeline stability. Regulatory enforcement waves, rare earth export restriction episodes, and semiconductor capital expenditure cycles warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Engineering Ceramics Market
Ceramics
Sodium Aluminum Silicate Market
Ceramics
Ceramic Lining Market
Ceramics
Liquid Sodium Silicate Market
Ceramics
Zirconium Dioxide Market
Ceramics
Kaolin Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Thermal Spray Powder Market
Ceramics
Stoneware Market
Ceramics
Pottery Ceramics Market
Ceramics
India Kaolin Market
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
Potassium Silicate Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
Global Ceramic Balls Market
Ceramics
Saudi Arabia Ceramic Tiles Market