
 Healthcare Satellite Connectivity Market | 2026-2036
Healthcare Satellite Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Satellite Connectivity Market Outlook
ISO 27001 certification for healthcare data security is rotating as a gatekeeping standard that determines vendor eligibility for hospital procurement cycles. Inmarsat Global Limited leverages its LEO-GEO hybrid architecture to sustain connectivity in maritime and remote terrestrial settings. Hughes Network Systems anchors North American market presence through managed service contracts with federal health agencies. Iridium Communications competes on polar coverage reliability where geostationary alternatives fail.
Healthcare satellite connectivity denotes the use of orbiting relay systems to transmit encrypted patient data, diagnostic imagery, and real-time clinical video between dispersed medical facilities and central health networks, typically operating across Ku-band, Ka-band, and L-band frequencies with latency thresholds dictated by application criticality. GEO platforms still dominate installed base revenue given their proven reliability for store-and-forward telemedicine, though LEO constellations represent the fastest-expanding segment as their sub-50ms latency enables synchronous surgical consultation and remote procedure guidance. Data Transmission applications command premium pricing due to DICOM file sizes and HIPAA-mandated encryption overhead, while Remote Monitoring is maturing into a volume-driven connectivity tier as chronic disease management programs scale.
The FCC enforces spectrum allocation and rural broadband subsidy rules that directly shape eligible vendor pools, while FDA oversight of connected medical devices imposes cybersecurity validation requirements on satellite-linked diagnostic hardware. Australia's TGA and Brazil's ANVISA maintain parallel device registration pathways that satellite service providers must navigate for market access. Stakeholders should monitor evolving LEO constellation launch schedules and corresponding spectrum coordination disputes as these will determine which vendors can guarantee quality-of-service commitments under emerging telehealth reimbursement frameworks.
Market Dynamics
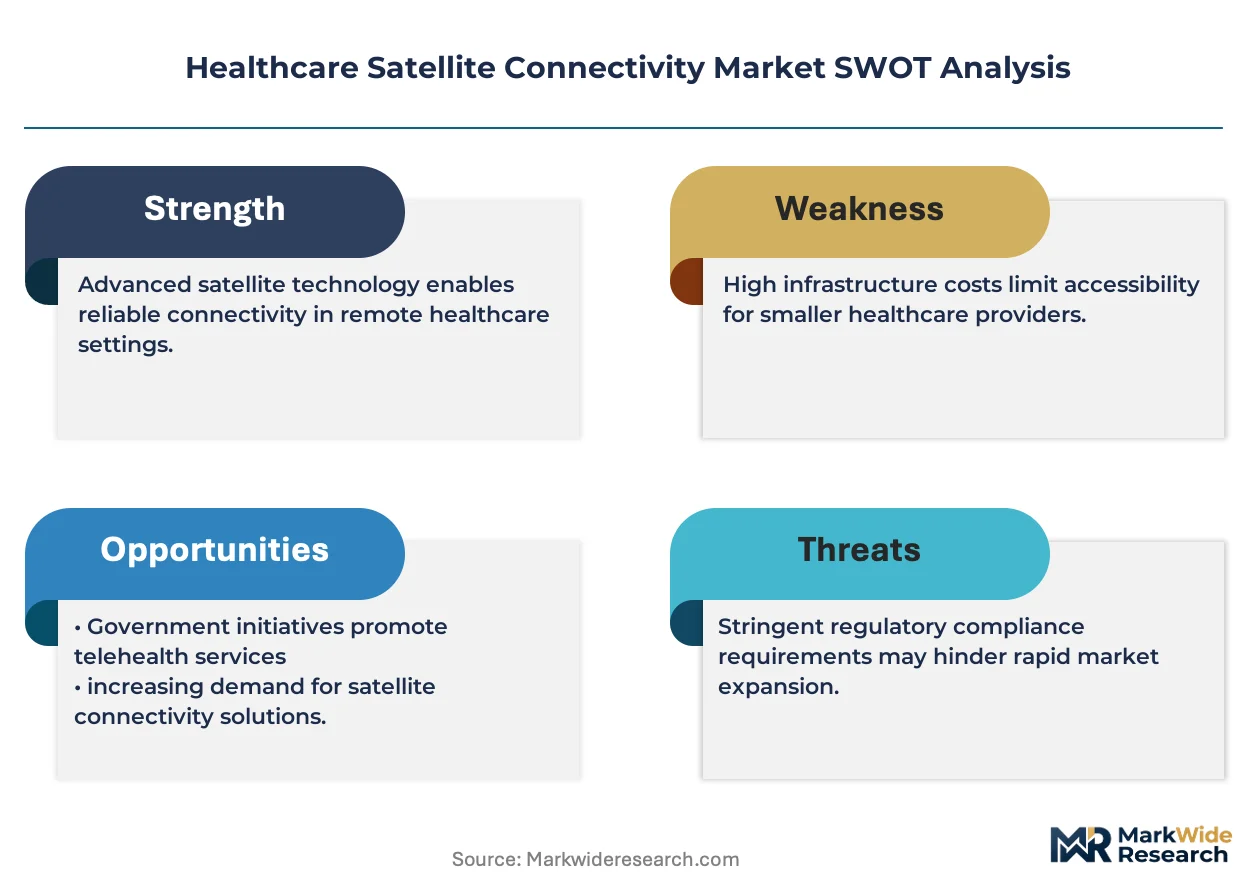
LEO constellation deployment schedules are compressing latency benchmarks below 50ms, forcing GEO operators to defend installed-base relationships through managed service bundling and encryption-grade differentiation.
Growth Catalysts
- Rural Digital Opportunity Fund:FCC subsidy allocations for satellite broadband in underserved census tracts are expanding addressable hospital networks in Montana, Alaska, and West Virginia.
- Store-and-forward telemedicine:GEO platforms deliver proven reliability for asynchronous diagnostic imaging transmission where synchronous video remains impractical.
- Chronic disease management:Remote patient monitoring programs in Australia are scaling device connectivity requirements for diabetes and cardiovascular cohorts.
Market Restraints
- Spectrum coordination disputes:ITU filing backlogs between LEO operators and incumbent GEO licensees are delaying quality-of-service guarantees in shared Ku-band allocations.
- Terminal cost structure:Flat-panel phased array antennas for LEO tracking remain 3-4x the cost of fixed GEO dishes, constraining clinic-level deployment.
- Brazilian ANVISA device registration:Parallel cybersecurity validation pathways for satellite-linked diagnostic hardware extend market access timelines by 14-18 months.
Strategic Opportunities
- Maritime health services:Cruise line medical centers and offshore platform clinics represent underpenetrated demand for hybrid LEO-GEO connectivity.
- ISO 27001 certification:Hospital procurement cycles are hardening data security prerequisites, creating vendor eligibility gaps for uncertified operators.
- AI-assisted diagnostics:Convergence of edge computing with low-latency satellite links enables real-time pathology analysis at remote surgical sites.
Industry Challenges
- RF engineer scarcity:Specialized talent for Ka-band link budget optimization and rain fade mitigation commands premium compensation in competitive labor markets.
- HIPAA encryption overhead:Payload compression ratios suffer under mandatory end-to-end security protocols, degrading effective throughput for DICOM imagery.
- Legacy HIS integration:Hospital information systems built for terrestrial MPLS architectures require middleware adaptation for satellite backhaul failover.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Satellite Connectivity Market |
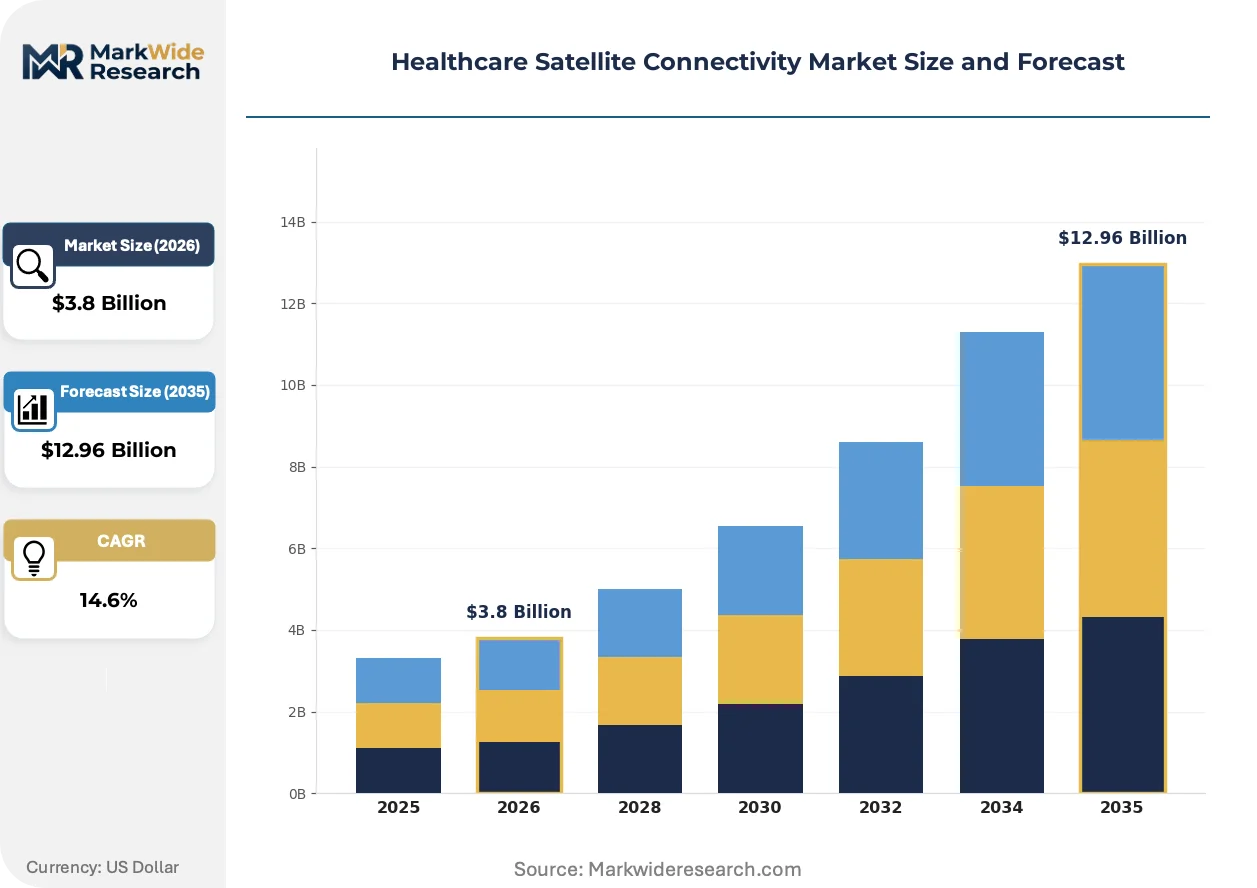
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: VSAT, MEO, LEO, GEO Application: Telemedicine, Remote Monitoring, Emergency Response, Data Transmission End User: Hospitals, Clinics, Research Institutions, Medical Facilities Service Type: Managed Services, Consulting, Support Services, Connectivity Services |
| Companies Covered | X2nSat, Eutelsat Communications, Inmarsat Global Limited, Iridium Communications, Expedition Communications, Hughes Network Systems, Globalstar, DISH Network, SES S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Satellite Connectivity Market Strategic Shifts
Terminal form factors and network architectures are diverging sharply as LEO constellations mature and regulatory frameworks harden data sovereignty requirements.
Flat-panel electronically steered antennas are miniaturizing from maritime-grade dimensions to suitcase-portable units suitable for mobile clinics and disaster response deployments. Emergency medical services in Queensland and Northern Territory are piloting these units for flood-isolated community access. The technology is miniaturizing total cost of ownership for intermittent-use scenarios where fixed infrastructure cannot be justified.
Australia's TGA has aligned cybersecurity guidance for connected medical devices with FDA premarket submission templates, reducing dual-registration burden for satellite-linked diagnostic hardware. Device manufacturers are consolidating validation documentation across both jurisdictions. Cardiology monitoring systems with embedded satellite modems face accelerated review timelines under this harmonization.
Hospital procurement departments are consolidating connectivity contracts under single-vendor managed service agreements rather than maintaining separate terrestrial and satellite relationships. Federal health agencies in the United States are driving this consolidation through standardized RFP language. The shift compresses vendor switching cycles and elevates ISO 27001 certification to table-stakes status.
Healthcare Satellite Connectivity Market Segmentation
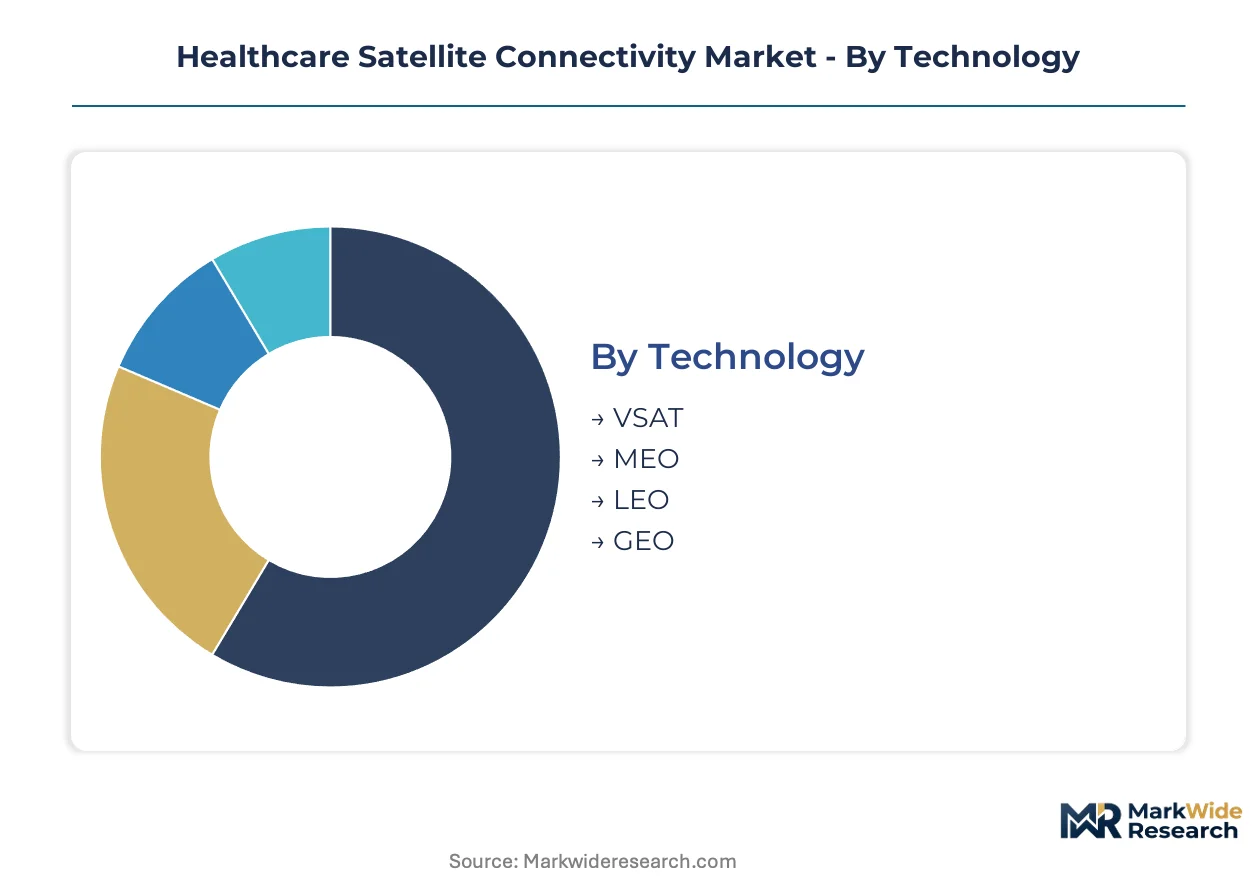
Healthcare satellite connectivity segments diverge sharply by latency tolerance, procurement authority, and reimbursement eligibility. Understanding where margin pools concentrate versus where volume scales reveals vendor positioning strategies.
Technology:
Margin pools cluster in low-latency architectures where synchronous clinical applications command premium pricing.
- LEO:Low Earth orbit constellations deliver sub-50ms latency through dense satellite swarms, enabling real-time surgical consultation and remote procedure guidance. Demand concentrates in United States rural hospital networks where FCC Rural Digital Opportunity Fund subsidies offset terminal costs. This segment is expanding most quickly as constellation deployment accelerates.
- GEO:Geostationary platforms maintain proven reliability for store-and-forward telemedicine and asynchronous diagnostic imaging transmission. Australia and Brazil leverage GEO infrastructure where terrestrial gaps persist and synchronous video remains impractical. Established installed-base relationships defend revenue through managed service bundling.
- MEO:Medium Earth orbit systems balance latency and coverage for maritime health services and offshore platform clinics.
- VSAT:Very Small Aperture Terminal technology enables clinic-level deployment with compact dish requirements for remote medical facilities.
The dominant share belongs to GEO, while LEO is closing the gap fastest.
Application:
Application segmentation tracks reimbursement codes and clinical workflow integration requirements.
- Data Transmission:DICOM file transmission for diagnostic imagery commands premium pricing due to HIPAA-mandated encryption overhead and payload compression challenges. United States federal health agencies drive standardization through procurement specifications. Volume scales with chronic disease management program expansion.
- Telemedicine:Synchronous video consultation requires sub-100ms latency for acceptable clinical interaction, favoring LEO architectures in Montana, Alaska, and West Virginia census tracts. FCC subsidy eligibility shapes addressable market boundaries.
- Remote Monitoring:Device connectivity for diabetes and cardiovascular cohorts in Australia is maturing into a volume-driven tier with standardized modem requirements.
- Emergency Response:Queensland and Northern Territory pilot suitcase-portable flat-panel antennas for flood-isolated community access.
Data Transmission captures the highest margin per connection, while Remote Monitoring scales fastest on unit volume.
End User:
End-user segmentation reflects procurement sophistication and integration complexity with hospital information systems.
- Hospitals:Large health networks consolidate connectivity contracts under single-vendor managed service agreements with ISO 27001 certification as table-stakes eligibility. United States federal RFP standardization compresses vendor switching cycles.
- Clinics:Rural and mobile clinic deployments favor flat-panel phased array terminals despite 3-4x cost premiums over fixed GEO dishes.
- Research Institutions:Polar coverage requirements for field stations favor Iridium Communications reliability where geostationary alternatives fail.
- Medical Facilities:Cruise line medical centers and offshore platform clinics represent underpenetrated hybrid LEO-GEO demand.
Hospitals anchor procurement value, though Clinics show steepest expansion trajectory as terminal costs compress.
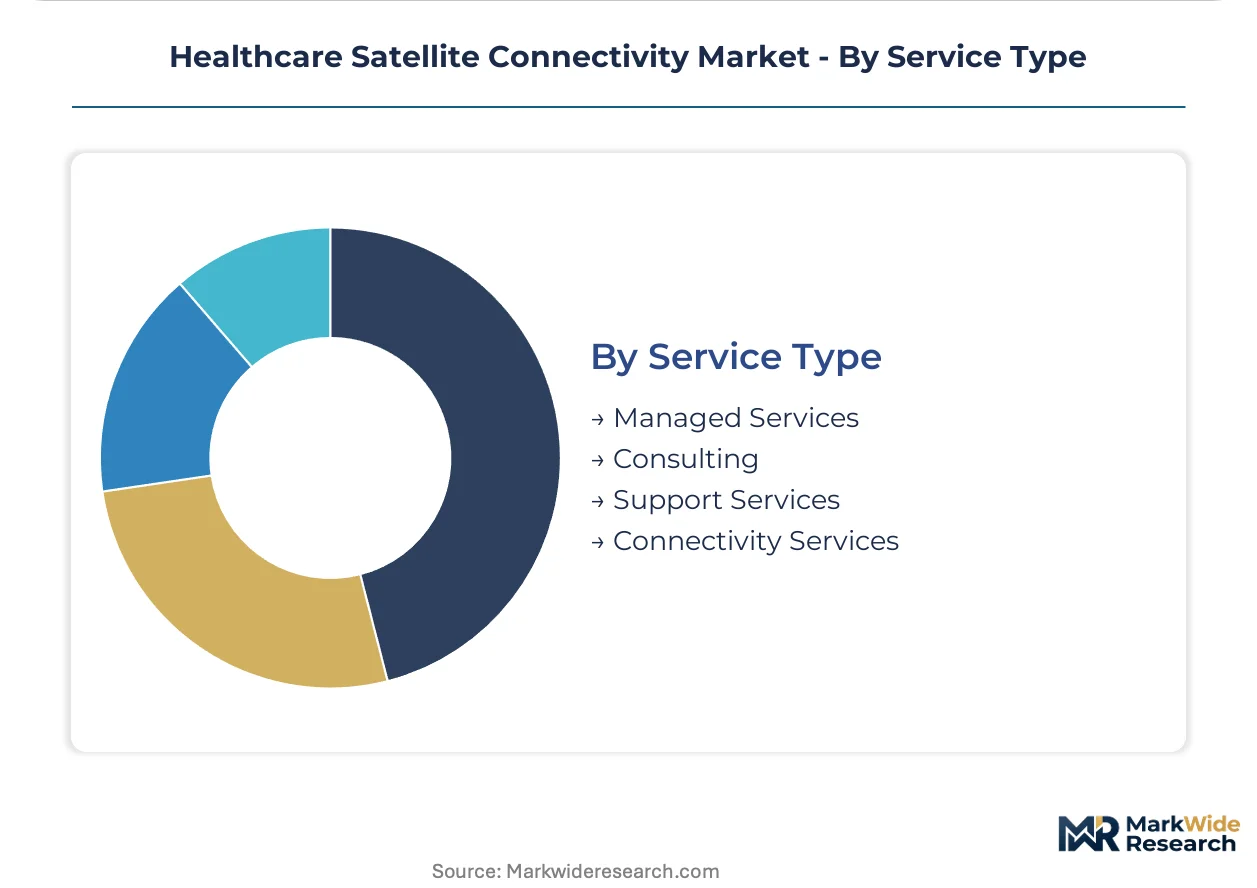
Service Type:
Service segmentation tracks vendor capability depth and customer technical staffing levels.
- Managed Services:End-to-end network operation with guaranteed quality-of-service commitments captures recurring revenue from hospital procurement departments seeking to outsource RF engineering specialization. Hughes Network Systems anchors North American presence through federal health agency contracts.
- Connectivity Services:Raw bandwidth provision competes on price with terrestrial failover integration requirements.
- Consulting:Ka-band link budget optimization and rain fade mitigation command premium compensation given RF engineer scarcity.
- Support Services:Middleware adaptation for legacy HIS integration addresses hospital information system architectures built for terrestrial MPLS.
Managed Services holds the revenue concentration, while Consulting gains share fastest amid talent constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in rural census tracts drive satellite connectivity investment where terrestrial fiber remains uneconomical. The United States, Australia, and Brazil concentrate demand through distinct subsidy mechanisms and regulatory pathways.
United States
Montana, Alaska, and West Virginia hospital networks deploy LEO terminals for synchronous telemedicine consultations. The FCC's Rural Digital Opportunity Fund subsidizes terminal costs in underserved census tracts. Federal health agencies in Washington D.C. standardize procurement specifications that compress vendor switching cycles.
Australia
Queensland and Northern Territory emergency services pilot flat-panel antennas for flood-isolated community access. The TGA harmonized cybersecurity guidance with FDA templates to accelerate satellite-linked device registration. Chronic disease management programs in remote Aboriginal communities scale remote monitoring device deployments.
Brazil
Amazon basin clinics rely on GEO platforms where synchronous video remains impractical. ANVISA's parallel cybersecurity validation pathways extend market access timelines by 14-18 months for satellite-linked diagnostic hardware. São Paulo-based hospital networks consolidate connectivity contracts under single-vendor managed service agreements.
Canada
Arctic and sub-Arctic health stations require polar coverage reliability for year-round connectivity. Health Canada maintains device registration pathways aligned with FDA premarket submission standards. Northern Territories health authorities negotiate bulk terminal procurement to offset LEO phased array cost premiums.
Germany
Bavarian alpine rescue services integrate satellite backhaul for emergency medical response in terrain-blocked valleys. The country's national telecom regulator enforces spectrum coordination rules that shape LEO-GEO hybrid deployment strategies. Munich-area medical device manufacturers validate satellite modem integration for export markets.
Healthcare Satellite Connectivity Market Competitive Environment
Player mix skews toward integrated satellite operators with hybrid orbit capabilities and specialized connectivity providers focused on healthcare verticals. Market structure concentrates around established GEO operators defending installed-base relationships against LEO constellation entrants. Two strategic archetypes dominate: full-stack satellite operators managing proprietary constellations, and managed service providers bundling third-party capacity with healthcare-specific compliance layers. Competitive moves center on managed service contract consolidation and ISO 27001 certification acquisition to meet hospital procurement prerequisites.
Within the full-stack operator tier, Inmarsat Global Limited and Iridium Communications represent distinct orbital strategies. Inmarsat leverages LEO-GEO hybrid architecture for maritime and remote terrestrial continuity, while Iridium anchors polar coverage reliability where geostationary alternatives fail. Hughes Network Systems occupies a position among North American managed service specialists, exemplifying the federal health agency contract pathway. Eutelsat Communications and SES S.A. sit within the European GEO incumbent group, defending revenue through encryption-grade differentiation and service bundling.
| Leading Market Players |
|---|
| X2nSat |
| Eutelsat Communications |
| Inmarsat Global Limited |
| Iridium Communications |
| Expedition Communications |
| Hughes Network Systems |
| Globalstar |
| DISH Network |
| SES S.A. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lead times for flat-panel phased array antennas compress procurement flexibility for rural clinic networks and concentrate pricing power among LEO terminal manufacturers with captive semiconductor sourcing. This inventory constraint tightens margin structures for GEO operators defending installed-base relationships through managed service bundling.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate LEO terminal procurement for hospital networks, while GEO operators rely on fixed-rate managed service agreements with encryption-grade tiers. Price differentiation rests on ISO 27001 certification status and latency guarantees, with synchronous surgical consultation commanding premiums over store-and-forward telemedicine. Cost compression in standard connectivity tiers intensifies as FCC subsidy eligibility expands addressable demand. Rural clinics exhibit highest price sensitivity due to constrained capital budgets, while federal health agencies demonstrate lowest sensitivity given standardized RFP specifications.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for Ka-band RF components and flat-panel antenna subassemblies sourced from East Asian manufacturing clusters. Terminal manufacturing concentrates in Taiwan, South Korea, and Japan, with satellite payload integration anchored in France and the United States. The supply chain draws from gallium nitride semiconductors, high-frequency printed circuit boards, and precision waveguide components. Single-source vulnerability for phased array beamforming chips creates structural risk. Distribution runs through federal procurement channels and GPO contracts for hospital networks, with direct OEM relationships for maritime and offshore clinic deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF engineering specialization for Ka-band link optimization commands premium compensation and constrains vendor scaling, creating capability bottlenecks that determine competitive positioning in hospital procurement cycles.
For Market Incumbents: Fortify managed service relationships with federal health agencies through ISO 27001 certification maintenance and encryption-grade differentiation against LEO constellation entrants. Defend installed-base revenue in Australia and Brazil by bundling GEO reliability with hybrid LEO-GEO failover architectures. Capacity addition in maritime health services addresses underpenetrated cruise line and offshore platform demand. For New Entrants and Emerging Players: Lead with flat-panel terminal miniaturization for mobile clinic and emergency response deployments where intermittent-use scenarios resist fixed infrastructure investment. Target Queensland and Northern Territory flood-isolation pilots with suitcase-portable units. Go-to-market through state emergency services procurement rather than hospital capital expenditure cycles. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because satellite connectivity for rural healthcare exhibits recurring revenue durability under federal subsidy frameworks. Acquisition targets should display hybrid orbit capabilities with healthcare-specific compliance layers. The signal to watch is ITU spectrum coordination resolution timelines, which determine quality-of-service guarantee feasibility for emerging constellation operators.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Acquisition | Hospital procurement cycles harden data security prerequisites, creating vendor eligibility gaps for uncertified operators. |
| Hybrid LEO-GEO Architecture Deployment | Inmarsat leverages orbital diversity to sustain connectivity in maritime and remote terrestrial settings. |
| Flat-Panel Terminal Miniaturization | Queensland emergency services pilot suitcase-portable units for flood-isolated community access. |
| Federal Health Agency Contract Consolidation | Hughes Network Systems anchors North American presence through standardized RFP procurement pathways. |
| Polar Coverage Reliability Investment | Iridium Communications competes where geostationary alternatives fail for research institution field stations. |
Study Parameters
Initial hypotheses were tested against primary input from satellite network engineers, hospital procurement managers, biomedical equipment specialists, and FCC regulatory affairs leads and refined through secondary validation against SEC filings, ITU spectrum allocation databases, hospital GPO contract repositories, and CMS telehealth reimbursement guidance. Bottom-up terminal deployment estimates triangulated with top-down addressable market sizing across rural census tracts.
Variance decomposition across technology orbit tiers, application latency requirements, end-user procurement sophistication, and regional subsidy eligibility shaped analytical framework construction over the projection horizon. CAGRs derived from installed base erosion rates for GEO platforms and constellation deployment schedules for LEO entrants. Forecast inputs incorporated FCC Rural Digital Opportunity Fund allocation trajectories and ANVISA device registration timeline assumptions.
The analysis sits within stated boundaries; outcomes outside sustained federal subsidy commitment or accelerated ITU spectrum coordination would require recalibration. Forecasts reflect documented assumptions regarding terminal cost compression curves and LEO constellation launch reliability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Spain Satellite Imagery Services Market
Satellite
Europe Satellite Connectivity Market
Satellite
UAE Satellite Communication Market
Satellite
Spain Satellite-Based Earth Observation Market
Satellite
Middle East Satellite Imagery Services Market
Satellite
United Arab Emirates Satellite-Based Earth Observation Market
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
Satellite Attitude and Orbit Control System Market
Satellite
Flat Panel Satellite Antenna Market
Satellite
Reusable Satellite Launch Vehicle (RSLV) Market
Satellite
Asia-Pacific Satellite Attitude and Orbit Control System Market
Satellite
Satellite Signal Meter Market
Satellite
North America Satellite Launch Vehicle Market
Satellite
Global Commercial Satellite Broadband Market
Satellite
North America Satellite Attitude and Orbit Control System Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market