
 Satellite Backhaul Market | 2026-2036
Satellite Backhaul Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Backhaul Market Outlook
High-throughput silicon is restructuring terminal economics across the satellite backhaul value chain, displacing legacy gallium arsenide components in ground segment hardware. Eutelsat Group leverages its geostationary fleet to anchor premium managed services for European telecom operators. SpaceX competes through Starlink's low Earth orbit density, sustaining aggressive price positioning in unmanaged rural connectivity. Viasat differentiates via integrated modem and satellite platform control, dominating Ka-Band throughput performance for enterprise backhaul.
Satellite backhaul denotes the use of satellite links to transport cellular traffic between base stations and core networks, typically operating at C-Band (4–8 GHz), Ku-Band (12–18 GHz), or Ka-Band (26.5–40 GHz) frequencies with latencies ranging from 500–700 milliseconds for geostationary systems to sub-50 milliseconds for low Earth orbit constellations. Its primary purpose extends mobile network coverage to terrain where terrestrial fiber or microwave backhaul proves technically unfeasible or economically unjustified. Ka-Band capacity leads absolute throughput metrics but faces rain-fade susceptibility that constrains deployment in tropical climates, while managed services capture the dominant margin pool as telecom operators outsource ground infrastructure complexity. Hybrid services represent the fastest-growing service type as operators blend geostationary reliability with low Earth orbit latency for tiered service level agreements.
The FCC governs spectrum licensing and orbital slot coordination for non-geostationary systems in the United States, tightening debris mitigation standards that elevate launch and operational compliance costs. EMA spectrum harmonization efforts across European Union member states are streamlining cross-border satellite service authorization, reducing regulatory fragmentation for pan-regional backhaul providers. ITU Radio Regulations mandate coordination procedures that shape constellation deployment sequencing and market access timelines for new entrants. Stakeholders must monitor spectrum auction outcomes and orbital debris rulemaking as these decisions will determine viable constellation architectures and service pricing floors.
Market Dynamics
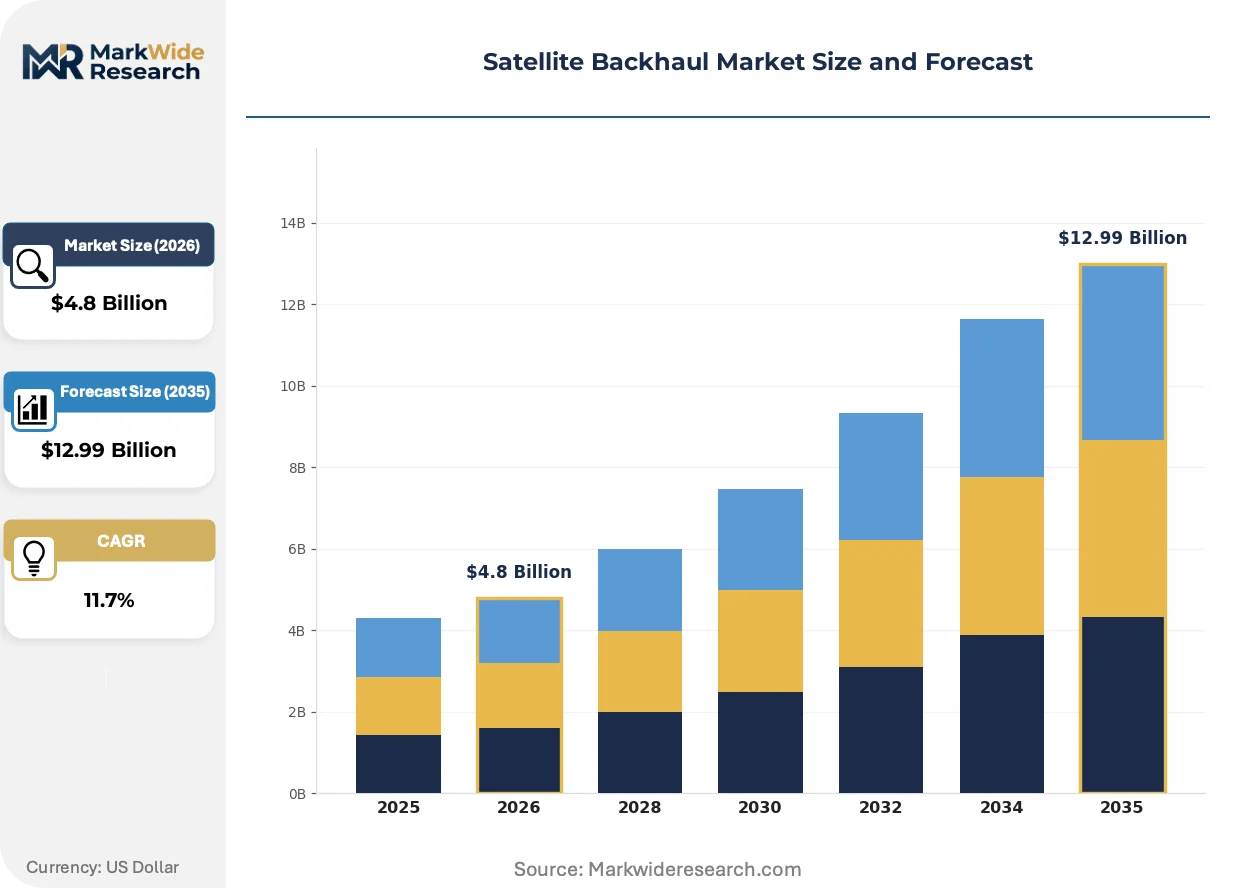
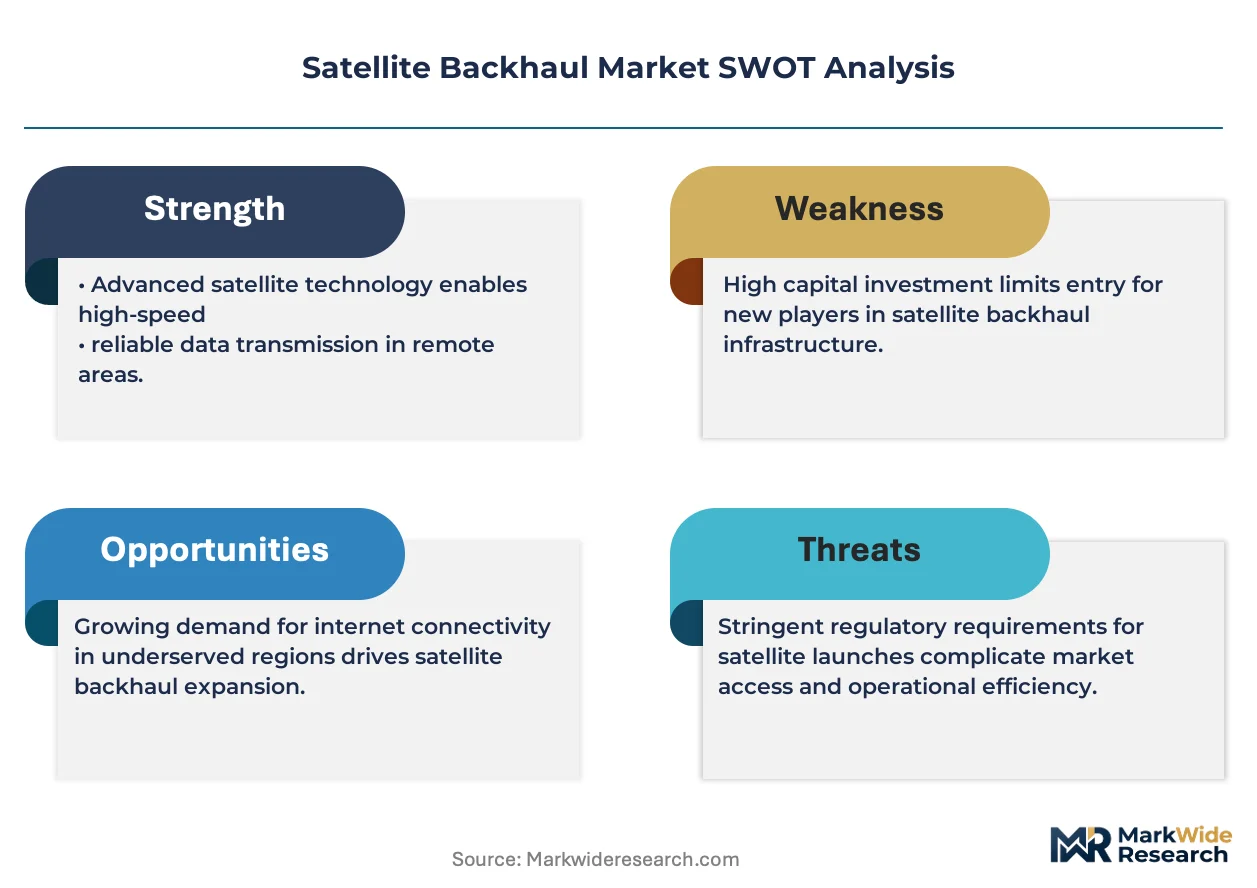
High-throughput silicon architectures are compressing ground segment costs while FCC orbital debris rules and ITU coordination mandates are extending constellation deployment timelines. These intersecting forces are redistributing margin pools from satellite manufacturing toward managed service orchestration and hybrid network integration.
Growth Catalysts
- Universal Service Obligations:ANATEL's mandates in Brazil compel telecom operators to extend coverage into Amazon basin territories unreachable by fiber. Satellite backhaul contracts satisfy these regulatory requirements while avoiding terrestrial infrastructure economics.
- Spectrum Harmonization:EMA coordination across EU member states reduces cross-border authorization friction for pan-regional service providers. This streamlines market access for constellation operators seeking multi-country terrestrial gateway deployments.
- Ku-Band Licensing Acceleration:FCC rule updates for non-geostationary orbit systems compress approval timelines for Ku-Band and Ka-Band allocations. This regulatory velocity enables faster constellation deployment and service commercialization.
Market Restraints
- Ka-Band Rain Fade Susceptibility:Tropical precipitation attenuation constrains reliable throughput in equatorial climates. This technical limitation restricts deployment viability across sub-Saharan Africa and Southeast Asian archipelagos despite spectrum availability.
- Launch Cost Concentration:Orbital insertion services concentrate among three dominant providers. This supply bottleneck elevates constellation deployment capital requirements and extends breakeven timelines for new entrants.
- Geostationary Latency Floor:Physics-bound 500-700 millisecond round-trip delays limit real-time application support. Low Earth orbit alternatives address this but require denser satellite counts and higher replenishment rates.
Strategic Opportunities
- Hybrid Service Tiering:Blending geostationary reliability with low Earth orbit latency enables differentiated service level agreements. Telecom operators in Germany and France are piloting these architectures for enterprise backhaul with failover guarantees.
- Rural Base Station Integration:Sub-Saharan African telecom operators face fiber uneconomics across vast territories. Managed satellite backhaul contracts address this white space with outsourced ground infrastructure complexity.
- Silicon Component Substitution:Gallium arsenide displacement by high-throughput silicon in terminal manufacturing reduces unit economics. This technology convergence opens price-competitive positioning in volume rural connectivity markets.
Industry Challenges
- Orbital Debris Compliance Engineering:FCC tightened mitigation standards require active deorbit capabilities and collision avoidance systems. These specifications elevate satellite design complexity and operational compliance overhead.
- ITU Coordination Sequencing:Radio Regulations mandate interference analysis and bilateral negotiations before service initiation. This procedural timeline creates market access delays that favor incumbent constellation operators with established filings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Backhaul Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: C-Band, Ku-Band, Ka-Band, V-Band Service Type: Managed Services, Unmanaged Services, Hybrid Services, Full-Duplex Services End User: Telecom Operators, Internet Service Providers, Government Agencies, Enterprises Application: Rural Connectivity, Disaster Recovery, Emergency Services, Remote Monitoring |
| Companies Covered | Eutelsat Group, Inmarsat, SpaceX, Viasat, AST SpaceMobile, OneWeb, Telesat, Intelsat, SES, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Backhaul Market Strategic Shifts
Terminal hardware economics are restructuring as silicon architectures replace legacy compound semiconductors, while regulatory frameworks for orbital slot coordination tighten and procurement patterns shift toward integrated managed services.
Software-defined radio platforms with integrated beamforming arrays are modularizing ground segment architectures. Rural telecom operators in Brazil and Nigeria are adopting these terminals to reduce installation complexity and enable remote configuration management. This modularization is compressing deployment timelines and lowering technical skill requirements for field maintenance.
FCC debris mitigation rulemaking now mandates active removal capabilities and collision avoidance propulsion for non-geostationary constellations. Satellite manufacturers must redesign bus architectures to incorporate deorbit mechanisms and tracking transparency. Small constellation operators in the United States are responding by extending development schedules and seeking partnership structures to distribute compliance costs.
Managed service contracts are displacing equipment-centric procurement as telecom operators outsource ground infrastructure operations. European operators in France, Germany, and Italy now favor subscription-based models with guaranteed uptime over capital-intensive terminal ownership. This preference shift concentrates vendor relationships toward integrated platform providers with end-to-end service orchestration capabilities.
Satellite Backhaul Market Segmentation
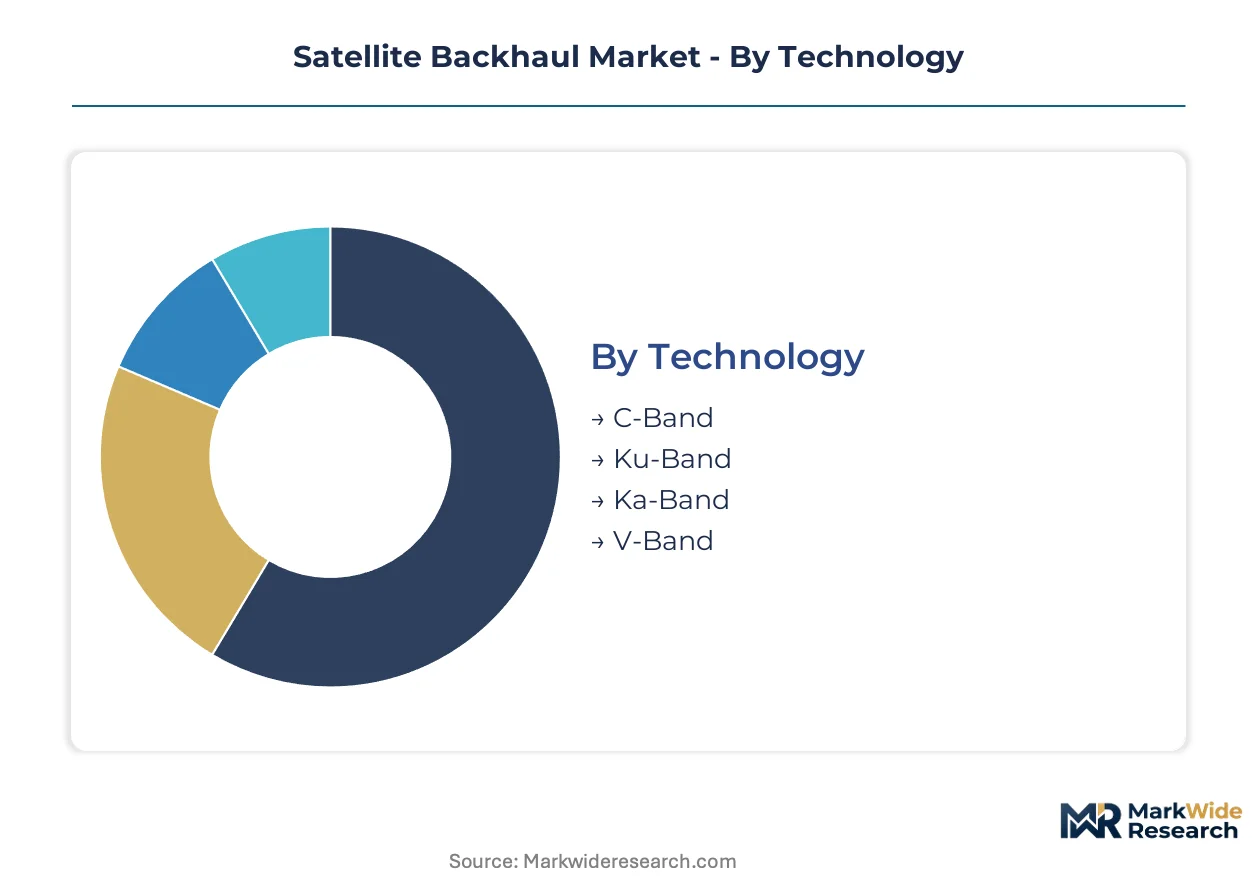
Satellite backhaul procurement patterns diverge sharply across frequency bands, service models, and end-user sophistication levels. Regulatory licensing requirements and terrain-specific propagation characteristics shape which segments command premium pricing versus commodity positioning.
Technology:
C-Band and Ku-Band deployments require FCC Part 25 licensing for U.S. gateway operations, while Ka-Band and V-Band systems face additional ITU coordination burdens for non-geostationary constellations.
- C-Band:Operating at 4–8 GHz with superior rain-fade resistance and established ITU frequency allocations. Demand concentrates in sub-Saharan African rural telecom deployments where tropical precipitation patterns and ANATEL universal service obligations in Brazil drive operator preference for reliability over raw throughput.
- Ku-Band:Spanning 12–18 GHz with balanced spectrum availability and terminal cost economics. European telecom operators in France and Germany favor this band for managed backhaul contracts due to EMA harmonization reducing cross-border authorization friction.
- Ka-Band:High-throughput spectrum at 26.5–40 GHz enabling gigabit-class links. Rain attenuation limits deployment in equatorial climates despite FCC accelerated licensing timelines.
- V-Band:Emerging 40–75 GHz allocations for ultra-high-density constellations. Experimental licensing frameworks in the United States and limited commercial terminal availability constrain near-term adoption.
C-Band sits at the top of the volume ranking, with Ka-Band climbing the fastest among operators prioritizing throughput over atmospheric resilience.
Service Type:
Cost tiering separates capital-intensive equipment ownership from operational expenditure models, with hybrid architectures commanding mid-tier pricing between pure managed and unmanaged extremes.
- Managed Services:End-to-end outsourcing encompassing satellite capacity, ground infrastructure, and network operations. Telecom operators in Italy and Brazil increasingly prefer subscription-based uptime guarantees over terminal ownership, concentrating vendor relationships toward integrated platform providers.
- Hybrid Services:Blending geostationary reliability with low Earth orbit latency for tiered service level agreements. German and French enterprise pilots demonstrate failover architectures that command pricing premiums over single-orbit alternatives.
- Unmanaged Services:Raw capacity procurement leaving ground segment operations to customer technical teams. SpaceX Starlink's aggressive positioning dominates this segment in rural connectivity markets.
- Full-Duplex Services:Symmetric upload-download links for specialized enterprise and government applications. Limited constellation support and higher terminal complexity restrict addressable market scope.
Managed Services dominates current revenue concentration, though Hybrid Services is expanding most quickly as operators seek latency-performance optimization.
End User:
Customer sophistication determines procurement complexity, with government agencies requiring extended certification cycles and enterprises demanding customized service level specifications.
- Telecom Operators:Mobile network providers extending coverage to fiber-uneconomical territories. Sub-Saharan African operators deploy satellite backhaul to satisfy universal service mandates while avoiding terrestrial infrastructure capital intensity.
- Internet Service Providers:Fixed wireless and rural broadband specialists bridging last-mile gaps. Brazilian Amazon basin deployments concentrate demand where ANATEL obligations intersect with terrain inaccessibility.
- Government Agencies:Defense, public safety, and rural development authorities with specialized security and availability requirements. FCC debris mitigation compliance adds procurement evaluation criteria for constellation reliability.
- Enterprises:Mining, energy, and maritime operations requiring private network backhaul. Ka-Band throughput performance supports bandwidth-intensive remote monitoring applications.
Telecom Operators anchor volume leadership, with Internet Service Providers gaining share fastest as rural broadband subsidies expand across emerging markets.
Application:
Deployment urgency and reliability requirements segment pricing power, with emergency response applications tolerating premium costs unavailable to routine connectivity provisioning.
- Rural Connectivity:Permanent network extension to unserved populations. Fiber economics fail across vast sub-Saharan territories and Brazilian Amazon regions, sustaining satellite as the sole viable backhaul medium.
- Disaster Recovery:Rapid-deployable communications following terrestrial infrastructure failure. Ku-Band terminal portability and established spectrum coordination enable faster activation than fiber restoration timelines.
- Emergency Services:First responder and humanitarian communication networks. Government procurement frameworks prioritize availability guarantees over per-megabit pricing.
- Remote Monitoring:Industrial sensor networks and environmental surveillance in inaccessible terrain. Ka-Band capacity supports high-data-rate video and telemetry streams for energy sector deployments.
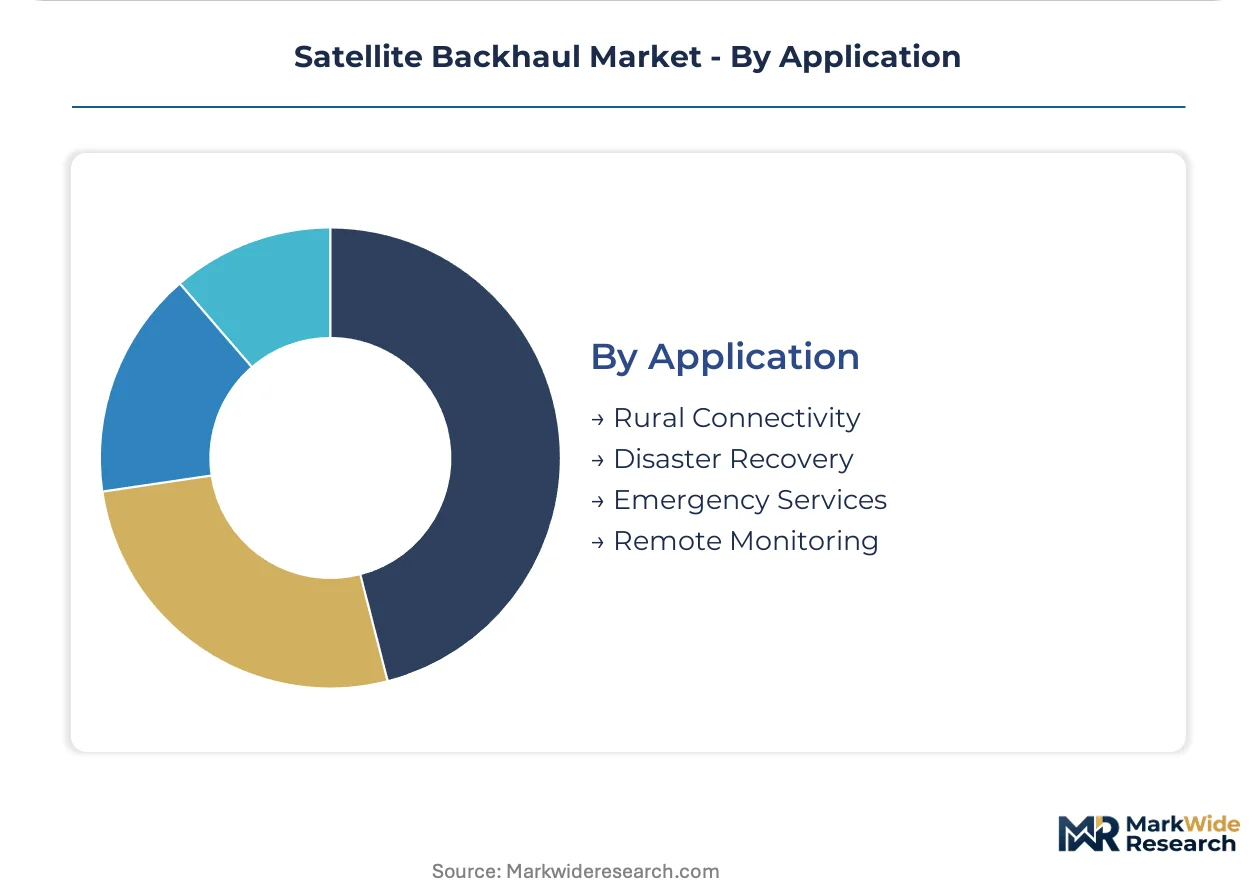
Rural Connectivity holds the volume apex, while Disaster Recovery demonstrates the steepest expansion trajectory as climate-related infrastructure vulnerability intensifies contingency planning investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian Amazon basin deployments anchor regional demand concentration, with ANATEL universal service obligations compelling fiber-uneconomical backhaul extensions across terrain-inaccessible territories.
Brazil
Telecom operators face ANATEL mandates to connect Amazon basin populations unreachable by terrestrial infrastructure. The national telecom regulator accelerates satellite licensing timelines for Ku-Band and Ka-Band allocations. Manaus and Belém industrial clusters concentrate managed service contract negotiations with constellation operators.
United States
FCC orbital debris rulemaking elevates compliance costs for non-geostationary constellation deployments. The regulator's updated spectrum allocation frameworks compress Ku-Band and Ka-Band approval timelines. California and Texas gateway facility clusters host terrestrial infrastructure for low Earth orbit network operators.
Germany
European telecom operators pilot hybrid service architectures blending geostationary reliability with low Earth orbit latency. EMA spectrum harmonization across EU member states reduces cross-border authorization friction. Munich and Frankfurt data center corridors anchor managed backhaul service orchestration platforms.
Nigeria
Rural mobile network expansion drives satellite backhaul procurement as fiber deployment economics fail across vast northern territories. The national communications commission implements universal service fund mechanisms subsidizing connectivity gaps. Lagos and Abuja technology hubs concentrate system integration and field maintenance capabilities.
France
Enterprise backhaul pilots in manufacturing and logistics sectors demonstrate failover architectures with tiered service level agreements. National spectrum management authority coordinates with EMA frameworks for pan-regional service authorization. Toulouse aerospace cluster contributes satellite manufacturing and ground segment engineering expertise.
Satellite Backhaul Market Competitive Environment
Managed service contract consolidation dominates the current landscape as telecom operators outsource ground infrastructure complexity to integrated platform providers. The vendor base separates into three strategic archetypes: geostationary fleet operators anchoring premium service tiers, low Earth orbit constellation builders competing on latency and price positioning, and hybrid network integrators orchestrating multi-orbit architectures. Capacity expansion through constellation densification and strategic partnerships for gateway infrastructure represent the dominant competitive moves reshaping market positioning.
Within the geostationary operator tier, Eutelsat Group and Intelsat occupy positions emphasizing premium managed services and established orbital slot portfolios. Among low Earth orbit constellation builders, SpaceX exemplifies aggressive price positioning through Starlink's density-driven architecture. Viasat sits within the integrated platform provider category, representing end-to-end service orchestration capabilities spanning modem manufacturing and satellite platform control.
| Leading Market Players |
|---|
| Eutelsat Group |
| Inmarsat |
| SpaceX |
| Viasat |
| AST SpaceMobile |
| OneWeb |
| Telesat |
| Intelsat |
| SES |
| Others |
Value Chain & Pricing Dynamics
Telecom operator procurement concentration in managed service contracts shapes pricing architecture across the satellite backhaul value chain, bundling satellite capacity with ground infrastructure operations into subscription-based uptime guarantees rather than equipment ownership models.
Pricing Analysis
Silicon component cost pass-through from terminal manufacturing compresses hardware pricing tiers, while rain-fade susceptibility in Ka-Band systems creates geographic price differentiation between tropical and temperate deployments. Three-tier pricing structure across premium managed services, standard hybrid architectures, and economy unmanaged capacity segments the market. Price erosion runs through the unmanaged tier as SpaceX Starlink's density-driven positioning intensifies competition. Internet service providers in Brazil and Nigeria exhibit highest price sensitivity due to universal service fund constraints, while European telecom operators in Germany and France prioritize reliability guarantees over per-megabit economics.
Supply Chain Analysis
Maritime freight and air cargo logistics for satellite bus components and ground terminal assemblies elevate landed costs for constellation operators deploying gateway infrastructure across multiple continental markets. Manufacturing concentration rests on the United States for high-throughput silicon chipsets, France and Germany for satellite bus engineering and ground segment systems, and China for solar panel and battery subsystem production. Gallium arsenide wafer supply and phased array antenna substrates represent critical input dependencies. Single-source vulnerability in launch services concentrates orbital insertion among three dominant providers. Distribution runs through direct managed service contracts with telecom operators and indirect channel partnerships with systems integrators in Lagos, Abuja, and São Paulo technology hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Satellite backhaul functions as a stable compounder anchored by universal service obligations that mandate connectivity extensions into terrain-inaccessible territories regardless of macroeconomic cycles.
For Market Incumbents: Acquire orbital slot portfolios and gateway facility clusters to consolidate spectrum access advantages against emerging low Earth orbit constellation entrants. Eutelsat Group and Intelsat should deepen backward integration into silicon terminal manufacturing to capture cost compression from gallium arsenide displacement. FCC debris mitigation compliance investments create certification barriers that favor established operators with capital reserves for active deorbit capability integration. For New Entrants and Emerging Players: Cloud-based network management platforms enable service orchestration without legacy ground infrastructure overhead, opening white-space entry points. Target sub-Saharan African rural connectivity markets where fiber economics fail and universal service subsidies sustain contract viability. Brazilian Amazon basin deployments offer the most penetrable geography given ANATEL mandate enforcement and existing managed service procurement patterns. Partner with regional systems integrators in Nigeria and Brazil to bypass direct telecom operator sales cycle complexity. For Investors and Strategic Acquirers: Defense contractors and national telecom infrastructure funds are the most active acquirer in this space, seeking dual-use satellite capacity for secure communications backhaul. Long-term viability hinges on hybrid service tiering capabilities that blend geostationary reliability with low Earth orbit latency. Acquisition targets should demonstrate integrated platform control spanning modem manufacturing and satellite operations. Monitor ITU coordination filing timelines as the critical inflection signal for constellation deployment sequencing and market access priority.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Service Architecture Deployment | Blending geostationary reliability with Starlink latency enables tiered SLA premiums in German enterprise pilots. |
| Ku-Band Gateway Infrastructure Expansion | Brazilian Amazon basin facility buildout satisfies ANATEL universal service obligations with accelerated FCC licensing timelines. |
| Silicon Terminal Manufacturing Integration | Backward integration into high-throughput chipsets captures gallium arsenide displacement cost compression for rural volume markets. |
| Managed Service Contract Consolidation | Subscription-based uptime guarantees displace equipment ownership among Italian and Brazilian telecom operators. |
| Orbital Debris Compliance Engineering | Active deorbit capability integration addresses FCC tightened mitigation standards for non-geostationary constellation authorization. |
Study Parameters
Bottom-up telecom operator deployment modeling reconciled against top-down constellation capacity tracking forms the analytical core of this study. Primary interviews with satellite fleet operations executives, ground segment engineering directors, telecom procurement managers, and regulatory affairs specialists at ANATEL and FCC inform demand-side validation. Secondary sources include ITU Radio Regulations filings, FCC Part 25 licensing databases, EMA spectrum harmonization directives, and constellation operator technical specifications. Cross-referencing bottom-up contract values with top-down satellite throughput metrics ensures segmentation integrity.
Input-output matrices map terminal hardware unit economics against managed service revenue pools across frequency band and service type dimensions. Segmentation modeling incorporates technology tier, service model, end-user sophistication, and application urgency as structural dimensions. CAGRs derive from deployment timeline phasing and contract value aggregation. Forecast inputs include ANATEL universal service obligation enforcement schedules and FCC orbital debris rulemaking implementation trajectories.
Launch cost volatility, ITU coordination delays, and tropical precipitation pattern intensity are the dominant revision risks to capacity deployment assumptions. Forecasts reflect modeled scenarios rather than deterministic predictions. Stakeholders should weight assumptions against their own operating context and regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Global Maritime Satellite Communication Market
Satellite
South Korea Satellite Connectivity Market
Satellite
Fixed Satellite Services (FSS) Market
Satellite
Global Satellite Propulsion System Market
Satellite
Germany Satellite Communications Market
Satellite
Asia-Pacific Military Satellite Market
Satellite
North America Satellite IoT Market
Satellite
Cubesat Market
Satellite
North America Remote Sensing Satellites Market
Satellite
Satellite Manufacturing Market
Satellite
UK Satellite Imagery Services Market
Satellite
Medium and Large Satellite Market
Satellite
Israel Satellite Communications Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
Canada Satellite-Based Earth Observation Market
Satellite
High-Throughput Satellite Market