
 Military Satellite Market | 2026-2036
Military Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
Military Satellite Market Outlook
Multi-source satellite procurement is rebalancing toward hybrid public-private partnerships as defense agencies seek cost resilience. Lockheed Martin anchors geostationary military communications with long-running production lines for protected wideband payloads. SpaceX competes aggressively on launch economics, leveraging reusable Falcon Heavy vehicles to undercut expendable alternatives for heavy national security missions. Boeing sustains its position through classified manufacturing integration with Space Force ground infrastructure.
A military satellite comprises a purpose-built spacecraft carrying hardened communications relays, sensor payloads, or navigation beacons, typically operating in geostationary or low-earth orbits with design lifespans exceeding ten years and radiation-hardened electronics rated for total ionizing dose thresholds above 100 krad. These systems enable beyond-line-of-sight command links, precision targeting, and missile warning for joint force operations. Communication applications dominate current procurement volumes, while signals intelligence payloads capture expanding budget share as electronic warfare threats intensify across contested theaters. Low Earth Orbit deployments represent the fastest-expanding segment, driven by proliferated architectures that complicate adversary targeting and reduce single-point failure risk.
The U.S. Space Force and NRO set technical standards for encryption, anti-jamming, and nuclear hardening that determine vendor qualification. FCC spectrum allocations and ITU orbital slot coordination constrain fleet deployment timelines and geographic coverage options. NATO allies face divergent compliance burdens as EU space traffic management rules emerge alongside national security classifications. Stakeholders must weigh proprietary payload development against modular open-architecture standards that enable faster technology refresh without full satellite replacement.
Market Dynamics
The proliferation of low-earth-orbit architectures is fragmenting legacy geostationary dominance as defense agencies prioritize resilience over single-satellite redundancy. This orbital shift demands new manufacturing rhythms, launch cadences, and ground segment integration that incumbent suppliers must absorb or cede position.
Growth Catalysts
- Electronic Warfare Threat Intensification:Contested theaters in Eastern Europe and the Indo-Pacific drive demand for signals intelligence payloads with advanced anti-jamming capabilities.
- Protected Wideband Mandates:NATO member states accelerate procurement of nuclear-hardened communications satellites under collective defense modernization frameworks.
- Hybrid Public-Private Partnerships:Cost resilience objectives push defense ministries toward shared infrastructure models that blend sovereign payloads with commercial bus platforms.
Market Restraints
- Radiation-Hardened Component Scarcity:Total ionizing dose thresholds above 100 krad constrain qualified semiconductor supply to a handful of specialized foundries.
- ITU Orbital Slot Coordination:Geographic coverage timelines stretch 18-36 months as national regulators queue for contested spectrum allocations.
- Launch Capacity Bottlenecks:Heavy national security missions face scheduling compression as expendable vehicle production lines contract against reusable alternatives.
Strategic Opportunities
- Modular Open-Architecture Standards:Faster technology refresh cycles emerge as payload-agnostic bus designs separate spacecraft infrastructure from mission electronics.
- Proliferated LEO Constellation Services:Tactical users in maritime and Arctic domains gain persistent coverage through distributed small-satellite networks.
- EU Space Traffic Management Rules:Emerging collision-avoidance mandates create compliance service markets for constellation operators navigating dual-use classifications.
Industry Challenges
- Radiation Effects Engineering Talent:Specialized workforce gaps in single-event upset mitigation and hardened electronics design extend development timelines.
- Legacy Ground Infrastructure Integration:New orbital assets must interoperate with decades-old command-and-control systems that resist rapid software-defined upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Satellite Market |
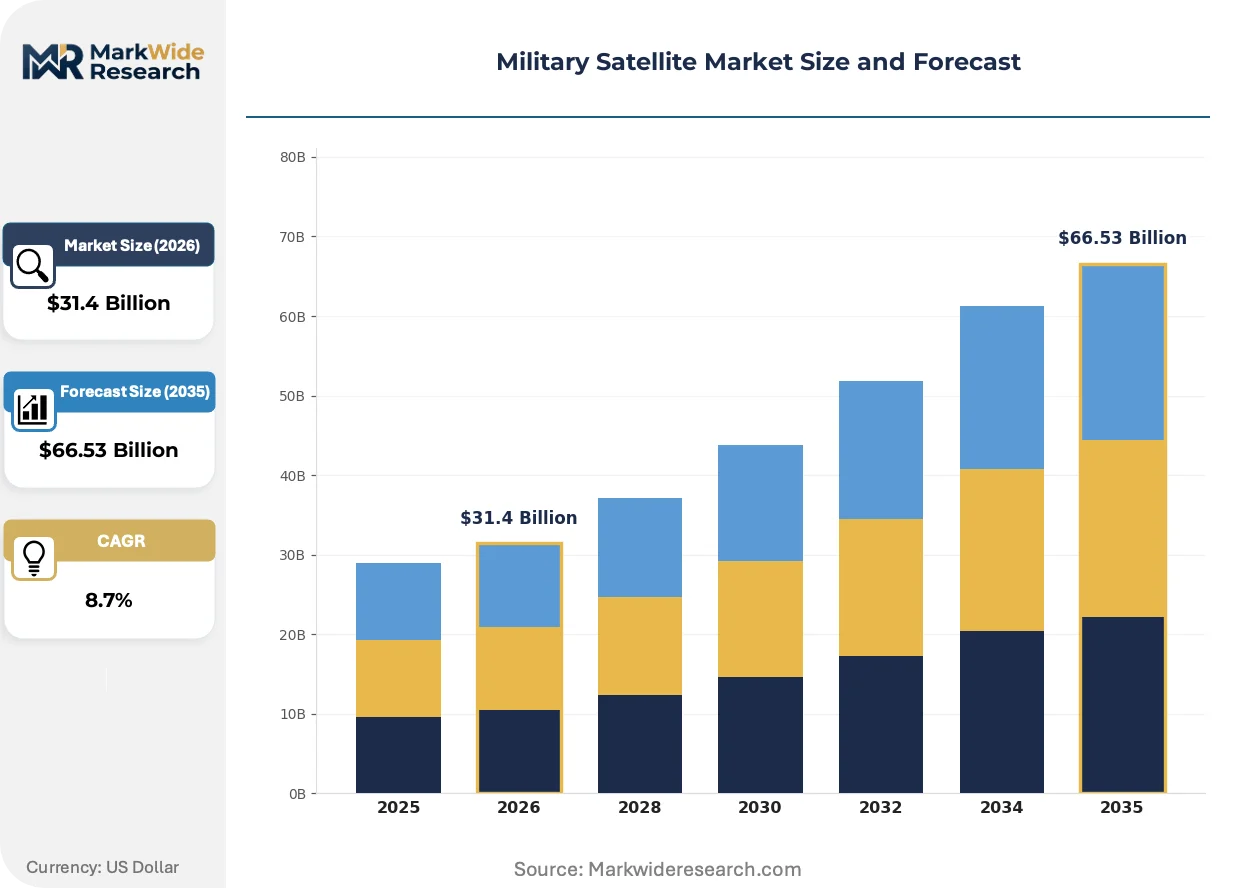
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $66.53 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Communication, Surveillance, Reconnaissance, Navigation Payload Type: Electro-Optical, Radar, Signals Intelligence, Electronic Warfare Launch Vehicle: Expendable, Reusable, Small Satellite Launch Vehicle, Heavy-Lift Orbit Type: Geostationary, Low Earth Orbit, Medium Earth Orbit, Polar Orbit |
| Companies Covered | Lockheed Martin, Northrop Grumman, Airbus, Boeing, Thales, SpaceX, L3Harris Technologies, Raytheon Technologies, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Satellite Market Strategic Shifts
Software-defined payload architectures are compressing hardware refresh cycles while quantum-resistant encryption standards force premature obsolescence into planned satellite lifespans. These shifts reward suppliers with modular manufacturing competencies over those anchored to static platform designs.
Optical inter-satellite links are consolidating laser-based cross-connectivity as the backbone of proliferated architectures. Space Force and NRO programs now mandate optical terminals for beyond-line-of-sight relay without ground station exposure. This technology is consolidating vendor tiers as only specialized photonics houses qualify for mission-critical deployment.
FCC spectrum reallocation proceedings are compressing protected military bands as commercial 5G and satellite broadband interests press for shared access. The industrial consequence forces military operators into more agile frequency-hopping and cognitive radio investments. Payload manufacturers serving U.S. end-uses face the steepest redesign imperatives under these coexistence mandates.
Multi-orbit service contracts are displacing single-architecture procurement as defense buyers seek seamless handoffs between geostationary assets and proliferated low-earth constellations. Systems integrators capturing these bundled awards are compressing pure-play operators into subsystem supplier roles. This pattern concentrates most visibly in U.S. Space Force resilient communications programs where orbital diversity is now a scored evaluation criterion.
Military Satellite Market Segmentation
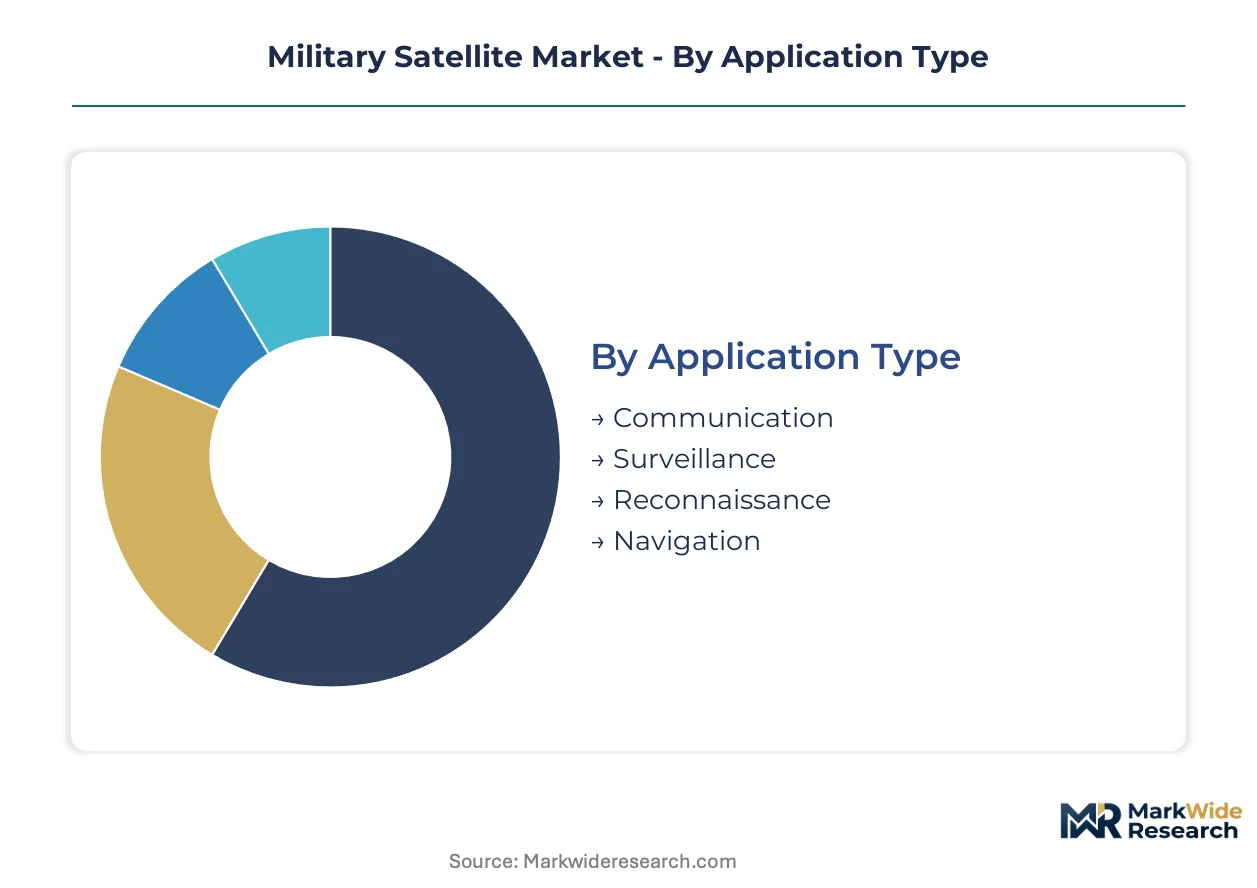
Segmentation in military satellite procurement reveals how defense buyers balance capability requirements against orbital economics and threat resilience. Each dimension carries distinct vendor qualification barriers and determines long-term fleet architecture decisions across NATO and allied programs.
Application Type:
Supply concentration for mission-ready payloads tilts heavily toward communication and surveillance platforms, with reconnaissance and navigation following distinct procurement rhythms.
- Communication:Hardened wideband relays operating in protected frequency bands dominate current procurement volumes. U.S. Space Force modernization programs drive sustained investment in nuclear-hardened architectures for beyond-line-of-sight command links.
- Surveillance:Persistent orbital monitoring systems integrate electro-optical and synthetic aperture radar sensors for missile warning and battlespace awareness. Indo-Pacific theater requirements accelerate demand for Arctic-capable coverage patterns.
- Reconnaissance:High-resolution imaging platforms serve national intelligence priorities with revisit rates measured in hours rather than days.
- Navigation:Precision timing and positioning beacons augment GPS constellations with military-specific signal authentication and anti-spoofing protections.
Today's leader: Communication. Tomorrow's challenger: Surveillance.
Payload Type:
Cost tier stratification separates radiation-hardened signals intelligence platforms from commodity electro-optical alternatives, with electronic warfare payloads commanding premium development timelines.
- Signals Intelligence:Advanced intercept and geolocation systems detect, characterize, and locate adversary emissions across contested electromagnetic spectrum. Eastern European theater operations intensify procurement urgency for anti-jam-capable designs.
- Electronic Warfare:Active countermeasure payloads execute denial and deception missions against adversary radar and communications networks. FCC spectrum reallocation proceedings compress protected military bands and force agile frequency-hopping investments.
- Electro-Optical:Visible and infrared imaging sensors provide high-resolution terrain and target identification.
- Radar:All-weather synthetic aperture systems penetrate cloud cover and darkness for persistent surface surveillance.
Signals Intelligence commands the steepest expansion trajectory as electronic warfare threats intensify across contested theaters.
Launch Vehicle:
Volume concentration is shifting from expendable heritage systems toward reusable alternatives, with small satellite and heavy-lift categories serving proliferated constellation and flagship payload missions respectively.
- Reusable:Falcon Heavy-class vehicles undercut expendable alternatives on per-kilogram economics for national security missions. Launch capacity bottlenecks persist as production lines for expendable vehicles contract against reusable cadences.
- Heavy-Lift:Dedicated large-payload vehicles deliver geostationary communications satellites exceeding ten-ton masses to high-energy orbits. U.S. Space Force and NRO set technical standards that determine vendor qualification for these missions.
- Expendable:Heritage launch systems retain role for specialized orbital insertions and nuclear-hardened payload requirements.
- Small Satellite Launch Vehicle:Rapid-response launchers deploy tactical replenishment assets for proliferated low-earth architectures.
Reusable vehicles anchor current procurement economics. Small satellite launchers represent the most rapidly scaling category.
Orbit Type:
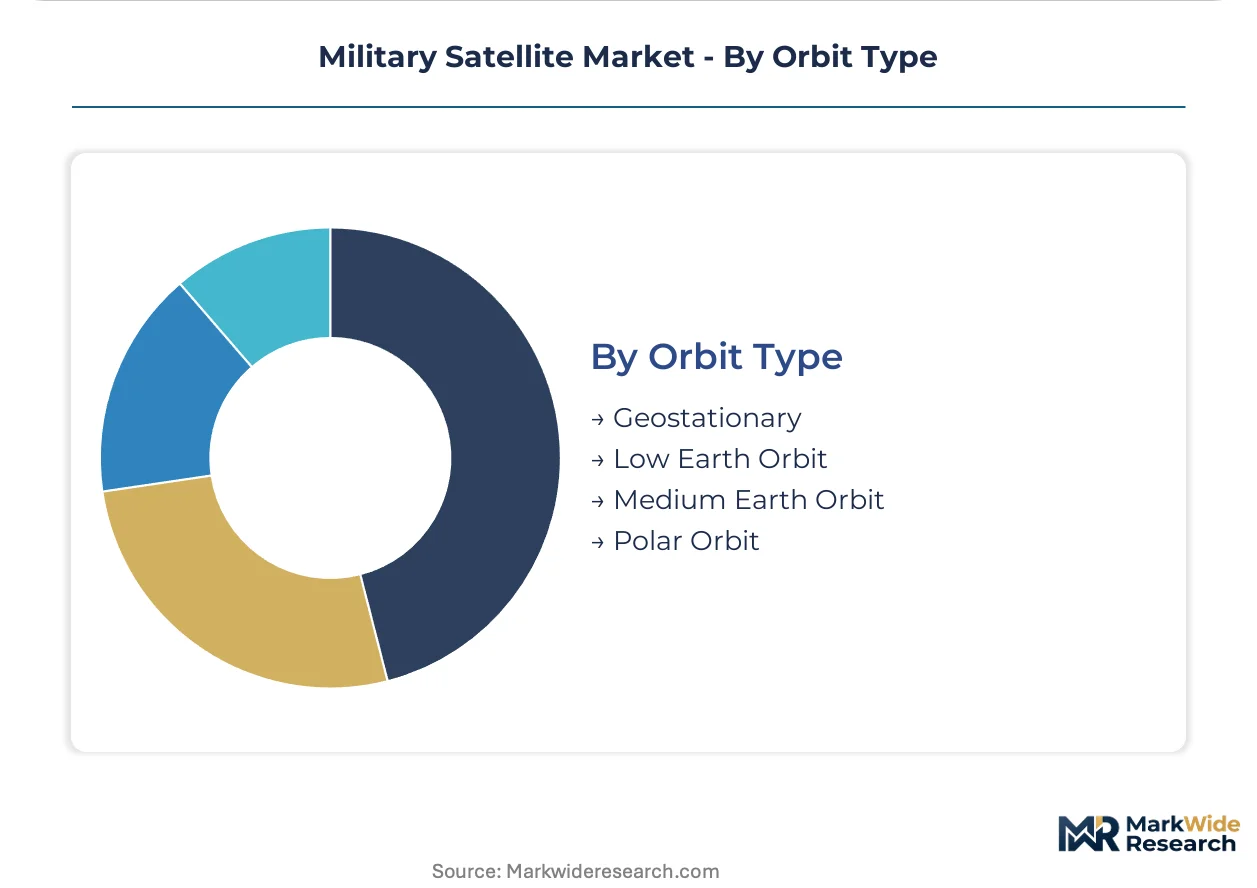
Maturity gradients separate legacy geostationary dominance from emerging proliferated architectures, with polar and medium earth orbits serving specialized coverage and navigation missions.
- Low Earth Orbit:Distributed small-satellite constellations complicate adversary targeting and reduce single-point failure risk through proliferated architectures. NATO allies accelerate procurement under collective defense modernization frameworks.
- Geostationary:Fixed-position relays above the equator provide persistent regional coverage for wideband communications and missile warning. ITU orbital slot coordination stretches deployment timelines 18-36 months for contested spectrum allocations.
- Medium Earth Orbit:Intermediate-altitude deployments host specialized navigation augmentation and communications relay missions.
- Polar Orbit:High-inclination paths enable complete earth coverage for reconnaissance and environmental monitoring applications.
Geostationary assets retain revenue concentration. Low Earth Orbit deployments are climbing the fastest as resilience priorities reshape fleet architecture requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Colorado aerospace corridor anchors military satellite production concentration, with Denver-Aurora-Boulder hosting prime contractor integration facilities and Space Force command infrastructure that shapes procurement rhythms across allied defense programs.
United States
Space Force modernization programs drive sustained investment in resilient space infrastructure, with protected wideband mandates accelerating nuclear-hardened communications procurement. FCC spectrum allocations and ITU orbital slot coordination constrain fleet deployment timelines for contested coverage requirements. The Los Angeles-San Diego axis concentrates payload manufacturing alongside Vandenberg Space Force Base launch operations.
France
Direction générale de l'armement programs sustain sovereign communications satellite production for independent nuclear deterrence command links. ANSM and national security classifications govern dual-use technology transfers within EU space traffic management frameworks. Toulouse hosts Airbus Defence and Space integration facilities serving both domestic and NATO allied requirements.
United Kingdom
UK Space Agency and Ministry of Defence joint procurement prioritizes signals intelligence payloads for contested electromagnetic spectrum operations. National security classifications align with Five Eyes intelligence sharing protocols for orbital sensor data exchange. Stevenage and Portsmouth clusters concentrate satellite bus manufacturing and ground segment engineering.
Germany
Bundeswehr space domain awareness investments expand under NATO collective defense modernization commitments. BAFA export controls and EU space traffic management rules create compliance burdens for dual-use constellation operators. Munich-Ottobrunn hosts sensor payload development alongside OHB SE manufacturing integration.
Japan
Ministry of Defense space domain mission units accelerate procurement of optical inter-satellite link terminals for beyond-line-of-sight relay. METI industrial policy coordinates domestic satellite bus production with U.S. alliance technology sharing agreements. Tanegashima Space Center launch capacity supports rapid replenishment for proliferated low-earth architectures.
Military Satellite Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue proliferated constellation services and commercial bus platform integration. Prime contractors anchor geostationary protected communications with decade-long production heritage, while new entrants compete on launch economics and rapid deployment cadences. Two strategic archetypes dominate: heritage system integrators with classified manufacturing clearance and commercial space operators leveraging reusable vehicle cost structures. Competitive moves concentrate on hybrid public-private partnership formation and modular open-architecture standard adoption.
Among U.S.-based defense primes, Lockheed Martin and Northrop Grumman exemplify the heritage integrator archetype through sustained protected payload production lines. Boeing occupies a position spanning both classified satellite integration and ground infrastructure manufacturing. SpaceX represents the commercial cost-disruption archetype, leveraging reusable Falcon Heavy economics to compress national security launch pricing. These three anchors illustrate the competitive tension between sovereign capability preservation and commercial efficiency adoption.
| Leading Market Players |
|---|
| Lockheed Martin |
| Northrop Grumman |
| Airbus |
| Boeing |
| Thales |
| SpaceX |
| L3Harris Technologies |
| Raytheon Technologies |
| BAE Systems |
| Others |
Value Chain & Pricing Dynamics
Radiation-hardened semiconductor foundry capacity indexes cascade through military satellite procurement tiers, compressing margins on nuclear-hardened payloads while inflating premiums for single-source qualified components. Cost pass-through mechanics separate heritage integrators with captive supply arrangements from entrants exposed to spot-market component volatility.
Pricing Analysis
Input-cost pass-through dominates contract structures, with radiation-hardened electronics and launch services feeding directly into fixed-price escalation clauses. Pricing stratifies across mission-critical payloads, qualified commercial buses, and rapid-replenishment small satellites, with certification grade and anti-jam capability as primary differentiation drivers. Pricing pressure stems from reusable launch vehicle economics undercutting heritage expendable alternatives. Defense primes with Space Force qualification show lowest price sensitivity; commercial bus integrators face acute margin compression.
Supply Chain Analysis
Single-source vulnerability sits with U.S.-based radiation-hardened foundries and specialized photonics houses qualifying for optical inter-satellite link terminals. Supply concentration centers on the United States for protected payload electronics, France for sovereign communications platforms, and Japan for precision sensor components. Critical dependencies include gallium nitride semiconductors, laser terminal assemblies, and nuclear-hardened composite structures. Tariff exposure on rare earth processing creates structural risk for magnet and thermal control subsystems. Distribution runs through prime contractor integration facilities with direct Space Force and NATO defense ministry contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Military satellite procurement functions as a geographic-arbitrage play, with EU space traffic management compliance costs in France and Germany running substantially above U.S. Federal Acquisition Regulation streamlined pathways for equivalent capability tiers.
For Market Incumbents: Anticipate proliferated LEO constellation mandates fragmenting geostationary revenue concentration by accelerating modular open-architecture investments that separate payload from bus refresh cycles. Lockheed Martin and Northrop Grumman must absorb software-defined payload competencies or cede ground to commercial bus integrators. Vertical integration into radiation-hardened component supply insulates against foundry bottlenecks. For New Entrants and Emerging Players: EU Space Traffic Management rules in France and Germany open a window for compliance-as-a-service offerings targeting dual-use constellation operators navigating collision-avoidance mandates. White-space targets include tactical maritime coverage gaps in the Indo-Pacific and Arctic relay networks. Penetrable entry points sit with rapid-replenishment small satellite launch services. Go-to-market positioning emphasizes hybrid public-private partnership formation with defense ministries seeking cost resilience. For Investors and Strategic Acquirers: Consolidation pressure builds where software-defined payload capabilities fragment across specialized photonics houses and legacy hardware integrators. Long-term viability favors suppliers with modular manufacturing competencies and classified manufacturing clearance. Acquisition targets include optical terminal specialists and radiation-hardened electronics designers. Watch proliferated architecture procurement scoring criteria as the inflection signal—orbital diversity mandates accelerate capability consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Open-Architecture Adoption | Payload-agnostic bus designs enable faster technology refresh without full satellite replacement under Space Force standards. |
| Optical Inter-Satellite Link Integration | Laser-based cross-connectivity consolidates vendor tiers as only specialized photonics houses qualify for NRO-mandated deployment. |
| Hybrid Public-Private Partnership Formation | Shared infrastructure models blend sovereign payloads with commercial buses to meet NATO cost resilience objectives. |
| Radiation-Hardened Supply Backward Integration | In-house production of qualified semiconductors insulates against single-source foundry bottlenecks exceeding 100 krad thresholds. |
| Multi-Orbit Service Contract Capture | Seamless handoffs between geostationary assets and LEO constellations score highest in Space Force resilient communications evaluation. |
Study Parameters
Bottom-up defense ministry procurement tracking reconciled against top-down prime contractor production monitoring forms the analytical core of this study. Primary interviews with Space Force program executives, satellite bus engineering directors, signals intelligence payload specialists, and NATO defense procurement officers combined with secondary validation from FCC spectrum allocation records, ITU orbital slot registration databases, SEC contractor filings, and congressional defense authorization documents. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of protected wideband communications procurement and proliferated LEO constellation deployment patterns informed projection frameworks across the analysis window. Segmentation modeling incorporated orbit type, payload classification, launch vehicle category, and application mission. CAGR derivation rested on defense budget authorization trajectories, threat environment escalation indices, and technology refresh cycle compression rates specific to software-defined architectures and quantum-resistant encryption mandates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ITU coordination delays, radiation-hardened component supply disruptions, and reusable launch vehicle reliability incidents. Forecasts reflect documented assumptions regarding Space Force modernization pacing and NATO collective defense commitment levels. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Japan Satellite-Based Earth Observation Market
Satellite
Latin America Satellite Connectivity Market
Satellite
Broadband Satellite System Market
Satellite
North America Satellite Manufacturing Market
Satellite
Israel Satellite Communications Market
Satellite
Spain Satellite Imagery Services Market
Satellite
Satellite Communication Subsystem Market
Satellite
Satellite Communications Service Market
Satellite
Satellite Services Market
Satellite
Russia Satellite Imagery Services Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
Germany Satellite Communications Market
Satellite
China Satellite Connectivity Market
Satellite
UK Satellite Connectivity Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
Asia-Pacific Military Satellite Market