
 Europe Satellite Attitude and Orbit Control System Market | 2026-2036
Europe Satellite Attitude and Orbit Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Satellite Attitude and Orbit Control System Market Insights
German aerospace manufacturing is realigning around sovereign constellation build-outs and institutional satellite programs. AAC Clyde Space leverages its Scottish-German footprint to dominate CubeSat AOCS supply across European NewSpace ventures. Jena-Optronik sustains optical sensor integration leadership that anchors precision pointing for Earth observation platforms. Thales competes through end-to-end mission capability extending from payload design to flight-proven control algorithms.
A Satellite Attitude and Orbit Control System comprises reaction wheels, thrusters, control moment gyroscopes, and magnetorquers that generate torque and translational force to stabilize spacecraft orientation and maintain orbital position against perturbation forces, typically operating with pointing accuracy measured in arc-seconds and fuel budgets spanning multi-year mission lifetimes. Reaction wheels and thrusters occupy the core hardware spend pool where European suppliers retain manufacturing depth against Asian price competition. Digital control and autonomous systems segments are expanding fastest as operators push for reduced ground-segment dependency and faster fault recovery loops.
EMA and ESA technical standards shape product qualification requirements while REACH compliance constrains material selection for propulsion subsystems and electronic components. The EU Green Deal's space sustainability provisions are forcing design trade-offs between mission lifetime extension and post-mission disposal reliability. Stakeholders must monitor how CSRD disclosure mandates affect supply chain transparency for AOCS component sourcing.
Market Dynamics
EU Green Deal space sustainability provisions are forcing satellite manufacturers to redesign AOCS architectures around post-mission disposal reliability and debris mitigation compliance, tightening qualification requirements across European supply chains.
Growth Catalysts
- Constellation Deployment Wave:Commercial operators across France, Germany, and Italy are scaling procurement of reaction wheels and control moment gyroscopes for medium and large satellite fleets.
- REACH Material Mandates:ECHA restrictions on hazardous substances in propulsion subsystems are accelerating adoption of green propellant-compatible thruster designs.
- Autonomous Control Algorithms:Operators demand reduced ground-segment dependency, expanding the addressable market for flight-proven digital AOCS with self-correcting fault loops.
Market Restraints
- Rare Earth Magnet Supply:European dependence on Chinese-processed neodymium and dysprosium for magnetorquer cores creates input cost volatility and strategic vulnerability.
- Optical Sensor Fab Capacity:Precision star tracker manufacturing concentrates in a narrow German-Austrian supplier corridor, limiting production elasticity for Earth observation platforms.
- CSRD Disclosure Burden:New corporate sustainability reporting mandates impose compliance overhead on mid-tier component suppliers without proportional revenue scale.
Strategic Opportunities
- Polish Manufacturing Expansion:Warsaw and Krakow aerospace clusters offer untapped precision machining capacity for reaction wheel housings and gyroscope frames at competitive cost structures.
- AI-Enabled Predictive Maintenance:Machine learning integration with AOCS telemetry streams enables subscription-based health monitoring services for constellation operators.
- Norwegian Spaceport Proximity:Andøya launch site development creates geographic pull for AOCS integration and test facilities serving polar orbit missions.
Industry Challenges
- Embedded Software Certification:ESA ECSS software standards impose multi-year qualification timelines for autonomous control algorithms, compressing product refresh cycles.
- Cross-Border Talent Mobility:Schengen visa friction and national security clearance fragmentation restrict movement of control systems engineers between French, German, and Italian prime contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Satellite Attitude and Orbit Control System Market |
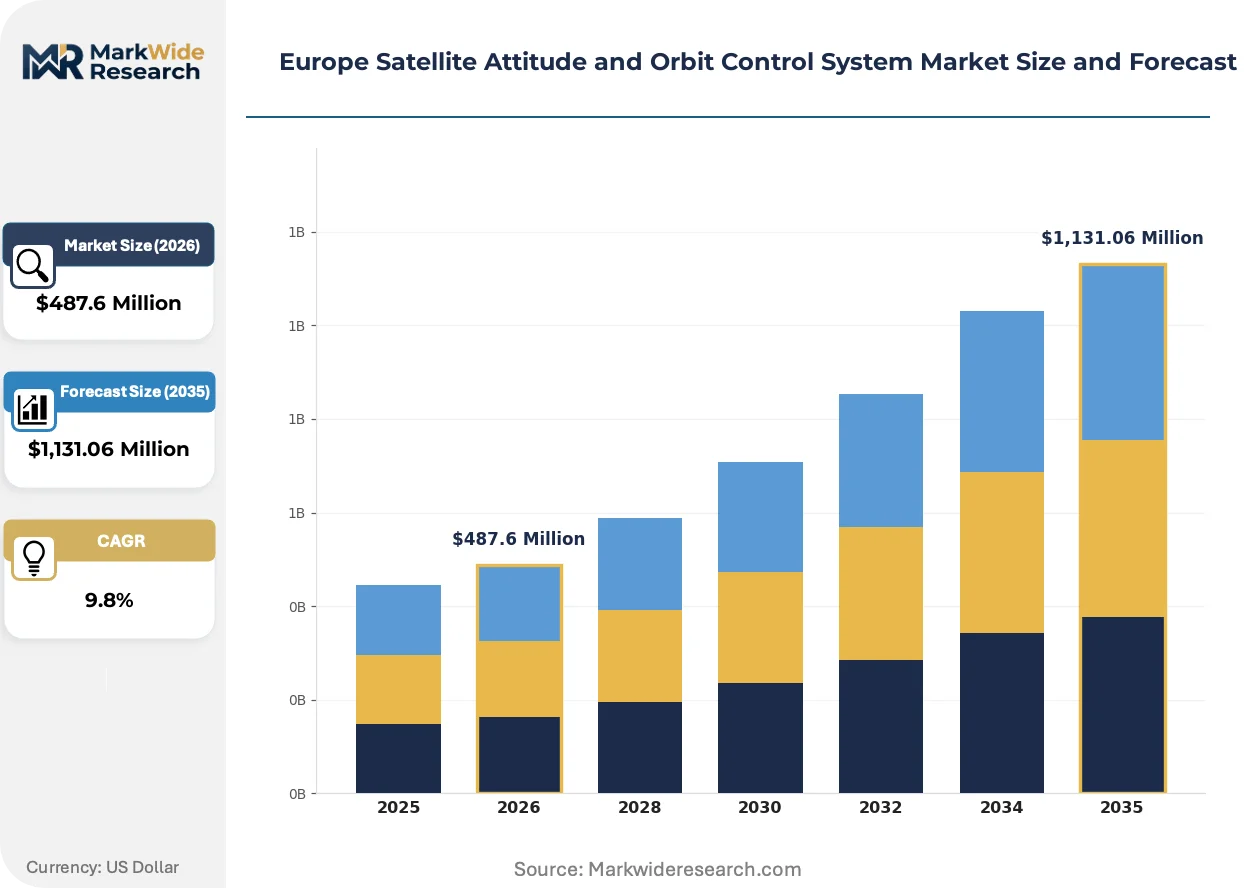
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,131.06 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reaction Wheels, Thrusters, Control Moment Gyroscopes, Magnetorquers Application: Earth Observation, Communication, Scientific Research, Navigation End User: Government Agencies, Commercial Operators, Aerospace Manufacturers, Research Institutions Technology: Analog Control, Digital Control, Software-Based Control, Autonomous Systems |
| Companies Covered | AAC Clyde Space, Jena-Optronik, OHB SE, Sitael S.p.A., Innovative Solutions in Space BV, SENER Group, Bradford Engineering BV, NewSpace Systems, Thales, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Satellite Attitude and Orbit Control System Market Trends and Innovations
Digital control architectures are displacing analog heritage designs across European satellite programs, while sustainability mandates and procurement consolidation reshape supplier relationships and technical roadmaps.
Software-defined AOCS is modularizing mission-specific control functions into containerized software blocks that operators reconfigure without hardware swaps. Smallsat and CubeSat builders in Scotland and Germany adopt this approach fastest, cutting integration timelines from months to weeks. The shift is compressing traditional hardware-software bundling strategies among incumbent suppliers.
EU Green Deal space sustainability guidelines are mandating design-for-demise features and active debris removal compatibility in new satellite procurements. ESA institutional programs now require AOCS architectures with guaranteed deorbit reliability, forcing thruster manufacturers to validate redundant firing sequences. Earth observation platforms with extended mission lifetimes face the tightest compliance deadlines.
Consolidated procurement by mega-constellation operators is unbundling legacy AOCS service packages. End-to-end mission capability contracts fragment into component-only supply with separate software licensing, favoring specialized hardware vendors over integrated system houses. French and German prime contractors feel this pressure most acutely on institutional anchor programs.
Europe Satellite Attitude and Orbit Control System Market Segmentation
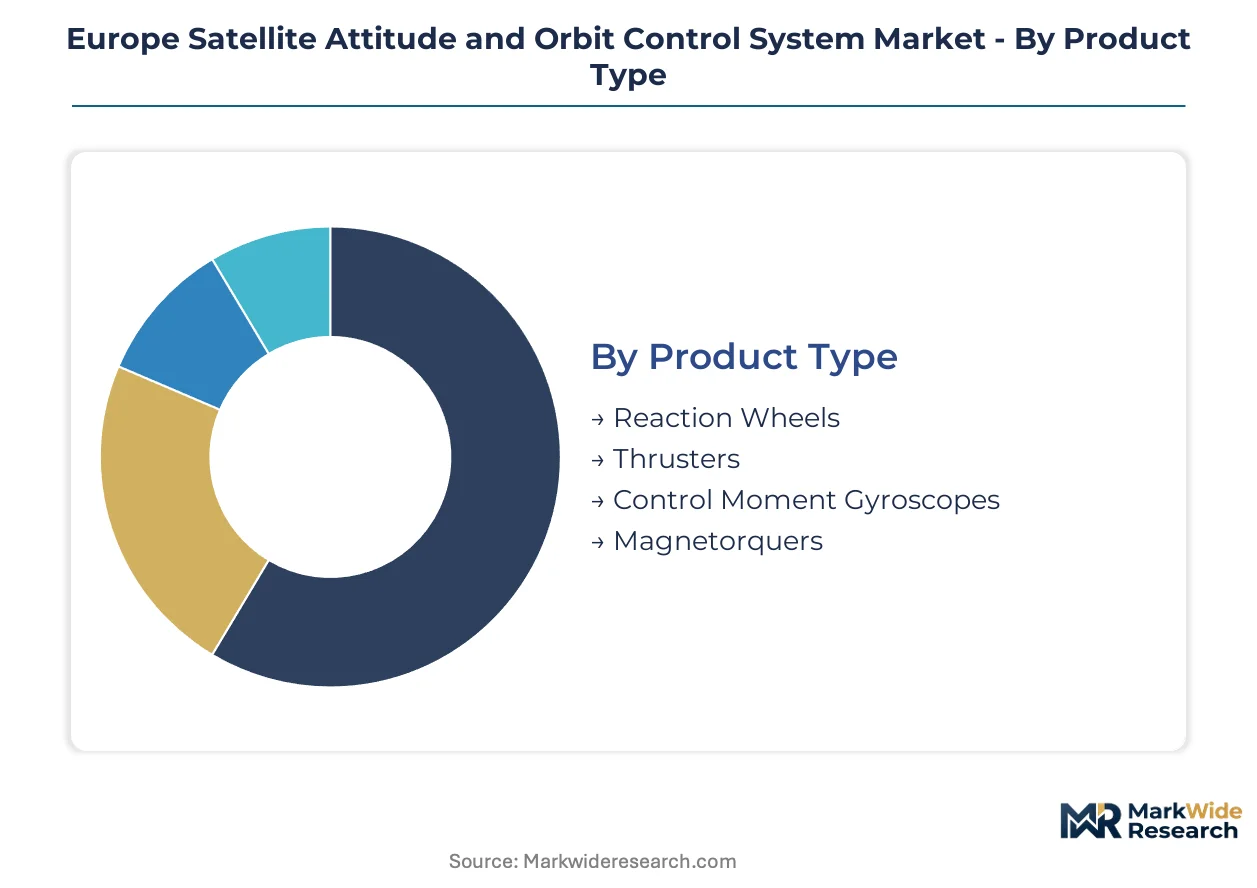
AOCS procurement patterns diverge sharply across product architectures and operator types, with ESA institutional programs imposing distinct qualification burdens that reshape supplier economics for each segment tier.
Product Type:
Reaction wheels and thrusters carry the heaviest ECSS certification overhead, while magnetorquers face REACH material constraints on rare-earth sourcing that complicate ECHA compliance pathways.
- Reaction Wheels:Momentum storage devices built from titanium or aluminum housings with ceramic bearing assemblies achieve pointing stability measured in arc-seconds. French and German Earth observation primes dominate procurement for institutional programs, though lead times stretch to 18 months under ESA qualification protocols.
- Thrusters:Chemical and electric propulsion units generating translational force for station-keeping and deorbit maneuvers. Italian propulsion specialists capture share in green propellant variants as ECHA restrictions on hydrazine accelerate chemistry transitions.
- Control Moment Gyroscopes:High-torque momentum exchange devices for large platforms.
- Magnetorquers:Electromagnetic torque rods using neodymium-dysprosium cores.
Reaction wheels sit at the top of the volume ranking, with thrusters climbing the fastest on constellation deployment schedules.
Application:
Margin structures compress toward commodity levels in navigation and communication, while Earth observation retains pricing power through precision pointing requirements.
- Earth Observation:Synthetic aperture radar and optical payloads demand sub-arcsecond pointing accuracy with rapid slew rates. German and French institutional programs anchor procurement, though commercial weather operators in Italy expand demand for agile revisit capabilities.
- Communication:Geostationary and LEO broadband constellations prioritize fuel efficiency over precision. Commercial operators unbundle AOCS packages, pressuring incumbent suppliers on mega-constellation tenders.
- Scientific Research:Deep-space and astronomy missions with extended operational horizons.
- Navigation:GNSS augmentation and timing payloads with standardized pointing requirements.
Earth observation commands the steepest expansion trajectory, with navigation gaining share fastest on Galileo refresh programs.
End User:
Procurement authority concentrates in government channels, though commercial operators reshape technical specifications through consolidated constellation tenders.
- Government Agencies:ESA, national space agencies, and defense ministries with multi-year procurement cycles. French CNES and German DLR anchor institutional demand, imposing ECSS software standards that extend qualification timelines.
- Commercial Operators:Constellation builders and satellite service providers. Scottish and German NewSpace ventures accelerate adoption of software-defined AOCS architectures.
- Aerospace Manufacturers:Prime contractors integrating AOCS into complete platforms.
- Research Institutions:University and laboratory missions with bespoke technical requirements.
Government agencies sit at the top of the volume ranking, with commercial operators climbing the fastest on venture-funded constellation build-outs.
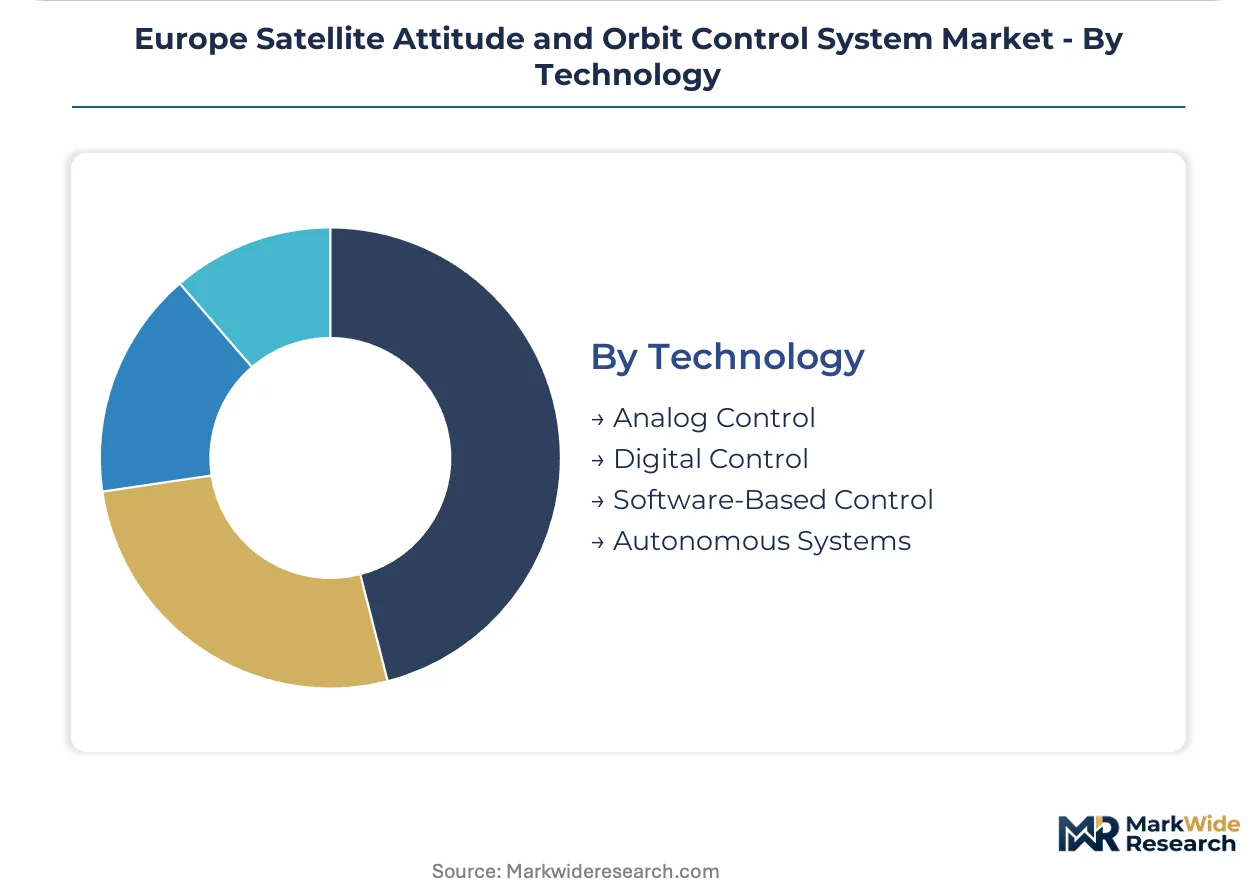
Technology:
Development timelines stretch longest for autonomous systems, where ESA software certification creates bottlenecks that analog heritage designs bypass.
- Digital Control:FPGA and processor-based architectures with reconfigurable gain schedules. German and Scottish smallsat builders adopt fastest, cutting integration timelines through modular software blocks.
- Autonomous Systems:Self-correcting fault detection and recovery loops reducing ground-segment dependency. ESA ECSS software standards impose multi-year qualification barriers that compress product refresh cycles.
- Analog Control:Heritage voltage-based architectures with fixed hardware implementations.
- Software-Based Control:Containerized mission functions deployable without hardware swaps.
Digital control sits at the top of the volume ranking, with autonomous systems climbing the fastest as operators push for reduced ground-staff ratios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping AOCS manufacturing footprints across Europe, with producers migrating toward jurisdictions offering streamlined ESA qualification pathways and lower REACH compliance costs.
Germany
DLR institutional programs and sovereign constellation build-outs anchor demand for precision pointing systems. ESA ECSS software standards impose multi-year qualification timelines that favor established Bavarian suppliers with existing certification infrastructure. Munich and Stuttgart aerospace clusters concentrate reaction wheel manufacturing and optical sensor integration for Earth observation platforms.
France
CNES anchor programs and Galileo refresh initiatives drive procurement of control moment gyroscopes and autonomous flight algorithms. EU Green Deal space sustainability guidelines mandate design-for-demise features that tighten debris mitigation requirements for Paris-region prime contractors. Toulouse and Île-de-France house integrated system houses extending from payload design to flight-proven control architectures.
Italy
Commercial weather operators and medium satellite fleets expand demand for agile revisit capabilities and green propellant-compatible thrusters. ECHA restrictions on hydrazine accelerate chemistry transitions favoring domestic propulsion specialists. Rome and Turin industrial corridors concentrate thruster manufacturing and satellite platform integration.
United Kingdom
Scottish NewSpace ventures accelerate adoption of software-defined AOCS architectures with modular software blocks. UK Space Agency funding for constellation deployments supports CubeSat AOCS supply chains. Glasgow and Edinburgh clusters dominate smallsat attitude control procurement with compressed integration timelines.
Poland
Warsaw and Krakow aerospace clusters offer untapped precision machining capacity for reaction wheel housings and gyroscope frames at competitive cost structures. Emerging suppliers leverage EU structural funds to build ESA-compliant manufacturing capabilities. The country's central European location provides logistics advantages for component distribution to German and French prime contractors.
Europe Satellite Attitude and Orbit Control System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined architectures and constellation-scale manufacturing. The vendor base stratifies across integrated system houses with end-to-end mission capability, specialized component suppliers with deep hardware expertise, and NewSpace-focused ventures emphasizing rapid iteration cycles. Dominant competitive moves include geographic expansion into lower-cost manufacturing jurisdictions and strategic partnerships around green propellant technology roadmaps.
Among Germany-based specialists, Jena-Optronik and OHB SE exemplify the precision-tier archetype anchored in institutional program supply chains. AAC Clyde Space represents the NewSpace-optimized model with Scottish-German footprint advantages. Thales occupies a position spanning integrated mission capability from payload design through autonomous control algorithms.
| Leading Market Players |
|---|
| AAC Clyde Space |
| Jena-Optronik |
| OHB SE |
| Sitael S.p.A. |
| Innovative Solutions in Space BV |
| SENER Group |
| Bradford Engineering BV |
| NewSpace Systems |
| Thales |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal space sustainability provisions gate access to premium-tier AOCS supply pools by mandating REACH-compliant propulsion subsystems and design-for-demise architectures that only ESA-qualified manufacturers can deliver. French and German prime contractors absorb these compliance costs into long-term institutional contracts, while commercial constellation operators in Italy and the United Kingdom face sharper trade-offs between qualification overhead and unit economics.
Pricing Analysis
Distributor margins for AOCS components compress toward single digits on high-volume constellation tenders, while direct-to-OEM channels retain 15-20 point premiums for flight-proven heritage hardware. Three-tier pricing structure across premium, standard, and economy levels separates ESA-qualified reaction wheels from commercial-grade magnetorquers and unqualified CubeSat components. Cost compression in the economy tier intensifies because Scottish and German NewSpace ventures unbundle software from hardware procurement. Commercial constellation operators exhibit the sharpest price sensitivity, whereas CNES and DLR anchor programs prioritize qualification reliability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese-processed neodymium and dysprosium for magnetorquer cores, which European manufacturers draw from despite strategic stockpiling initiatives. Precision machining for reaction wheel housings concentrates in Germany, Italy, and emerging Polish clusters around Warsaw and Krakow. Supply chain risk centers on rare earth export restrictions from Beijing that could disrupt torque rod production timelines. Distribution runs through prime contractor integration facilities in Toulouse, Munich, and Rome, with component vendors maintaining captive supply relationships to bypass distributor markups on mission-critical hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Satellite Attitude and Orbit Control System Market functions as a stable compounder anchored by sovereign constellation build-outs and ESA institutional refresh programs that generate predictable multi-year procurement cycles.
For Market Incumbents: Anchor market position through backward integration into rare earth magnet processing and optical sensor fabrication, mitigating single-source exposure to Chinese material flows. Incumbent suppliers should deepen certification infrastructure investments to extend ESA ECSS software qualification timelines that emerging entrants cannot match, while consolidating component-only supply relationships as mega-constellation operators fragment end-to-end mission contracts.
For New Entrants and Emerging Players: The price-point gap between premium institutional-grade AOCS and economy CubeSat components creates entry space for mid-tier vendors offering REACH-compliant thrusters without full ESA heritage overhead. Polish manufacturing clusters present the most penetrable geography for precision machining capacity, with EU structural funds de-risking facility build-out. A software-defined go-to-market angle—containerized control algorithms sold separately from hardware—aligns with Scottish and German NewSpace procurement patterns.
For Investors and Strategic Acquirers: Roll-up economics work for specialized AOCS component suppliers because ESA qualification barriers prevent rapid organic entry and create scarcity value for certified manufacturing assets. The optimal acquisition target archetype combines reaction wheel or thruster hardware expertise with existing ECSS software certification, positioned for Galileo refresh and sovereign constellation ramp-ups. Watch for inflection where green propellant chemistry transitions accelerate Italian propulsion specialist consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Propellant Chemistry Transition | ECHA hydrazine restrictions favor Italian thruster manufacturers with compliant product roadmaps. |
| Software-Defined AOCS Architecture | Modular control blocks cut Scottish smallsat integration timelines from months to weeks. |
| Polish Manufacturing Footprint Expansion | Warsaw and Krakow clusters offer competitive precision machining for reaction wheel housings. |
| Rare Earth Magnet Supply Security | Strategic stockpiling mitigates Chinese neodymium-dysprosium export vulnerability for magnetorquers. |
| AI-Enabled Predictive Maintenance | Machine learning integration with AOCS telemetry enables subscription health monitoring for constellations. |
Research Methodology
Coverage spans Western Europe, Central Europe, and Nordic regions, with primary inputs from each territory combined with secondary validation across regulatory filings and trade databases. Primary interviews engaged satellite platform engineers at French and German prime contractors, procurement leads at Italian propulsion specialists, ESA program managers, and Scottish NewSpace venture technical directors. Secondary sources included ESA procurement disclosures, ECHA REACH substance restriction updates, EU Green Deal space sustainability guidelines, and national space agency budget appropriations. Bottom-up component demand modeling and top-down institutional program sizing were triangulated against manufacturer capacity disclosures.
Rate-of-change decomposition across the analysis window separated volume growth from mix-shift effects as constellation deployments displace single-satellite procurements. Segmentation dimensions modeled include product architecture, application payload type, end-user procurement channel, and technology control philosophy. CAGRs were derived from installed base turnover analysis and new program award pipelines. Industry-specific forecast inputs incorporated ESA multi-annual budget trajectories and commercial constellation venture funding disclosed through UK Space Agency and national innovation agency filings.
Caveats apply where rare earth export restrictions, ESA budget reallocation, or green propellant chemistry validation delays could materially shift the outlook. Forecasts reflect assumptions about qualification timeline stability and REACH enforcement consistency that may prove sensitive to regulatory priority shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Russia Satellite Imagery Services Market
Satellite
Europe Small Satellite Market
Satellite
Satellite GPS Receivers Market
Satellite
Global Enterprise VSAT System Market
Satellite
Eastern Europe and North Africa Satellite Communication Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
Global Maritime Satellite Communication Market
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
Global Broadband Satellite Services Market
Satellite
North America Mobile Satellite Services Market
Satellite
South Korea Satellite Communication Market
Satellite
Global Dish Antennas Market
Satellite
LEO Satellite Constellation Market
Satellite
Satellite Services Market
Satellite
Japan Satellite Communication Market
Satellite
North America Satellite Launch Vehicle Market