
 Canada Satellite-Based Earth Observation Market | 2026-2036
Canada Satellite-Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Satellite-Based Earth Observation Market Insights
Canadian government procurement channels for Earth observation data is fragmenting as federal contracts once monopolized by domestic primes now split across international satellite operators and analytics specialists. MDA Space Ltd. leverages its RADARSAT heritage to anchor sovereign imaging capabilities for defense and climate programs. Maxar Technologies Inc. competes through high-resolution optical constellations serving precision agriculture clients in Saskatchewan and Manitoba. Planet Labs PBC differentiates via daily revisit frequency that supports wildfire response coordination across British Columbia and the Yukon.
Canada satellite-based Earth observation encompasses the acquisition, processing, and distribution of geospatial imagery and sensor data from low-Earth orbit and geostationary platforms, typically spanning spatial resolutions from sub-meter to 250 meters and spectral bands from visible through synthetic aperture radar wavelengths. These systems serve commercial and governmental users requiring persistent environmental surveillance, infrastructure assessment, and resource inventory across Canada's vast and remote territories. Optical technology leads current revenue contribution due to mature downstream analytics ecosystems, while radar technology represents the fastest-expanding segment given all-weather reliability demanded by Arctic maritime monitoring and disaster response protocols. Government end users command the largest budget allocation through programs administered by the Canadian Space Agency and Department of National Defence, though private sector adoption accelerates fastest as insurance underwriters and commodity traders integrate satellite-derived intelligence into operational workflows.
Health Canada and PMRA shape agricultural application standards through pesticide runoff monitoring requirements that mandate satellite-verified compliance reporting from Prairie province farm operators. The Canadian Space Agency coordinates with Transport Canada to enforce ice surveillance protocols under the Canada Shipping Act, directly stimulating demand for RADARSAT-2 and future constellation services. Stakeholders must monitor whether proposed amendments to the Remote Sensing Space Systems Act expand licensing burdens on foreign satellite operators or create preferential market access for domestically controlled data providers.
Market Dynamics
The Canadian Space Agency's RADARSAT program is compressing technology cycles toward synthetic aperture radar dominance, while federal procurement fragmentation pulls international operators into sovereign defense and climate monitoring workflows previously controlled by domestic primes.
Growth Catalysts
- Arctic maritime surveillance mandates:Transport Canada's ice surveillance protocols under the Canada Shipping Act require persistent all-weather monitoring, directly stimulating demand for RADARSAT-2 and successor constellation services across northern shipping corridors.
- Pesticide runoff compliance:Health Canada and PMRA enforce satellite-verified reporting requirements on Prairie province farm operators, embedding Earth observation into agricultural environmental management systems.
- Oil sands carbon accountability:Alberta's environmental compliance frameworks for oil sands operators mandate synthetic aperture radar monitoring of tailings ponds and reclamation sites, creating concentrated demand in the Athabasca region.
Market Restraints
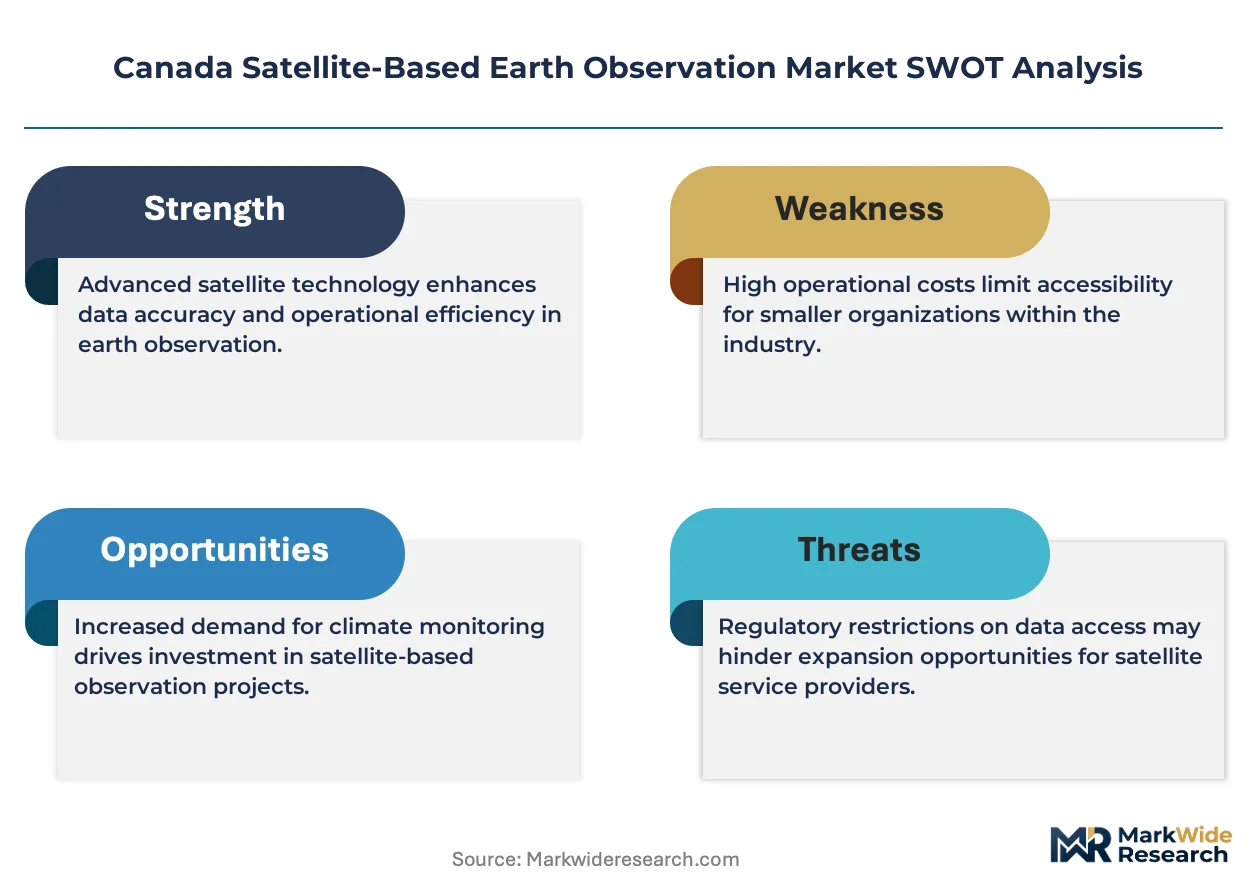
- Launch cost volatility:Dependence on foreign launch providers exposes Canadian satellite operators to payload integration delays and currency fluctuation risks that compress margin structures on constellation deployment schedules.
- Data sovereignty constraints:Proposed amendments to the Remote Sensing Space Systems Act may impose licensing burdens on foreign satellite operators, potentially fragmenting data access for commercial analytics providers.
- Optical weather dependency:Persistent cloud cover across Pacific Coast and Atlantic maritime zones limits reliable revisit frequencies for electro-optical systems, forcing redundancy investments in radar-capable alternatives.
Strategic Opportunities
- Wildfire response coordination:Daily revisit frequencies from commercial smallsat constellations enable real-time burn perimeter tracking across British Columbia and Yukon territories, displacing slower aerial survey methods.
- Indigenous land management partnerships:First Nations territorial monitoring agreements create emerging demand channels for community-controlled data analytics and traditional knowledge integration platforms.
- Insurance risk modeling:Property and casualty underwriters in Toronto and Montreal are integrating satellite-derived flood and permafrost thaw intelligence into parametric coverage products for northern infrastructure.
Industry Challenges
- Synthetic aperture radar expertise scarcity:Specialized signal processing and interferometric analysis skills concentrate within legacy RADARSAT program alumni, constraining workforce expansion for commercial analytics startups.
- Legacy system integration friction:Federal agencies maintain decades of optical imagery archives in incompatible formats, complicating multi-sensor fusion workflows for climate change detection algorithms.
- Dual-use classification delays:Defense and civilian application overlap triggers extended export control reviews under Canadian Controlled Goods regulations, elongating procurement cycles for international component sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Satellite-Based Earth Observation Market |
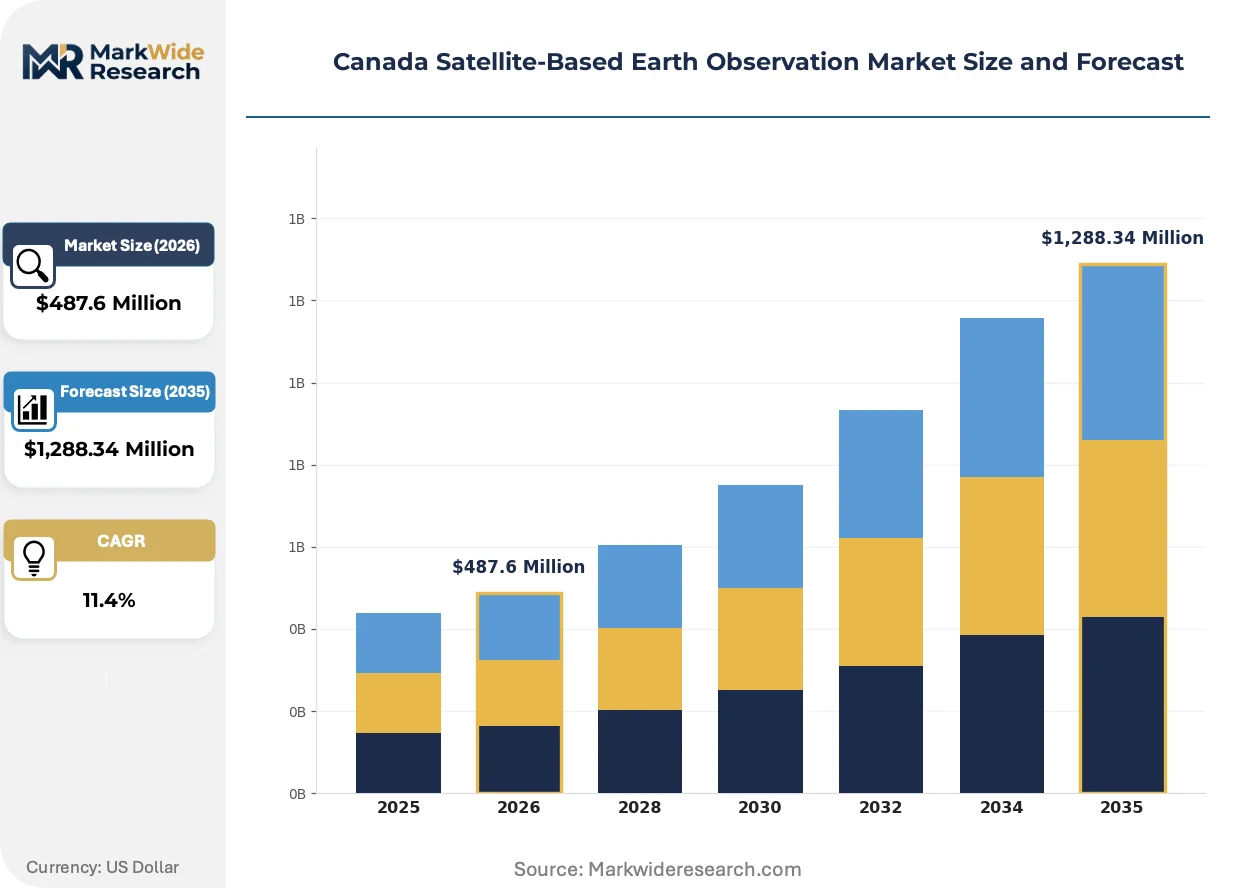
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Optical, Radar, Hyperspectral, LiDAR Application: Agriculture, Forestry, Urban Planning, Climate Monitoring End User: Government, Private Sector, Research Institutions, NGOs Service Type: Data Analytics, Consulting, Software Development, Training |
| Companies Covered | MDA Space Ltd., Telesat Canada, Maxar Technologies Inc., Airbus Defence and Space, Planet Labs PBC, GeoOptics Inc., L3Harris Technologies Inc., Thales Group, Spire Global, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Satellite-Based Earth Observation Market Trends and Innovations
Machine learning inference at the sensor edge is compressing analytics latency from hours to minutes, while regulatory pressure on climate disclosure accelerates integration of satellite-derived environmental verification into corporate reporting workflows.
Hyperspectral imaging payloads are digitizing mineral exploration workflows across Quebec's Plan Nord and Saskatchewan's potash belt. Junior mining companies deploy satellite-derived alteration mapping to prioritize drill targets before committing to airborne geophysical surveys. This technology is digitizing resource assessment timelines that previously required seasonal field campaigns.
Health Canada and PMRA are tightening agricultural chemical runoff monitoring standards, mandating satellite-verified compliance documentation from Prairie province operators. The regulatory consequence is embedding persistent Earth observation into farm management software platforms. Saskatchewan's grain belt operators now face mandatory spectral verification of buffer zone maintenance and drainage pattern modifications.
Commodity traders and agricultural insurers are unbundling traditional data subscription models in favor of API-delivered, on-demand analytics for specific field boundaries. This procurement evolution displaces annual licensing arrangements with transactional pricing tied to growing season decision windows. Manitoba's crop insurance providers represent the most advanced adopters, integrating satellite-derived yield forecasting directly into claims adjustment workflows.
Canada Satellite-Based Earth Observation Market Segmentation
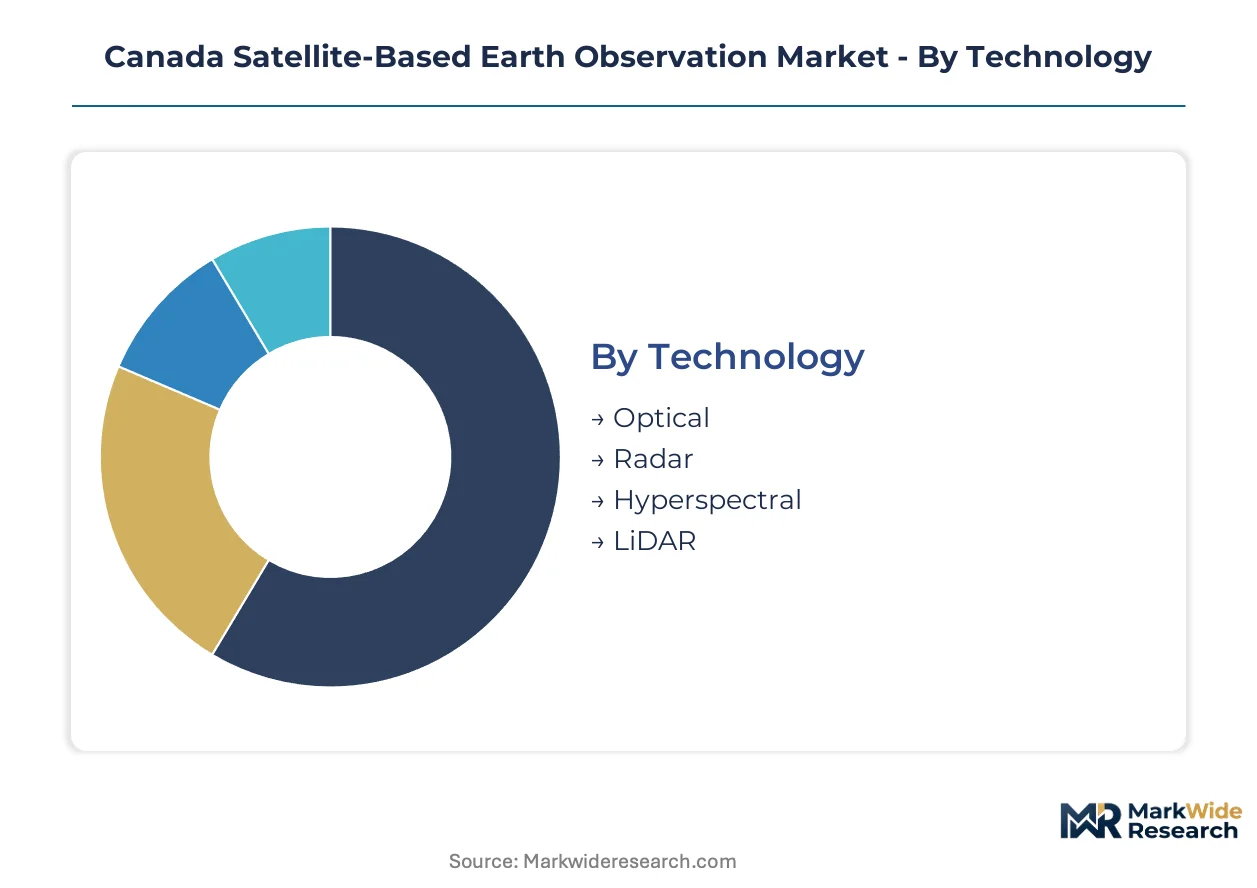
Canada's satellite-based Earth observation market segments along four functional dimensions that reflect procurement priorities across federal agencies, provincial resource operators, and commercial analytics buyers. Each category reveals distinct technology preferences shaped by Arctic operational requirements, agricultural compliance mandates, and data sovereignty considerations.
Technology:
Use-case spectrum spans all-weather maritime surveillance to precision spectral mapping, with each technology addressing specific environmental constraints across Canadian territories.
- Optical:Electro-optical sensors capture visible to near-infrared imagery at sub-meter to 250-meter resolutions. Prairie province farm operators in Saskatchewan and Manitoba deploy optical analytics for crop health monitoring and buffer zone compliance verification under Health Canada and PMRA standards.
- Radar:Synthetic aperture radar transmits microwave signals that penetrate cloud cover and darkness, enabling persistent monitoring regardless of weather. Transport Canada's ice surveillance protocols under the Canada Shipping Act drive concentrated demand across northern shipping corridors where optical systems fail.
- Hyperspectral:Narrow spectral bands detect mineral alteration signatures and vegetation stress indicators invisible to standard multispectral sensors. Quebec's Plan Nord mining juniors prioritize drill targets using satellite-derived alteration mapping before committing to airborne surveys.
- LiDAR:Laser ranging systems generate high-precision elevation models for infrastructure assessment and flood plain mapping. British Columbia utilities integrate LiDAR-derived terrain data into wildfire risk models for transmission line corridors.
The dominant share belongs to Optical, while Radar is closing the gap fastest as Arctic maritime mandates expand and cloud-cover limitations constrain electro-optical reliability.
Application:
Customer workflows determine margin structures, with resource extraction and regulatory compliance commanding premium pricing against lower-tier planning and research applications.
- Agriculture:Spectral monitoring of crop health, yield forecasting, and chemical runoff compliance dominates Prairie province demand. Manitoba crop insurance providers integrate satellite-derived yield forecasting directly into claims adjustment workflows, displacing manual field assessment.
- Forestry:Natural Resources Canada drives adoption across inventory management, pest outbreak detection, and sustainable harvest planning. British Columbia's wildfire response coordination now relies on daily revisit frequencies from commercial smallsat constellations for real-time burn perimeter tracking.
- Urban Planning:Municipal governments in Toronto, Vancouver, and Montreal deploy change detection algorithms for infrastructure growth monitoring and zoning enforcement. Permafrost thaw detection guides northern community expansion planning in Yukon and Northwest Territories.
- Climate Monitoring:Federal climate programs require multi-decadal data fusion for carbon stock assessment and ice sheet dynamics tracking. Alberta's oil sands operators face mandatory synthetic aperture radar monitoring of tailings ponds and reclamation sites under provincial environmental compliance frameworks.
Agriculture captures the largest revenue pool through embedded compliance mandates, though Climate Monitoring exhibits the steepest expansion trajectory as carbon disclosure regulations tighten.
End User:
Budget authority concentrates in federal procurement channels, while private sector adoption accelerates through insurance and commodity trading workflows.
- Government:Canadian Space Agency and Department of National Defence command the largest budget allocation through RADARSAT program continuity and defense surveillance requirements. Federal contracts increasingly split between domestic primes and international operators as procurement channels fragment.
- Private Sector:Property and casualty underwriters in Toronto and Montreal integrate satellite-derived flood and permafrost thaw intelligence into parametric coverage products. Commodity traders unbundle traditional subscriptions for API-delivered, on-demand analytics tied to growing season decision windows.
- Research Institutions:Universities and federal laboratories access archived imagery through Canadian Space Agency partnerships for climate change detection algorithm development. Legacy optical archives in incompatible formats complicate multi-sensor fusion workflows.
- NGOs:Environmental advocacy groups and Indigenous organizations deploy community-controlled monitoring for territorial stewardship and traditional knowledge integration. First Nations agreements create emerging demand channels for participatory data analytics platforms.
Government retains the dominant procurement position, while Private Sector adoption is climbing fastest as operational workflows integrate satellite intelligence.
Service Type:
Downstream value capture shifts from raw data licensing toward outcome-based analytics and embedded software integration.
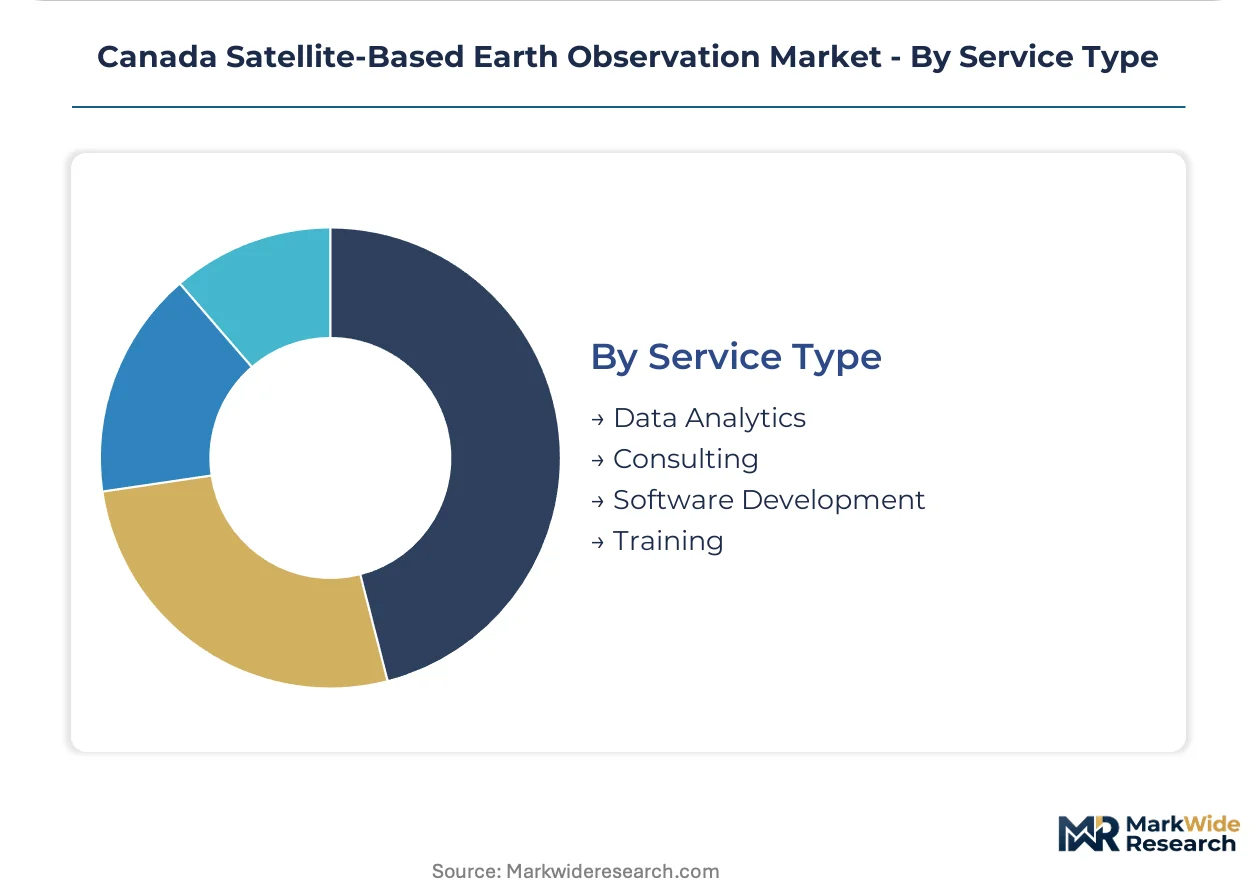
- Data Analytics:Processed imagery products including change detection, classification, and predictive modeling command premium pricing against raw pixel delivery. Machine learning inference at the sensor edge compresses analytics latency from hours to minutes for time-sensitive applications.
- Consulting:Custom project design, regulatory compliance documentation, and integration advisory support federal and provincial procurement requirements. Specialized synthetic aperture radar expertise scarcity concentrates within legacy RADARSAT program alumni.
- Software Development:Platform integration, API architecture, and farm management system embedding embed Earth observation into operational technology stacks. Saskatchewan grain belt operators now face mandatory spectral verification through software-mediated compliance reporting.
- Training:Workforce development for interferometric analysis, multi-sensor fusion, and domain-specific interpretation addresses capability gaps in commercial analytics startups. Signal processing skills concentration constrains expansion for emerging providers.
Data Analytics holds the dominant revenue position, while Software Development is gaining share fastest as API-delivered integration displaces annual licensing arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans Mountain Pipeline expansion underwrites British Columbia's emergence as a critical node for environmental monitoring infrastructure, while the St. Lawrence Seaway anchors Quebec's maritime surveillance demand.
Ontario
Toronto's financial sector drives insurance risk modeling applications, with property underwriters integrating satellite-derived flood intelligence into parametric coverage products. Transport Canada coordinates ice surveillance protocols from Ottawa headquarters, stimulating procurement for RADARSAT constellation services. The Greater Toronto Area concentrates machine learning analytics startups addressing agricultural compliance workflows.
Quebec
Plan Nord mining operations digitize exploration timelines using hyperspectral alteration mapping before committing to airborne geophysical surveys. The Canadian Space Agency's satellite operations center in Longueuil anchors federal procurement for synthetic aperture radar capabilities. Montreal's aerospace cluster hosts legacy RADARSAT program alumni whose specialized signal processing expertise remains scarce in commercial markets.
Alberta
Oil sands operators face mandatory synthetic aperture radar monitoring of tailings ponds and reclamation sites under provincial environmental compliance frameworks. The Athabasca region concentrates demand for persistent all-weather surveillance that optical systems cannot provide. Calgary's energy sector procurement channels increasingly split between domestic primes and international analytics specialists.
British Columbia
Wildfire response coordination across the province and Yukon relies on daily revisit frequencies from commercial smallsat constellations for real-time burn perimeter tracking. Vancouver's municipal government deploys change detection algorithms for infrastructure growth monitoring and zoning enforcement. Pacific Coast cloud cover limitations force redundancy investments in radar-capable alternatives for reliable environmental surveillance.
Prairie Provinces
Saskatchewan grain belt operators now face mandatory spectral verification of buffer zone maintenance and drainage pattern modifications under Health Canada and PMRA standards. Manitoba crop insurance providers represent the most advanced adopters, integrating satellite-derived yield forecasting directly into claims adjustment workflows. Winnipeg and Regina anchor agricultural analytics demand that unbundles traditional data subscriptions for API-delivered, on-demand field boundary intelligence.
Canada Satellite-Based Earth Observation Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin on sensor payloads and ground segment hardware. The vendor base splits between consolidated domestic primes with RADARSAT heritage and fragmented international operators penetrating through analytics specialization. Three archetypes dominate: sovereign imaging capability providers, high-resolution optical constellation operators, and smallsat daily revisit frequency specialists. Competitive moves concentrate on strategic partnerships for Arctic maritime surveillance contracts and portfolio diversification into climate monitoring analytics.
Within the sovereign capability tier, MDA Space Ltd. anchors domestic radar imaging heritage for defense and climate programs. Maxar Technologies Inc. and Planet Labs PBC occupy positions on the commercial analytics vector, with the former representing high-resolution optical constellation provision and the latter exemplifying daily revisit frequency deployment for time-sensitive environmental response. These three entities collectively illustrate the procurement fragmentation pulling international operators into workflows previously controlled by domestic primes.
| Leading Market Players |
|---|
| MDA Space Ltd. |
| Telesat Canada |
| Maxar Technologies Inc. |
| Airbus Defence and Space |
| Planet Labs PBC |
| GeoOptics Inc. |
| L3Harris Technologies Inc. |
| Thales Group |
| Spire Global, Inc. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in domestic launch infrastructure compresses procurement timelines for Canadian satellite operators while simultaneously elevating pricing power for foreign launch providers serving the RADARSAT constellation deployment schedule. This utilization imbalance feeds directly into downstream data pricing structures, where sovereign imaging capabilities command substantial premiums against commoditized optical analytics.
Pricing Analysis
Volume-discount tiering structures segment procurement across government, enterprise, and research buyer archetypes, with annual subscription commitments securing preferential per-scene rates against transactional API access. Three-tier pricing stratifies across premium sovereign radar imagery, standard commercial optical products, and economy smallsat revisit data. Price differentiation hinges on resolution grade and data sovereignty certification under Canadian Space Agency licensing frameworks. Pricing pressure stems from international constellation overcapacity in optical segments. Government end users exhibit lowest price sensitivity given mission-critical Arctic surveillance mandates, while agricultural analytics providers face acute margin compression.
Supply Chain Analysis
Extended payment terms from federal procurement channels strain working capital for domestic component suppliers, accelerating consolidation toward vertically integrated primes capable of self-financing constellation development cycles. Sensor payload manufacturing concentrates in the United States, Germany, and France, while launch services draw from Florida, California, and French Guiana facilities. Specialized synthetic aperture radar electronics, precision optics, and radiation-hardened processors constitute critical input dependencies. Single-source vulnerability in synthetic aperture radar expertise constrains workforce expansion. Distribution runs through Canadian Space Agency-coordinated procurement channels and direct commercial sales to resource extraction operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada satellite-based Earth observation market represents a high-growth disruption anchored by synthetic aperture radar technology maturation and federal Arctic sovereignty mandates. Machine learning inference at the sensor edge compresses analytics latency from hours to minutes, creating structural advantage for operators integrating edge-computing payloads.
For Market Incumbents: Insulate sovereign imaging capabilities through backward integration into radar payload manufacturing and exclusive licensing arrangements with Transport Canada for ice surveillance protocols. Prioritize capacity expansion in synthetic aperture radar signal processing expertise, where legacy RADARSAT program alumni concentration creates defensive moats against commercial analytics entrants. Counter international constellation overcapacity by embedding data analytics into farm management software platforms under Health Canada compliance mandates.
For New Entrants and Emerging Players: Establish a beachhead in Indigenous land management partnerships, where First Nations territorial monitoring agreements create emerging demand channels underserved by incumbent primes. Target wildfire response coordination workflows across British Columbia and Yukon, where daily revisit frequency requirements exceed legacy system capabilities. Deploy API-delivered, on-demand analytics to displace annual licensing arrangements with Manitoba crop insurance providers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across smallsat constellation deployment as standardized bus platforms and rideshare launch access compress unit economics. Long-term viability favors operators controlling both sensor manufacturing and downstream analytics software development. Acquisition target archetypes include synthetic aperture radar signal processing specialists and agricultural compliance analytics platforms. Monitor amendments to the Remote Sensing Space Systems Act as regulatory inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Arctic Maritime Surveillance Partnership | Transport Canada's ice surveillance protocols under the Canada Shipping Act mandate persistent all-weather monitoring capabilities. |
| Hyperspectral Mining Analytics Platform | Quebec's Plan Nord juniors prioritize drill targets using satellite-derived alteration mapping before airborne surveys. |
| Agricultural Compliance Software Integration | Health Canada and PMRA standards embed spectral verification into Saskatchewan grain belt farm management systems. |
| Wildfire Response Coordination Service | British Columbia and Yukon territories displace slower aerial survey methods with daily revisit constellation data. |
| Insurance Risk Modeling Partnership | Toronto and Montreal underwriters integrate flood and permafrost thaw intelligence into parametric coverage products. |
Research Methodology
The analysis maps optical, radar, hyperspectral, and LiDAR technology sub-sectors, each validated through satellite program directors, Earth observation procurement officers, agricultural analytics platform engineers, and insurance risk modeling specialists. Primary interviews with Canadian Space Agency contract managers, MDA Space heritage program alumni, and Manitoba crop insurance claims adjusters combined with secondary validation against Department of National Defence procurement disclosures, Health Canada regulatory filings, and Alberta environmental compliance frameworks. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume estimates.
Assumption sets held federal Arctic surveillance mandates and agricultural chemical runoff monitoring standards fixed while varying launch cost trajectories and foreign operator licensing burden scenarios across the projection horizon. Segmentation dimensions modeled include technology type, application workflow, end-user budget authority, and service tier. CAGRs derived from historical procurement pattern analysis and technology adoption curve positioning. Forecast inputs incorporated synthetic aperture radar constellation deployment schedules and machine learning edge-computing penetration rates.
Stress conditions across launch provider concentration, currency fluctuation exposure, and regulatory licensing expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding federal procurement continuity and technology cycle compression. Macroeconomic deviation, regulatory amendment, or technological disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
South Korea Satellite Connectivity Market
Satellite
North America Remote Sensing Services Market
Satellite
North America Satellite IoT Market
Satellite
France Satellite-Based Earth Observation Market
Satellite
North America Small Satellite Market
Satellite
Satellite Connectivity Market
Satellite
India Satellite-Based Earth Observation Market
Satellite
Middle East Satellite-Based Earth Observation Market
Satellite
Mexico Satellite Connectivity Market
Satellite
Satellite Antenna Market
Satellite
4K Satellite Broadcasting Market
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
Electric Propulsion Satellite Market
Satellite
Small Satellite Market
Satellite
Russia Satellite Imagery Services Market
Satellite
Global LEO Satellite Market