
 Brazil Satellite Imagery Services Market | 2026-2036
Brazil Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Satellite Imagery Services Market Insights
Constellation-as-a-service architecture is fragmenting traditional vertically integrated satellite operations into layered component markets. Satellogic leverages its Buenos Aires-built microsatellite factory to sustain cost leadership in high-revisit optical tasking over Brazilian territory. Maxar Technologies anchors premium defense and intelligence contracts through its sub-meter resolution archive and direct government relationships.
Brazil satellite imagery services encompass the acquisition, processing, and analytic distribution of geospatial data captured from orbital platforms, with spatial resolutions ranging from 30-centimeter panchromatic to 10-meter multispectral depending on sensor class and orbital altitude. These services convert raw sensor data into orthorectified products and derived intelligence layers for commercial and institutional decision-making. Orthophoto and multi-spectral imagery segments dominate current revenue as mature, price-transparent procurement categories, while geospatial analytics represents the fastest-expanding margin pool as buyers shift from pixels to actionable variable-rate prescriptions. Defense and agriculture end-user verticals absorb the majority of contracted volume, though environmental monitoring is deepening its share under federal compliance obligations.
INCRA's territorial certification requirements and the Brazilian Space Agency's satellite data policy shape procurement standards for land governance applications, while ANA's water resource monitoring mandates drive recurring environmental imagery subscriptions. ANVISA maintains indirect influence through traceability rules that push agribusiness toward auditable geospatial documentation. Stakeholders must weigh the trade-off between foreign constellation dependency and domestic data sovereignty as Visiona Tecnologia Espacial advances indigenous electro-optical payload capabilities.
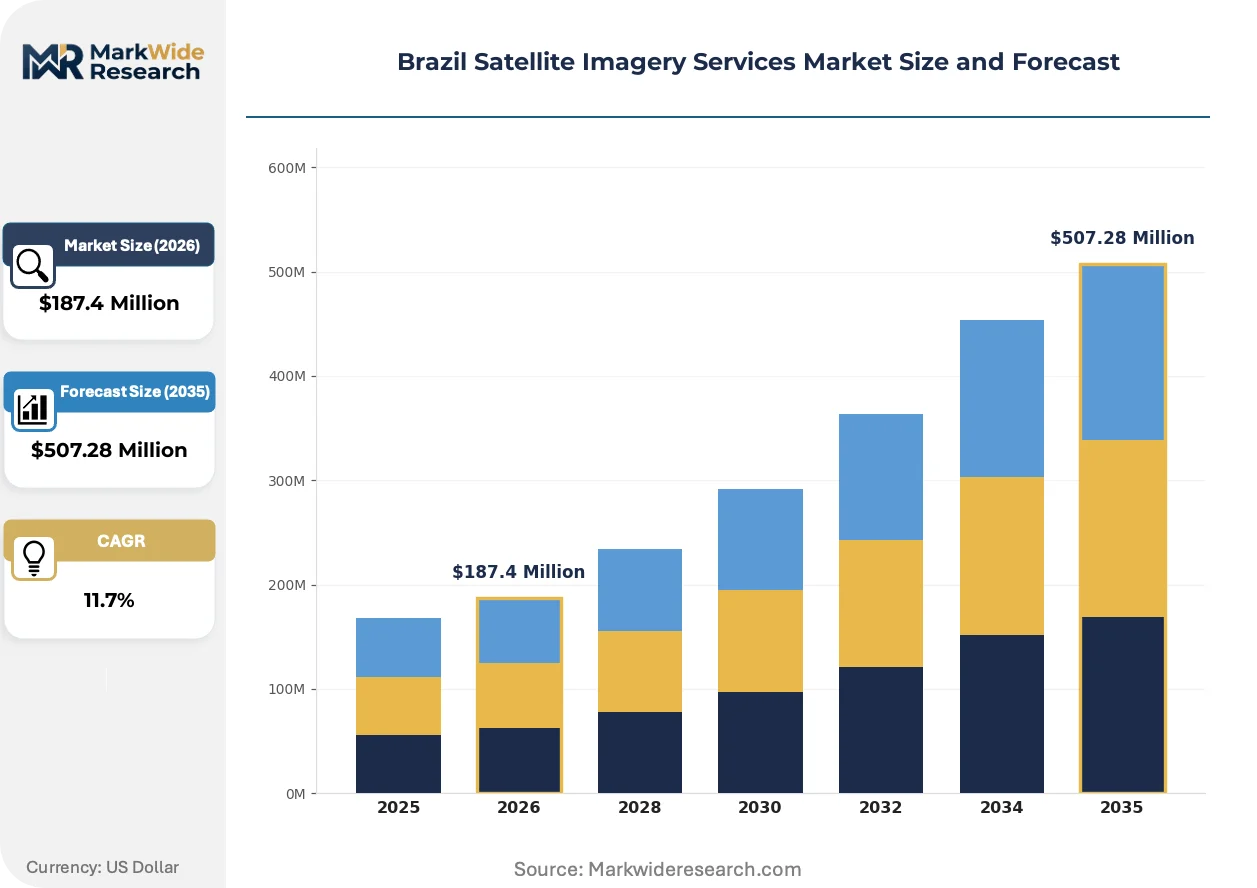
Market Dynamics
Constellation-as-a-service architecture fragments vertically integrated satellite operations into layered component markets, forcing buyers to assemble imagery pipelines from specialized providers rather than purchasing bundled end-to-end solutions.
Growth Catalysts
- INCRA territorial certification mandates:Land regularization programs require georeferenced imagery for property boundary verification, creating recurring procurement cycles from cooperatives and individual landholders.
- Multi-spectral precision agriculture:Soy and corn operators in Mato Grosso deploy variable-rate input prescriptions derived from weekly revisit imagery during critical growth windows.
- ANA water resource monitoring:Federal hydrological mandates sustain subscriptions for watershed-scale change detection across the Pantanal and Amazon basin headwaters.
Market Restraints
- Foreign constellation dependency:Domestic electro-optical payload capabilities remain underdeveloped, exposing buyers to currency volatility and foreign data sovereignty restrictions.
- High-resolution tasking costs:Sub-meter panchromatic imagery requires dedicated orbital passes, pricing out smallholder cooperatives from premium analytics tiers.
- Cloud cover interference:Persistent tropical convection over the Amazon and Atlantic forest biomes degrades optical sensor utility during wet seasons.
Strategic Opportunities
- Synthetic aperture radar convergence:All-weather SAR capability combined with optical multi-spectral layers enables year-round crop monitoring regardless of atmospheric conditions.
- Carbon credit verification:Emerging compliance frameworks for REDD+ and voluntary carbon markets create demand for deforestation baseline imagery and change detection audits.
- Minas Gerais coffee belt penetration:Precision agriculture adoption lags in southeastern highland regions, representing untapped subscription volume for frost damage and flowering stage monitoring.
Industry Challenges
- Geospatial data science talent scarcity:Agronomy programs lack integrated remote sensing curricula, forcing service providers to train variable-rate prescription analysts in-house.
- Legacy farm management system integration:Established ERP platforms in Brazilian agribusiness require custom API development to ingest orbital imagery feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Satellite Imagery Services Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Orthophoto, Multi-Spectral Imagery, LiDAR, Aerial Photography End User: Agriculture, Urban Planning, Environmental Monitoring, Defense Technology: Satellite-Based, UAV, Geospatial Analytics, Ground-Based Application: Disaster Management, Natural Resource Exploration, Infrastructure Development, Climate Research |
| Companies Covered | Satellogic, Airbus Group, Inc., Maxar Technologies, Embraer S.A., L3Harris Technologies, Planet Labs PBC, Telespazio Brasil, Embratel Star One, Visiona Tecnologia Espacial S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Satellite Imagery Services Market Trends and Innovations
Orbital data delivery models are fragmenting as buyers reject bundled pixels-for-pixels pricing in favor of outcome-based agricultural intelligence subscriptions.
Hyperspectral sensor technology is migrating from research-grade government missions to commercial microsatellite constellations. Mato Grosso cotton and sugarcane operators now contract early-stage crop stress detection at 10-meter ground sample distance. This capability compression is collapsing the historical premium commanded by airborne hyperspectral surveys.
ANA's 2023 updated hydrological monitoring framework mandates quarterly satellite-derived surface water extent reporting for all hydroelectric concessions. Dam operators must submit georeferenced reservoir sedimentation and shoreline erosion assessments. The Paraná and Tocantins river basins face the steepest compliance timelines, driving rushed procurement of archival stereo imagery for baseline establishment.
Cooperative buyers are consolidating imagery purchasing through federated procurement platforms. Individual Mato Grosso soy producers no longer contract directly with constellation operators; instead, regional cooperatives negotiate enterprise tasking rights and redistribute analytic outputs through shared data lakes. This channel compression squeezes margin from traditional value-added resellers while concentrating negotiating leverage among three dominant agricultural federations.
Brazil Satellite Imagery Services Market Segmentation
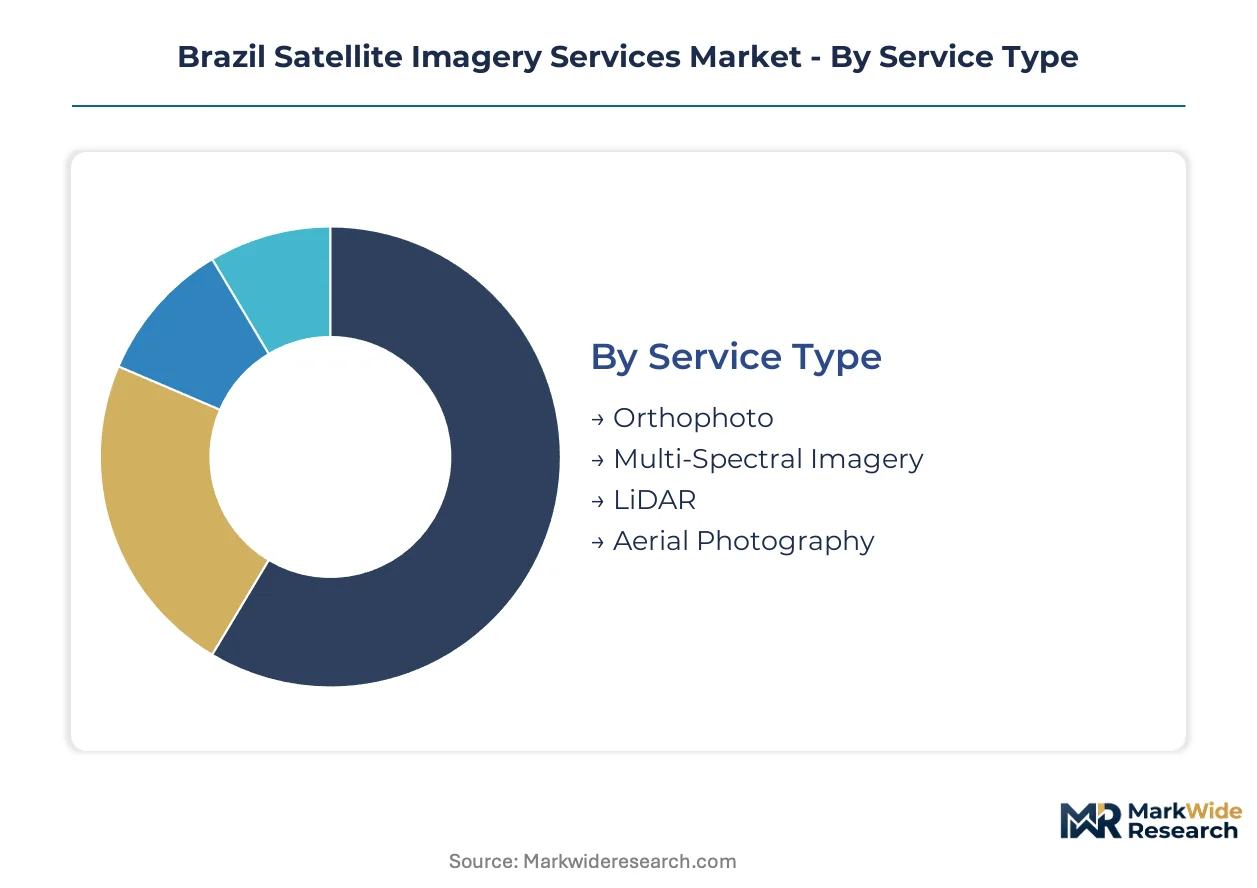
Brazil's satellite imagery market fragments across service delivery modes, end-use verticals, and sensing platforms. Procurement patterns diverge sharply between commodity orthophoto subscriptions and premium analytics tiers. Understanding these segment boundaries clarifies where margin pools concentrate versus where price competition erodes returns.
Service Type:
Use-case spectrum spans from standardized geospatial commodities to bespoke survey-grade deliverables. Cost tier differentiation separates volume buyers from precision-dependent operators.
- Orthophoto:Geometrically corrected aerial imagery with uniform scale, typically delivered at 10-30 centimeter resolution for cadastral mapping. INCRA land regularization programs in Pará and Amazonas states sustain recurring procurement cycles from cooperatives and individual landholders seeking territorial certification.
- Multi-Spectral Imagery:Captures reflected energy across discrete wavelength bands including near-infrared and red-edge, enabling vegetation index calculation. Mato Grosso soy operators deploy normalized difference vegetation index layers for variable-rate nitrogen application during reproductive growth stages.
- LiDAR:Active laser ranging generates high-density point clouds for terrain modeling and canopy structure analysis. ANA watershed management contracts in the Pantanal headwaters drive intermittent demand for bathymetric and floodplain elevation mapping.
- Aerial Photography:Piloted aircraft capture at sub-10 centimeter resolution for engineering-grade corridor mapping. Transmission line operators in Minas Gerais and São Paulo states commission flight campaigns for vegetation encroachment monitoring.
The dominant share belongs to Multi-Spectral Imagery, while Geospatial Analytics (embedded in service delivery) is closing the gap fastest as buyers shift from pixel procurement to prescription-based subscriptions.
End User:
Customer type concentration determines pricing power and contract duration. Volume buyers negotiate enterprise tasking rights; fragmented users absorb premium per-scene pricing.
- Agriculture:Precision agriculture operators and cooperatives constitute the largest addressable demand pool. Federated purchasing through Mato Grosso agricultural federations concentrates negotiating leverage and squeezes traditional value-added reseller margins.
- Urban Planning:Municipal governments and metropolitan regional entities require cadastral updates and informal settlement monitoring. São Paulo and Rio de Janeiro metropolitan procurement cycles align with electoral and budgetary calendars.
- Environmental Monitoring:Federal agencies and hydroelectric concessionaires sustain subscriptions for compliance-driven change detection. ANA's quarterly surface water reporting mandates for Paraná basin dams anchor recurring revenue.
- Defense:Intelligence and border surveillance contracts demand sub-meter resolution with guaranteed revisit latency. Premium pricing reflects security clearance requirements and dedicated orbital tasking priority.
Agriculture commands the largest contract volume, though Environmental Monitoring is expanding most quickly under federal compliance obligation expansion.
Technology:
Supply concentration varies across platform maturity curves. Satellite constellations scale across territory; UAV and ground systems serve point-specific requirements.
- Satellite-Based:Orbital platforms deliver systematic coverage at 30-centimeter to 10-meter resolution depending on sensor class. Foreign constellation dependency exposes Brazilian buyers to currency volatility and data sovereignty constraints.
- UAV:Unpiloted aerial systems capture at sub-5 centimeter resolution for field-scale crop stress mapping. Regulatory fragmentation across state aviation authorities limits cross-border service deployment.
- Geospatial Analytics:Machine learning pipelines convert raw imagery into actionable intelligence layers including yield prediction and deforestation alerts. Talent scarcity in agronomy-remote sensing integration forces providers to train analysts in-house.
- Ground-Based:Terrestrial laser scanning and GPS survey networks provide control point verification for orbital product accuracy assessment. Infrastructure monitoring in dam and mining tailings applications sustains niche demand.
Satellite-Based platforms absorb the majority of contracted value, while Geospatial Analytics climbs the fastest as margin migrates from pixels to prescriptions.
Application:
Maturity differentiation separates established procurement categories from emerging compliance-driven segments. Legacy applications compete on price; newer use cases support premium positioning.
- Disaster Management:Rapid response tasking for flood and landslide damage assessment. Persistent cloud cover over the Atlantic forest biome degrades optical utility during wet-season emergency windows.
- Natural Resource Exploration:Geological structure mapping and mineral prospecting support. Regulatory uncertainty around Amazon protected area boundaries constrains survey permit issuance.
- Infrastructure Development:Corridor planning and construction progress monitoring for transportation and energy projects. Federal concession timelines in the North-South railway expansion sustain medium-term demand visibility.
- Climate Research:Long-term vegetation dynamics and carbon stock estimation for REDD+ baseline establishment. Emerging voluntary carbon market verification protocols are creating audit-grade imagery requirements.
Infrastructure Development holds the largest committed contract backlog, while Climate Research is gaining share fastest under carbon credit verification protocol development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural cooperatives and federal compliance agencies dominate procurement across Brazilian states, with demand clustering in soy-intensive regions and hydroelectric watersheds. State-level procurement patterns diverge sharply between precision agriculture operators and territorial certification programs.
Mato Grosso
Soy and corn operators deploy variable-rate nitrogen prescriptions derived from weekly revisit multi-spectral imagery during reproductive growth windows. INCRA land regularization mandates sustain recurring procurement cycles from cooperatives seeking territorial certification. The state's agricultural federations have consolidated purchasing through shared data lakes, squeezing traditional reseller margins.
São Paulo
Municipal governments commission cadastral updates and informal settlement monitoring for metropolitan regional planning. ANA hydrological monitoring mandates drive quarterly surface water extent reporting for hydroelectric concessions in the Paraná basin. The state's transmission line operators commission aerial photography campaigns for vegetation encroachment monitoring.
Minas Gerais
Precision agriculture adoption lags in the southeastern highland coffee belt, representing untapped subscription volume for frost damage and flowering stage monitoring. ANA watershed management contracts sustain demand for bathymetric and floodplain elevation mapping in the São Francisco river basin. The state's iron ore mining corridors require georeferenced imagery for tailings dam stability monitoring.
Pará
INCRA territorial certification programs sustain recurring procurement from individual landholders and cooperatives in Amazon frontier zones. Federal compliance obligations for REDD+ baseline establishment create demand for deforestation alert systems and change detection audits. The state's hydroelectric concessions on the Tocantins river face compressed timelines for sedimentation assessment submissions.
Rio Grande do Sul
Poultry and swine integrators deploy geospatial analytics for facility siting and environmental compliance documentation. State aviation authority regulatory fragmentation limits cross-border UAV service deployment for field-scale crop stress mapping. The state's rice belt operators represent emerging demand for flooded paddy monitoring through synthetic aperture radar subscriptions.
Brazil Satellite Imagery Services Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement layers. Agricultural federations and federal agencies concentrate negotiating leverage, forcing providers to assemble imagery pipelines from specialized sources rather than bundled end-to-end solutions. Three archetypes dominate: foreign constellation operators with high-revisit optical capabilities, domestic payload developers advancing indigenous electro-optical technology, and geospatial analytics platforms converting raw pixels into prescription-based subscriptions. Competitive moves center on federated procurement platform partnerships and SAR-optical convergence for all-weather monitoring.
Within the foreign constellation tier, Satellogic and Maxar Technologies occupy distinct positioning—Satellogic leveraging Buenos Aires-built microsatellite manufacturing for cost leadership in high-revisit tasking, Maxar anchoring premium defense and intelligence contracts through sub-meter resolution archives. Among domestic developers, Visiona Tecnologia Espacial S.A. represents the indigenous payload capability push as stakeholders weigh foreign dependency against data sovereignty objectives.
| Leading Market Players |
|---|
| Satellogic |
| Airbus Group, Inc. |
| Maxar Technologies |
| Embraer S.A. |
| L3Harris Technologies |
| Planet Labs PBC |
| Telespazio Brasil |
| Embratel Star One |
| Visiona Tecnologia Espacial S.A. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Buenos Aires-built microsatellite manufacturing compresses tasking rates across Brazilian territory, forcing foreign constellation operators to absorb currency volatility while domestic buyers exploit fragmented supplier leverage.
Pricing Analysis
Cost-plus contracts with US dollar indexation dominate enterprise tasking agreements, exposing Brazilian cooperatives to exchange rate risk. Pricing stratifies across premium defense-intelligence tiers, standard agricultural subscriptions, and economy orthophoto bundles. Cost compression in standard tiers intensifies because federated purchasing concentrates buyer negotiating power. Smallholder cooperatives exhibit highest price sensitivity, while defense agencies accept premium latency guarantees.
Supply Chain Analysis
Contract manufacturing concentrates in Argentina's microsatellite assembly facilities and US optical payload foundries. Supply draws from German precision optics, Japanese sensor components, and Canadian ground station hardware. Single-source vulnerability persists in sub-meter resolution satellite bus supply. Distribution runs through regional agricultural federations and federal agency procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward three dominant agricultural federations in Mato Grosso, fragmenting traditional value-added reseller channels and compressing margins across the imagery pipeline.
For Market Incumbents: Entrench position through backward integration into geospatial analytics talent development, addressing agronomy-remote sensing curriculum gaps. Secure dedicated orbital tasking priority with defense agencies as foreign constellation dependency risks escalate. Lock in federated procurement platform partnerships before channel compression accelerates. For New Entrants and Emerging Players: Minas Gerais coffee belt underpenetration offers white-space capture for frost damage and flowering stage monitoring subscriptions. Untapped demand in Rio Grande do Sul rice belt for synthetic aperture radar flooded paddy monitoring represents second entry vector. Pursue cooperative data lake integration as primary go-to-market pathway. For Investors and Strategic Acquirers: Long-term, this sits as a data-sovereignty play because Visiona Tecnologia Espacial's indigenous payload development trajectory determines foreign dependency risk. Acquisition targets should display SAR-optical convergence capabilities and established ANA compliance relationships. Monitor INCRA land regularization program expansion rates as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| SAR-Optical Convergence Partnership | All-weather monitoring capability captures ANA hydrological mandates regardless of Amazon cloud cover. |
| Domestic Payload Capability Investment | Visiona Tecnologia Espacial advancement reduces foreign constellation dependency and currency exposure. |
| Federated Procurement Platform Integration | Direct cooperative relationships bypass traditional reseller margin extraction in Mato Grosso soy belt. |
| Carbon Credit Verification Service Launch | REDD+ baseline imagery demand aligns with emerging voluntary carbon market audit protocols. |
| Geospatial Analytics Talent Acquisition | In-house prescription analyst training addresses agronomy program remote sensing curriculum gaps. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with satellite constellation operators, precision agriculture cooperative managers, ANA hydrological monitoring officers, and INCRA territorial certification specialists; and secondary validation against ANA regulatory filings, INCRA land regularization databases, Brazilian Space Agency policy documents, and agricultural federation procurement records. Bottom-up subscription volume estimates triangulated against top-down market sizing from imagery tasking capacity disclosures.
Forecast inputs span service type segmentation across orthophoto, multi-spectral, and analytics tiers; end-user verticals including agriculture, defense, and environmental monitoring; and technology platforms distinguishing satellite-based from UAV and ground-based systems. CAGRs derive from trajectory analysis of federated purchasing consolidation, SAR sensor deployment timelines, and carbon credit verification protocol maturation. Currency volatility exposure and cloud cover degradation patterns factor as Brazil-specific adjustments.
Practitioners should monitor INCRA land regularization program budget allocations, ANA hydrological framework expansion scope, and Visiona Tecnologia Espacial payload launch schedules for early signals of demand inflection or supply localization. Quarterly review of agricultural federation procurement platform consolidation rates and defense agency foreign dependency risk assessments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Germany Satellite Connectivity Market
Satellite
United Arab Emirates Satellite-Based Earth Observation Market
Satellite
Satellite Photography Service Market
Satellite
Eastern Europe and North Africa Satellite Communication Market
Satellite
Commercial LEO Satellite Market
Satellite
UK Satellite-Based Earth Observation Market
Satellite
Argentina Satellite Imagery Services Market
Satellite
Tactical Satellite Market
Satellite
UK Satellite Imagery Services Market
Satellite
Satellite Connectivity Market
Satellite
Global LEO Satellite Market
Satellite
Satellite Communication Subsystem Market
Satellite
Satellite Backhaul Market
Satellite
EMEA Satellite Antenna Market
Satellite
Nano and Microsatellite Market
Satellite
Optical Satellite Communication Market