
 Europe Small Satellite Market | 2026-2036
Europe Small Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Small Satellite Market Foresight
Multi-source procurement of satellite buses and payloads is consolidating around established European aerospace suppliers. Airbus Defence and Space leverages its integrated manufacturing footprint across France, Germany, and Spain to anchor large constellation programs. Thales Alenia Space competes through dual-use platform designs that bridge civil and defense applications. OHB SE specializes in compact bus architectures that reduce integration timelines for institutional customers.
A small satellite denotes a spacecraft with a wet mass below 500 kilograms, typically constructed from aluminum or carbon-fiber-reinforced polymer structures with standardized form factors measured in units of 10 cm × 10 cm × 10 cm. These platforms serve commercial and governmental operators requiring rapid deployment of distributed sensor networks or communications relays at lower capital intensity than traditional geostationary spacecraft. NanoSats and MicroSats are capturing disproportionate investment flows as operators prioritize constellation density over individual platform capability. Earth Observation applications dominate current procurement volumes, though Technology Demonstration missions are expanding as agencies de-risk next-generation payloads before operational commitment.
ESA procurement rules, EU Space Programme funding mechanisms, and national export control regimes shape market access and platform qualification requirements across member states. REACH compliance for materials and CE marking for ground equipment add layer-specific compliance obligations that filter supplier participation. Stakeholders must track how the EU Green Deal's embodied carbon requirements and the F-Gas Regulation's thermal management constraints propagate into satellite manufacturing specifications and launch service contracting.
Market Dynamics
Platform standardization across the EU Space Programme is compressing supplier qualification timelines while concentrating procurement authority within national space agencies. This structural shift favors vertically integrated manufacturers with established ESA heritage over modular subsystem vendors.
Growth Catalysts
- EU Space Programme funding:Institutional budget allocations for Earth observation constellations are accelerating platform procurement cycles across France, Germany, and the United Kingdom.
- Carbon-fiber-reinforced polymer structures:These materials are reducing wet mass thresholds and enabling higher payload fractions for NanoSat form factors.
- REACH compliance pathways:Harmonized materials certification is reducing re-qualification costs for suppliers operating across multiple member states.
Market Restraints
- Launch capacity concentration:Dependence on a limited set of European launch service providers creates scheduling bottlenecks for constellation deployment timelines.
- F-Gas Regulation constraints:Thermal management system specifications face stricter refrigerant restrictions, complicating propulsion subsystem design.
- Aluminum alloy price volatility:Primary structure material costs fluctuate with energy-intensive smelting input prices, pressuring fixed-price contract margins.
Strategic Opportunities
- Defense-civil dual-use platforms:Thales Alenia Space and comparable suppliers are bridging institutional and military procurement channels through modular bus architectures.
- Technology Demonstration missions:ESA's de-risking programs for next-generation payloads create recurring revenue streams for qualified platform providers.
- Ground equipment CE marking:Standardized certification for earth stations and control systems is opening aftermarket service expansion for bus manufacturers.
Industry Challenges
- Embedded systems engineering talent:Shortages in radiation-hardened electronics design are extending payload integration timelines for institutional customers.
- ESA qualification bureaucracy:Multi-stage review processes for platform heritage status create 18-24 month certification cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Small Satellite Market |
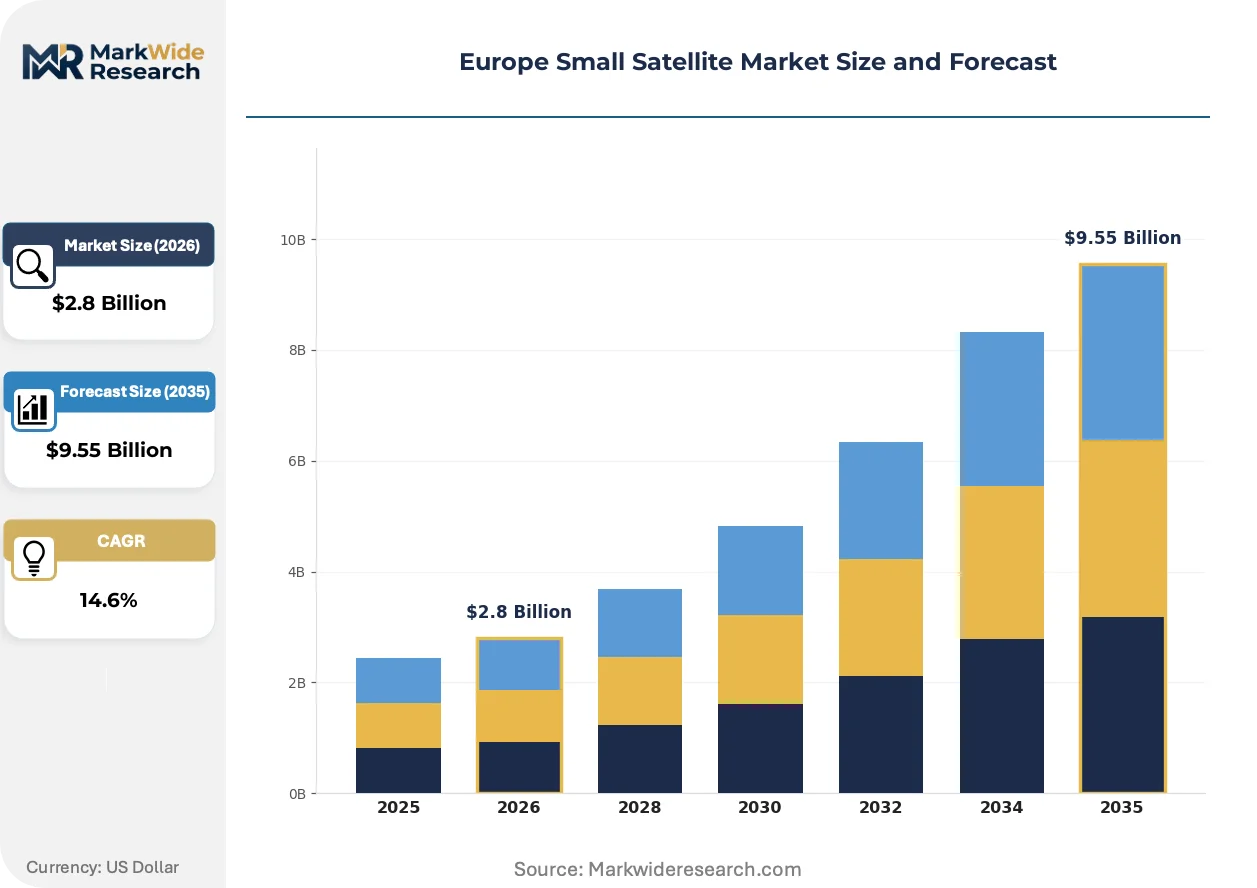
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CubeSats, NanoSats, MicroSats, PicoSats Application: Earth Observation, Communications, Scientific Research, Technology Demonstration End User: Aerospace & Defense, Telecommunications, Government, Academic Institutions Launch Service Type: Dedicated Launch, Rideshare, Piggyback, Small Launch Vehicle |
| Companies Covered | Airbus Defence and Space, Thales Alenia Space, OHB SE, GomSpace, Surrey Satellite Technology Ltd, SatRev, AAC Clyde Space, BAE Systems, Berlin Space Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Small Satellite Market Shifts & Advancements
Constellation-scale deployment is overtaking single-satellite procurement as the dominant demand pattern. This shift is compressing platform design cycles and forcing suppliers to prioritize manufacturing throughput over bespoke engineering.
Standardized CubeSat form factors are overtaking custom microsatellite buses in institutional procurement. French and German space agencies are specifying 10 cm × 10 cm × 10 cm units for distributed sensor networks. This standardization is enabling batch manufacturing economies that custom architectures cannot match.
The EU Green Deal's embodied carbon requirements are propagating into satellite manufacturing specifications. Suppliers must now document lifecycle emissions for aluminum and carbon-fiber structures. French aerospace manufacturers are responding fastest, integrating carbon accounting into ESA tender submissions ahead of formal mandate deadlines.
Institutional buyers are consolidating procurement authority within national space agencies rather than dispersing contracts across research institutes. The United Kingdom's UK Space Agency now centralizes constellation commitments that previously fragmented across university consortia. This concentration is favoring suppliers with established agency relationships and multi-mission platform heritage.
Europe Small Satellite Market Segmentation
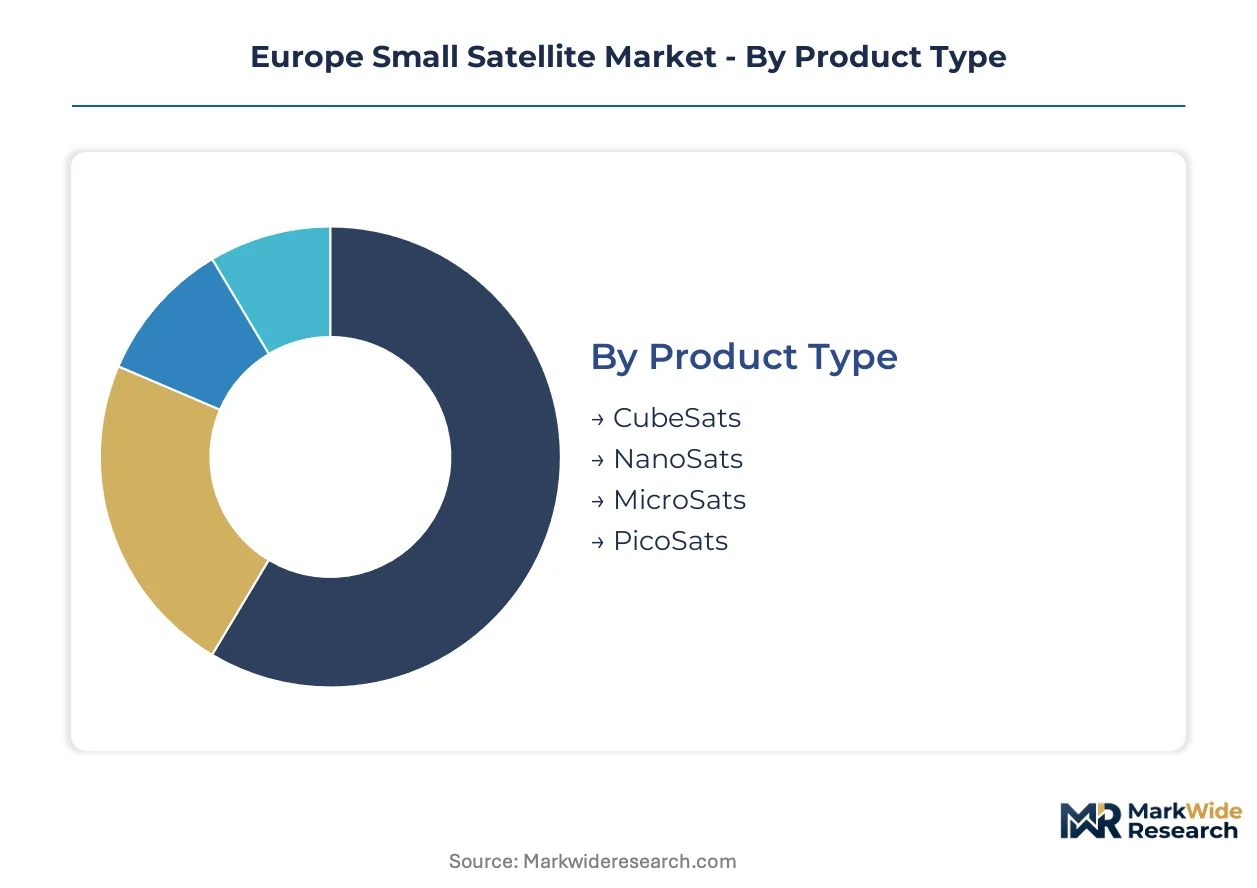
Platform mass thresholds and form factor standardization determine procurement economics across European institutional programs. Each segmentation axis reveals distinct supplier qualification requirements and customer concentration patterns that shape competitive positioning.
Product Type:
Mass-class specifications dictate structural materials, launch integration protocols, and payload capacity trade-offs that filter supplier participation in ESA-funded programs.
- CubeSats:Standardized 10 cm × 10 cm × 10 cm units constructed from aluminum frames or carbon-fiber-reinforced polymer. French and German space agencies specify these for distributed Earth observation constellations requiring rapid batch manufacturing.
- NanoSats:Wet mass between 1-10 kg with expanded payload volume beyond CubeSat constraints. United Kingdom procurement concentrates here for technology demonstration missions that de-risk operational payloads.
- MicroSats:Platforms ranging 10-100 kg enabling multi-sensor configurations. Academic institutions in the Netherlands and Italy favor these for collaborative research consortia.
- PicoSats:Sub-1 kg architectures for minimal mission profiles. Limited commercial uptake; primarily experimental deployments by university programs.
CubeSats lead on scale; NanoSats lead on momentum.
Application:
End-use function determines payload specification, orbital regime selection, and mission lifetime requirements that cascade into platform design priorities.
- Earth Observation:Multi-spectral and synthetic aperture radar payloads demanding precise attitude control. Copernicus program expansion drives procurement concentration across France, Germany, and Italy.
- Communications:Inter-satellite link terminals and store-forward data relay systems. United Kingdom and Luxembourg operators are deploying L-band and V-band payloads for maritime and aeronautical connectivity.
- Scientific Research:Space weather monitoring and cosmic ray detection instruments. ESA's Science Directorate funds these through competitive mission calls.
- Technology Demonstration:De-risking platforms for unproven subsystems before operational commitment. Fastest-expanding category as agencies prioritize heritage accumulation.
Earth Observation commands procurement volume; Technology Demonstration offers the steepest expansion trajectory.
End User:
Customer organizational type shapes contracting mechanisms, payment terms, and platform heritage requirements that filter supplier eligibility.
- Aerospace & Defense:Dual-use platforms with encrypted command links and radiation-hardened avionics. French DGES and German BAAINBw procurement channels favor suppliers with established security clearances.
- Telecommunications:Commercial operators seeking constellation density for broadband service delivery. Regulatory compliance with national spectrum authorities adds certification layers.
- Government:Civil space agencies executing EU Space Programme mandates. Centralized procurement authority within CNES, DLR, and UK Space Agency reduces vendor fragmentation.
- Academic Institutions:University-led missions with simplified qualification requirements. Budget constraints favor rideshare launch arrangements over dedicated services.
Government channels concentrate procurement authority; Aerospace & Defense offers premium pricing power.
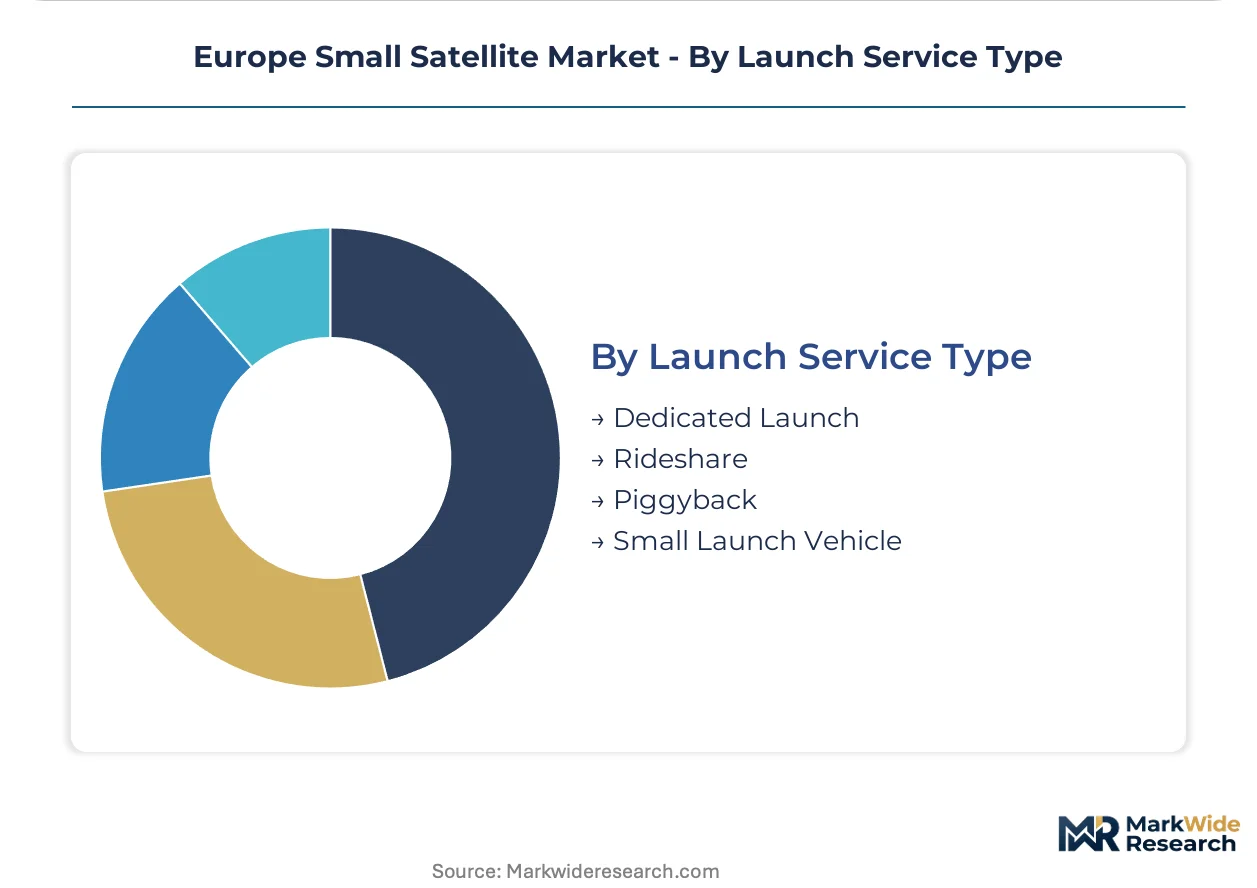
Launch Service Type:
Access-to-orbit modality determines schedule certainty, orbital insertion precision, and cost structure that influence constellation deployment economics.
- Dedicated Launch:Single-customer missions with customized orbital parameters. Institutional buyers in France and Germany specify these for operational constellations requiring precise phasing.
- Rideshare:Aggregated payloads on medium-lift vehicles with standardized deployment interfaces. Cost-sensitive academic and commercial operators dominate demand.
- Piggyback:Secondary payloads on missions with excess capacity. Limited schedule control constrains operational constellation planning.
- Small Launch Vehicle:Purpose-built rockets for sub-500 kg payloads. Emerging providers in the United Kingdom and Germany are qualifying vehicles under ESA oversight.
Rideshare dominates volume; Small Launch Vehicle development attracts the most investment flow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toulouse anchors European small satellite manufacturing through Airbus Defence and Space's integrated production campus. National space agencies in France, Germany, and the United Kingdom are consolidating constellation procurement authority within centralized bodies. REACH compliance and EU Green Deal carbon accounting requirements are reshaping supplier qualification pathways across member states.
France
CNES drives institutional demand through Copernicus expansion and sovereign Earth observation constellations. The F-Gas Regulation constrains thermal management subsystem specifications for propulsion modules. Toulouse and Cannes clusters concentrate Airbus Defence and Space and Thales Alenia Space manufacturing footprints for ESA-qualified platforms.
Germany
DLR procurement concentrates on technology demonstration missions that de-risk operational payloads for institutional buyers. REACH harmonization reduces cross-border materials re-qualification costs for suppliers operating in multiple member states. Bremen and Munich industrial zones host OHB SE and Berlin Space Technologies production facilities serving ESA programs.
United Kingdom
UK Space Agency centralization replaces fragmented university consortium contracting with streamlined constellation commitments. National export control regimes filter platform qualification requirements for dual-use applications. Glasgow and Harwell clusters anchor Surrey Satellite Technology Ltd and AAC Clyde Space manufacturing operations for rideshare-optimized CubeSats.
Italy
ASI funding channels prioritize synthetic aperture radar payloads for Mediterranean maritime surveillance missions. CE marking requirements for ground equipment create aftermarket service expansion opportunities for bus manufacturers. Rome and Turin aerospace districts concentrate Thales Alenia Space satellite integration capabilities.
Poland
SatRev exemplifies emerging European New Space entrants targeting constellation-scale manufacturing for commercial Earth observation operators. EU Space Programme funding mechanisms accelerate platform standardization adoption among newer member state suppliers. Warsaw and Łódź technology parks are attracting venture capital for small satellite subsystem development.
Europe Small Satellite Market Competitive Landscape
Global majors compete with regional champions across platform heritage and ESA qualification timelines. The vendor base stratifies into three tiers: vertically integrated aerospace conglomerates with multi-decade ESA relationships, mid-cap specialists in compact bus architectures, and emerging New Space entrants targeting batch manufacturing economies. Dominant competitive moves include strategic partnerships for launch service integration and portfolio diversification into ground equipment aftermarket services.
Within the heritage-integrated tier, Airbus Defence and Space and Thales Alenia Space exemplify suppliers leveraging cross-border manufacturing footprints to anchor large constellation programs. OHB SE occupies a position among compact bus specialists that reduce integration timelines for institutional customers with constrained mission schedules. These three anchors represent distinct archetypes: the pan-European conglomerate, the dual-use platform bridger, and the rapid-delivery specialist.
| Leading Market Players |
|---|
| Airbus Defence and Space |
| Thales Alenia Space |
| OHB SE |
| GomSpace |
| Surrey Satellite Technology Ltd |
| SatRev |
| AAC Clyde Space |
| BAE Systems |
| Berlin Space Technologies |
| Others |
Supply & Pricing Matrix
Aluminum alloy and carbon-fiber-reinforced polymer feedstock costs cascade through three distinct pricing tiers for European small satellite procurement. CNES and DLR institutional buyers absorb premium pricing for ESA-qualified platforms with multi-mission heritage, while academic consortia and emerging commercial operators cluster at economy tiers optimized for rideshare launch economics.
Pricing Analysis
Input-cost pass-through from energy-intensive aluminum smelting and aerospace-grade carbon-fiber prepreg drives contract pricing volatility for platform manufacturers. Pricing stratifies across ESA-qualified heritage platforms, rapid-delivery compact buses, and batch-manufactured CubeSat units based on certification level and integration timeline. Cost compression in the economy tier intensifies because SatRev and AAC Clyde Space are scaling automated production lines for standardized 10 cm form factors. Academic institutions exhibit highest price sensitivity due to fixed grant funding, while French DGES defense channels accept substantial premiums for encrypted command-link architectures.
Supply Chain Analysis
EU Green Deal local-content requirements and ESA procurement rules are reshaping sourcing patterns toward French, German, and United Kingdom manufacturing clusters. Raw material dependencies center on German aluminum semifabricators, Spanish carbon-fiber composite suppliers, and Dutch radiation-hardened electronics foundries. Single-source vulnerability concentrates in gallium nitride power amplifiers and space-qualified lithium-ion cells. Distribution runs through vertically integrated primes with captive subsystem production, bypassing modular vendor networks for constellation-scale commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Small Satellite Market functions as a stable compounder anchored by ESA's multi-year budgetary commitments for Earth observation infrastructure. Institutional procurement cycles generate predictable revenue streams for qualified suppliers.
For Market Incumbents: Acquire launch service integration capabilities to secure schedule certainty for constellation deployment timelines. Airbus Defence and Space and Thales Alenia Space should consolidate payload adapter manufacturing in-house to reduce dependence on ArianeGroup bottlenecks. OHB SE must extend rapid-delivery platform heritage into UK Space Agency procurement channels before Surrey Satellite Technology Ltd entrenches.
For New Entrants and Emerging Players: Digital-channel routes through ESA's open competitive tender platforms offer lowest barrier to initial contract capture. SatRev should target Polish and Baltic state technology demonstration missions with accelerated delivery commitments. AAC Clyde Space can penetrate Netherlands academic consortia through rideshare-optimized CubeSat bundles with integrated ground station access.
For Investors and Strategic Acquirers: Consolidation pressure builds where ESA qualification timelines exceed 18 months and revenue recognition delays strain mid-cap specialists. Long-term viability favors vertically integrated manufacturers with cross-border production footprints and established security clearances. The signal to watch is UK Space Agency procurement centralization accelerating toward single-source constellation awards.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Heritage Accumulation | ESA qualification status unlocks multi-year Copernicus program revenue streams for French suppliers. |
| Launch Service Integration | Vertical control over payload adapters reduces Ariane 6 scheduling bottlenecks for German constellation operators. |
| Carbon Accounting Certification | EU Green Deal compliance documentation secures preferential scoring in CNES tender evaluations. |
| Dual-Use Platform Bridging | Modular bus architectures capture parallel DGES and BAAINBw procurement channels for Thales Alenia Space. |
| Batch Manufacturing Scale-Up | Automated CubeSat production lines enable SatRev to undercut heritage primes on Polish commercial contracts. |
Research Methodology
Coverage spans France, Germany, United Kingdom, Italy, and Poland, with primary inputs from each national space agency procurement directorate. The analysis combines structured interviews with ESA program managers, platform engineering leads at prime contractors, and ground station operations specialists with secondary validation from ESA budget documents, EU Space Programme implementation reports, and national export control filings. Bottom-up triangulation across platform unit economics and top-down reconciliation against institutional funding allocations anchor volume and value estimates.
Granularity-level modeling disaggregates forecasts by mass class, application function, end-user organization type, and launch service modality across the projection horizon. CAGRs derive from logistic growth curve fitting calibrated to ESA's published constellation deployment schedules and member state budget trajectory assumptions. Industry-specific inputs include F-Gas Regulation compliance cost curves for thermal management subsystems and REACH materials certification timeline distributions.
The model assumes a particular technology adoption path; alternative pathways for electric propulsion miniaturization would alter the outlook for platform wet mass thresholds and launch integration economics. Forecasts reflect embedded assumptions regarding Ariane 6 operational cadence and EU Green Deal mandate enforcement timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
LEO Satellite System Market
Satellite
Global Commercial Satellite Broadband Market
Satellite
Europe Military Satellite Market
Satellite
Europe Satellite Launch Vehicle Market
Satellite
Satellite Photography Service Market
Satellite
Global Satellite Modem Market
Satellite
South Korea Satellite Communication Market
Satellite
Europe Satellite Attitude and Orbit Control System Market
Satellite
Satellite Communication (SATCOM) Market
Satellite
Argentina Satellite-Based Earth Observation Market
Satellite
Middle East Satellite Imagery Services Market
Satellite
North America Satellite Attitude and Orbit Control System Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
Communication Satellite Launch Services Market
Satellite
ASEAN Satellite Imagery Services Market
Satellite
North America Satellite Launch Vehicle Market