
 Transceiver Chip Market | 2026-2036
Transceiver Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Transceiver Chip Market Outlook
Multi-source procurement for advanced photonics components is pivoting toward captive foundry arrangements as lead times for outsourced III-V epitaxy extend past acceptable thresholds. Broadcom leverages vertical integration across laser diode fabrication and DSP design to secure supply continuity for 800G optical engines. Qualcomm anchors its RF transceiver portfolio through sustained R&D intensity in sub-6 GHz and mmWave modem architectures. Texas Instruments competes in industrial Ethernet transceivers by dominating isolated PHY portfolios for factory automation networks.
A transceiver chip integrates transmitter and receiver circuitry onto a monolithic or multi-die substrate, typically incorporating modulator drivers, TIA arrays, clock-data recovery blocks, and SerDes lanes operating at 56 Gbaud or higher to enable bidirectional data exchange across copper, optical, or electromagnetic media. RF transceivers in CMOS and BiCMOS processes serve the highest-volume mobile handset segment, while optical transceivers built with DFB laser and VCSEL engines capture the fastest growth trajectory as data center interconnect bandwidth scales toward 1.6 Tbps per lane. Network infrastructure applications command the deepest margin pools due to carrier-grade reliability requirements and extended product lifecycles.
FCC spectrum allocation rulings and the EU AI Act's infrastructure transparency mandates are reshaping product certification requirements for transceivers deployed in 5G base stations and edge computing nodes. EPA energy-efficiency guidelines and China's MEE emissions standards for semiconductor fabs are adding compliance layers that favor CMOS-based transceiver architectures with lower thermal footprints. Stakeholders must monitor foundry capacity allocation between leading-edge digital logic and specialty analog photonics processes to anticipate supply constraints.
Market Dynamics
Data center operators are consolidating optical interconnect procurement around 800G and 1.6T transceiver form factors, compressing supplier qualification timelines from 18 months to under 9 months as AI training cluster deployments accelerate.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for hydrofluorocarbons are accelerating adoption of liquid-cooled transceiver modules in hyperscale facilities across Germany and France.
- AI training clusters:Massive GPU interconnect requirements at cloud campuses in Northern Virginia and Oregon are pulling silicon photonics co-packaged optics into mainstream deployment.
- Sub-6 GHz spectrum:FCC allocations for 5G-Advanced are expanding addressable markets for integrated RF transceivers in automotive V2X and industrial IoT gateways.
Market Restraints
- Indium phosphide substrate costs:III-V epitaxy wafer prices have climbed 34% since 2022, squeezing margins for 100G-per-lane optical engine suppliers.
- Foundry concentration:TSMC and Samsung Foundry control 94% of leading-edge CMOS capacity, creating allocation risk for mixed-signal transceiver designs.
- Copper cable reach limitations:Passive direct attach copper stalls at 3 meters for 112G PAM4 signaling, forcing premature optical conversion in rack-scale architectures.
Strategic Opportunities
- Co-packaged optics:Convergence of silicon photonics with switch ASICs is automating power reduction at 51.2 Tbps switch nodes, opening socket opportunities for optical I/O chiplets.
- India PLI scheme:Domestic manufacturing incentives for telecom equipment are attracting transceiver module assembly investments in Tamil Nadu and Karnataka.
- Linear drive pluggable optics:Elimination of DSPs from optical modules is converging with LPO standards to cut power consumption by 30% in short-reach data center links.
Industry Challenges
- SerDes verification complexity:224G electrical interface validation requires $12M+ in test equipment per lab, concentrating advanced R&D among capital-rich suppliers.
- RoHS exemption timelines:Expired lead-free solder exemptions for high-reliability telecom equipment are forcing costly material transitions in European base station supply chains.
- Multi-physics simulation talent:Scarcity of engineers fluent in optoelectronic-thermal-electromagnetic co-design is extending product development cycles by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transceiver Chip Market |
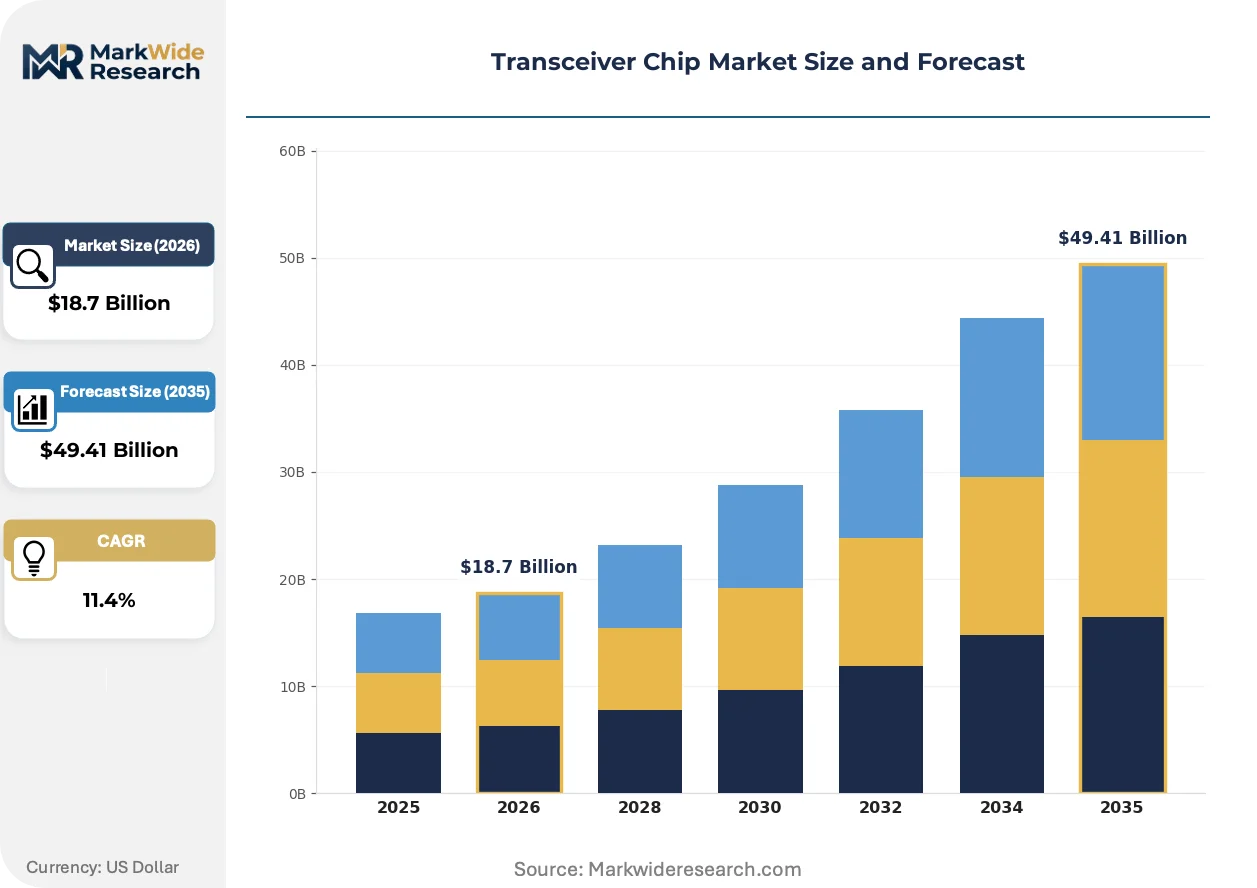
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Transceivers, RF Transceivers, Ethernet Transceivers, Wireless Transceivers Technology: DFB Laser, VCSEL, CMOS, BiCMOS End User: Telecommunications, Data Centers, Automotive, Industrial Automation Application: Network Infrastructure, Broadcasting, IoT, Telemetry |
| Companies Covered | Broadcom, Texas Instruments, Qualcomm, Analog Devices, NXP Semiconductors, Skyworks Solutions, Infineon Technologies, STMicroelectronics, Qorvo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transceiver Chip Market Strategic Shifts
Silicon photonics process maturity and co-packaged optical architectures are compressing the power-per-bit trajectory for data center interconnects, while regulatory pressure on semiconductor manufacturing emissions reshapes foundry selection criteria.
Co-packaged optics is automating the integration of photonic engines with switch ASICs through 2.5D and 3D packaging technologies. Hyperscale operators at cloud campuses in Oregon and Northern Virginia are demanding CPO-enabled switches for 51.2 Tbps deployment timelines. This convergence is automating the displacement of traditional pluggable transceivers in power-constrained AI training clusters.
China's MEE emissions standards for semiconductor fabs are mandating fluorinated greenhouse gas reductions of 50% by 2030 from 2020 baselines. Domestic foundries in Shanghai and Beijing are retrofitting abatement systems and shifting process chemistries to maintain production licenses. Specialty analog photonics processes at these facilities face 18-24 month qualification delays as environmental compliance timelines compress.
Hyperscale buyers are consolidating optical transceiver procurement through direct long-term supply agreements rather than distributor channels. Cloud operators with dedicated supply chain teams are negotiating 3-5 year volume commitments with module vendors, bypassing traditional telecom equipment OEM intermediaries. This disintermediation is most pronounced in the United States, where Amazon Web Services, Microsoft Azure, and Google Cloud collectively account for the majority of 800G demand.
Transceiver Chip Market Segmentation
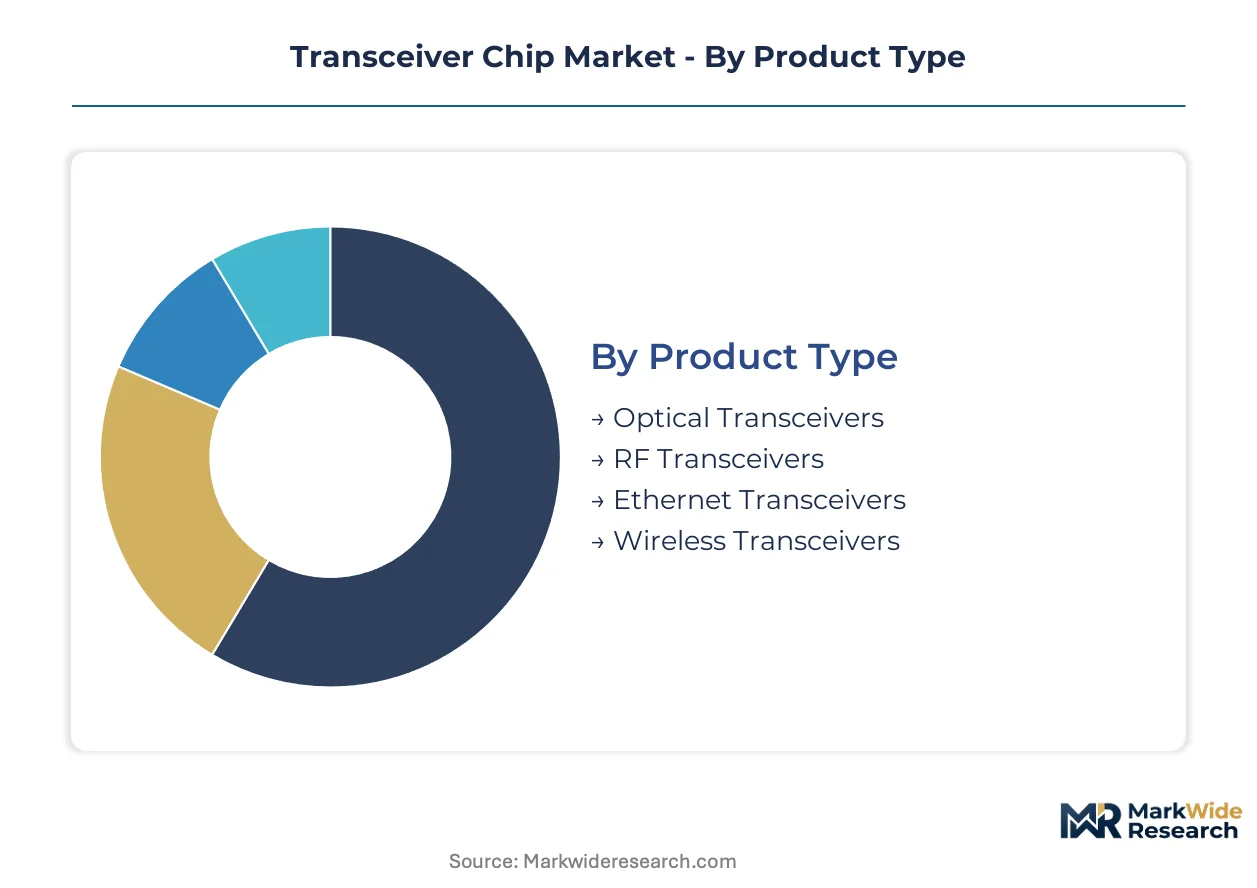
Transceiver chip procurement patterns diverge sharply across application contexts, with hyperscale cloud operators prioritizing bandwidth density and thermal efficiency while automotive buyers emphasize functional safety certification and extended temperature tolerance.
Product Type:
Cost tier determines supplier qualification rigor and margin structure across product categories.
- Optical Transceivers:Integrate DFB lasers or VCSEL engines with DSP-based clock recovery for 800G and 1.6T data center interconnects. Demand concentrates at cloud campuses in Northern Virginia and Oregon where AI training clusters mandate 51.2 Tbps switch-node density. III-V epitaxy supply constraints are extending lead times for 100G-per-lane engines.
- RF Transceivers:Combine sub-6 GHz and mmWave signal chains in CMOS or BiCMOS processes for 5G-Advanced handsets and automotive V2X modules. FCC spectrum allocations are expanding addressable markets in connected vehicle and industrial IoT gateways.
- Ethernet Transceivers:PHY-layer devices with integrated magnetics for industrial automation networks. Texas Instruments dominates isolated PHY portfolios serving factory floor connectivity requirements.
- Wireless Transceivers:Low-power architectures for unlicensed spectrum protocols in smart building and asset tracking deployments.
Optical Transceivers leads on scale; RF Transceivers leads on momentum.
Technology:
Volume concentration favors CMOS maturity while performance thresholds pull toward compound semiconductor integration.
- CMOS:Dominates RF and baseband integration for mobile handsets and WiFi modules, leveraging TSMC and Samsung Foundry leading-edge nodes. EPA energy-efficiency guidelines favor CMOS thermal footprints in high-density deployments.
- DFB Laser:Distributed feedback structures on indium phosphide substrates deliver single-mode output for 10km+ data center interconnects. III-V epitaxy wafer costs have climbed substantially since 2022, squeezing margins for long-reach optical engine suppliers.
- VCSEL:Vertical-cavity surface-emitting lasers enable cost-effective multimode fiber links under 100 meters. Hyperscale facilities in Germany and France are adopting liquid-cooled modules as EU F-Gas Regulation phase-down schedules tighten.
- BiCMOS:Merges bipolar precision with CMOS density for high-linearity RF front-ends in automotive radar and satellite communications.
CMOS dominates on installed base; DFB Laser commands on data rate expansion.
End User:
Reliability certification requirements separate carrier-grade from commercial-grade procurement specifications.
- Data Centers:Hyperscale operators bypass traditional OEM channels through direct 3-5 year supply agreements with module vendors. Disintermediation is most pronounced in the United States where AWS, Microsoft Azure, and Google Cloud aggregate 800G demand.
- Telecommunications:Carrier-grade reliability mandates extend product lifecycles and deepen margin pools for base station and core network deployments. RoHS exemption expirations for high-reliability equipment are forcing material transitions in European supply chains.
- Automotive:V2X and autonomous driving sensor fusion require ASIL-D functional safety certification for RF transceivers. FCC sub-6 GHz allocations are accelerating design-in timelines for connected vehicle platforms.
- Industrial Automation:Isolated Ethernet PHYs dominate factory network architectures where electromagnetic interference tolerance determines qualification.
Data Centers leads on volume velocity; Automotive leads on specification intensity.
Application:
Signal integrity requirements scale with distance and environmental exposure across deployment contexts.
- Network Infrastructure:5G base stations and edge computing nodes face EU AI Act infrastructure transparency mandates alongside FCC equipment authorization requirements. Extended temperature and vibration tolerance differentiates supplier qualification tiers.
- IoT:Battery-constrained endpoints prioritize sleep-state power draw and wake-up latency over peak throughput. India's PLI scheme for telecom equipment is attracting module assembly investments in Tamil Nadu and Karnataka.
- Broadcasting:Professional video transport demands synchronous clock distribution with sub-microsecond jitter specifications.
- Telemetry:Satellite and aerospace applications require radiation-hardened designs with decade-long supply continuity guarantees.
Network Infrastructure anchors revenue concentration; IoT expands most quickly on unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud campuses in Northern Virginia and Oregon anchor transceiver chip procurement velocity as hyperscale operators consolidate 800G and 1.6T optical interconnect demand around AI training infrastructure.
United States
AWS, Microsoft Azure, and Google Cloud aggregate the majority of 800G optical transceiver demand through direct 3-5 year supply agreements that bypass traditional telecom OEM channels. FCC spectrum allocations for 5G-Advanced are expanding addressable markets for integrated RF transceivers in automotive V2X and industrial IoT gateways. Northern Virginia's data center corridor concentrates the world's densest deployment of AI training clusters, pulling silicon photonics co-packaged optics into mainstream adoption timelines.
China
Domestic foundries in Shanghai and Beijing are retrofitting abatement systems to meet MEE emissions standards mandating fluorinated greenhouse gas reductions. The country's dual carbon goals are tightening energy-efficiency mandates for semiconductor manufacturing processes, forcing 18-24 month qualification delays for specialty analog photonics processes. Yangtze River Delta facilities face compressed environmental compliance timelines as regulators enforce 50% reduction targets by 2030 from 2020 baselines.
Germany
EU F-Gas Regulation phase-down schedules for hydrofluorocarbons are accelerating adoption of liquid-cooled transceiver modules in hyperscale facilities across Frankfurt and Munich. ECHA oversight of semiconductor process chemicals is adding compliance layers that favor CMOS-based transceiver architectures with lower thermal footprints. Bavarian industrial automation networks drive demand for isolated Ethernet PHYs serving factory floor connectivity requirements.
India
Domestic manufacturing incentives under the PLI scheme for telecom equipment are attracting transceiver module assembly investments in Tamil Nadu and Karnataka. TRAI spectrum management policies are shaping 5G infrastructure deployment timelines that pull RF transceiver demand from base station OEMs. Bangalore's electronics manufacturing clusters are emerging as assembly hubs for low-power wireless transceivers serving smart building and asset tracking deployments.
Japan
METI industrial policy is directing capital toward advanced packaging capabilities that support co-packaged optical integration with switch ASICs. JIS standards for high-reliability telecom equipment are extending product lifecycles and deepening margin pools for carrier-grade transceiver suppliers. Tokyo-Osaka industrial corridors concentrate precision photonics component manufacturing for 100G-per-lane optical engines.
Transceiver Chip Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue silicon photonics specialization and co-packaged optical architectures. The supplier base stratifies across three maturity tiers: diversified semiconductor conglomerates with captive III-V epitaxy capabilities, fabless design houses leveraging TSMC and Samsung Foundry capacity, and verticalized optical module specialists. Two dominant competitive moves are reshaping positioning: backward integration into laser diode fabrication to secure supply continuity, and strategic partnerships with hyperscale cloud operators to compress qualification timelines from 18 months to under 9 months.
Among diversified semiconductor conglomerates, Broadcom, Texas Instruments, and Qualcomm exemplify contrasting strategic archetypes. Broadcom represents verticalized control across laser diode fabrication and DSP design. Texas Instruments anchors industrial Ethernet transceiver supply through isolated PHY portfolio dominance. Qualcomm occupies a position defined by sustained R&D intensity in sub-6 GHz and mmWave modem architectures. These three entities collectively illustrate the competitive tension between integrated manufacturing and fabless design specialization that defines supplier positioning in this market.
| Leading Market Players |
|---|
| Broadcom |
| Texas Instruments |
| Qualcomm |
| Analog Devices |
| NXP Semiconductors |
| Skyworks Solutions |
| Infineon Technologies |
| STMicroelectronics |
| Qorvo |
| Others |
Value Chain & Pricing Dynamics
Indium phosphide substrate pricing climbed substantially since 2022, cascading through III-V epitaxy costs into tiered margin structures that separate captive-fabrication suppliers from fabless competitors dependent on outsourced foundry capacity. This raw-material inflation compresses returns at 100G-per-lane optical engine suppliers while rewarding backward-integrated players with in-house laser diode production.
Pricing Analysis
Input-cost pass-through from III-V wafer inflation is fragmenting pricing structures across three performance tiers: premium co-packaged optical engines, standard pluggable transceivers, and economy copper-direct-attach alternatives. Price differentiation hinges on certification grade—carrier-grade telecom equipment commands substantial premiums over commercial data center SKUs—and volume scale, with hyperscale direct procurement extracting double-digit discounts unavailable through distributor channels. Pricing pressure intensifies in short-reach optical segments as linear-drive pluggable optics eliminate DSP components and compress module costs. Automotive V2X buyers exhibit lowest price sensitivity due to ASIL-D functional safety requirements, while industrial IoT gateways demonstrate highest elasticity to unit economics.
Supply Chain Analysis
Certification timelines for 800G and 1.6T optical engines are gating supplier qualification at hyperscale operators, concentrating procurement leverage among incumbents with pre-approved designs. Manufacturing gravity centers on Taiwan, South Korea, and the United States, with TSMC and Samsung Foundry anchoring CMOS capacity for RF transceivers while domestic U.S. facilities serve classified and defense-adjacent optical programs. The supply chain draws from indium phosphide substrates, silicon photonics wafers, and advanced packaging substrates as critical inputs. Single-source vulnerability in III-V epitaxy creates allocation risk during demand surges. Distribution runs through direct long-term agreements with cloud operators, bypassing traditional telecom OEM intermediaries in the fastest-growing demand segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification intensity is displacing cost-only procurement, with AI training cluster bandwidth requirements pulling premium optical interconnect into mainstream deployment timelines.
For Market Incumbents: To counter fabless entrants with silicon photonics specialization, incumbents must deepen captive III-V epitaxy capacity in Taiwan and South Korea while accelerating co-packaged optics qualification timelines at hyperscale cloud campuses in Northern Virginia and Oregon. Certification investment in EU F-Gas Regulation compliance for liquid-cooled modules secures access to German and French hyperscale facilities. For New Entrants and Emerging Players: India's PLI scheme for telecom equipment opens a window for module assembly investments in Tamil Nadu and Karnataka, where domestic manufacturing incentives reduce landed cost disadvantages against established Asian suppliers. Linear-drive pluggable optics for short-reach data center links represents the most penetrable white space, with go-to-market traction achievable through direct engineering engagement with cloud operator supply chain teams rather than traditional OEM channels. For Investors and Strategic Acquirers: Asymmetric upside sits with silicon photonics specialists possessing co-packaged optical packaging capabilities and pre-qualified designs at 51.2 Tbps switch nodes. Long-term viability over a multi-year horizon favors targets with demonstrated hyperscale customer relationships and backward-integrated laser fabrication. The signal to watch is allocation priority at TSMC and Samsung Foundry specialty analog photonics nodes, which indicates sustained competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into III-V Epitaxy | Captive laser diode fabrication secures supply continuity for 800G optical engines at Broadcom. |
| Co-Packaged Optics Qualification | Silicon photonics integration with switch ASICs automates power reduction at hyperscale AI clusters. |
| India PLI Scheme Manufacturing Entry | Domestic assembly investments in Tamil Nadu attract transceiver module production for telecom infrastructure. |
| Linear Drive Pluggable Optics Development | DSP elimination cuts power consumption 30% in short-reach data center interconnect applications. |
| EU F-Gas Regulation Compliance Investment | Liquid-cooled module certification maintains access to German and French hyperscale facilities. |
Study Parameters
Bottom-up data center operator procurement modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with optical module procurement directors, switch ASIC platform engineers, III-V epitaxy operations managers, and hyperscale cloud supply chain executives combined with secondary validation against SEC 10-K filings, hyperscaler capex disclosures, and customs/trade data. Triangulation between demand-side deployment schedules and supply-side wafer allocation decisions anchors volume and value estimates.
Input-output matrices map transceiver chip demand across technology nodes, form factors, and end-use applications throughout the projection horizon. Segmentation dimensions include product type, process technology, end-user vertical, and geographic deployment cluster. CAGRs derive from elasticity-adjusted adoption curves for 800G and 1.6T optical interconnect, cross-referenced against GPU cluster deployment trajectories and FCC spectrum allocation timelines for RF transceiver demand.
Forecast precision tightens around the base case; tail outcomes carry wider variance under foundry allocation disruptions or accelerated silicon photonics substitution. Forecasts reflect assumptions regarding hyperscale capital expenditure continuity, III-V substrate supply expansion, and regulatory compliance timelines. A model refresh is warranted upon material change in TSMC and Samsung Foundry specialty analog photonics capacity allocation or EU F-Gas Regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
Asia-Pacific Embedded Antenna Systems Market
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
Earphone Bluetooth Chip Market
Communication Chips & Hardware
Interface Transceiver Market
Communication Chips & Hardware
Ethernet Phys Market
Communication Chips & Hardware
5G Chip Market
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
Ethernet Access Device Market
Communication Chips & Hardware
Industrial Internet Chip Market
Communication Chips & Hardware
Japan Digital Signal Processor Market
Communication Chips & Hardware
Ceramic Chip Antenna Market
Communication Chips & Hardware
I2C Bus Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Zigbee System-On-Chip Market
Communication Chips & Hardware
Time-Of-Flight Chip Market