
 Global Diphtheria Vaccine Market | 2026-2036
Global Diphtheria Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diphtheria Vaccine Market Foresight
Long-term supply contracts for cold-chain maintenance and vial monitoring services is rebalancing how vaccine procurement contracts are structured. Serum Institute of India leverages its Pune manufacturing campus to anchor large-volume DTaP supply for UNICEF tenders. Sanofi sustains differentiated positioning through its pediatric combination portfolio across European and African markets. Merck & Co., Inc. competes in the North American Tdap booster segment with established hospital pharmacy channels.
A diphtheria vaccine is a toxoid preparation derived from formaldehyde-inactivated Corynebacterium diphtheriae exotoxin, adsorbed onto aluminum salts to enhance immunogenicity, administered intramuscularly to induce antitoxin antibodies that neutralize circulating toxin during infection. Its primary purpose is preventing diphtheria mortality and morbidity through population-level immunization, with combination formulations serving as the backbone of national immunization schedules worldwide. The DTaP and combination vaccine segments dominate procurement volumes due to their integration into pediatric protocols across developing nations, while Tdap boosters for adolescents and adults represent a faster-growing margin pool in mature markets. Government supply channels handle the majority of volume, though retail pharmacy distribution is expanding for travel medicine and occupational health applications.
FDA lot-release testing, WHO prequalification, and EMA batch verification frameworks collectively determine market access for diphtheria vaccine manufacturers, with each regulator imposing distinct potency and stability requirements that filter the supplier base. India's CDSCO and China's NMPA maintain parallel national standards that shape regional procurement eligibility for domestic producers such as Bharat Biotech and China National Biotec. Stakeholders must monitor evolving prequalification criteria for thermostable formulations and single-dose presentations, as these specifications will determine which manufacturers retain tender eligibility in the highest-volume markets.
Market Dynamics
Cold-chain infrastructure gaps and WHO prequalification barriers are concentrating procurement power among manufacturers with validated thermostable formulations and integrated distribution networks.
Growth Catalysts
- GAVI Alliance funding cycles:Multi-year immunization financing is locking in procurement volumes for low-income countries expanding their national schedules.
- India:Domestic manufacturing scale and CDSCO alignment with WHO standards are positioning Indian suppliers as anchor tenders for UNICEF and PAHO.
- Controlled-temperature chain (CTC) protocols:WHO-approved CTC labeling is reducing field wastage rates and extending reach to remote clinics lacking standard cold-chain equipment.
Market Restraints
- Aluminum adjuvant supply concentration:Three chemical suppliers control global pharmaceutical-grade aluminum salt production, creating input bottlenecks during demand surges.
- WHO prequalification timelines:Average eighteen-month review cycles for new combination formulations delay market entry for second-tier manufacturers.
- Tetanus-diphtheria (Td) substitution in adult programs:Lower-margin Td presentations displace Tdap in cost-constrained national budgets, compressing revenue per dose.
Strategic Opportunities
- Nigeria:Population growth and Gavi transition status are expanding the addressable birth cohort for pentavalent and hexavalent combinations.
- Single-dose vial presentations:WHO prequalification for preservative-free unit-dose formats opens tender eligibility for clinics with limited multi-dose cold storage.
- Digital vaccine vial monitors (VVMs) plus electronic logistics:Integration of visual heat exposure indicators with national immunization information systems is enabling outcome-based supplier contracts.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation-scale toxoid production expertise concentrates at legacy institutes, constraining workforce expansion for new market entrants.
- Legacy equipment integration:Batch potency testing protocols require specialized animal facilities that conflict with modern in-vitro assay upgrades, complicating facility retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diphtheria Vaccine Market |
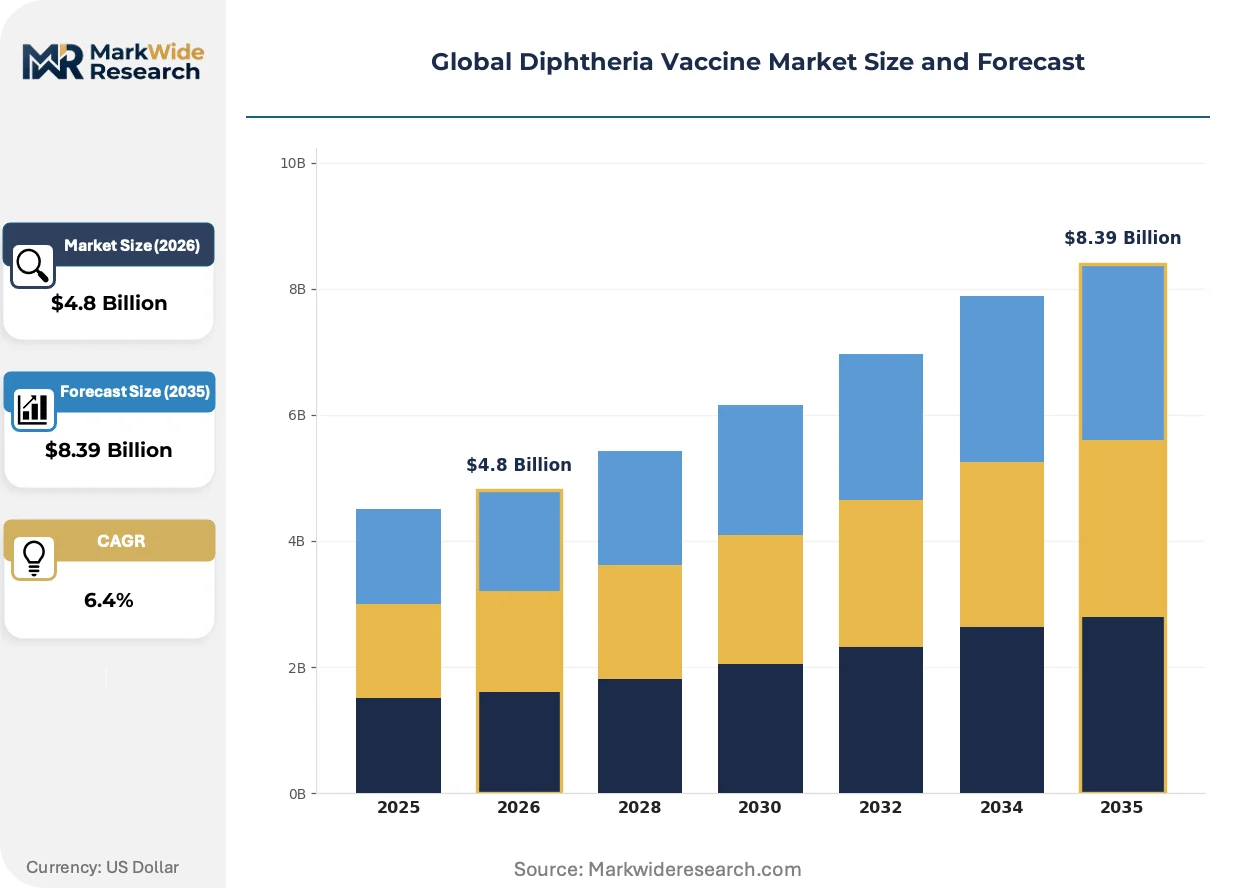
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: DTaP, Td, Tdap, Monovalent Diphtheria, Combination Vaccines Application: Immunization Programs, Outbreak Control, Travel Medicine, Adult Boosters, Pediatric Vaccination End User: Public Health Clinics, Private Hospitals, Immunization Centers, Occupational Health Providers, Pediatric Clinics Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Government Supply, Online Pharmacies, Wholesale Distributors |
| Companies Covered | Serum Institute of India Pvt. Ltd., Bharat Biotech, Merck & Co., Inc., Japan BCG Lab, China National Biotec, Sanofi, Pfizer, Panacea Biotec, GlaxoSmithKline plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diphtheria Vaccine Market Shifts & Advancements
Formulation science and distribution technology are converging to reshape how diphtheria toxoid products reach end-users, with stability engineering and data-enabled logistics emerging as the primary vectors of competitive differentiation.
Thermostable lyophilized toxoid formulations are expanding into field conditions previously inaccessible to standard liquid presentations. National programs in sub-Saharan Africa are piloting these products in clinics with intermittent refrigeration. This technology is expanding into the last-mile distribution tier, compressing the cold-chain capital burden on ministries of health.
WHO prequalification requirements for controlled-temperature chain labeling are tightening potency verification standards for combination vaccines. EMA batch release protocols are converging with these standards, creating unified testing burdens for suppliers serving both European and developing markets. Manufacturers with existing CTC-validated portfolios are capturing tender preference in Nigeria and Pakistan procurement cycles.
Long-term service contracts for cold-chain equipment maintenance and stock monitoring are displacing transactional vial-only purchasing in Gavi-eligible countries. UNICEF Supply Division is bundling vaccine procurement with temperature logger deployment and remote inventory tracking. This model is most visible in India, where domestic manufacturers are integrating logistics subsidiaries to capture full-stack contract value.
Global Diphtheria Vaccine Market Segmentation
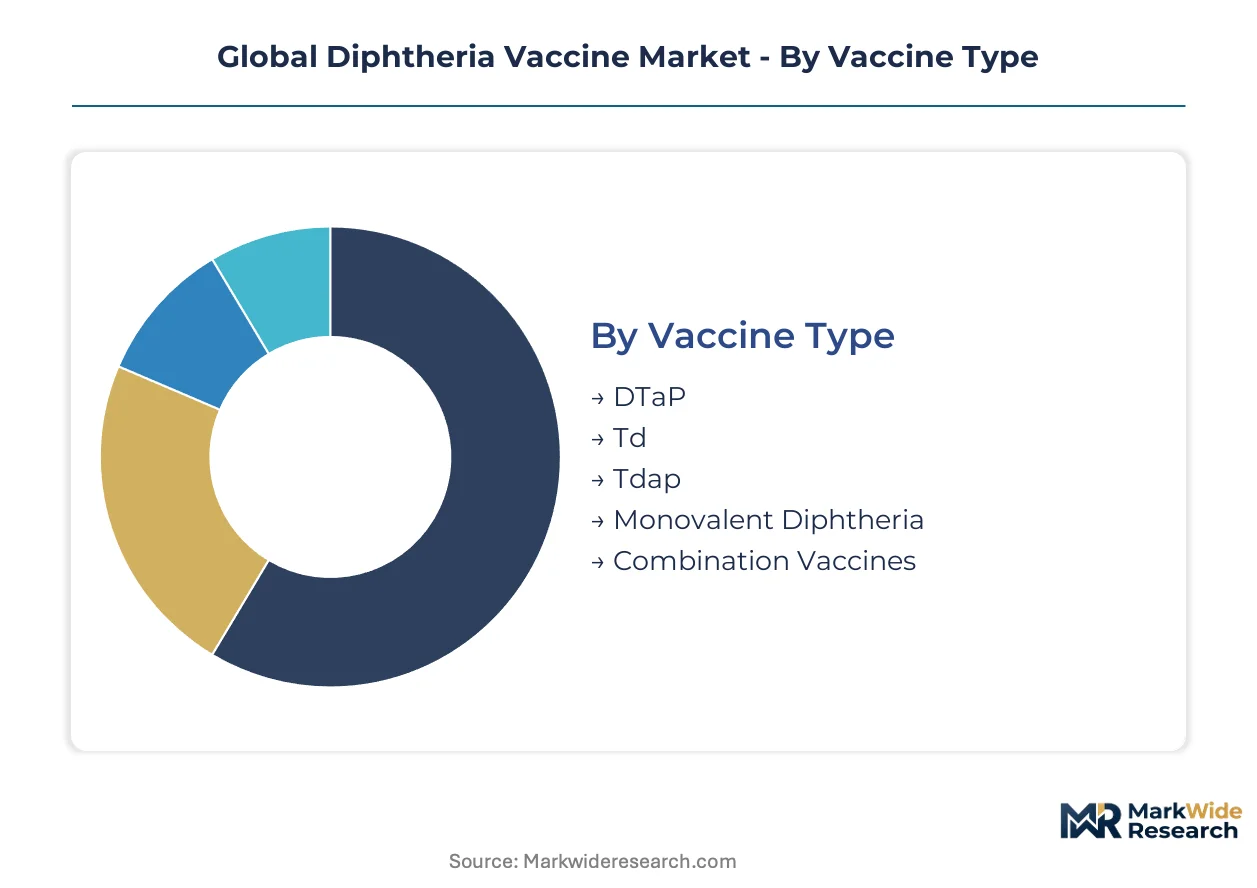
Diphtheria vaccine procurement splits sharply between high-volume pediatric combinations and lower-volume adult boosters. Manufacturers configure production lines around this bifurcation. Tender structures and cold-chain requirements differ materially across each segment.
Vaccine Type:
Volume concentration in pediatric combinations contrasts with premium pricing in specialized adult formulations.
- DTaP:Trivalent toxoid preparation adsorbed onto aluminum phosphate delivers diphtheria, tetanus, and acellular pertussis immunization in single administration. Demand concentrates in India's national immunization schedule and Nigeria's pentavalent expansion programs, driven by GAVI procurement cycles locking in multi-year volumes.
- Combination Vaccines:Pentavalent and hexavalent presentations integrate DTaP with hepatitis B, Hib, or inactivated polio components. Procurement in Pakistan and Ethiopia favors these formats to reduce injection burden and cold-chain footprint, constrained by WHO prequalification bottlenecks for new formulations.
- Tdap:Reduced-dose pertussis formulation for adolescent and adult boosters commands higher per-dose margins in US and European retail channels.
- Td:Tetanus-diphtheria dual toxoid serves adult revaccination programs where cost constraints exclude pertussis components.
- Monovalent Diphtheria:Single-antigen presentation retains niche use in outbreak response stockpiles and specialized immunization protocols.
Today's leader: Combination Vaccines. Tomorrow's challenger: Tdap.
Application:
Programmatic scale in routine immunization diverges from episodic demand in outbreak and travel segments.
- Immunization Programs:National schedule integration drives procurement through UNICEF and PAHO tender mechanisms. India's Universal Immunization Programme anchors regional volume with state-level cold-chain distribution.
- Pediatric Vaccination:Birth-dose and booster protocols in sub-Saharan Africa define the addressable cohort. Nigeria's expanding hexavalent coverage and Ethiopia's outreach clinic network concentrate demand growth, limited by field wastage rates in remote settings.
- Adult Boosters:Decennial revaccination protocols in North America and Western Europe sustain replacement demand through occupational health and pharmacy channels.
- Outbreak Control:Ring vaccination deployments and mass prophylaxis campaigns generate surge procurement from strategic stockpiles.
- Travel Medicine:Pre-departure immunization for endemic-region travel supports retail pharmacy distribution in urban centers.
Immunization Programs capture current procurement value. Pediatric Vaccination climbs the fastest trajectory as birth cohorts expand in GAVI transition countries.
End User:
Public procurement channels dominate volume while private delivery points capture margin.
- Public Health Clinics:Government-funded primary care facilities administer routine pediatric doses through national cold-chain networks in India and Nigeria.
- Immunization Centers:Dedicated vaccination facilities in Brazil and Indonesia handle campaign-style delivery and catch-up schedules.
- Private Hospitals:Fee-for-service delivery in urban India and South Africa serves insured populations seeking combination products outside public schedules.
- Pediatric Clinics:Specialist practices in US metropolitan markets coordinate DTaP with other childhood immunizations.
- Occupational Health Providers:Corporate and institutional programs manage adult Tdap and Td boosters for healthcare and laboratory workers.
Public Health Clinics anchor present volume. Private Hospitals gain share fastest as insurance penetration deepens in middle-income markets.
Distribution Channel:
Government supply centralization conflicts with retail pharmacy expansion in mature markets.
- Government Supply:Centralized procurement through national immunization programs and multilateral agencies handles bulk tender fulfillment. India's state-level vaccine depots and Nigeria's zonal stores exemplify this channel's cold-chain integration requirements.
- Hospital Pharmacies:Institutional purchasing in US health systems and European hospital networks manages inpatient and outpatient administration.
- Wholesale Distributors:Regional logistics providers bridge manufacturers to immunization centers in Brazil and Southeast Asia.
- Retail Pharmacies:Community pharmacy access expands for adult boosters and travel medicine in North American and European urban markets.
- Online Pharmacies:Digital procurement platforms emerge for occupational health bulk purchasing and travel clinic pre-booking.
Government Supply commands current procurement volume. Hospital Pharmacies represent the steepest expansion trajectory as institutional purchasing consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's manufacturing scale contrasts with Nigeria's procurement volume expansion, while the United States and Germany anchor mature-market booster demand and Brazil consolidates Latin American supply integration.
India
Domestic toxoid production capacity and CDSCO regulatory alignment with WHO standards position Indian suppliers as anchor tender winners for UNICEF and PAHO procurement cycles. The Pune manufacturing corridor hosts fermentation-scale facilities serving pentavalent and hexavalent combination programs. Serum Institute of India's campus operations exemplify integrated supply chain control from bulk toxoid to finished vial distribution.
Nigeria
Birth cohort expansion and Gavi transition financing are accelerating hexavalent vaccine adoption across national immunization schedules. Federal Ministry of Health procurement reforms emphasize zonal cold-chain infrastructure upgrades. Lagos and Abuja distribution hubs handle surge volumes for northern state outreach campaigns, with wastage reduction protocols driving CTC-labeled product preference.
United States
Decennial adult revaccination protocols and occupational health mandates sustain Tdap replacement demand through hospital pharmacy channels. FDA lot-release testing requirements filter supplier eligibility to established manufacturers with validated potency assays. The Southeast regional distribution network connects CDC stockpile reserves to metropolitan health systems managing travel medicine and booster administration.
Germany
EMA batch verification frameworks and pediatric combination portfolio demand sustain differentiated supplier positioning across European tender mechanisms. Bavaria-based biologics manufacturing clusters coordinate toxoid supply for regional combination vaccine production. Berlin and Frankfurt distribution nodes manage cross-border hospital pharmacy procurement for Central European immunization programs.
Brazil
PAHO pooled procurement participation and national immunization schedule integration concentrate demand for pentavalent presentations through Ministry of Health tenders. São Paulo and Rio de Janeiro immunization centers anchor regional distribution networks reaching Amazon basin outreach clinics. ANVISA regulatory convergence with WHO prequalification standards is accelerating market access for validated thermostable formulations.
Global Diphtheria Vaccine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated supply for high-volume pediatric combinations contrasting fragmented positioning in travel medicine and outbreak response niches. Three archetypes dominate: integrated toxoid producers with captive fermentation capacity, combination vaccine specialists leveraging formulation science differentiation, and regional fill-finish contractors serving national immunization programs. Capacity expansion in controlled-temperature chain validation and strategic partnerships for aluminum adjuvant security represent the primary competitive vectors reshaping procurement eligibility.
Within the integrated manufacturing tier, Serum Institute of India Pvt. Ltd. and Sanofi exemplify scale-driven positioning anchored by multi-product campus operations and established WHO prequalification portfolios. Bharat Biotech occupies a specialist position representing CDSCO-aligned domestic producers competing for regional tender share. Merck & Co., Inc. anchors the North American booster segment archetype, with hospital pharmacy channel access distinguishing mature-market positioning from procurement-driven volume plays.
| Leading Market Players |
|---|
| Serum Institute of India Pvt. Ltd. |
| Bharat Biotech |
| Merck & Co., Inc. |
| Japan BCG Lab |
| China National Biotec |
| Sanofi |
| Pfizer |
| Panacea Biotec |
| GlaxoSmithKline plc. |
| Others |
Supply & Pricing Matrix
WHO prequalification for controlled-temperature chain labeling gates both qualified supply and premium-tier pricing access, as manufacturers without validated thermostable formulations face exclusion from UNICEF tenders while CTC-validated portfolios command tender preference in Nigeria and Pakistan procurement cycles.
Pricing Analysis
Capacity additions in India are reshaping price floors for pentavalent and hexavalent combinations, with Serum Institute of India's Pune campus operations enabling economies of scale that compress per-dose economics for GAVI-eligible procurement. Three-tier pricing structure across WHO-prequalified, CDSCO-aligned domestic, and non-prequalified imports separates tender-eligible from secondary-market supply. Cost compression in adult Tdap boosters is intensifying because tetanus-diphtheria substitution in cost-constrained national budgets displaces higher-margin presentations. Government supply channels exhibit highest price sensitivity; private hospital channels in urban India and South Africa show lowest sensitivity due to insurance-backed fee-for-service delivery.
Supply Chain Analysis
Direct-to-government supply channels handle bulk tender fulfillment, with India's state-level vaccine depots and Nigeria's zonal stores exemplifying cold-chain integration requirements for national immunization programs. Manufacturing concentrates in India, China, and France, with fermentation-scale toxoid production anchored at legacy institutes constraining workforce expansion. Aluminum phosphate adjuvant, pharmaceutical-grade formaldehyde, and specialized animal-derived media draw from three chemical suppliers controlling global pharmaceutical-grade aluminum salt production. Single-source vulnerability in aluminum adjuvant inputs creates bottlenecks during demand surges. Distribution runs through government supply centralization in developing markets and hospital pharmacy networks in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge from the cost differential between India's CDSCO-aligned manufacturing scale and the regulatory compliance burden facing European producers seeking WHO prequalification for thermostable formulations.
For Market Incumbents: Lock in long-term service contracts for cold-chain equipment maintenance and stock monitoring that displace transactional vial-only purchasing, while securing captive supply of aluminum adjuvant through backward integration into chemical inputs to defend against input bottlenecks during GAVI funding cycle surges. For New Entrants and Emerging Players: Enter via Nigeria's Gavi transition status and expanding hexavalent coverage, where federal procurement reforms and zonal infrastructure upgrades create white-space for CTC-labeled product tenders; target single-dose vial presentations for clinics with limited multi-dose cold storage as the most penetrable format segment. For Investors and Strategic Acquirers: Roll-up economics work for regional fill-finish contractors with validated WHO prequalification pathways because CDSCO-EMA regulatory convergence is accelerating market access for thermostable formulations across European and developing markets. Fermentation-scale toxoid production expertise concentrates at legacy institutes, creating acquisition scarcity value. Watch GAVI transition country procurement volume inflections as the signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Investment | CTC-label validation unlocks UNICEF tender eligibility in Nigeria and Pakistan procurement cycles. |
| Aluminum Adjuvant Security | Backward integration into chemical inputs buffers against three-supplier concentration risk. |
| Single-Dose Vial Development | Preservative-free unit-dose formats open tender eligibility for remote clinics with limited cold storage. |
| Digital VVM Integration | Electronic logistics integration with national immunization systems enables outcome-based supplier contracts. |
| Fermentation Capacity Expansion | Pune corridor scale operations anchor pentavalent supply for GAVI multi-year financing cycles. |
Research Methodology
Direct dialogue with vaccine development executives, regulatory affairs leads at CDSCO and EMA, UNICEF supply division procurement managers, and national immunization program coordinators grounded qualitative insights. Secondary validation drew from WHO prequalification listings, FDA lot-release documentation, EMA batch verification records, and GAVI funding cycle disclosures. Bottom-up tender volume analysis and top-down immunization schedule coverage modeling were triangulated against manufacturer capacity disclosures.
Segment-level outputs across vaccine type, application, end user, and distribution channel were generated through the projection horizon. CAGRs were derived from birth cohort expansion trajectories in Gavi transition countries and replacement demand patterns in mature-market booster protocols. Modeled inputs included CDSCO-WHO regulatory alignment timelines, CTC validation adoption curves, and aluminum adjuvant supply elasticity assumptions.
Inputs from WHO prequalification databases and national immunization program procurement disclosures were available through the study window; gaps in real-time cold-chain infrastructure deployment data introduce uncertainty bands around last-mile distribution reach assumptions. Forecasts reflect documented assumptions regarding GAVI financing continuity and regulatory convergence timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Ceftriaxone Sodium (API) Market
Pharmaceuticals
North America Analgesics Market
Pharmaceuticals
US External Analgesics Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
Mtor Inhibitors Market
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Performance Enhancing Drugs Market
Pharmaceuticals
Veterinary Active Pharmaceutical Ingredients Manufacturing Market
Pharmaceuticals
Global Rx to OTC Switches Market
Pharmaceuticals
Analgesics Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Global Pharmaceutical Traceability Market