
 Fanfold Market | 2026-2036
Fanfold Market Size, Share, and Industry Trends Forecast 2026-2036
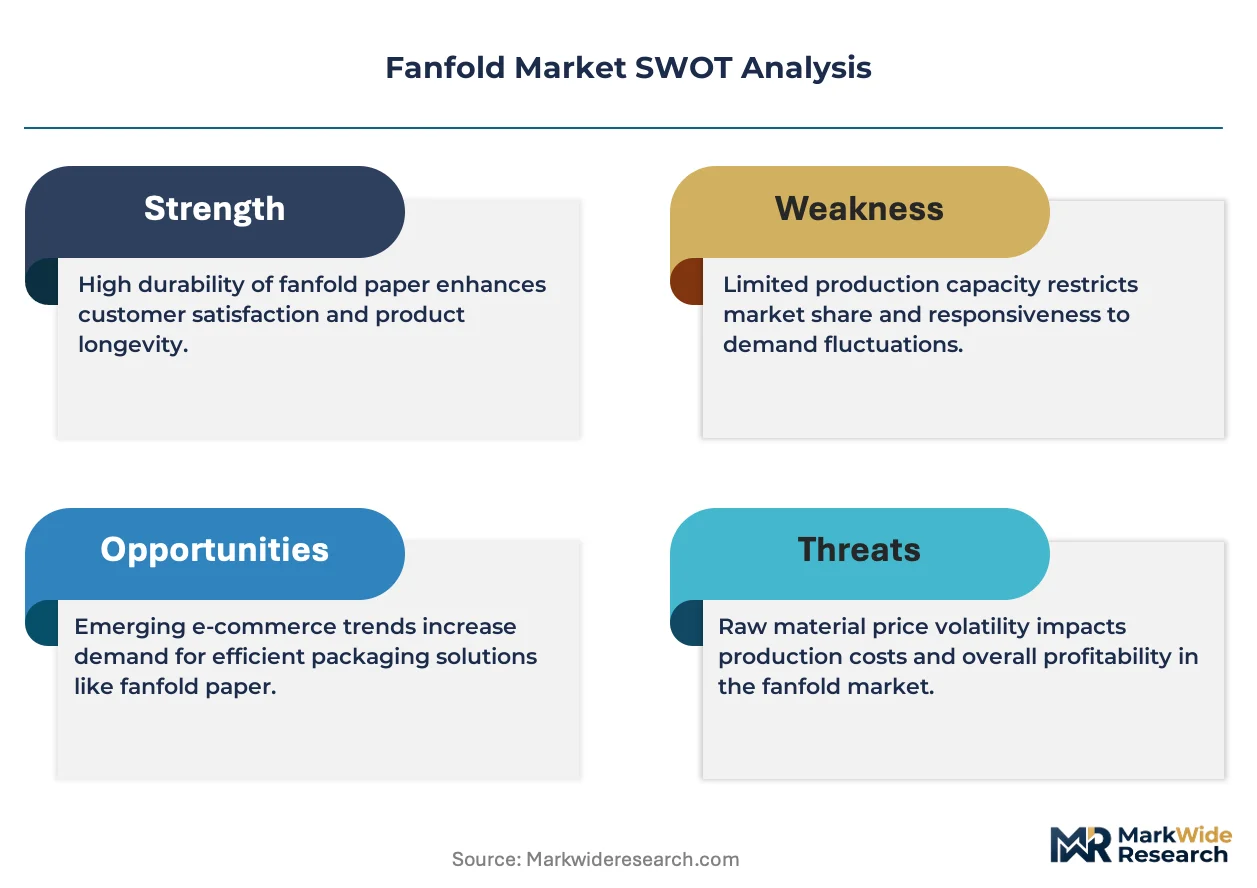
Fanfold Market Analysis
Subscription-based packaging optimization software is consolidating how fanfold buyers manage inventory turnover and cut waste. International Paper leverages its North American mill network to sustain supply continuity for high-volume e-commerce accounts. Smurfit Kappa anchors European demand through integrated corrugated operations spanning multiple countries. Pratt Industries differentiates by controlling recycled fiber supply from its own material recovery facilities.
Fanfold consists of continuous corrugated board scored and folded in alternating directions, typically manufactured in flute profiles from E-flute to C-flute with basis weights between 125 and 350 grams per square meter, designed for on-demand box-making and void-fill applications. Blank fanfold dominates volume shipments to automated packaging stations in manufacturing plants and logistic companies, where standard dimensions reduce changeover downtime. Custom fanfold commands margin premiums from retail stores requiring branded print surfaces and exact-fit dimensions for fragile goods. Recycled material grades are gaining share as mills improve fiber recovery rates without sacrificing board stiffness.
The EPA regulates corrugated medium emissions under Clean Air Act standards, while the EU Green Deal's packaging waste directives mandate minimum recycled content thresholds that reshape fiber procurement across export-oriented mills. OSHA guidelines for ergonomic material handling influence fanfold roll weights and dispensing equipment design in US warehouse environments. Stakeholders must weigh virgin fiber price volatility against recycled stream quality consistency when committing to multi-year supply agreements.
Market Dynamics
Automated packaging lines in e-commerce fulfillment centers are compressing lead times and forcing fanfold suppliers to synchronize mill output with real-time box demand signals. This operational shift is restructuring procurement relationships between corrugated producers and logistics operators.
Growth Catalysts
- EU Green Deal packaging waste directives:Mandated recycled content thresholds are pulling investment into fiber recovery infrastructure across export-oriented mills.
- On-demand box-making systems:Manufacturing plants and logistics companies are retrofitting warehouse floors with fanfold dispensing equipment to eliminate pre-formed box inventory.
- Germany's corrugated packaging clusters:Concentrated production capacity around Central European distribution networks is shortening delivery radiuses for just-in-time fulfillment.
Market Restraints
- Recycled fiber quality inconsistency:Contamination rates in municipal recovery streams limit high-grade fanfold output without virgin pulp blending.
- Supply concentration in German mill networks:Central European production dominance creates vulnerability to energy price spikes and logistics bottlenecks.
- Pre-formed corrugated box substitution:Legacy packaging buyers in low-SKU retail operations resist capital investment in automated fanfold systems.
Strategic Opportunities
- Extended producer responsibility expansion:State-level EPR laws in the US are creating compliance-service revenue streams for integrated fiber recovery operators.
- Subscription-based packaging optimization software:Inventory turnover analytics are opening recurring revenue models alongside physical fanfold supply.
- Branded print surfaces for retail:Custom fanfold with direct-to-corrugate graphics is penetrating specialty retail channels requiring exact-fit fragile goods protection.
Industry Challenges
- Ergonomic material handling compliance:OSHA guidelines for warehouse roll weights are constraining fanfold roll dimensions and requiring redesigned dispensing equipment.
- Multi-year supply agreement rigidity:Virgin fiber price volatility against fixed recycled stream contracts complicates margin forecasting for procurement teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fanfold Market |
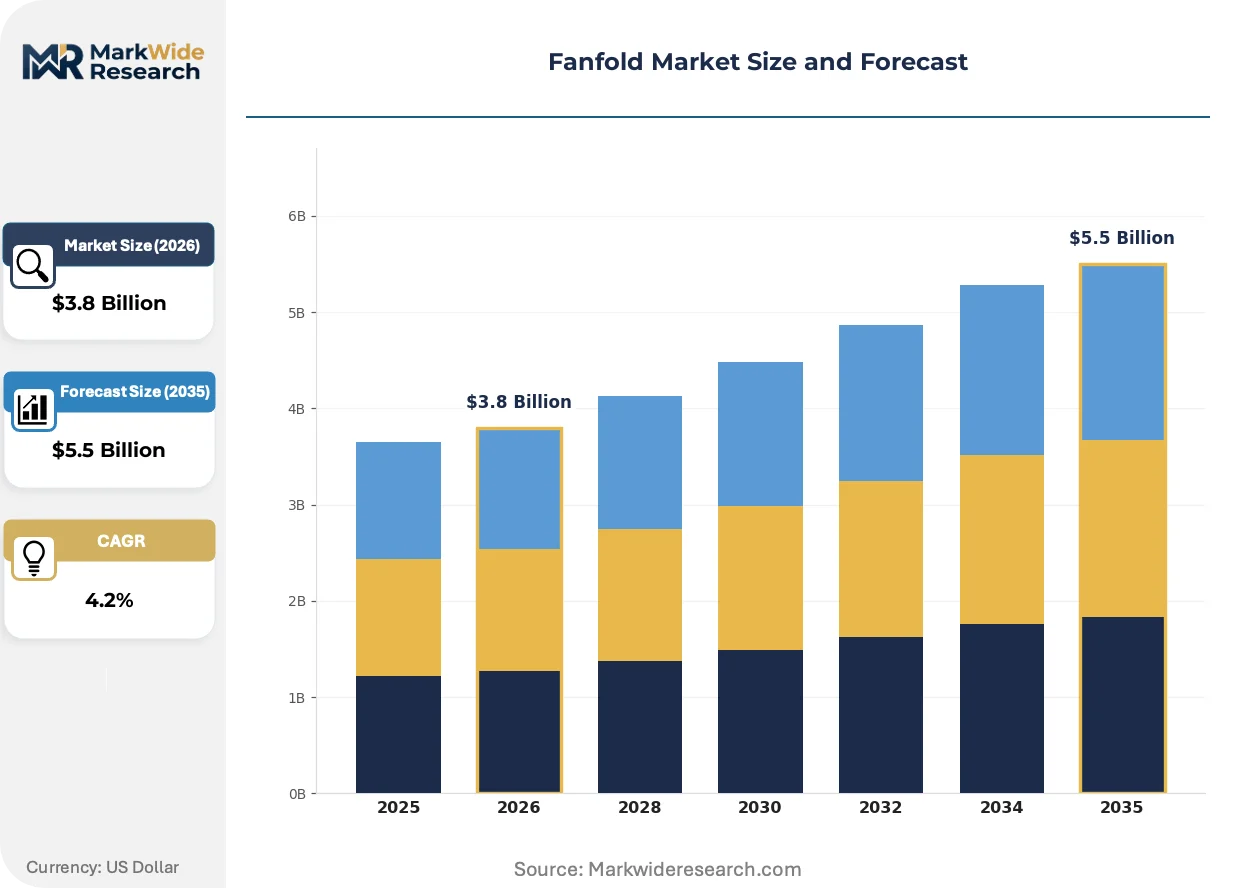
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colored Fanfold, Blank Fanfold, Custom Fanfold, Perforated Fanfold End User: Retail Stores, Manufacturing Plants, Logistic Companies, Educational Institutions Material: Paper, Cardboard, Synthetic, Recycled Material Size: A4 Size, A3 Size, Custom Size, Multi-Size |
| Companies Covered | International Paper, WestRock, DS Smith, Smurfit Kappa, Mondi Group, Nine Dragons Paper, Packaging Corporation of America, Pratt Industries, Rondo Ganahl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fanfold Market Emerging Trajectories
Digital integration across the fanfold value chain is collapsing traditional boundaries between production scheduling, customer inventory systems, and automated box-making equipment. Three developments are restructuring competitive positioning.
Machine-vision-guided cutting systems are decentralizing box fabrication from centralized corrugating plants to warehouse floors. E-commerce fulfillment operators are installing these units at accelerating rates to eliminate pre-formed box SKUs. The technology is decentralizing packaging production authority from brand owners to logistics providers.
EPA Clean Air Act standards for corrugated medium emissions are tightening stack monitoring requirements at US mills. Compliance investments are absorbing capital that might otherwise expand fanfold-specific production lines. Southern and Midwestern mill locations with newer pollution control infrastructure are capturing incremental volume from legacy Northeast facilities facing retrofit deadlines.
Just-in-time inventory practices are compressing fanfold order cycles from monthly to weekly replenishment. Third-party logistics providers are displacing direct mill relationships for mid-volume accounts seeking consolidated material sourcing. Germany and the Netherlands show the most advanced adoption of vendor-managed inventory programs linking mill scheduling to warehouse consumption data.
Fanfold Market Segmentation
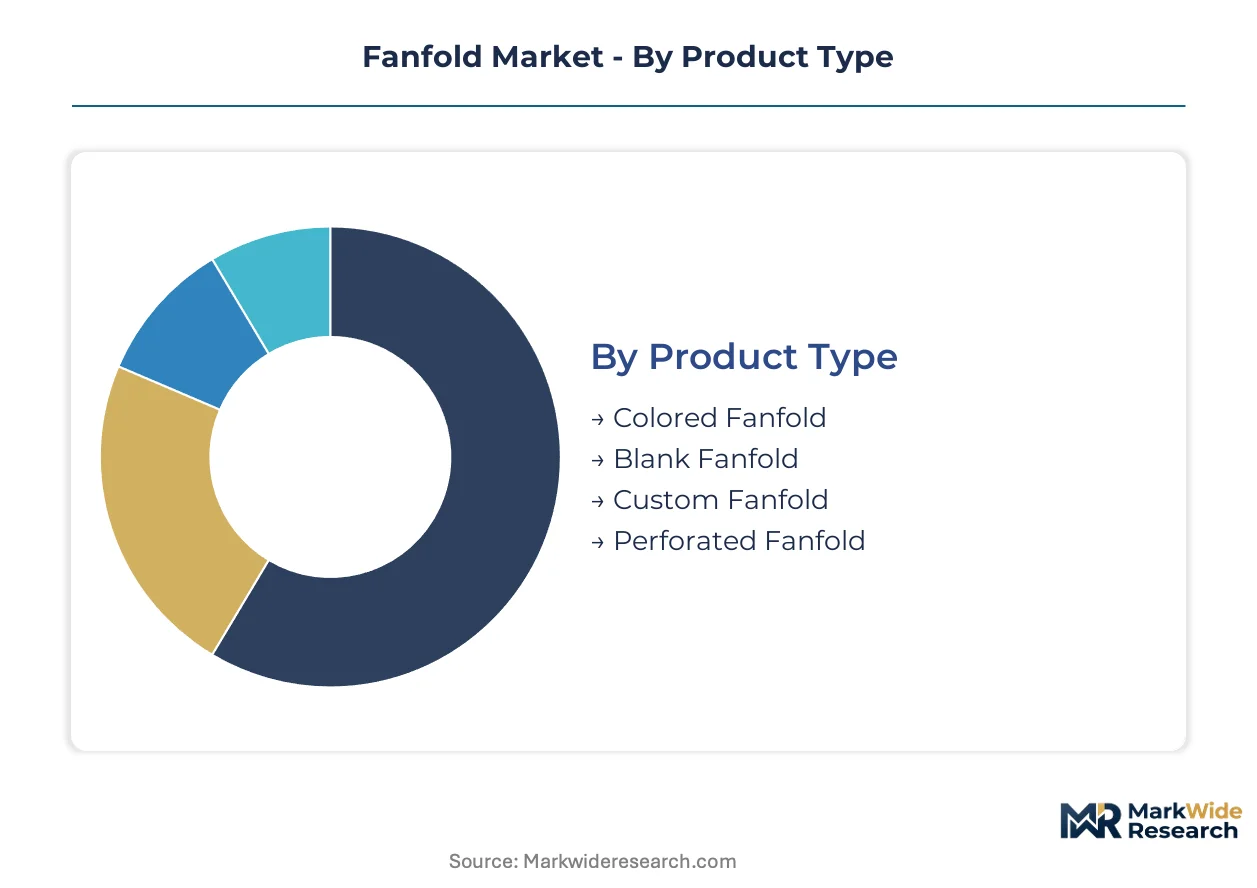
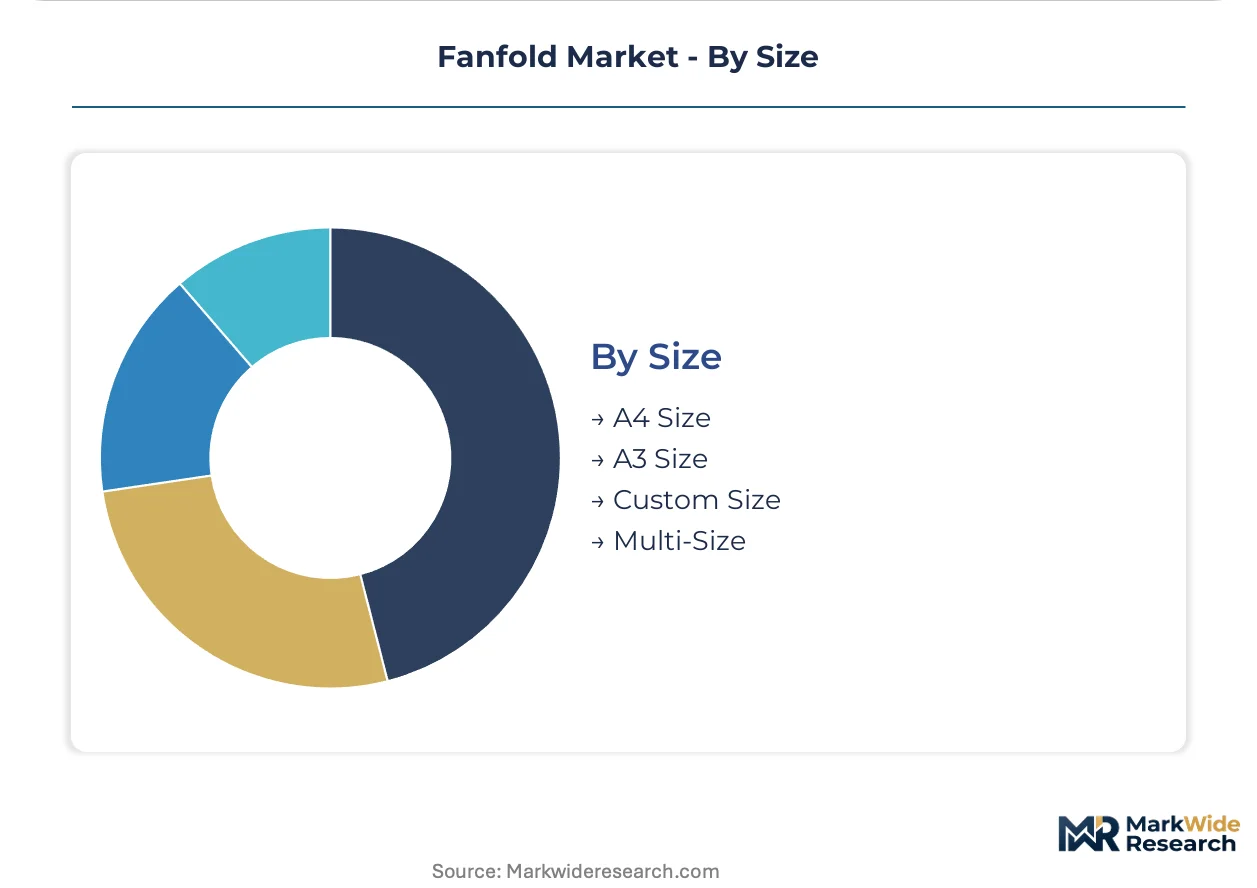
Fanfold segmentation reveals how material specifications, end-use requirements, and dimensional standards fragment procurement patterns across automated packaging ecosystems. Distinct compliance burdens attach to each category, reshaping supplier qualification criteria and mill investment priorities.
Product Type:
EPA Clean Air Act emissions standards for corrugated medium production apply uniformly across all product types, while EU Green Deal recycled content mandates create tiered compliance thresholds based on print coverage and surface treatment intensity.
- Blank Fanfold:Unprinted continuous corrugated board scored in alternating directions, manufactured in E-flute through C-flute profiles with basis weights from 125 to 350 gsm. Demand concentrates in e-commerce fulfillment centers across Germany and the Netherlands, where automated packaging lines prioritize rapid changeover and minimal SKU complexity. German corrugated clusters supply these high-volume accounts through vendor-managed inventory programs synchronized to real-time consumption data.
- Custom Fanfold:Dimensionally specified continuous board with branded print surfaces or exact-fit scoring patterns for fragile goods protection. Retail stores in France and Belgium drive specification requirements, with ANSM and CNIL data handling rules influencing traceability coding on printed surfaces. Margin premiums justify shorter production runs and dedicated tooling investments at specialized converting facilities.
- Colored Fanfold:Pigmented or dyed corrugated medium requiring REACH-compliant colorant certification for EU export eligibility. Paper and packaging converters in Italy specify these grades for premium retail presentation.
- Perforated Fanfold:Board with machine-punched separation lines enabling hand-tear box fabrication without cutting equipment. Educational institutions and small-format retail operations in Spain favor this grade for low-capital packaging workflows.
Blank Fanfold sits at the top of the volume ranking, with Custom Fanfold climbing the fastest as branded retail requirements penetrate automated fulfillment networks.
End User:
Cost tier stratification separates capital-intensive automated installations from manual handling environments, with procurement authority increasingly consolidating through third-party logistics intermediaries.
- Logistic Companies:Third-party fulfillment operators operating automated fanfold dispensing systems at warehouse scale. These accounts demand weekly replenishment cycles and consolidated material sourcing across multiple mill relationships, with Germany and the Netherlands showing the most advanced vendor-managed inventory adoption.
- Manufacturing Plants:Industrial operations retrofitting production floors with on-demand box-making equipment to eliminate pre-formed corrugated inventory. OSHA ergonomic guidelines constrain roll weights and dispensing equipment design in US facilities, while EU machinery directives govern safety interlocks for automated cutting systems.
- Retail Stores:Specialty and big-box retailers requiring exact-fit dimensions for fragile goods protection with direct-to-corrugate graphics capability. These accounts generate specification complexity that favors regional converting partnerships over direct mill relationships.
- Educational Institutions:Universities and school districts with fragmented purchasing authority and low-volume requirements. These end users typically procure through distributor intermediaries rather than direct mill contracts.
Logistic Companies anchor procurement volume, with Manufacturing Plants expanding most quickly as just-in-time inventory practices compress order cycles from monthly to weekly replenishment.
Material:
Supply concentration in German and Benelux fiber recovery infrastructure creates geographic bias in recycled material availability, while virgin pulp price volatility complicates multi-year contract structures across all grades.
- Recycled Material:Post-consumer recovered fiber processed through mechanical pulping with controlled contamination screening. EU Green Deal minimum recycled content thresholds are pulling investment into fiber recovery infrastructure at export-oriented mills in Germany and the Netherlands.
- Paper:Virgin kraft pulp-based corrugated medium with consistent fiber length distribution for high-strength applications. Premium e-commerce accounts in France specify these grades for heavy-goods protection where board stiffness cannot be compromised.
- Cardboard:Multi-ply construction with mixed fiber sources and clay-coated surfaces for print receptivity. Retail branding requirements in Belgium and Luxembourg drive specification of these grades for shelf-ready presentation.
- Synthetic:Polypropylene or polyester-based continuous board for moisture-resistant or reusable packaging applications. Niche demand from pharmaceutical distributors in Switzerland and Austria requires Swissmedic-compliant material traceability.
Recycled Material commands the steepest expansion trajectory as mills improve fiber recovery rates without sacrificing board stiffness, with Paper retaining premium positioning in heavy-goods segments.
Size:
Dimensional standardization reduces changeover downtime in automated systems, while custom specifications capture margin from fragmented retail requirements with low volume per SKU.
- Custom Size:Non-standard dimensions specified to exact product fit requirements, typically produced on short-run converting equipment with dedicated tooling. Fragile goods retailers in France and Germany drive demand for these specifications.
- Multi-Size:Variable-width fanfold with adjustable scoring patterns enabling single-roll supply across multiple box formats. E-commerce fulfillment operators in the Netherlands favor this grade for SKU reduction in automated lines.
- A4 Size:Standardized 210mm width dimension compatible with desktop and small-format box-making equipment. Educational institutions and small business users in Spain and Italy procure these grades through office supply distributors.
- A3 Size:297mm width dimension serving mid-volume manufacturing and logistics applications with moderate box size requirements. German automotive component suppliers specify these grades for standardized parts packaging.
Custom Size generates the highest margin per ton, with Multi-Size gaining share fastest as logistics operators consolidate material specifications across fulfillment networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands corrugated packaging volume while the United States builds automated fulfillment infrastructure at faster deployment rates. National regulatory frameworks and industrial cluster geography reshape where fanfold capacity expands.
Germany
E-commerce fulfillment centers and automotive component packaging drive fanfold consumption across the Rhine-Ruhr and Bavarian industrial corridors. The EU Green Deal's packaging waste directives mandate minimum recycled content thresholds that reshape fiber procurement at export-oriented mills. Corrugated packaging clusters around Stuttgart and Hamburg serve Central European distribution networks with compressed delivery radiuses.
United States
Third-party logistics operators and manufacturing plants retrofit warehouse floors with on-demand box-making equipment to eliminate pre-formed inventory. EPA Clean Air Act standards for corrugated medium emissions tighten stack monitoring requirements at mills in the Northeast and Midwest. Southern mill locations with newer pollution control infrastructure capture incremental volume from legacy facilities facing retrofit deadlines.
Netherlands
Rotterdam-Antwerp port logistics and European distribution hub status concentrate demand for multi-size fanfold with adjustable scoring patterns. EU machinery directives govern safety interlocks for automated cutting systems installed at fulfillment centers. Vendor-managed inventory programs linking mill scheduling to warehouse consumption data show the most advanced adoption in the Randstad region.
France
Retail stores and specialty fragile goods distributors generate specification complexity for custom fanfold with direct-to-corrugate graphics. ANSM and CNIL data handling rules influence traceability coding requirements on printed surfaces. Industrial converting partnerships in the Île-de-France and Auvergne-Rhône-Alpes regions serve these accounts with shorter production runs.
China
Domestic e-commerce fulfillment expansion and export-oriented corrugated packaging production pull investment into automated fanfold dispensing systems. GB standards and dual carbon goals under MEE oversight shape emissions compliance and fiber sourcing requirements. Manufacturing concentration in the Yangtze River Delta and Pearl River Delta integrates fanfold supply with box-making equipment fabrication.
Fanfold Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated corrugated producers holding supply continuity advantages for high-volume accounts. The vendor base organizes around three strategic archetypes: North American mill networks with recycled fiber control, European integrated operations spanning multiple countries, and Asia-Pacific scale producers serving export demand. Competitive moves center on capacity alignment with automated packaging line deployment and fiber recovery infrastructure investment.
Among North American integrated producers, International Paper and WestRock exemplify mill-network scale advantages for sustaining supply continuity. Smurfit Kappa anchors European positioning through corrugated operations spanning multiple countries. These three occupy positions that reflect the geographic concentration of demand in Germany and the United States.
| Leading Market Players |
|---|
| International Paper |
| WestRock |
| DS Smith |
| Smurfit Kappa |
| Mondi Group |
| Nine Dragons Paper |
| Packaging Corporation of America |
| Pratt Industries |
| Rondo Ganahl |
| Others |
Supply Flow & Price Mechanics
Family-owned German mill networks anchor supply-side ownership structures, translating concentrated fiber recovery infrastructure into disciplined contract pricing for high-volume e-commerce accounts. Their captive control over recycled pulp streams insulates margin positions against virgin fiber volatility while limiting spot-market liquidity for mid-tier buyers.
Pricing Analysis
Capacity additions in the Netherlands are reshaping price floors for multi-size fanfold grades serving automated fulfillment networks. Three-tier pricing structure across premium custom-printed, standard blank, and economy perforated levels separates buyers by volume commitment and surface treatment requirements. Cost compression in standard grades is intensifying because logistics operators consolidate procurement through third-party intermediaries demanding weekly replenishment cycles. Educational institutions and small-format retailers exhibit highest price sensitivity due to fragmented purchasing authority, while automotive component suppliers in Germany show lowest sensitivity given just-in-time inventory penalties for supply disruption.
Supply Chain Analysis
Fanfold supply rests on German, Dutch, and Belgian fiber recovery infrastructure with concentrated mechanical pulping capacity around Rotterdam-Antwerp port logistics. Recovered OCC streams, virgin kraft pulp, and REACH-compliant colorants constitute the primary input dependencies. Single-source vulnerability concentrates in municipal contamination screening bottlenecks that constrain high-grade output without virgin blending. Distribution runs through vendor-managed inventory programs linking mill scheduling to warehouse consumption data, with third-party logistics providers displacing direct mill relationships for mid-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fanfold offers margin expansion through recycled fiber recovery rate improvements that reduce virgin pulp exposure while EU Green Deal mandates create premium-tier pricing for compliant grades. Automated packaging line deployment compresses order cycles and opens recurring software revenue alongside physical supply.
For Market Incumbents: Cement supply continuity advantages by deepening backward integration into material recovery facilities near German corrugated clusters. Lock in multi-year vendor-managed inventory contracts with Rotterdam-Antwerp logistics hubs before regional competitors replicate the infrastructure. Machine-vision-guided cutting system partnerships represent the priority defensive lever against equipment suppliers encroaching on packaging production authority.
For New Entrants and Emerging Players: Machine-vision-guided dispensing technology offers a technology-first wedge into mid-volume manufacturing plant retrofits in the US Midwest where OSHA ergonomic compliance constrains incumbent roll dimensions. Target educational institutions and small-format retail in Spain and Italy through perforated fanfold grades requiring minimal capital equipment. A distributor-centric go-to-market angle bypasses direct mill relationship requirements that concentrate procurement authority with established German networks.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional converting specialists with custom print capabilities and ANSM traceability coding certifications serving French fragile goods retail. The five-to-ten-year viability framing favors integrated fiber recovery operators positioned for US state-level EPR law expansion. Watch vendor-managed inventory adoption rates in the Randstad region as the inflection signal for logistics-provider procurement consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Recovery | Pratt Industries' captive MRF network insulates margin against OCC price volatility. |
| Vendor-Managed Inventory Expansion | Smurfit Kappa's Randstad programs synchronize mill scheduling to real-time warehouse consumption. |
| Machine-Vision Equipment Partnership | International Paper's cutting system alliances decentralize box fabrication authority to logistics floors. |
| Custom Print Surface Investment | DS Smith's Île-de-France converting partnerships capture margin from ANSM-coded fragile goods retail. |
| EPR Compliance Service Development | WestRock's state-level EPR positioning creates recurring revenue alongside physical fanfold supply. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with corrugated mill operations directors, third-party logistics procurement leads, automated packaging equipment engineers, and retail category buyers with secondary validation. Trade data from Eurostat and USITC, EPA Clean Air Act compliance filings, EU Green Deal directive documentation, and SEC disclosures from publicly traded packaging producers anchored the quantitative foundation. Bottom-up segment sizing and top-down market reconciliation triangulated volume and value estimates.
Segment-weighting approaches modeled product type, end user archetype, material grade, and dimensional standard across the analysis window. CAGRs derived from historical trajectory analysis and forward-looking deployment rates for automated box-making equipment. Fiber recovery infrastructure investment pipelines and e-commerce fulfillment center buildout schedules served as industry-specific forecast inputs alongside regulatory compliance timeline assumptions.
The model holds under stable EU Green Deal implementation trajectories and continued e-commerce fulfillment expansion; deviation in energy price spikes affecting German mill networks or municipal contamination rate deterioration would shift supply availability and pricing dynamics. A small set of named triggers warrants ongoing watch: Rotterdam port logistics disruptions, US state EPR law acceleration, and machine-vision equipment cost curves enabling mid-market manufacturing adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Coconut Wraps Market
Packaging Materials
Microwave Packaging Market
Packaging Materials
Polystyrene Packaging Market
Packaging Materials
Construction Films Market
Packaging Materials
Lid Laminates Market
Packaging Materials
Punnet Packaging Market
Packaging Materials
Insulated Box Liner Market
Packaging Materials
France Packaging Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Wrapping Tissues Market
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
Asia-Pacific Solar Control Window Films Market
Packaging Materials
Crimped End Mailing Tubes Market
Packaging Materials
Absorbent Tray Liners Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
Collapsible Tube Packaging Market